
 Raman Amplifier Market | 2026-2036
Raman Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Raman Amplifier Market Insights
Software-defined amplification management is consolidating around recurring revenue models that reshape vendor-customer relationships. Coherent leverages its vertically integrated pump laser and amplifier module portfolio to sustain pricing power across submarine and terrestrial contracts. Fujitsu anchors its position through deep relationships with Japanese and Asia-Pacific carriers, while Ciena Corporation differentiates via programmable coherent optics tightly coupled with Raman amplification control planes.
A Raman amplifier employs stimulated Raman scattering in optical fibers or semiconductor waveguides to amplify weak optical signals across extended transmission spans, typically achieving noise figures below 4.5 dB by pumping at wavelengths approximately 100 nm shorter than the signal band. Distributed Raman Amplifier technology leads installed base volumes due to its seamless integration with existing fiber spans and superior noise performance over erbium-doped alternatives. Fiber Raman Amplifier configurations capture the fastest expansion in data center interconnects where low-latency amplification without discrete component insertion proves critical. Among end users, telecommunications providers remain the dominant revenue pool, though research institutions operating quantum communication testbeds represent an emerging premium segment.
FCC spectral efficiency rules in the United States and the EU Green Deal energy consumption frameworks for network infrastructure both shape product roadmaps, pushing manufacturers toward higher pump conversion efficiency and reduced thermal footprints. China's MIIT fiber broadband acceleration mandates and GB standards for optical transmission equipment create a distinct compliance environment that favors domestic suppliers and joint-venture partners. Stakeholders must monitor how evolving national security reviews of submarine cable equipment affect supply chain access for pump laser subcomponents across these three regulatory spheres.
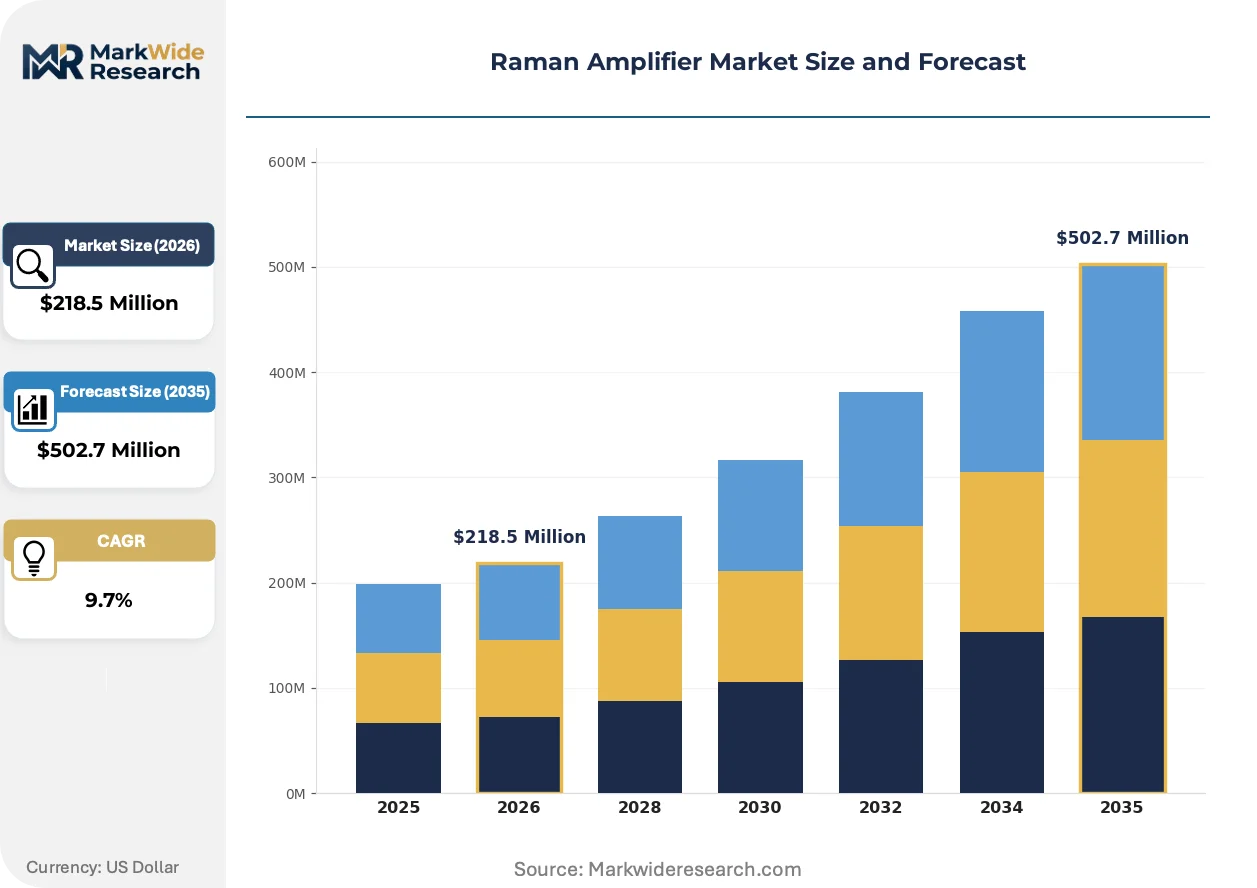
Market Dynamics
Telecommunications operators face mounting pressure to extend optical reach without deploying discrete amplifiers every 80 kilometers, forcing pump laser efficiency and remote management capabilities to the center of procurement decisions.
Growth Catalysts
- EU Green Deal energy mandates:Network infrastructure efficiency requirements under the EU Green Deal compel carriers to adopt distributed Raman amplification, cutting amplifier site counts and thermal loads across terrestrial long-haul routes.
- China's MIIT fiber acceleration:China's Ministry of Industry and Information Technology broadband mandates drive massive procurement of high-performance amplification modules for provincial interconnect and data center fiber buildouts.
- Submarine cable renewal cycles:Transoceanic cable systems reaching end-of-life replacement windows specify hybrid amplification architectures combining Raman with erbium-doped fiber amplifiers for extended unrepeatered spans.
Market Restraints
- Pump laser supply concentration:High-power 14xx nm semiconductor pump lasers concentrate among a limited supplier base in Japan and the United States, creating vulnerability to allocation constraints during demand surges.
- High-fiber qualification costs:Distributed Raman deployment requires fiber characterization and safety certification per span, adding capital intensity that deters smaller regional operators from upgrades.
- Competition from coherent DSP advances:Digital signal processor improvements in coherent transceivers extend reach without amplification, threatening displacement in margin-sensitive metro applications.
Strategic Opportunities
- Quantum communication testbeds:Research institutions in Germany, China, and the United States require ultra-low-noise amplification for quantum key distribution networks, commanding premium pricing for specialized pump configurations.
- Software-defined amplification control:API-driven amplifier management platforms enable recurring revenue streams through subscription-based optimization services, shifting vendor relationships from hardware transactions to ongoing partnerships.
- Data center interconnect fiberization:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore deploy Raman amplification for low-latency campus and metro links where discrete component insertion violates latency budgets.
Industry Challenges
- Specialized optical engineering talent scarcity:Raman system design requires expertise in nonlinear optics and pump-signal interaction modeling, with limited university programs producing qualified engineers.
- Legacy SONET/SDH integration friction:Carriers maintaining synchronous optical network infrastructure face protocol translation complexity when overlaying Raman-amplified coherent wavelengths onto existing management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raman Amplifier Market |
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $502.7 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Distributed Raman Amplifier, Fiber Raman Amplifier, Semiconductor Raman Amplifier, Optical Raman Amplifier End User: Telecommunications Providers, Data Centers, Research Institutions, Cable Operators Application: Long-Haul Transmission, Access Networks, Fiber-Optic Sensors, Test and Measurement Solution: Amplification Systems, Testing Solutions, Integration Services, Network Optimization |
| Companies Covered | Coherent, Fujitsu, Ciena Corporation, II-VI Incorporated, Fiberhome Telecommunication Technologies, Nokia, Broadcom, Thorlabs, Lumentum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raman Amplifier Market Trends and Innovations
Amplification architecture is shifting from standalone hardware toward intelligent, software-coordinated systems that optimize pump power in real time. This transformation redefines competitive advantage around control plane sophistication rather than raw optical performance.
Machine learning-based pump optimization is converging with coherent transceiver telemetry to enable dynamic gain flattening across C+L band systems. Tier-one carriers in Japan and the United States pilot these closed-loop configurations for transpacific routes. The technology is converging with software-defined networking control planes to compress provisioning intervals from weeks to hours.
China's GB standards for optical transmission equipment now mandate energy efficiency reporting for amplification subsystems, mirroring trajectory of EU Green Deal requirements. Manufacturers must certify pump conversion efficiency and thermal dissipation metrics to maintain qualification for state-backed tenders. Domestic suppliers and joint-venture partners capture preferential positioning under these technical compliance frameworks.
Carrier procurement teams now unbundle amplifier hardware from system integration services, awarding separate contracts for pump laser supply, module assembly, and field optimization. This disintermediation pressures vertically integrated vendors to defend margin through software differentiation rather than captive component supply. The pattern is most visible among European incumbent operators restructuring supplier panels under CSRD-linked procurement policies.
Raman Amplifier Market Segmentation
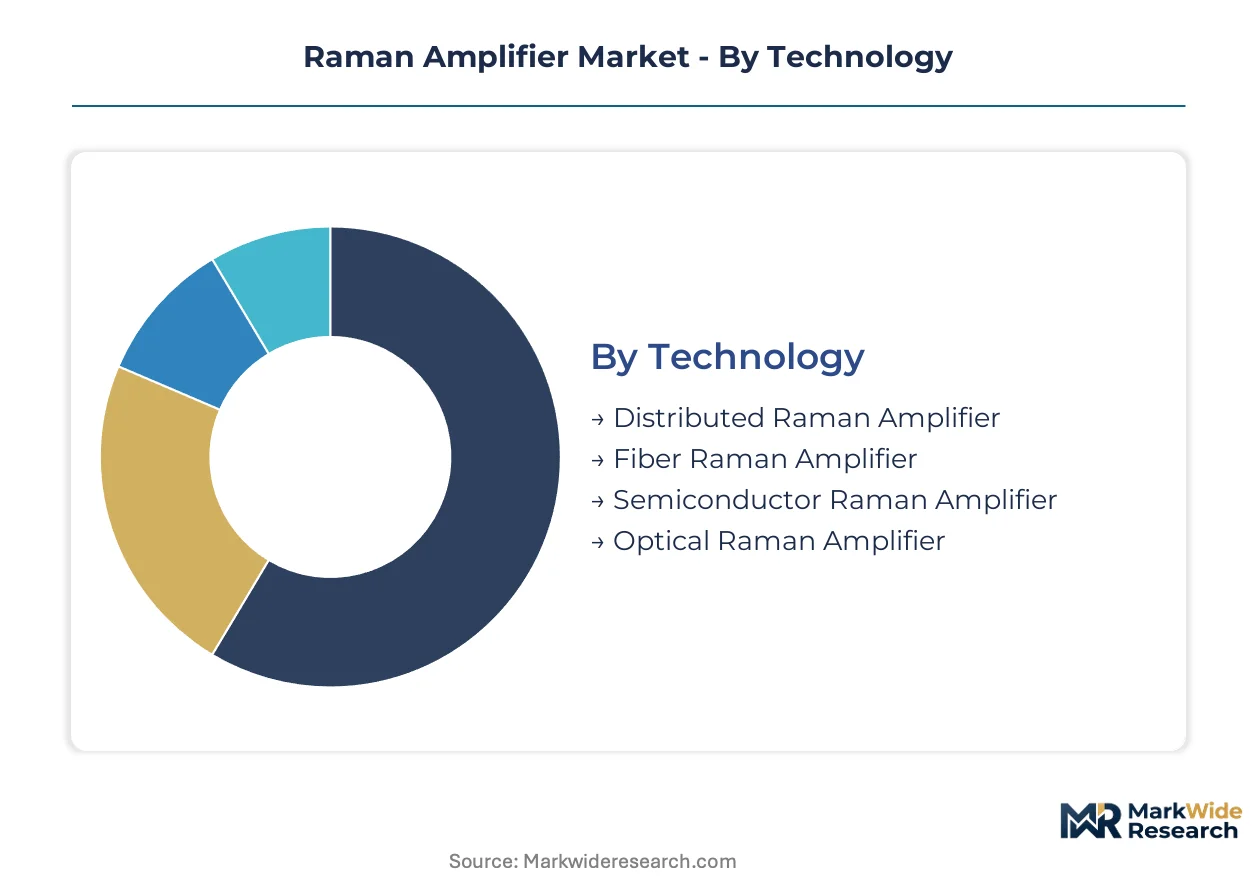
Raman amplifier procurement varies sharply by deployment context. Discrete amplification systems serve different technical and economic requirements than embedded pump modules integrated into coherent transceiver platforms.
Technology:
Standalone amplification systems dominate submarine and ultra-long-haul terrestrial routes, while embedded semiconductor configurations penetrate data center interconnects where space and thermal constraints rule.
- Distributed Raman Amplifier:Pump lasers couple directly into transmission fiber spans, achieving noise figures below 4.5 dB without discrete component insertion. Telecommunications providers in China deploy these across provincial backbone routes under MIIT fiber acceleration mandates.
- Fiber Raman Amplifier:Discrete fiber-based modules integrate with existing erbium-doped amplifier sites for hybrid amplification architectures. Submarine cable renewal cycles in the North Atlantic and Pacific specify these for extended unrepeatered spans.
- Semiconductor Raman Amplifier:Compact waveguide-based devices target chip-scale integration.
- Optical Raman Amplifier:Specialized configurations for sensing and metrology applications.
Distributed Raman leads volumes today; Fiber Raman is gaining share fastest.
End User:
Cost tier separation distinguishes capital-intensive national carriers from research institutions commanding premium pricing for specialized pump configurations.
- Telecommunications Providers:National and regional carriers account for the dominant revenue pool, procuring amplification modules for long-haul backbone and metro aggregation. EU Green Deal energy efficiency mandates compel these operators toward distributed architectures that reduce amplifier site counts.
- Data Centers:Hyperscale facilities and colocation operators deploy Raman amplification for low-latency campus interconnects where discrete component insertion violates latency budgets. Northern Virginia and Frankfurt clusters drive procurement concentration.
- Research Institutions:Quantum communication testbeds in Germany and the United States require ultra-low-noise amplification.
- Cable Operators:Hybrid fiber-coaxial providers upgrade fiber deep architectures.
Telecommunications Providers dominate revenue today; Data Centers are climbing the fastest.
Application:
Volume concentration aligns with transmission distance requirements, separating transoceanic and continental backbone routes from metro access and sensing deployments.
- Long-Haul Transmission:Transcontinental and submarine routes spanning thousands of kilometers require amplification every 80-120 kilometers. FCC spectral efficiency rules in the United States shape procurement specifications for these deployments.
- Access Networks:Fiber-to-the-premises buildouts and business Ethernet services employ Raman amplification to extend reach from central offices.
- Fiber-Optic Sensors:Distributed temperature and strain sensing systems leverage Raman scattering for measurement.
- Test and Measurement:Laboratory and manufacturing test equipment requires stable amplification sources.
Long-Haul Transmission leads volumes today; Access Networks are expanding most quickly.
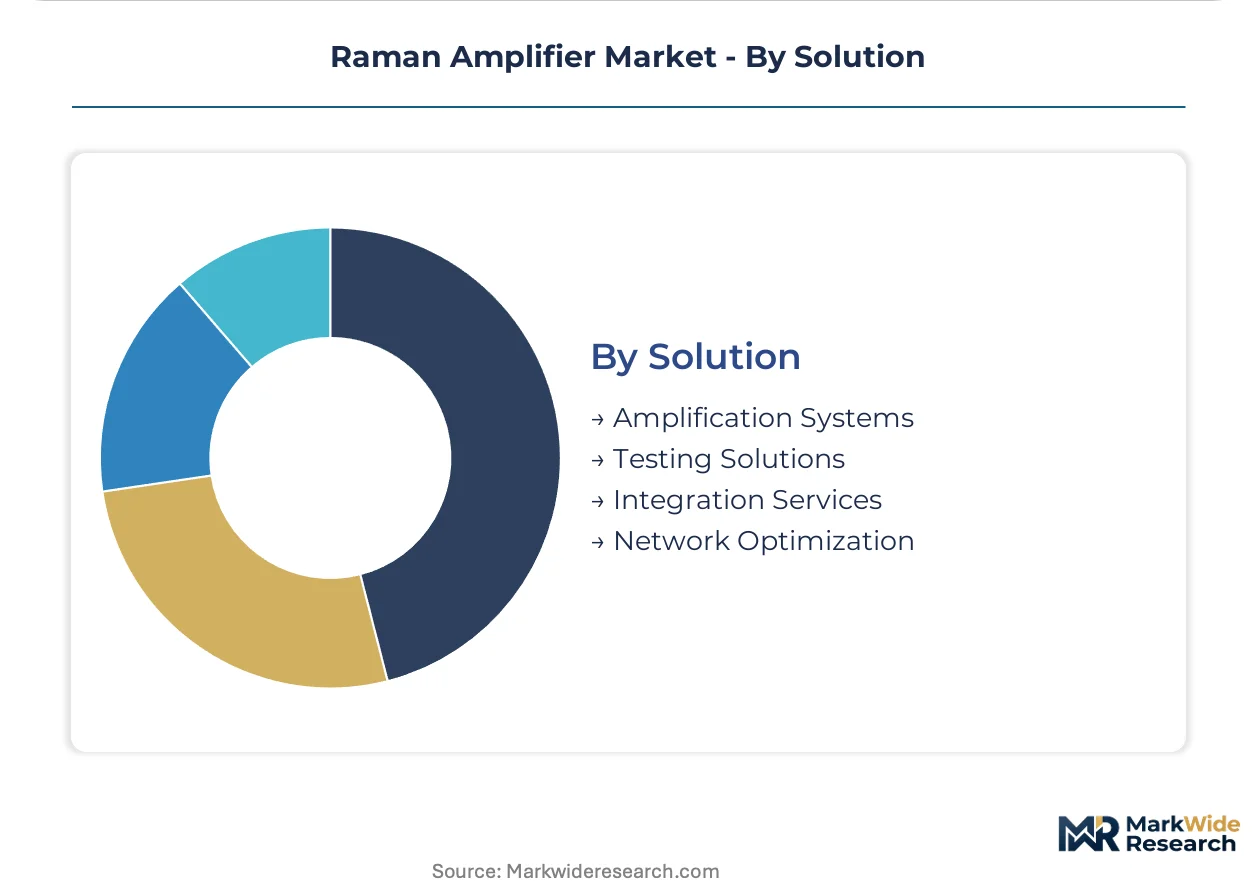
Solution:
Margin structure separates hardware-centric amplification systems from recurring-revenue optimization services that reshape vendor-customer relationships.
- Amplification Systems:Complete pump laser and control module assemblies for greenfield deployment and overlay upgrades. Hardware procurement concentrates among Japanese and Asia-Pacific carriers with established supplier relationships.
- Testing Solutions:Characterization equipment for fiber span qualification and amplifier performance verification.
- Integration Services:Field engineering for pump power optimization and gain flattening.
- Network Optimization:Software-defined amplification management platforms enabling API-driven pump control and dynamic reconfiguration.
Amplification Systems leads volumes today; Network Optimization shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT fiber acceleration mandates generate procurement volumes that dwarf Germany's EU Green Deal compliance cycles, yet both regulatory frameworks reshape amplifier specifications in distinct directions.
United States
FCC spectral efficiency rules and submarine cable renewal cycles drive demand for hybrid amplification architectures. The FCC mandates shape long-haul procurement specifications across continental backbone routes. Northern Virginia hyperscale clusters deploy Raman amplification for low-latency campus interconnects.
China
Provincial backbone buildouts and data center interconnect programs absorb massive amplification module volumes. MIIT fiber broadband acceleration mandates and GB standards for optical transmission equipment create compliance environments favoring domestic suppliers. Yangtze River Delta fiber infrastructure clusters concentrate state-backed tender awards.
Germany
EU Green Deal energy consumption frameworks compel carriers toward distributed architectures that cut amplifier site counts. CSRD-linked procurement policies restructure supplier panels among European incumbent operators. Frankfurt data center clusters drive premium amplification demand for metro latency budgets.
Japan
High-power 14xx nm semiconductor pump laser supply concentrates among domestic manufacturers serving global demand. METI industrial policy supports advanced optical component production for submarine and terrestrial contracts. Tokyo-Osaka corridor carriers pilot machine learning-based pump optimization for transpacific routes.
Singapore
Submarine cable landing stations and regional data center interconnects position the city-state as amplification procurement hub. Maritime cable system operators specify hybrid architectures for Asia-Pacific route extensions. Hyperscale facilities deploy chip-scale amplification for intra-campus fiber links.
Raman Amplifier Market Competitive Landscape
Top-tier vendors anchor submarine and ultra-long-haul terrestrial contracts, while mid-tier specialists serve data center interconnect and research testbed niches. The vendor base separates into vertically integrated pump laser manufacturers, system integrators with coherent optics portfolios, and component specialists supplying modular assemblies. Strategic archetypes include captive pump laser producers, programmable control plane developers, and field optimization service providers. Competitive moves center on software-defined amplification management platforms and API-driven pump control licensing arrangements.
Among vertically integrated optical component manufacturers, Coherent and Lumentum occupy positions that exemplify upstream control over pump laser supply chains. Ciena Corporation represents the programmable control plane archetype through its coherent optics integration. These three anchors illustrate how vendor relationships shift from hardware transactions toward recurring-revenue optimization partnerships.
| Leading Market Players |
|---|
| Coherent |
| Fujitsu |
| Ciena Corporation |
| II-VI Incorporated |
| Fiberhome Telecommunication Technologies |
| Nokia |
| Broadcom |
| Thorlabs |
| Lumentum |
| Others |
Pricing and Supply Chain Analysis
Pump laser component costs cascade from Japanese and United States semiconductor foundries through three pricing tiers: premium configurations for submarine cable operators, standard modules for terrestrial carriers, and economy options for regional data center interconnects. EU Green Deal energy efficiency mandates compress margins at the standard tier while creating premium pricing power for vendors certifying reduced thermal footprints.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-tier amplification modules as domestic suppliers undercut incumbent pricing. Three-tier pricing structure across premium, standard, and economy levels separates submarine-certified systems from terrestrial deployments and data center interconnects. Cost compression in the economy tier intensifies because hyperscale buyers consolidate procurement volumes and demand API-driven management bundling. Regional telecommunications providers exhibit highest price sensitivity, while quantum communication testbeds at German and United States research institutions accept substantial premiums for specialized pump configurations.
Supply Chain Analysis
Single-source vulnerability sits with high-power 14xx nm pump laser production concentrated among Japanese and United States manufacturers. Raman amplifier assembly draws from semiconductor substrates in Japan, precision optics in Germany, and control electronics from Taiwan. Tariff exposure on pump laser subcomponents creates procurement risk for European and Chinese system integrators. Distribution runs through direct carrier contracts for submarine and long-haul terrestrial deployments, while data center interconnect modules move via specialized optical component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Raman amplification hinges on software-defined control plane monetization shifting vendor relationships from hardware transactions toward recurring optimization subscriptions.
For Market Incumbents: To counter coherent DSP reach extension threatening metro amplification displacement, incumbents should deepen API-driven pump control licensing and secure captive supply of 14xx nm pump lasers through joint ventures with Japanese semiconductor manufacturers. Certification investment for EU Green Deal energy efficiency compliance creates pricing power tier separation from unqualified competitors.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium submarine systems and economy data center modules creates entry space for specialized semiconductor Raman amplifiers targeting chip-scale integration. Hyperscale data center interconnects in Northern Virginia and Frankfurt represent the most penetrable segment given latency budget constraints and procurement consolidation. Go-to-market positioning should emphasize software-native amplification management without legacy SONET/SDH integration overhead.
For Investors and Strategic Acquirers: Roll-up economics work for field optimization service providers because carrier procurement teams now unbundle hardware from integration services under CSRD-linked restructuring. Five-to-ten year viability favors vendors with coherent optics control plane integration rather than pure-play pump laser manufacturing. Monitor submarine cable renewal award cycles as inflection indicator for hybrid amplification architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Amplification Platform Launch | API-driven pump control enables recurring revenue from tier-one carriers piloting closed-loop C+L band systems. |
| Pump Laser Supply Agreement | Long-term contracts with Japanese semiconductor manufacturers secure allocation priority during demand surges. |
| EU Green Deal Certification Program | Energy efficiency reporting compliance maintains qualification for state-backed tenders in Germany and China. |
| Quantum Communication Testbed Partnership | Ultra-low-noise specialization commands premium pricing from German and United States research institutions. |
| Data Center Interconnect Geographic Expansion | Frankfurt and Singapore hyperscale clusters drive procurement for low-latency campus fiber links. |
Research Methodology
Multiple input streams — structured interviews with optical network architects, procurement directors at telecommunications carriers, pump laser manufacturing specialists, and data center interconnect engineers — were reconciled against secondary validation from FCC spectral efficiency filings, MIIT broadband acceleration mandates, EU Green Deal technical documentation, and hyperscaler capital expenditure disclosures. Bottom-up triangulation across amplification module shipment volumes and top-down reconciliation against carrier procurement budgets anchored the analysis.
Data-stream reconciliation applied analytical framework across technology type, end-user segment, application distance requirement, and solution delivery model throughout the forecast period. CAGRs derived from segment-level volume projections weighted by average selling price evolution, with specific inputs including submarine cable renewal cycle timing and China provincial backbone buildout acceleration.
Caveats apply where pump laser supply allocation constraints, national security review expansion for submarine cable equipment, or coherent DSP reach breakthroughs could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mobile Optical Pluggable Market
Optical Components
Silicon Photonics Market
Optical Components
Fogless Mirror Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Liquid Lenses Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Photomask Pellicle Market
Optical Components
Display Optical Film Market
Optical Components
Optical Dome Market
Optical Components
Bio-Optics Market
Optical Components
Polarizer Film Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Acousto Optic Devices Market
Optical Components
Laser Module Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market