
 Duplication Disc Market | 2026-2036
Duplication Disc Market Size, Share, and Industry Trends Forecast 2026-2036
Duplication Disc Market Analysis
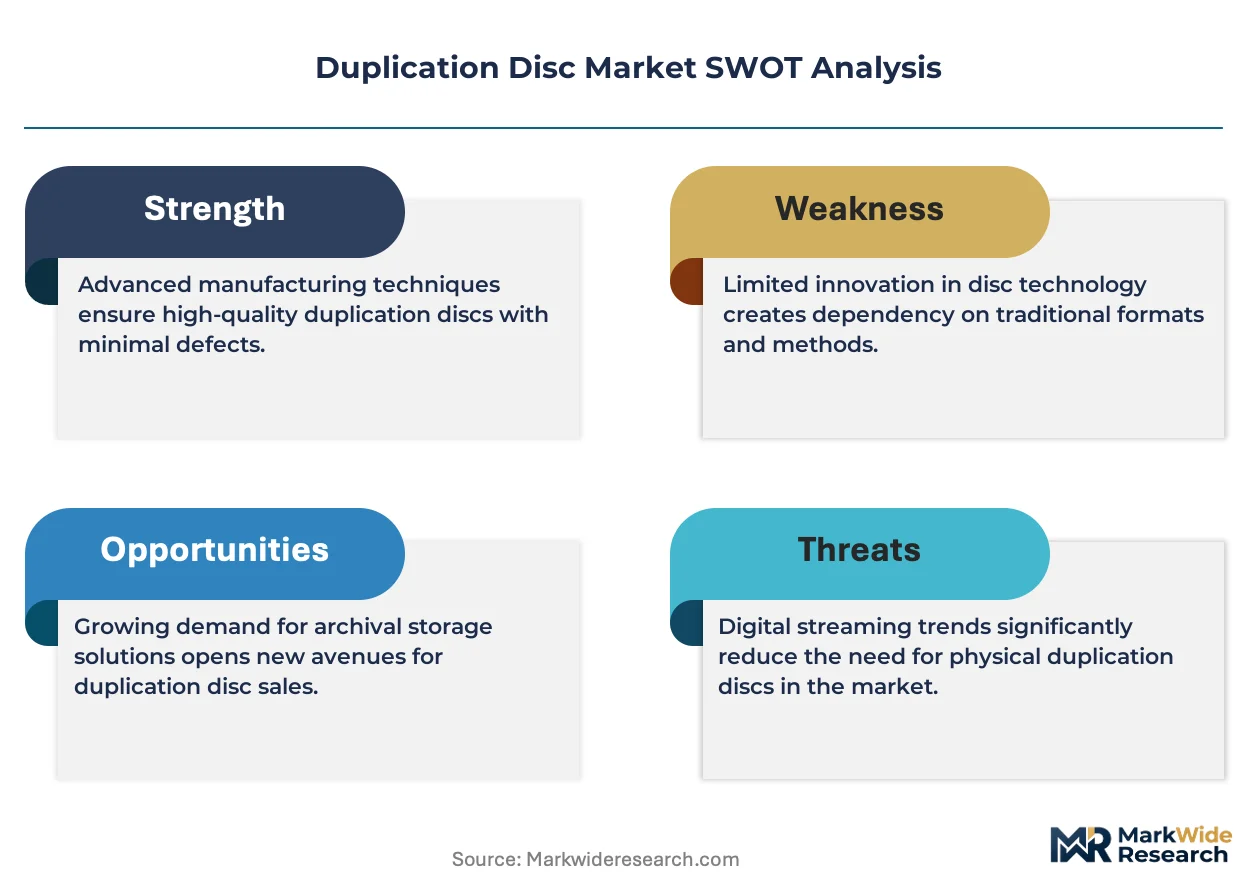
Enterprise data-archiving buyers are rotating toward hybrid physical-digital retention systems, displacing pure-cloud strategies in regulated sectors. Rimage Corporation leverages thermal retransfer printing expertise to anchor high-assurance labeling for government and medical archives. Vinpower Digital competes on duplication tower density, sustaining manufacturing scale across North American and Asian assembly lines. Disc Makers specializes in short-run custom media, occupying the independent music and video distribution niche with direct-to-creator channel control.
A duplication disc is an optical storage medium—typically polycarbonate substrate with aluminum or gold reflective layers, 120 mm diameter, 1.2 mm thickness—produced through injection molding, stamper replication, and spin-coating processes, designed for writable or pre-recorded data distribution and long-term archival retention. Physical media retains dominance in jurisdictions with legal hold requirements, while cloud storage segments capture transactional data workflows; optical technology leads in write-once-read-many compliance applications where tamper evidence matters, and analog transfer persists in legacy audio preservation where bit-perfect migration demands specialized hardware. Margin pools concentrate in customization services—labeling and packaging—rather than commodity blank disc manufacturing.
The EPA regulates hazardous substances in optical disc substrate production under TSCA, while the EU RoHS directive restricts heavy metals in electronic media components, and Japan's METI promotes JIS standards for optical media durability in climate-vulnerable storage environments. These frameworks elevate compliance-grade disc specifications, filtering out uncertified suppliers from institutional procurement channels. Stakeholders must monitor regulatory divergence between REACH-aligned European requirements and evolving US state-level chemical disclosure laws to determine manufacturing location and certification investment priorities.
Market Dynamics
Healthcare archival mandates are compressing procurement cycles for write-once optical media as institutions confront F-Gas Regulation constraints on manufacturing inputs and cloud-integrated hybrid retention systems displace pure-digital strategies in regulated sectors.
Growth Catalysts
- RoHS-aligned procurement mandates:European healthcare systems now require heavy-metal-free disc substrates for patient record archiving, filtering uncertified suppliers from institutional tenders.
- Injection molding precision gains:Advanced stamper replication now achieves sub-micron pit geometry for 100-year archival-grade polycarbonate, satisfying climate-vulnerable storage specifications under Japan METI durability frameworks.
- German industrial compliance archiving:Long-term record retention laws sustain optical disc procurement for manufacturing quality documentation and environmental audit trails.
Market Restraints
- Polycarbonate resin cost volatility:Petrochemical feedstock fluctuations compress margins for substrate producers operating at commodity scale.
- Asian assembly concentration:Tower duplication equipment manufacturing clusters in Taiwan and mainland China create single-source vulnerability for North American integrators.
- Cloud storage substitution:Transactional data workflows increasingly migrate to distributed cloud architectures, shrinking addressable volume for short-cycle rewritable media.
Strategic Opportunities
- Indian pharmaceutical serialization:CDSCO track-and-trace mandates for export drug packaging create demand for tamper-evident optical backup systems alongside primary digital records.
- Thermal retransfer-printing convergence:High-resolution on-disc labeling technology merges with automated archival robotics to serve government intelligence and medical imaging repositories.
- EU Green Deal circularity incentives:Recycled polycarbonate feedstock certification opens premium pricing tiers for sustainability-scored institutional procurement.
Industry Challenges
- Stamper engineering talent scarcity:Precision electroforming expertise for master disc production concentrates among retiring specialists in German and Japanese toolmaking clusters.
- REACH compliance timeline compression:Evolving chemical disclosure requirements for substrate additives force reformulation cycles that outpace standard product certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duplication Disc Market |
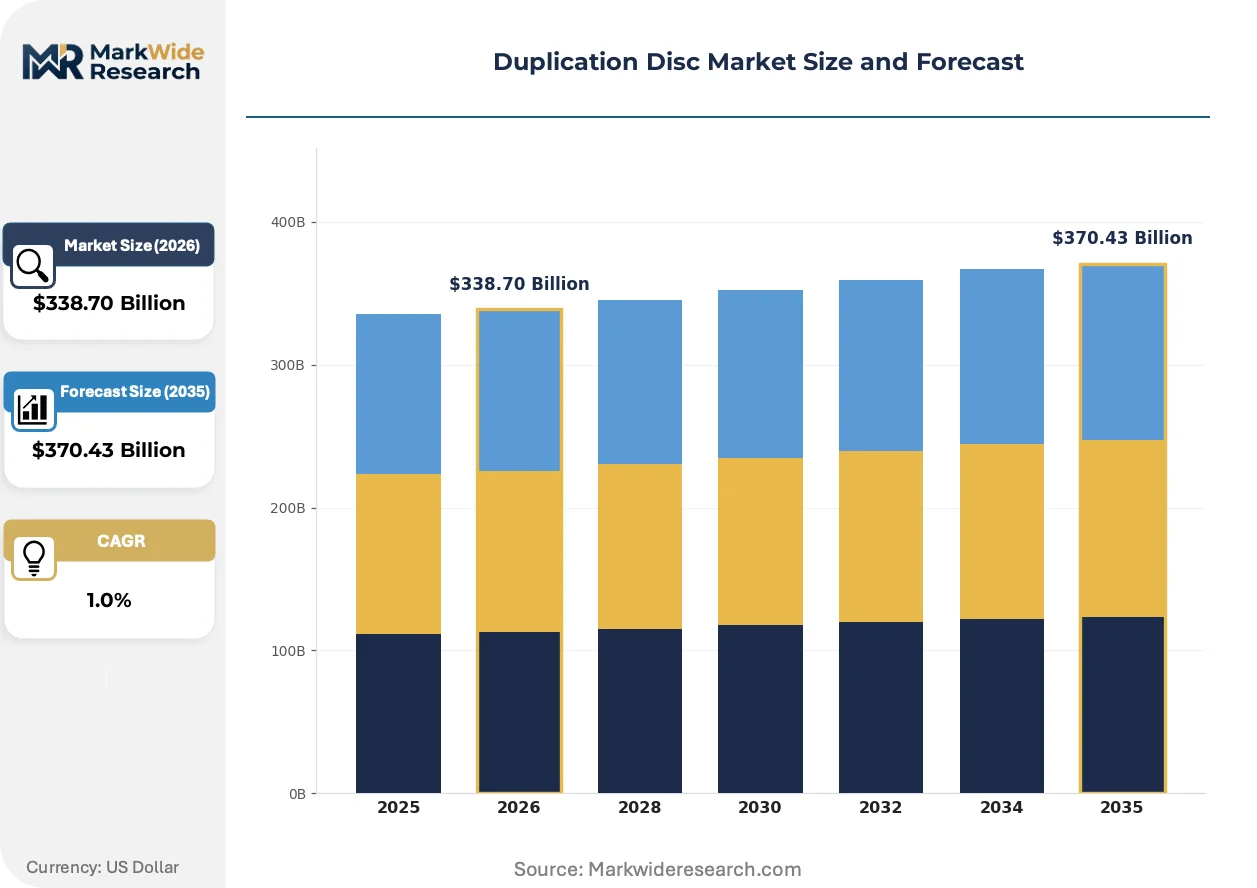
| Market Size in 2026 | $338.70 Billion |
| Market Size in 2035 | $370.43 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CD, DVD, Blu-ray, Digital Download Technology: Physical Media, Cloud Storage, Optical Technology, Analog Transfer End User: Retailers, Educational Institutions, Corporations, Media Companies Customization Options: Labeling, Packaging, Content Variation, Format Choice |
| Companies Covered | Rimage Corporation, Microboards Technology, Primera Technology, Vinpower Digital, Disc Makers, Epson, TEAC Corporation, Acronova Technology, All Pro Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duplication Disc Market Emerging Trajectories
Active reshaping of the duplication disc landscape centers on physical-digital hybrid architectures, regulatory chemistry constraints, and automation of archival infrastructure as buyers prioritize tamper-evident retention over convenience.
Archival-grade gold reflective layer technology is miniaturizing deposition thickness while maintaining oxidation resistance for century-scale data retention. National film archives and audio preservation laboratories in the United States and Japan are adopting these substrates for bit-perfect analog-to-digital migration projects. The structural compression of sputtering equipment footprints enables distributed manufacturing nodes closer to end-use clusters.
REACH substance restriction expansions are forcing reformulation of polycarbonate stabilizers and reflective layer alloys across European supply chains. Manufacturers serving institutional healthcare and government markets must now maintain dual-certified substrate inventories. German duplication equipment vendors report extended qualification periods as buyers verify compliance documentation through ECHA-registered supply chain databases.
Healthcare systems are consolidating optical media procurement through centralized supply agreements that bundle disc manufacturing with automated labeling and robotic archival retrieval. Independent radiology networks and regional hospital alliances in the United States are displacing decentralized purchasing. This concentration favors vendors with integrated thermal printing and tower duplication capabilities over commodity blank disc suppliers.
Duplication Disc Market Segmentation
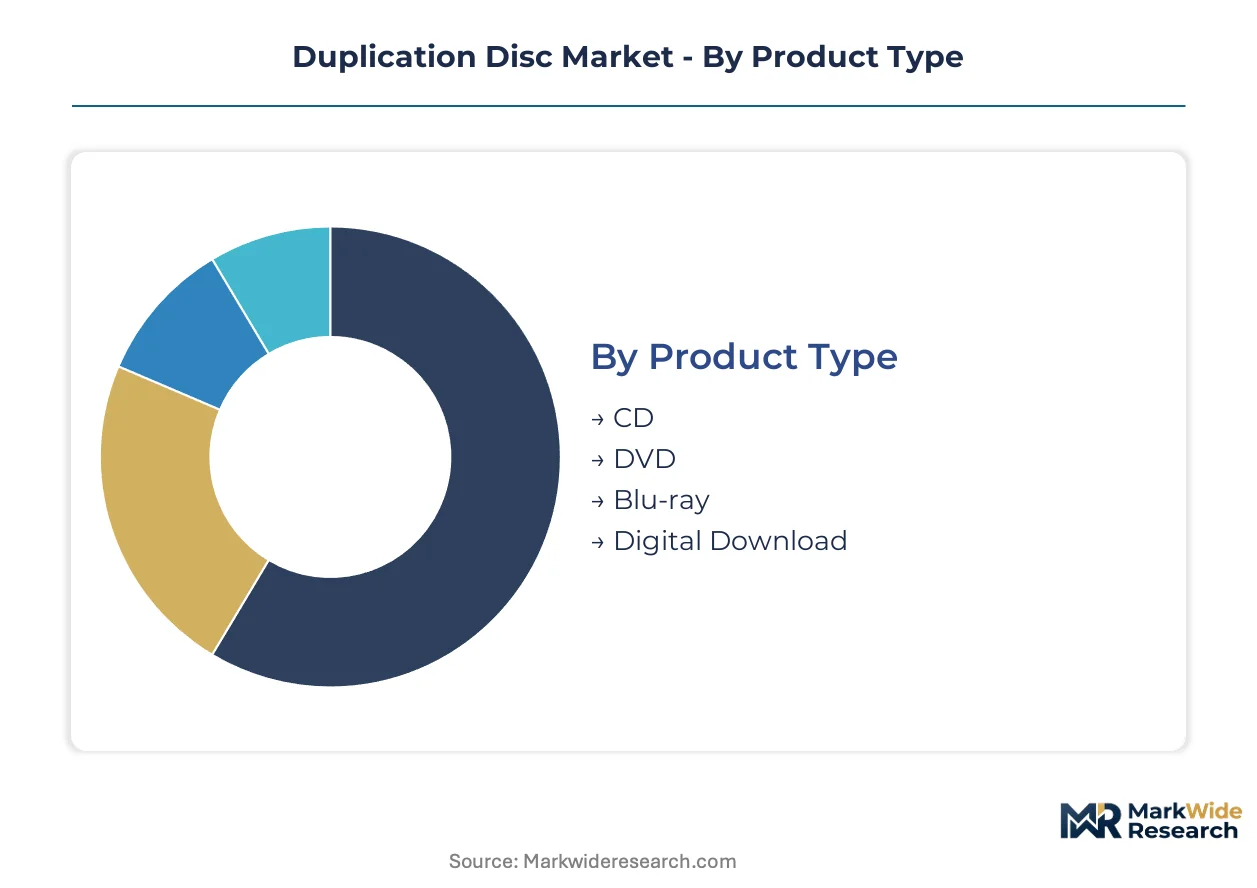
Duplication disc procurement patterns diverge sharply across product formats and institutional buyer profiles. Technology choices and end-use regulations fragment demand into specialized supply channels with distinct certification requirements.
Product Type:
Domestic archival mandates in Germany and Japan sustain physical media demand, while export-oriented music distribution favors short-run CD and DVD formats.
- CD:Polycarbonate substrate with aluminum reflective layer, 700 MB capacity, 74-80 minute audio standard. German automotive suppliers use CD-R for manufacturing quality documentation under long-term retention laws; REACH-compliant substrate certification filters Asian commodity suppliers from institutional tenders.
- DVD:Dual-layer polycarbonate construction with 4.7-8.5 GB capacity, employing organic dye or phase-change recording layers. US healthcare networks deploy DVD-R for medical imaging archives where HIPAA requires tamper-evident write-once retention; procurement concentrates through centralized hospital supply agreements.
- Blu-ray:25-50 GB capacity via 405 nm blue laser technology with hard-coat protective surface. Japanese national film archives adopt gold-reflective archival grades for bit-perfect analog-to-digital migration under METI durability frameworks.
- Digital Download:File-based distribution without physical substrate, relying on server infrastructure and bandwidth provisioning. Independent music distributors use this channel for direct-to-creator release, bypassing manufacturing lead times entirely.
CD and DVD together hold the largest share; momentum sits with Blu-ray archival grades.
Technology:
Cost tiers separate commodity replication from premium compliance-grade manufacturing with specialized certification overhead.
- Physical Media:Injection-molded polycarbonate discs with stamped or burned data layers, requiring stamper replication and spin-coating equipment. German industrial compliance archiving sustains procurement for manufacturing quality documentation and environmental audit trails.
- Cloud Storage:Distributed server architectures with redundant data centers, subscription-based access models. Transactional data workflows in US financial services increasingly migrate here, shrinking addressable volume for short-cycle rewritable optical media.
- Optical Technology:Write-once-read-many formats with tamper-evident properties, gold or silver reflective layers, and century-scale archival specifications. EU healthcare systems require heavy-metal-free substrates under RoHS-aligned procurement mandates.
- Analog Transfer:Legacy audio preservation using specialized hardware for bit-perfect migration from magnetic tape or vinyl sources. US and Japanese audio preservation laboratories drive demand for ultra-stable gold reflective layer substrates.
Optical technology commands premium pricing; cloud storage is climbing the fastest in volume terms.
End User:
Customer type determines whether procurement flows through centralized institutional tenders or fragmented direct channels.
- Retailers:Brick-and-mortar and e-commerce distributors stocking packaged media for consumer resale. German retail chains face EU Green Deal circularity incentives for recycled polycarbonate feedstock certification.
- Educational Institutions:Universities and K-12 systems using discs for course materials, research archives, and library preservation. US regional university systems consolidate optical media procurement through shared services alliances.
- Corporations:Enterprise buyers deploying discs for compliance archiving, training distribution, and quality documentation. Indian pharmaceutical exporters use optical backup for CDSCO track-and-trace mandates alongside primary digital records.
- Media Companies:Film studios, record labels, and broadcasters mastering content for physical distribution. Short-run custom media specialists serve independent music and video distribution with direct-to-creator channel control.
Corporations hold the largest share; educational institutions are gaining share fastest through centralized supply agreements.
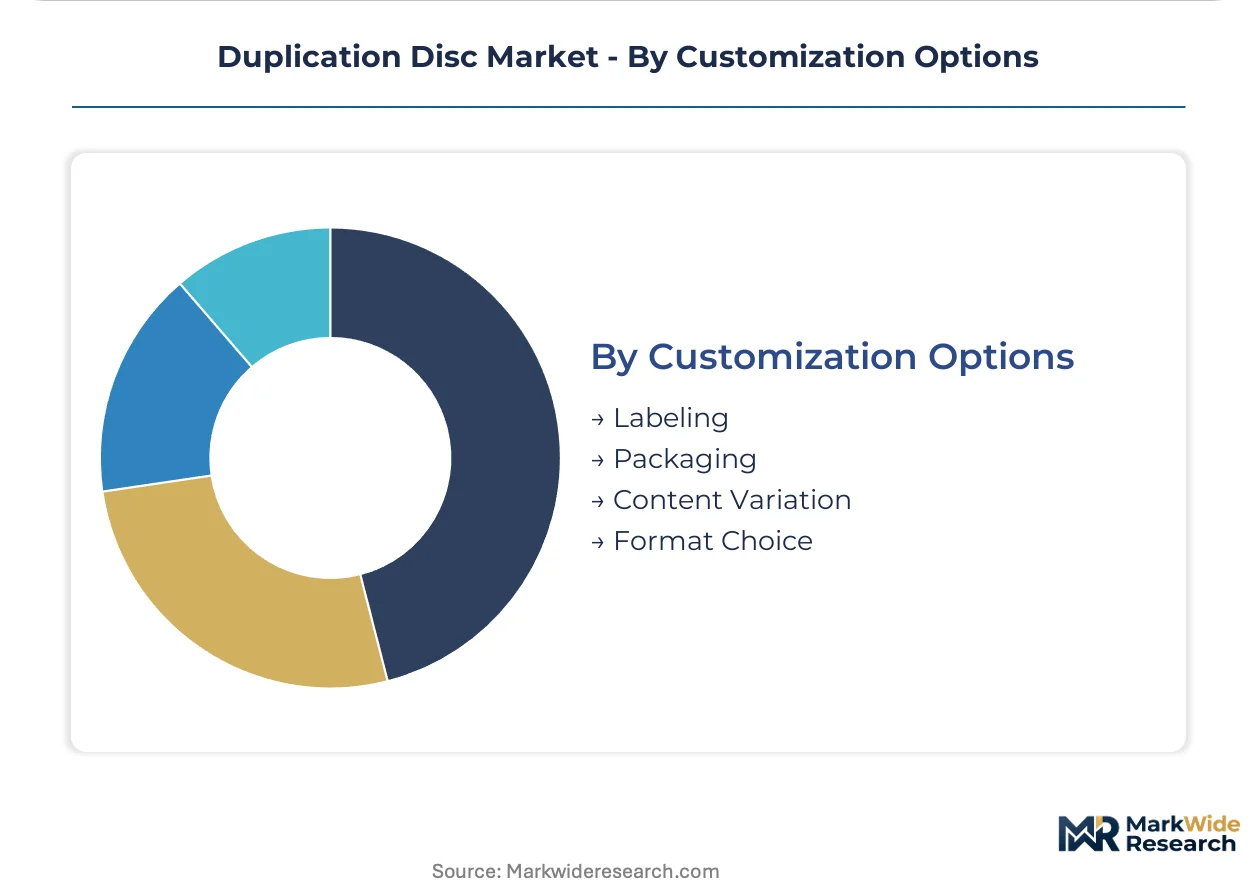
Customization Options:
Margin pools concentrate in value-added services rather than commodity blank disc manufacturing, with automation reshaping service delivery.
- Labeling:Thermal retransfer printing, screen printing, or lithographic disc surface decoration. Rimage Corporation anchors government and medical archive contracts through high-assurance labeling expertise.
- Packaging:Jewel cases, digipaks, eco-wallet designs, and retail-ready box sets. EU Green Deal recycled content mandates open premium pricing tiers for sustainability-scored institutional procurement.
- Content Variation:Multi-language tracks, regional encoding, bonus material inclusion, and version control. Media companies use this for territory-specific release strategies.
- Format Choice:Selection between CD, DVD, Blu-ray, or hybrid multi-format packages. Healthcare systems bundle disc manufacturing with automated labeling and robotic archival retrieval.
Labeling holds the largest share; packaging shows the steepest expansion trajectory through circularity incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German duplication equipment exports supply healthcare archiving systems across the European Union, while Japanese archival-grade substrate manufacturers serve North American film preservation laboratories. Taiwan-based tower assembly lines feed North American integrators facing single-source vulnerability.
United States
Medical imaging networks and national film archives drive demand for tamper-evident write-once media. The EPA regulates hazardous substances in optical disc substrate production under TSCA. Healthcare procurement concentrates through centralized hospital supply agreements in regional alliances across the Midwest and Southeast.
Germany
Automotive suppliers and industrial manufacturers require CD-R formats for manufacturing quality documentation under long-term retention laws. The EU F-Gas Regulation restricts certain manufacturing inputs for physical media production. Duplication equipment vendors in Baden-Württemberg report extended qualification periods as buyers verify REACH compliance documentation.
Japan
National film archives and audio preservation laboratories adopt gold-reflective archival grades for bit-perfect analog-to-digital migration. METI promotes JIS standards for optical media durability in climate-vulnerable storage environments. Sputtering equipment manufacturers in the Kanto region enable distributed manufacturing nodes with compressed footprints.
India
Pharmaceutical exporters require optical backup systems for CDSCO track-and-trace mandates alongside primary digital records. The country's national pharmaceutical regulator enforces serialization requirements for export drug packaging. Manufacturing clusters in Maharashtra and Gujarat are integrating tamper-evident disc systems into compliance infrastructure.
Taiwan
Tower duplication equipment manufacturing concentrates in assembly lines serving North American integrators. The country's central technology regulator oversees standards alignment with international optical media specifications. Precision injection molding operations in Hsinchu Science Park supply substrate components to certified archival-grade producers.
Duplication Disc Market Vendor Landscape
Player mix skews toward specialized equipment fabricators with thermal printing integration capabilities. Market structure exhibits moderate consolidation around vendors bundling disc manufacturing with automated labeling and robotic archival retrieval. Two strategic archetypes dominate: integrated solution providers combining hardware, media, and software; and component specialists focusing on stamper replication or tower density engineering. Competitive moves center on strategic partnerships with healthcare procurement alliances and geographic expansion through distributed sputtering equipment nodes.
Within the integrated solution tier, Rimage Corporation and Vinpower Digital exemplify contrasting scale positions. Rimage Corporation anchors government and medical archive contracts through high-assurance labeling expertise. Vinpower Digital occupies the manufacturing-scale end with duplication tower density capabilities across North American and Asian assembly lines. Disc Makers represents the independent channel archetype, serving music and video distribution with direct-to-creator positioning.
| Leading Market Players |
|---|
| Rimage Corporation |
| Microboards Technology |
| Primera Technology |
| Vinpower Digital |
| Disc Makers |
| Epson |
| TEAC Corporation |
| Acronova Technology |
| All Pro Solutions |
| Others |
Supply Flow & Price Mechanics
Polycarbonate resin substitution for recycled feedstock under EU Green Deal circularity mandates simultaneously redraws manufacturing geography toward certified European recyclers and compresses margin structures for Asian commodity producers serving price-sensitive institutional buyers.
Pricing Analysis
Blu-ray archival-grade media commands substantial premiums over DVD-R and CD-R formats due to gold-reflective layer deposition costs and century-scale durability certifications. Three-tier pricing structure across premium archival, standard compliance, and economy bulk tiers separates healthcare procurement from independent music distribution. Cost compression in economy-grade substrates intensifies because petrochemical feedstock volatility erodes producer margins. Educational institutions exhibit highest price sensitivity through shared services alliances, while government intelligence archives demonstrate lowest sensitivity due to tamper-evidence requirements.
Supply Chain Analysis
Taiwan and mainland China anchor tower duplication equipment manufacturing, while Germany and Japan concentrate precision stamper replication expertise. Polycarbonate resin draws from petrochemical complexes, gold sputtering targets from precious metals refiners, and injection molding tooling from specialized toolmakers. Single-source vulnerability pervades North American integrators dependent on Taiwanese assembly lines for duplication hardware. Distribution runs through institutional procurement alliances in healthcare and direct-to-creator channels in media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare archival mandates for tamper-evident write-once media signal early-cycle expansion as hybrid physical-digital retention systems displace pure-cloud strategies in regulated sectors.
For Market Incumbents: Fortify stamper engineering capabilities through apprenticeship pipelines in German and Japanese toolmaking clusters before specialist retirement accelerates. Secure REACH-compliant substrate certification dual-inventories to filter uncertified competitors from EU healthcare tenders. Cloud storage substitution in transactional workflows threatens short-cycle rewritable volume; vertical integration into thermal retransfer printing preserves margin pools in government and medical archive contracts. For New Entrants and Emerging Players: Lead with Indian pharmaceutical serialization compliance as CDSCO track-and-trace mandates create optical backup demand alongside primary digital records. Target sustainability-scored institutional procurement in German retail chains seeking recycled polycarbonate feedstock certification. Pursue automated archival robotics partnerships with regional hospital alliances consolidating optical media procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed duplication equipment fabricators lacking integrated thermal printing capabilities. Long-term viability hinges on healthcare and government retention mandates persisting through regulatory continuity across political cycles. Acquisition candidates include component specialists in stamper replication or tower density engineering with certification moats. Watch for REACH substance restriction expansions forcing reformulation cycles that outpace standard product windows as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stamper Replication | German toolmaking clusters preserve precision electroforming expertise against specialist retirement. |
| REACH-Compliant Substrate Certification | ECHA-registered supply chain databases filter uncertified Asian commodity suppliers from EU tenders. |
| Automated Archival Robotics Deployment | US regional hospital alliances consolidate procurement through bundled disc manufacturing and retrieval systems. |
| Recycled Polycarbonate Feedstock Sourcing | EU Green Deal circularity incentives open premium pricing tiers for sustainability-scored institutional buyers. |
| Thermal Retransfer Printing Convergence | High-resolution on-disc labeling merges with archival infrastructure for government intelligence repositories. |
Methodological Framework
Initial hypotheses were tested against primary input from duplication equipment engineers, healthcare procurement managers, optical media manufacturing directors, and regulatory compliance officers, then refined through secondary validation against EPA TSCA filings, EU ECHA substance databases, Japan METI JIS standards documentation, and customs trade records for polycarbonate substrate flows. Bottom-up demand modeling across institutional buyer segments triangulated with top-down market sizing from equipment shipment data.
Variance decomposition across product format, technology generation, end-user vertical, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration. Industry-specific forecast inputs included healthcare archival mandate implementation timelines and REACH substance restriction evolution patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of write-once retention requirements or accelerated cloud storage substitution would require recalibration. Forecasts reflect documented assumptions regarding polycarbonate resin cost stability and stamper engineering talent availability. Recalibration cycles align with material shifts in EU chemical disclosure requirements and healthcare procurement centralization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Asia-Pacific Optical Film Market
Optical Components
South Korea Optical Detector Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
Europe Scintillator Market
Optical Components
Global Optical Imaging System Market
Optical Components
Photosensitive Glass Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Diode Laser Module Market
Optical Components
Electro Optical System Market
Optical Components
Global Optical Diode Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Optical Encoder Market