
 Passive Optical Component Market | 2026-2036
Passive Optical Component Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Optical Component Market Analysis
Premium wavelength-selective filters and commodity couplers is consolidating into separate supply chains with divergent qualification requirements. Corning Incorporated anchors North American fiber supply through captive glass-drawing operations and backward integration into silica preform manufacturing. Fujikura Ltd. differentiates in Asia-Pacific through specialty fusion splicer bundling and precision cleaver ecosystems that lock in connector demand. ZTE Corporation competes on volume scale in splitter modules for state-backed fiber rollout programs.
Passive optical components are non-powered devices that manipulate, direct, or split light signals in fiber optic networks without electrical conversion, typically operating across the 1260 nm to 1625 nm wavelength window with insertion loss budgets below 0.5 dB for single-mode applications. Their primary purpose is to distribute, combine, or filter optical signals in telecommunications infrastructure, data center interconnects, and broadcast distribution systems. Connectors command the largest revenue share due to repetitive deployment in last-mile fiber drops, while splitters represent the fastest-expanding margin pool as gigabit passive optical network architectures displace point-to-point fiber in multi-dwelling units. Silicon-based planar lightwave circuit splitters are displacing fused biconical taper alternatives in data center applications where footprint and thermal stability dictate material selection.
China's MIIT enforces GB standards for optical fiber mechanical reliability and environmental testing that determine product access to state procurement tenders. The FCC in the United States conditions Rural Digital Opportunity Fund disbursements on certified optical component interoperability, directing service provider sourcing decisions. India's TRAI mandates quality of service benchmarks for fiber-based broadband that cascade into splitter and connector specifications for BharatNet contractors. Stakeholders must monitor how national broadband subsidy programs synchronize certification timelines with infrastructure deployment schedules.
Market Dynamics
State-backed fiber infrastructure programs across multiple jurisdictions are consolidating procurement volumes around certified component suppliers, compressing qualification timelines and favoring manufacturers with captive preform-to-connector production capabilities.
Growth Catalysts
- Rural Digital Opportunity Fund:FCC disbursement conditions in the United States mandate certified optical component interoperability, directing carrier sourcing toward pre-qualified vendors.
- BharatNet expansion:India's TRAI quality-of-service benchmarks for fiber broadband cascade into splitter and connector specifications for tier-two city contractors.
- Silicon photonics integration:Data center operators are adopting planar lightwave circuit splitters for thermal stability in high-density interconnect environments.
Market Restraints
- Silica preform concentration:Captive glass-drawing operations in select geographies create supply bottlenecks for uncabled fiber feedstock.
- GB certification friction:China's MIIT mechanical reliability testing extends product access timelines for non-domestic manufacturers seeking state tender participation.
- Fused biconical taper displacement:Legacy splitter fabrication equipment faces accelerated obsolescence as planar lightwave circuit platforms capture volume.
Strategic Opportunities
- Multi-dwelling unit penetration:Gigabit passive optical network architectures in India's tier-two municipalities create demand for high-port-count splitter modules.
- Specialty fusion splicer ecosystems:Precision cleaver bundling locks in connector demand across Asia-Pacific installation markets.
- Environmental testing services:GB standards tightening creates adjacent revenue streams for third-party certification laboratories serving export manufacturers.
Industry Challenges
- Fusion splicing technician scarcity:Precision fiber termination skills lag deployment timelines in rural municipalities with accelerated build schedules.
- Preform furnace capex intensity:Backward integration into silica preform manufacturing requires multi-year capital commitments that strain mid-tier balance sheets.
- Multi-standard certification complexity:Concurrent FCC, MIIT, and TRAI qualification timelines fragment product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Optical Component Market |
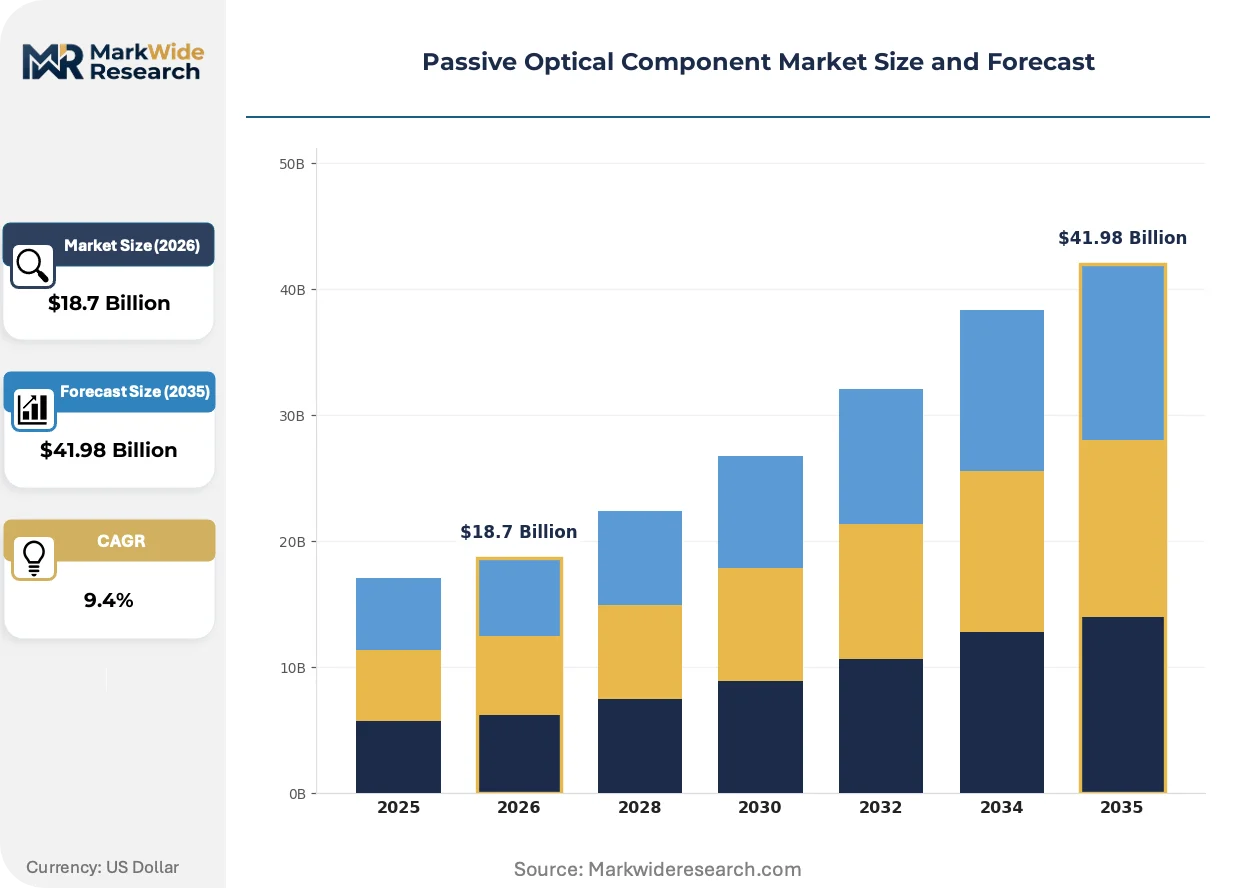
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Filters, Couplers, Splitters, Connectors Material: Glass, Plastic, Silicon, Ceramic Application: Telecommunications, Data Centers, Broadcast, Fiber To The Home End User: Service Providers, Enterprises, Governments, Research Institutions |
| Companies Covered | ZTE Corporation, Adtran, Inc., Corning Incorporated, TE Connectivity Ltd., CommScope Holding Company, Inc., Huawei Technologies Co., Ltd., Fujikura Ltd., NTT Electronics Corporation, Sumitomo Electric Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Optical Component Market Emerging Trajectories
Wavelength-selective filter architectures and connector form factors are diverging across telecommunications, data center, and broadcast verticals, creating distinct qualification ecosystems with incompatible test protocols.
Planar lightwave circuit technology is modularizing splitter manufacturing by enabling wafer-scale fabrication of 1x32 and 1x64 port configurations. Hyperscale data center operators are specifying these devices for spine-leaf architectures where footprint constraints override first-cost considerations. This shift is compressing margins for fused biconical taper specialists while rewarding semiconductor-process competency.
China's MIIT enforcement of GB standards for optical fiber mechanical reliability is restructuring supplier access to state procurement tenders. Domestic manufacturers with in-house environmental testing capabilities are capturing preferential qualification status. Foreign component vendors are responding by establishing joint certification laboratories in Shenzhen and Wuhan.
Carrier procurement patterns are consolidating around turnkey optical distribution network suppliers capable of delivering pre-connectorized cable assemblies. This behavior compresses the addressable market for standalone connector vendors while expanding contract manufacturing relationships. The shift is most visible in United States Rural Digital Opportunity Fund deployments where installation labor scarcity favors plug-and-play solutions.
Passive Optical Component Market Segmentation
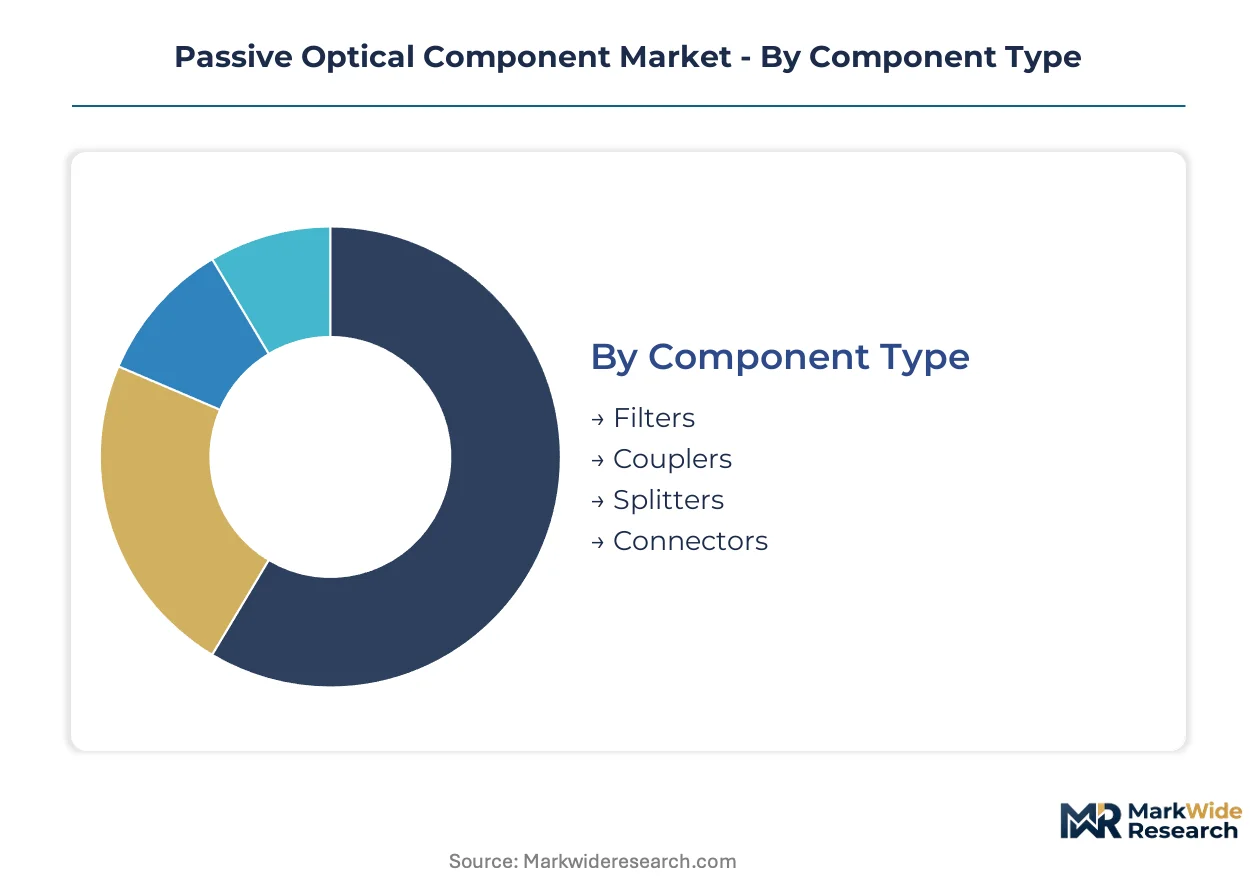
Segmentation in passive optical components reveals how capital intensity, certification requirements, and deployment scale fragment manufacturing strategies. Component type dictates preform-to-finished-glass investment thresholds, while material selection determines compatibility with planar lightwave circuit fabrication or fused biconical taper processes.
Component Type:
Capital intensity varies sharply across this category, with silica preform backward integration and wafer-scale fabrication equipment separating tier-one suppliers from assembly-only competitors.
- Connectors:Ceramic ferrule and precision alignment sleeve assemblies dominate last-mile fiber drops. Procurement concentrates in India's tier-two municipalities under BharatNet contractor specifications, with repetitive deployment cycles favoring vendors with captive ferrule molding capacity.
- Splitters:Planar lightwave circuit platforms enable wafer-scale fabrication of 1x32 and 1x64 port configurations for data center spine-leaf architectures. Thermal stability requirements in high-density interconnect environments are displacing fused biconical taper alternatives.
- Filters:Wavelength-selective thin-film coatings operate across 1260 nm to 1625 nm windows with insertion loss budgets below 0.5 dB. Specialty applications in broadcast distribution systems demand environmental testing beyond standard telecommunications qualifications.
- Couplers:Fused biconical taper fabrication serves legacy point-to-point fiber installations. Margin compression is accelerating as planar lightwave circuit technology captures volume in multi-dwelling unit deployments.
Most installed capacity flows through Connectors. Expansion is steepest in Splitters.
Material:
Material selection determines process compatibility with semiconductor fabrication lines versus traditional glass-drawing operations, creating divergent supplier qualification ecosystems.
- Silicon:Planar lightwave circuit substrates enable thermal stability in data center environments. Hyperscale operators specify these devices where footprint constraints override first-cost considerations.
- Glass:Silica preform drawing anchors connector ferrule and uncabled fiber feedstock supply. Captive operations in select geographies create supply bottlenecks for non-integrated manufacturers.
- Ceramic:Zirconia ferrules provide precision alignment in single-mode connector assemblies. China's GB standards for mechanical reliability testing favor domestic suppliers with in-house environmental laboratories.
- Plastic:Lower-cost alternatives serve temporary installations and indoor drop cables. Performance limitations restrict adoption in outside-plant telecommunications infrastructure.
Glass retains the largest installed base. Silicon is climbing the fastest as data center specifications tighten.
Application:
Application verticals impose incompatible test protocols and qualification timelines, fragmenting product development resources across telecommunications, data center, and broadcast ecosystems.
- Telecommunications:State-backed fiber infrastructure programs consolidate procurement around certified suppliers. FCC Rural Digital Opportunity Fund disbursements mandate component interoperability, directing carrier sourcing toward pre-qualified vendors.
- Fiber To The Home:Gigabit passive optical network architectures displace point-to-point fiber in multi-dwelling units. India's tier-two cities under BharatNet expansion create concentrated demand for high-port-count splitter modules.
- Data Centers:Spine-leaf architectures specify planar lightwave circuit splitters for thermal stability in high-density interconnect environments. Footprint constraints override first-cost considerations in hyperscale procurement.
- Broadcast:Wavelength-selective filter architectures diverge from telecommunications specifications. Distinct qualification ecosystems with incompatible test protocols limit supplier crossover.
Telecommunications commands the deepest installed base. Fiber To The Home shows the steepest expansion trajectory.
End User:
End user type determines volume scale, certification stringency, and installation labor requirements, with service providers consolidating procurement around turnkey optical distribution network suppliers.
- Service Providers:Carrier procurement patterns favor pre-connectorized cable assemblies to address installation labor scarcity. United States Rural Digital Opportunity Fund deployments compress the addressable market for standalone connector vendors.
- Governments:State procurement tenders in China require GB standards compliance that extends product access timelines for non-domestic manufacturers. Domestic suppliers with captive testing capabilities capture preferential qualification status.
- Enterprises:Private data center operators specify planar lightwave circuit devices for thermal stability. Procurement decisions prioritize semiconductor-process competency over traditional fused biconical taper supply relationships.
- Research Institutions:Specialty wavelength-selective filters and precision cleaver ecosystems serve experimental fiber optic networks. Volume scale remains limited compared to commercial telecommunications deployments.
Service Providers account for the largest installed capacity. Governments are gaining share fastest through state-backed fiber rollout programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fusion splicing technician pools concentrate in China's Yangtze River Delta and India's Karnataka telecom corridor. Rural buildout timelines in both markets outpace skilled labor formation.
United States
Rural Digital Opportunity Fund disbursements from the FCC mandate certified optical component interoperability. Carrier procurement concentrates around pre-qualified vendors with captive preform-to-connector capabilities. Installation labor scarcity in Appalachian and Midwestern municipalities favors plug-and-play cable assemblies over field-terminated connectors.
China
State-backed fiber infrastructure programs consolidate procurement volumes around domestic suppliers with in-house environmental testing. MIIT enforcement of GB standards for mechanical reliability extends product access timelines for non-domestic manufacturers. Joint certification laboratories in Shenzhen and Wuhan serve export manufacturers seeking tender participation.
India
BharatNet expansion drives splitter and connector specifications through TRAI quality-of-service benchmarks for fiber-based broadband. Tier-two municipalities in Maharashtra and Gujarat generate concentrated demand for high-port-count splitter modules. Contractor qualification timelines compress as state broadband initiatives accelerate last-mile access deployment.
Japan
Precision cleaver ecosystems and specialty fusion splicer bundling lock in connector demand across Asia-Pacific installation markets. METI standards for optical fiber compatibility influence regional procurement specifications. Industrial clusters in Nagoya and Osaka anchor semiconductor-process competency for planar lightwave circuit fabrication.
Germany
Data center spine-leaf architectures in Frankfurt and Munich specify planar lightwave circuit splitters for thermal stability in high-density interconnect environments. CE marking requirements and RoHS compliance shape component sourcing decisions. Precision manufacturing traditions in Baden-Württemberg support specialty wavelength-selective filter production for broadcast distribution systems.
Passive Optical Component Market Vendor Landscape
Top-tier vendors anchor captive preform-to-connector production, while mid-tier assembly specialists compete on certification velocity and regional procurement relationships. The vendor base separates into three strategic archetypes: integrated glass-drawing operations, semiconductor-process fabricators, and turnkey optical distribution network suppliers. Consolidation pressures favor manufacturers with backward integration into silica preform manufacturing. Capacity expansion and strategic partnerships dominate competitive moves as qualification timelines compress.
Among Asia-Pacific-based fabricators, Fujikura Ltd. and NTT Electronics Corporation exemplify specialty equipment bundling strategies that lock in connector demand. Corning Incorporated occupies a position representing North American captive supply integration from preform drawing through finished component assembly. ZTE Corporation sits within the scale-driven tier serving state-backed fiber rollout programs with volume splitter module production.
| Leading Market Players |
|---|
| ZTE Corporation |
| Adtran, Inc. |
| Corning Incorporated |
| TE Connectivity Ltd. |
| CommScope Holding Company, Inc. |
| Huawei Technologies Co., Ltd. |
| Fujikura Ltd. |
| NTT Electronics Corporation |
| Sumitomo Electric Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Silica preform spot pricing cascades through three distinct tiers: captive-drawn fiber commands premium positioning, merchant preform feedstock sits at mid-tier, and assembly-only vendors absorb margin compression from raw material volatility.
Pricing Analysis
Bundled turnkey optical distribution network assemblies capture 15-20% pricing premiums over unbundled connector components in United States Rural Digital Opportunity Fund deployments. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified suppliers from FCC-qualified vendors from uncertified assembly houses. Cost compression in economy-tier fused biconical taper splitters is intensifying because planar lightwave circuit platforms capture data center volume. Government contractors show highest price sensitivity; hyperscale data center operators prioritize thermal stability over first-cost.
Supply Chain Analysis
GB certification friction and FCC interoperability mandates gate supplier access to procurement tenders, extending qualification timelines for non-integrated manufacturers. Silica preform drawing concentrates in China, United States, and Japan; planar lightwave circuit fabrication clusters in Taiwan and South Korea. Feedstock dependencies include high-purity silicon wafers, zirconia ferrule blanks, and specialty optical coatings. Single-source vulnerability runs through Yangtze River Delta environmental testing laboratories. Distribution runs through carrier procurement consortia and state-backed infrastructure contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passive optical components function as stable compounders where state-backed fiber infrastructure programs provide demand visibility across multi-year deployment cycles.
For Market Incumbents: Hedge against planar lightwave circuit displacement by securing captive silica preform capacity and accelerating GB certification timelines. Threat from semiconductor-process fabricators capturing data center share demands backward integration into environmental testing capabilities. Priority lever: joint certification laboratories in Shenzhen and Wuhan to compress tender access friction. For New Entrants and Emerging Players: FCC Rural Digital Opportunity Fund disbursement conditions in the United States open a window for pre-qualified turnkey assembly specialists. Most penetrable white-space: India's tier-two municipalities under BharatNet expansion lacking high-port-count splitter module supply. Go-to-market angle: fusion splicer bundling with precision cleaver ecosystems to lock in connector demand. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier assembly specialists possessing certification velocity and regional procurement relationships in underserved fiber corridors. Long-term viability frames around 5-10 year state infrastructure commitment windows. Acquisition target archetype: environmental testing laboratories serving export manufacturers seeking GB compliance. Signal to watch: MIIT enforcement intensity against non-domestic tender participants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Preform Manufacturing | Captive glass-drawing operations insulate Corning and Fujikura from feedstock bottlenecks. |
| Joint Certification Laboratory Establishment | Shenzhen and Wuhan facilities compress GB standards access timelines for foreign vendors. |
| Planar Lightwave Circuit Capacity Expansion | Wafer-scale fabrication of 1x64 splitters captures hyperscale data center procurement. |
| Turnkey Optical Distribution Network Partnerships | Pre-connectorized assemblies address installation labor scarcity in Appalachian municipalities. |
| Specialty Fusion Splicer Ecosystem Development | Precision cleaver bundling locks in connector demand across Asia-Pacific installation markets. |
Methodological Framework
Bottom-up fiber-to-the-home deployment modeling reconciled against top-down silica preform capacity tracking forms the analytical core of this study. Primary interviews with carrier procurement officers, fusion splicing technicians, optical component manufacturing engineers, and BharatNet contractor supervisors combined with secondary validation from FCC disbursement records, MIIT GB standards documentation, TRAI quality-of-service benchmarks, and SEC filings from listed fiber suppliers. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of rural fiber deployment cycles and data center interconnect buildouts anchors the projection framework. Volume and value outputs reflect reconciliation across component type, material substrate, application vertical, and end-user category dimensions throughout the forecast period. CAGRs derive from fitted growth curves calibrated against state infrastructure budget commitments and hyperscale capex disclosure patterns. Industry-specific inputs include silica preform furnace utilization rates and planar lightwave circuit wafer yield assumptions.
Revisions become necessary when MIIT enforcement intensity shifts, FCC Rural Digital Opportunity Fund disbursement schedules accelerate, or planar lightwave circuit yield breakthroughs alter cost structures. Forecasts reflect documented assumptions about certification timeline compression and skilled labor formation rates. A model refresh is warranted upon material change in state broadband subsidy program synchronization with infrastructure deployment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Coating Equipment Market
Optical Components
North America Optical Film Market
Optical Components
Global Optical Imaging System Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Optical Transmitter Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Optical Dome Market
Optical Components
CMP Polishing Machine Market
Optical Components
Laser Module Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
US Optical Sensors Market
Optical Components
Erbium-Doped Fiber Amplifier Market