
 Photodiode Sensors Market | 2026-2036
Photodiode Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Photodiode Sensors Market Analytics
Healthcare monitoring is hardening its position as the dominant demand vertical for photodiode sensors, displacing traditional industrial automation in new-design wins. Hamamatsu Photonics K.K. anchors Japan's precision optics supply chain with captive crystal growth and detector fabrication. Excelitas Technologies Corp. competes through vertically integrated thermal and photonic sensor portfolios spanning aerospace and medical end uses. Vishay Intertechnology, Inc. dominates cost-optimized silicon photodiode production for consumer electronics and automotive ambient light sensing.
Photodiode sensors are semiconductor devices that convert incident photons into electrical current through the photoelectric effect, with responsivity, dark current, and junction capacitance defining performance boundaries for a given wavelength and bias condition. Their primary commercial purpose spans optical power measurement, position sensing, spectroscopy, and high-speed data reception in fiber optic networks. Silicon photodiodes occupy the highest volume tier due to mature CMOS-compatible foundry access and visible-to-near-infrared spectral coverage, while InGaAs variants command premium positioning for telecom and defense applications extending into the short-wave infrared. Optical communication segments are pulling digital-output and pulse-technology variants as 800G and coherent transceiver architectures displace legacy analog front ends.
FDA 510(k) clearance pathways and EU MDR Class IIa/IIb device classifications shape product development cycles for medical-grade photodiodes, with biocompatibility and electromagnetic compatibility testing adding eighteen to thirty-six months to qualification timelines. ISO 9001 and IEC 60825 laser safety standards further constrain supplier selection for OEMs serving regulated end markets. Stakeholders must monitor how REACH substance restrictions and RoHS recast directives affect germanium and III-V material sourcing before committing to long-term foundry agreements.
Market Dynamics
Optical communication architectures are forcing photodiode suppliers to abandon analog front-end designs as 800G transceivers and coherent detection systems demand digital-output and pulse-technology variants with integrated amplification.
Growth Catalysts
- EU MDR Class IIa/IIb pathways:Medical device reclassification is tightening performance validation requirements for optical biosensors, pulling premium-grade photodiodes into pulse oximetry and diagnostic imaging systems.
- Automotive LiDAR development:Advanced driver-assistance systems in Germany are consuming InGaAs and silicon avalanche photodiodes for time-of-flight ranging at 905nm and 1550nm wavelengths.
- Telecom infrastructure refresh:Fiber optic network densification is accelerating demand for high-speed InGaAs PIN photodiodes in coherent optical receivers.
Market Restraints
- III-V epitaxy supply concentration:InGaAs wafer production concentrates among a handful of compound semiconductor foundries, exposing buyers to indium phosphide substrate allocation constraints.
- Dark current thermal sensitivity:Germanium photodiodes suffer elevated noise floors above 25°C ambient, limiting outdoor and uncooled defense applications.
- RoHS recast substance restrictions:REACH Annex XVII cadmium and lead exemptions for infrared optics are narrowing, complicating legacy detector material sourcing.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing are attracting photodiode packaging investment away from traditional East Asian hubs.
- Silicon photonics convergence:Monolithic integration of germanium-on-silicon photodetectors with CMOS electronics is collapsing receiver module footprints for data center interconnects.
- Japan METI carbon neutrality roadmap:Energy efficiency mandates for industrial sensors are creating preference for low-bias silicon photodiodes in factory automation retrofits.
Industry Challenges
- Cleanroom technician scarcity:Compound semiconductor wafer fabrication requires specialized MOCVD and ion implantation expertise that outpaces vocational training output.
- FDA 510(k) timeline compression:Biocompatibility and electromagnetic compatibility testing for medical-grade photodiodes extends qualification cycles beyond typical automotive product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photodiode Sensors Market |
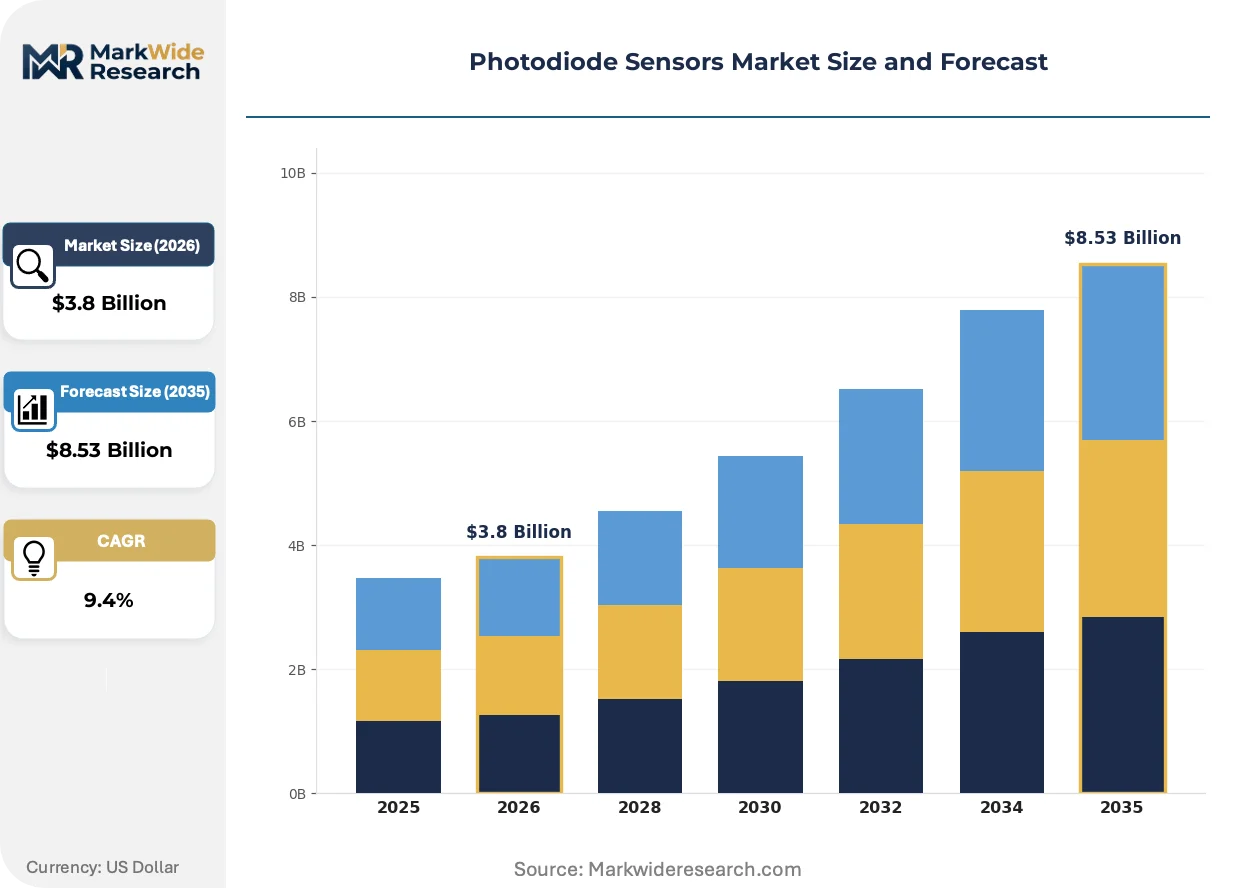
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Silicon, InGaAs, Gallium Phosphide, Germanium Application: Industrial Automation, Healthcare Monitoring, Consumer Electronics, Optical Communication Technology: Analog, Digital, Linear, Pulse End User: Manufacturers, Medical Institutions, Electronics Companies, Research Labs |
| Companies Covered | Hamamatsu Photonics K.K., Thorlabs, Inc., Edmund Optics, Inc., Excelitas Technologies Corp., Everlight Electronics Co., Ltd., Vishay Intertechnology, Inc., OSRAM Opto Semiconductors GmbH, First Sensor AG, TT Electronics plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photodiode Sensors Market Evolving Landscape
Photodiode technology is bifurcating between commodity silicon devices for ambient light sensing and specialized III-V structures for coherent optical systems, with packaging innovation becoming the primary differentiation lever.
Silicon germanium-on-insulator photodetectors are rewriting receiver economics for 400G and 800G datacenter transceivers. Cloud hyperscalers are qualifying these devices for 1310nm and 1550nm operation at 56Gbaud and above. The technology is compressing module costs by eliminating discrete InGaAs chips and hermetic packages from pluggable form factors.
EU MDR technical documentation requirements are reshaping supplier qualification protocols for medical photodiodes. OEMs now demand ISO 13485-certified manufacturing with complete traceability from crystal growth through final test. Pulse oximetry module manufacturers serving European hospitals are consolidating vendor bases to reduce audit burden.
Direct procurement from foundries is displacing distribution channels for high-volume photodiode consumers. Automotive Tier-1 suppliers and telecom module houses are establishing annual volume agreements with Hamamatsu and Excelitas, bypassing regional distributors. This pattern is most visible in Germany and Japan, where precision optics clusters enable just-in-time wafer delivery.
Photodiode Sensors Market Segmentation
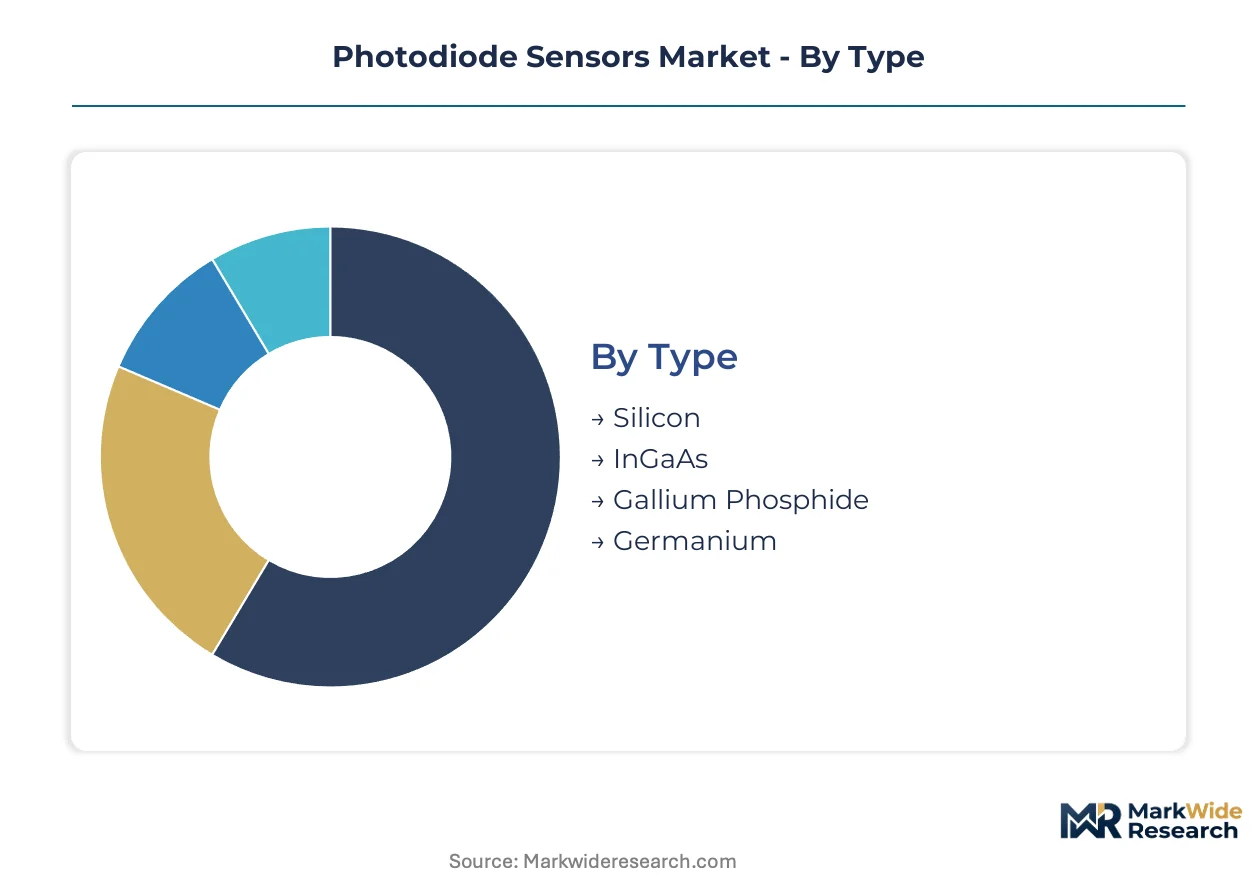
Photodiode sensor procurement splits sharply between commodity silicon devices for high-volume consumer applications and precision III-V compounds for regulated medical and defense end uses. Material selection cascades through wafer sourcing, packaging protocols, and qualification timelines, creating distinct supply ecosystems that rarely intersect.
Type:
Customization intensity peaks with epitaxial layer engineering for defense and telecom wavelengths, while silicon leverages standardized CMOS foundry flows.
- Silicon:CMOS-compatible fabrication enables foundry access at mature process nodes. Consumer electronics ambient light sensing and automotive LiDAR in Germany pull the highest wafer volumes.
- InGaAs:Lattice-matched indium phosphide substrates deliver short-wave infrared responsivity for coherent optical receivers. Telecom infrastructure refresh in Japan and Germany concentrates demand for PIN and avalanche architectures.
- Gallium Phosphide:Direct bandgap properties suit ultraviolet detection and flame sensing applications.
- Germanium:Near-infrared absorption extends silicon economics to 1600nm, though thermal dark current limits uncooled deployments.
Leading the category by volume: Silicon. Expanding most quickly: InGaAs.
Application:
End-use concentration follows regulatory intensity, with FDA and EU MDR pathways filtering suppliers for clinical-grade segments.
- Healthcare Monitoring:Pulse oximetry and diagnostic imaging systems demand ISO 13485-certified manufacturing with full traceability. EU MDR Class IIa/IIb reclassification extends qualification cycles for optical biosensors.
- Optical Communication:800G transceivers and coherent detection architectures displace analog front ends with digital-output variants. Cloud hyperscalers in Germany and Japan drive qualification of silicon germanium-on-insulator photodetectors.
- Industrial Automation:Factory retrofit programs under Japan METI carbon neutrality mandates favor low-bias silicon devices for energy efficiency.
- Consumer Electronics:Ambient light sensing and proximity detection in smartphones and wearables prioritize cost-optimized silicon photodiodes.
Fastest-growing application: Healthcare Monitoring. Highest volume: Consumer Electronics.
Technology:
Output format selection hinges on system integration complexity, with digital variants commanding premium positioning in high-speed data links.
- Digital:Integrated amplification and A/D conversion collapse receiver module footprints for 400G and 800G datacenter interconnects.
- Pulse:Time-of-flight ranging for automotive LiDAR consumes avalanche photodiodes at 905nm and 1550nm wavelengths.
- Analog:Legacy front-end designs persist in industrial sensing where signal conditioning remains external.
- Linear:Position sensing and spectroscopy applications require uniform responsivity across active areas.
Steepest expansion trajectory: Digital. Dominant by shipment volume: Analog.
End User:
Procurement authority concentrates with direct foundry relationships for high-volume consumers, while fragmented buyers rely on distribution.
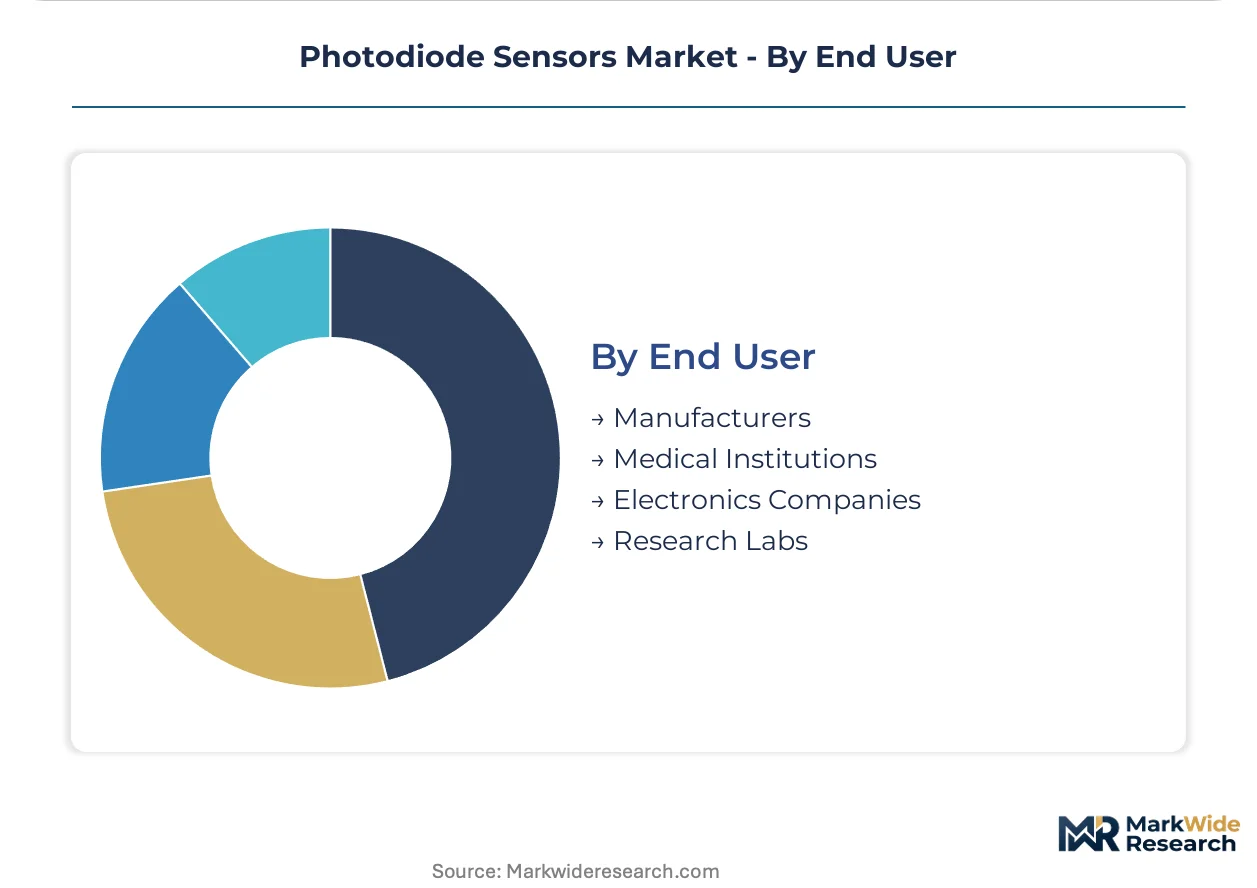
- Electronics Companies:Smartphone and automotive Tier-1 suppliers negotiate annual volume agreements bypassing regional distributors. Germany and Japan precision optics clusters enable just-in-time wafer delivery.
- Medical Institutions:Hospital procurement of pulse oximetry modules consolidates vendor bases to reduce EU MDR audit burden.
- Manufacturers:Industrial OEMs source through authorized distributors with ISO 9001 certification requirements.
- Research Labs:Low-volume, high-mix procurement tolerates longer lead times for specialized detector geometries.
Volume leader: Electronics Companies. Procurement consolidation fastest: Medical Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and Germany concentrate photodiode wafer fabrication capacity, while the United States and China absorb the highest device volumes through optical communication and consumer electronics demand. India is emerging as an alternative packaging hub under production-linked incentive schemes.
United States
FDA 510(k) clearance pathways shape medical photodiode qualification timelines for pulse oximetry and diagnostic imaging systems. Cloud hyperscalers in Northern Virginia and Oregon drive demand for silicon germanium-on-insulator photodetectors in 800G datacenter transceivers. Boston's precision optics cluster anchors coherent optical receiver development for telecom infrastructure.
Germany
Automotive LiDAR development in Stuttgart and Munich consumes InGaAs and silicon avalanche photodiodes for time-of-flight ranging systems. EU MDR Class IIa/IIb reclassification tightens performance validation requirements for optical biosensors entering European hospitals. The precision optics corridor linking Berlin and Dresden enables just-in-time wafer delivery for automotive Tier-1 suppliers.
Japan
METI carbon neutrality mandates favor low-bias silicon photodiodes in factory automation retrofits across the Chubu industrial belt. Hamamatsu Photonics K.K. anchors domestic supply chains with captive crystal growth and detector fabrication in Shizuoka Prefecture. Tokyo's fiber optic equipment manufacturers accelerate qualification of digital-output variants for coherent detection architectures.
China
MIIT standards for optical communication equipment drive adoption of high-speed InGaAs PIN photodiodes in 400G and 800G transceiver modules. The Yangtze River Delta concentration of compound semiconductor foundries supplies indium phosphide substrates for short-wave infrared detectors. Shenzhen's consumer electronics ecosystem pulls cost-optimized silicon photodiodes for smartphone ambient light sensing.
India
The PLI scheme for electronics manufacturing attracts photodiode packaging investment away from traditional East Asian hubs. BIS certification requirements for medical devices extend qualification timelines for optical biosensor imports. Karnataka's semiconductor assembly and testing corridor near Bangalore is consolidating backend operations for telecom and automotive photodiode modules.
Photodiode Sensors Market Competitive Landscape
Top-tier vendors anchor premium-tier supply for regulated medical and defense applications, while mid-scale fabricators compete on cost-optimized silicon volumes for consumer electronics. Japanese and German precision optics specialists maintain backward integration into crystal growth and epitaxial wafer production. Two strategic archetypes dominate: vertically integrated device manufacturers with captive foundry capacity, and fabless design houses outsourcing III-V epitaxy to compound semiconductor foundries. Capacity expansion and direct procurement agreements with automotive Tier-1 suppliers represent the dominant competitive moves.
Within the integrated-manufacturer tier, Hamamatsu Photonics K.K. and Excelitas Technologies Corp. exemplify archetypes combining captive material production with detector fabrication. Vishay Intertechnology, Inc. occupies a position representing cost-optimized silicon photodiode supply for high-volume consumer and automotive ambient light sensing applications. These three entities collectively illustrate the market's bifurcation between precision-regulated segments and commodity-scale deployment.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Thorlabs, Inc. |
| Edmund Optics, Inc. |
| Excelitas Technologies Corp. |
| Everlight Electronics Co., Ltd. |
| Vishay Intertechnology, Inc. |
| OSRAM Opto Semiconductors GmbH |
| First Sensor AG |
| TT Electronics plc |
| Others |
Value Network & Pricing Analysis
Medical-grade ISO 13485 certification against consumer-grade silicon commoditization splits the photodiode market into divergent pricing and sourcing ecosystems. FDA 510(k) and EU MDR clearance pathways extend qualification timelines for clinical-grade devices, while automotive LiDAR and smartphone ambient light sensing pull high-volume silicon through contract manufacturing channels with compressed lead times.
Pricing Analysis
Lead-time-driven pricing stratification rewards just-in-time wafer delivery with premium positioning, while spot inventory from distributors trades at discounts. Three-tier pricing separates ISO 13485-certified medical devices from automotive-grade qualified products and unqualified consumer silicon, with certification level and volume scale as primary differentiation drivers. Cost compression in commodity silicon intensifies because CMOS foundry access democratizes fabrication, making smartphone OEMs the most price-sensitive buyers while defense contractors show least sensitivity due to performance guarantees.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping photodiode packaging sourcing away from traditional East Asian hubs. Crystal growth and epitaxial wafer production concentrates in Japan, Germany, and the United States, with indium phosphide substrates, high-purity germanium, and III-V epitaxy equipment as critical input dependencies. Single-source vulnerability in InGaAs wafer fabrication exposes buyers to allocation constraints. Distribution runs through direct annual volume agreements for automotive Tier-1 suppliers and telecom module houses, bypassing regional distributors in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound semiconductor cleanroom technician scarcity props pricing for InGaAs and germanium photodiodes, constraining capacity expansion regardless of demand pull from telecom and defense applications.
For Market Incumbents: Anchor captive crystal growth capacity in Shizuoka Prefecture and Dresden precision optics corridors to defend against fabless design houses outsourcing III-V epitaxy. Add ISO 13485-certified manufacturing lines for EU MDR Class IIa/IIb device qualification, extending qualification cycle leverage over emerging entrants lacking medical-grade traceability infrastructure. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer white-space entry for low-volume research lab and industrial sensing segments underserved by Hamamatsu and Excelitas direct sales organizations. Target India's PLI scheme packaging incentives for telecom module backend operations, using BIS certification timelines as competitive moat against established East Asian suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with silicon germanium-on-insulator photodetector specialists given cloud hyperscaler qualification momentum for 800G datacenter interconnects. Long-term viability in the 5-10 year window favors backward-integrated manufacturers with indium phosphide substrate access. Watch FDA 510(k) clearance velocity for pulse oximetry modules as inflection indicator for medical-grade photodiode demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive indium phosphide substrate production secures InGaAs wafer allocation for telecom defense applications. |
| ISO 13485 Certification Investment | EU MDR compliance opens pulse oximetry and diagnostic imaging procurement at European hospital systems. |
| Silicon Germanium-on-Insulator Product Launch | Cloud hyperscaler qualification for 800G transceivers collapses receiver module costs against discrete InGaAs. |
| India PLI Scheme Manufacturing Footprint | Karnataka assembly and testing corridor attracts packaging investment from telecom and automotive module suppliers. |
| Direct Foundry Volume Agreements | Annual contracts with automotive Tier-1 suppliers bypass distribution and enable just-in-time wafer delivery from Berlin-Dresden corridor. |
Research Methodology
Independent corroboration across primary interviews with photodiode design engineers, biomedical equipment procurement managers, automotive LiDAR platform specialists, and compound semiconductor foundry operations directors underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, METI energy efficiency mandate disclosures, and India PLI scheme beneficiary announcements. Bottom-up wafer shipment aggregation from Japan and Germany precision optics clusters triangulates against top-down optical communication equipment demand estimates.
Comparable-period anchoring to historical CMOS foundry utilization rates and III-V epitaxy capacity utilization establishes baseline growth trajectories across the projection horizon. Segmentation modeling spans material type, output technology, application vertical, and end-user procurement authority. CAGRs derive from slope analysis of wafer price trends and equipment content per vehicle in automotive LiDAR deployments. Forecast inputs include cloud hyperscaler datacenter capex disclosures and EU MDR Class IIa/IIb device reclassification implementation timelines.
The model holds under stable indium phosphide substrate supply and sustained FDA 510(k) clearance velocity; deviation in REACH Annex XVII cadmium exemption withdrawals or RoHS recast enforcement would shift germanium and III-V material sourcing economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
United States Smart Sensors Market