
 Optical Switches Market | 2026-2036
Optical Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Switches Market Intelligence
Silicon photonics is decoupling optical switch economics from legacy mechanical assembly costs. Cisco Systems leverages vertically integrated foundry partnerships to secure wafer supply for coherent optical engines. Huawei Technologies anchors its portfolio around proprietary silicon photonics fabrication, insulating its product roadmap from external foundry constraints. Nokia competes through specialized wavelength selective switch designs that dominate submarine cable landing stations.
An optical switch routes light signals between fiber optic pathways without optical-to-electrical conversion, typically operating across the C-band and L-band wavelength ranges with insertion loss below 3 dB. MEMS switches retain structural importance in reconfigurable optical add-drop multiplexers where millisecond switching speeds suffice. Integrated photonic switches are displacing mechanical alternatives in data center interconnects where form factor and power density determine rack economics. Liquid crystal switches occupy niche positions in military applications requiring absence of moving parts under shock and vibration conditions.
FCC equipment authorization rules shape product certification timelines for optical switches deployed in US carrier networks. ETSI standards and the EU AI Act's infrastructure transparency requirements are tightening documentation burdens for European telecommunications procurement. China's GB standards and MIIT network equipment licensing govern domestic market access for foreign suppliers. Stakeholders must monitor how divergent national security review frameworks for critical communications infrastructure reshape vendor qualification criteria across major economies.
Market Dynamics
Silicon photonics integration is collapsing the cost structure of optical switching by eliminating mechanical assembly steps and reducing power consumption per port. This technology transition is redrawing competitive boundaries between foundry-dependent and vertically integrated suppliers.
Growth Catalysts
- AI Traffic Surge:Data center operators in the United States are deploying optical switches to manage machine learning workload densities that exceed electrical interconnect thermal limits.
- F-Gas Regulation:The European Union's phase-down of fluorinated greenhouse gases is accelerating replacement of legacy mechanical switches with solid-state photonic alternatives.
- 5G Backbone Buildout:China's eastern seaboard corridor is concentrating procurement for hyperscale cloud facilities and state-backed fiber infrastructure projects.
Market Restraints
- Wafer Supply Concentration:Advanced silicon photonics fabrication depends on a limited number of specialty foundries concentrated in Taiwan and South Korea.
- Input Cost Volatility:Indium phosphide substrate prices fluctuate with mining output from Chinese rare earth processing facilities.
- Technical Insertion Loss Floors:Silicon photonics waveguides cannot yet match the sub-1 dB loss achieved by traditional fiber-based MEMS architectures.
Strategic Opportunities
- Edge Computing Expansion:Germany's industrial automation clusters present underpenetrated demand for compact optical switches in factory floor networks.
- Submarine Cable Modernization:Wavelength selective switch upgrades at transoceanic landing stations are creating replacement cycles across the Atlantic and Pacific routes.
- Defense Hardening Mandates:Liquid crystal switch platforms are capturing military procurement for shock-resistant communications under US Department of Defense vibration specifications.
Industry Challenges
- Photonics Design Talent Scarcity:The intersection of semiconductor process engineering and optical physics requires specialists that outnumber available training programs.
- Multi-Jurisdiction Certification Burden:FCC equipment authorization timelines, ETSI documentation requirements, and China's MIIT network equipment licensing create sequential approval bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Switches Market |
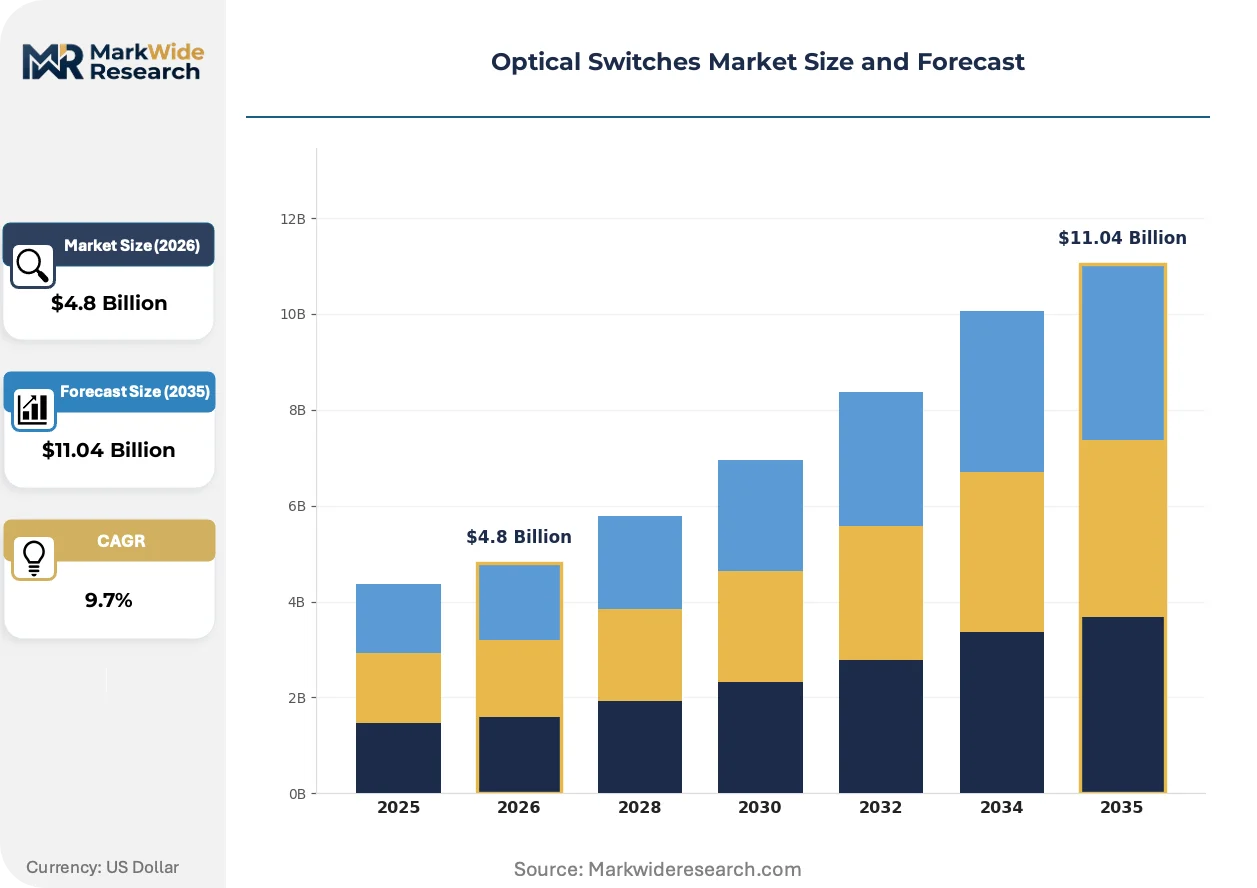
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Switches, MEMS Switches, Liquid Crystal Switches, Optical Matrix Switches End User: Telecommunication Providers, Data Centers, Military Applications, Internet Service Providers Technology: Wavelength Selective Switches, Optical Cross Connects, Free-Space Optical Switches, Integrated Photonic Switches Application: Signal Routing, Network Management, Optical Networking, Fiber Optic Communication |
| Companies Covered | Cisco Systems, Huawei Technologies, Ciena Corporation, Fujitsu, Juniper Networks, Infinera Corporation, Nokia, NEC Corporation, Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Switches Market Strategic Shifts & Innovations
Optical switching architecture is migrating from discrete component assembly toward monolithic photonic integration. This shift is compressing form factors, reducing power budgets, and enabling new deployment topologies that were previously uneconomical.
Silicon photonics is converging with electronic switching fabrics to create co-packaged optical engines. Cloud operators in the United States are adopting these modules for 51.2 Tbps switch capacities. The structural consequence is converging with rack economics by collapsing transceiver-to-switch cabling complexity and reclaiming physical space for compute density.
The EU AI Act's infrastructure transparency requirements are tightening documentation burdens for European telecommunications procurement. ETSI standards bodies are responding with enhanced test specifications for optical switch failure mode reporting. Submarine cable operators are most affected, adapting vessel maintenance protocols to meet new audit trail mandates.
Hyperscale buyers are consolidating vendor relationships and demanding multi-year volume commitments in exchange for design collaboration access. Distributors serving mid-tier data centers are losing relevance as direct procurement channels expand. This pattern is most visible in China's eastern provinces, where state-backed cloud entities negotiate consolidated supply agreements spanning optical switch and fiber infrastructure categories.
Optical Switches Market Segmentation
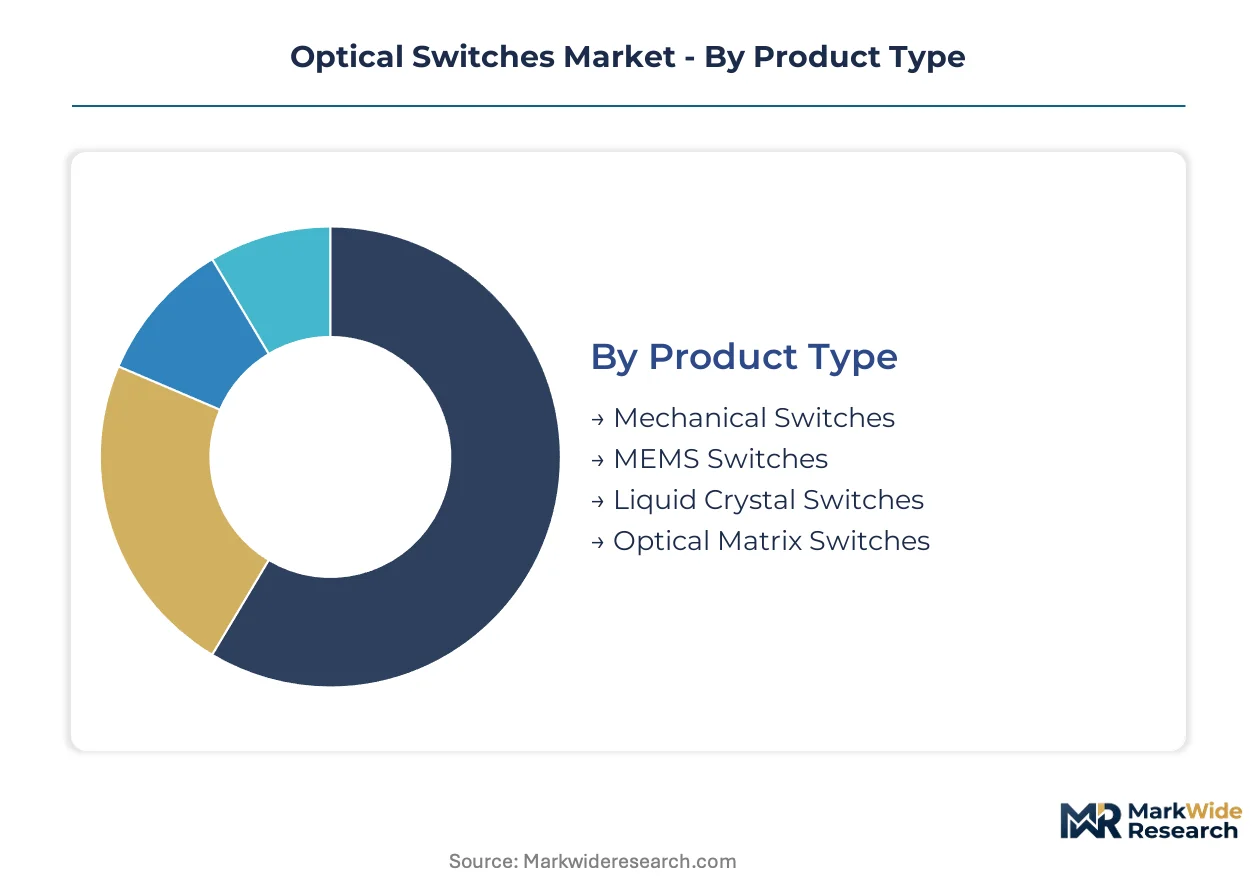
Optical switch procurement patterns diverge sharply across deployment contexts. Product architecture, end-user infrastructure requirements, and integration technology each create distinct specification thresholds that reshape vendor competitive boundaries.
Product Type:
Volume deployment clusters around mature mechanical platforms, while premium positioning concentrates in solid-state alternatives that eliminate moving parts.
- Mechanical Switches:Fiber alignment via precision electromechanical actuators achieves insertion loss below 1 dB in submarine cable landing stations. Demand concentrates in transoceanic infrastructure where proven reliability under seawater pressure dominates procurement criteria.
- MEMS Switches:Micro-electromechanical mirror arrays route signals through free-space optical paths with millisecond reconfiguration speeds. Procurement is accelerating in United States data center interconnects where port density requirements exceed mechanical switch physical limits.
- Liquid Crystal Switches:Electrically controlled birefringence enables polarization-independent routing without mechanical motion.
- Optical Matrix Switches:N×M port configurations support broadcast-and-select architectures in test and measurement environments.
Mature deployment sits with Mechanical Switches. Newer deployment is concentrated in MEMS Switches.
End User:
Procurement scale separates carrier infrastructure from enterprise and defense applications, with specification rigor inversely tracking volume.
- Telecommunication Providers:Long-haul backbone operators demand switches certified to ITU-T G.698.4 standards for coherent optical systems. Deployment concentrates in China's eastern seaboard corridor where state-backed 5G fiber expansion drives batch procurement.
- Data Centers:Hyperscale operators prioritize silicon photonics integration to collapse transceiver-to-switch cabling complexity. Rack economics in United States cloud facilities are forcing adoption of co-packaged optical engines.
- Military Applications:Shock and vibration specifications under US Department of Defense MIL-STD-810G mandate solid-state switching platforms.
- Internet Service Providers:Metro aggregation networks require cost-optimized switches for 10G-400G upgrade cycles.
Carrier-grade deployment dominates Telecommunication Providers. Fastest expansion is occurring in Data Centers.
Technology:
Integration depth separates discrete component solutions from monolithic photonic platforms, with cost trajectories diverging accordingly.
- Wavelength Selective Switches:Liquid crystal on silicon (LCoS) or MEMS grating engines enable flexible-grid spectrum allocation in reconfigurable optical add-drop multiplexers. Submarine cable operators across Atlantic and Pacific routes are driving replacement cycles at landing stations.
- Optical Cross Connects:Large-scale matrix architectures support transparent wavelength switching in central office consolidation projects. European Union F-Gas Regulation compliance is accelerating displacement of refrigerant-dependent legacy systems.
- Free-Space Optical Switches:Collimated beam steering through micro-mirror arrays achieves ultra-low loss in laboratory environments.
- Integrated Photonic Switches:Silicon photonics monolithic integration collapses assembly cost structure for data center interconnects.
Legacy dominance sits with Wavelength Selective Switches. Technology transition is accelerating in Integrated Photonic Switches.
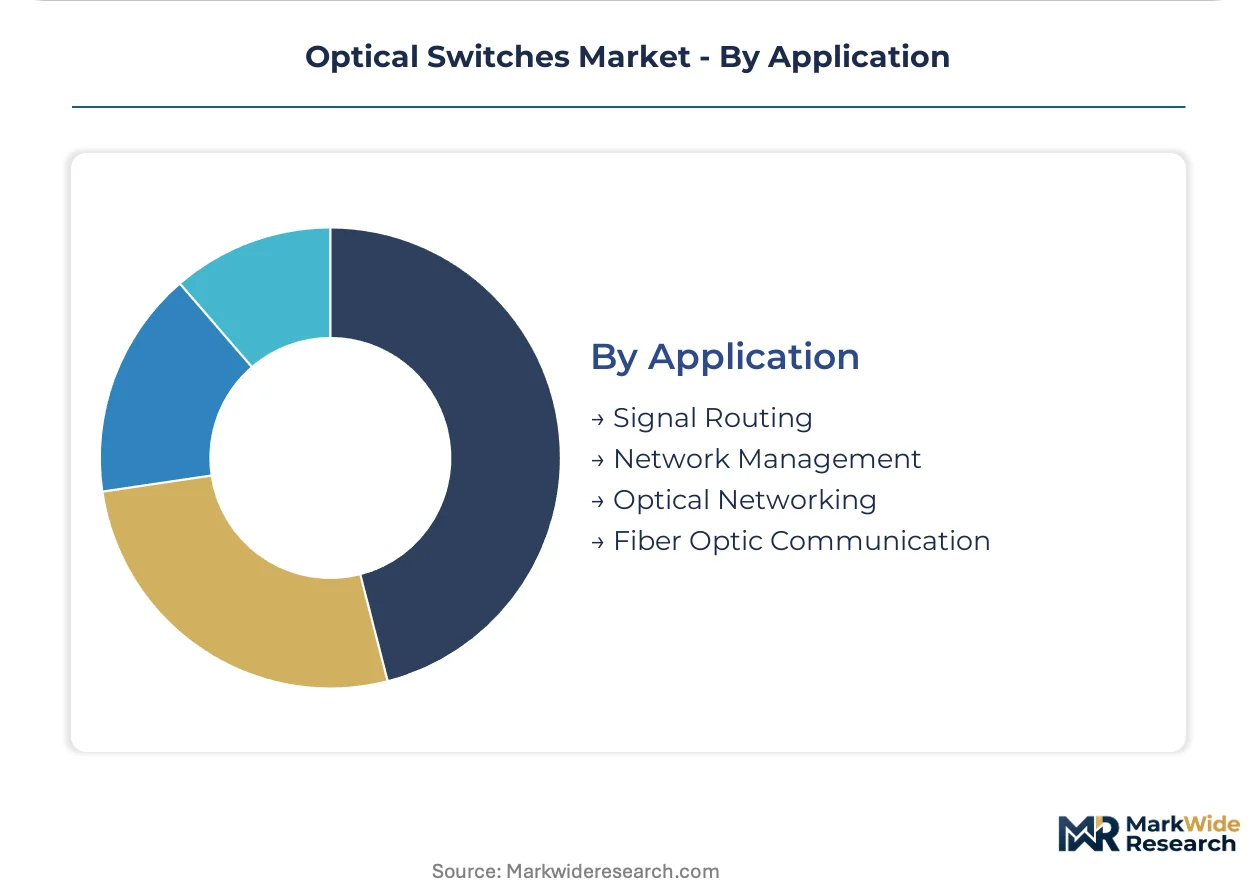
Application:
Functional purpose determines switching speed requirements, with traffic engineering applications demanding faster reconfiguration than static provisioning.
- Signal Routing:Dynamic path selection across fiber routes requires sub-millisecond switch reconfiguration in packet-optical convergence layers. United States AI training clusters are deploying these capabilities to manage workload-dependent bandwidth allocation.
- Network Management:Optical layer monitoring and protection switching demand high reliability with moderate speed requirements. European telecommunications procurement under ETSI standards is tightening failure mode documentation burdens.
- Optical Networking:Mesh restoration and bandwidth provisioning support core transport infrastructure.
- Fiber Optic Communication:Point-to-point link protection represents baseline switching functionality.
Established deployment sits with Network Management. Emerging demand is concentrating in Signal Routing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for optical switches concentrates in three national markets where hyperscale data center buildouts and carrier infrastructure modernization coincide. Procurement volumes track AI training cluster expansion, submarine cable landing station upgrades, and 5G backbone densification programs.
United States
Hyperscale cloud operators in Virginia's Northern Virginia corridor and Oregon's Hillsboro cluster are deploying silicon photonics-based optical switches to manage thermal constraints from machine learning workloads. FCC equipment authorization timelines shape product certification for carrier network deployments. Texas's Dallas-Fort Worth metroplex anchors secondary procurement for edge computing facilities serving autonomous vehicle data processing.
China
State-backed 5G fiber expansion and hyperscale cloud facility construction in the Yangtze River Delta are concentrating procurement volumes. MIIT network equipment licensing governs domestic market access for foreign suppliers. Shenzhen and Hangzhou clusters drive integrated photonic switch adoption for data center interconnect applications.
Germany
Industrial automation clusters in Bavaria present underpenetrated demand for compact optical switches in factory floor networks. The EU F-Gas Regulation accelerates displacement of legacy mechanical switches with solid-state photonic alternatives. Frankfurt's financial data center hub anchors carrier-grade wavelength selective switch procurement for latency-sensitive trading infrastructure.
Japan
Submarine cable landing station modernization across Pacific routes drives wavelength selective switch replacement cycles. METI industrial policy supports domestic silicon photonics foundry capacity expansion. Tokyo-Osaka corridor concentrates procurement for 400G coherent optical system upgrades in metropolitan aggregation networks.
South Korea
Advanced silicon photonics fabrication capacity concentrates in foundry clusters serving global optical component demand. The country's national semiconductor regulator enforces export control compliance for photonic integrated circuit technologies. Seoul's Pangyo technovalley anchors R&D procurement for co-packaged optical engine development.
Optical Switches Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated technology conglomerates commanding premium positioning in carrier infrastructure while fabless designers capture data center interconnect volumes. The vendor base organizes into three tiers: foundry-dependent component suppliers, vertically integrated systems houses, and specialized wavelength management boutiques. Strategic differentiation centers on silicon photonics fabrication access and coherent optical engine design autonomy. Consolidation pressure is intensifying through foundry partnership exclusivity agreements and hyperscale direct procurement channel expansion.
Among North American networking equipment houses, Cisco Systems and Ciena Corporation exemplify divergent strategic postures toward optical switching integration. Cisco's vertically integrated foundry partnerships secure wafer supply for coherent engine production. Ciena occupies a position within the wavelength selective switch specialization tier, serving submarine cable operator upgrade cycles. Nokia, headquartered in Finland, anchors European representation in reconfigurable optical add-drop multiplexer markets. These three companies represent distinct archetypes: captive fabrication, component specialization, and systems integration.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Ciena Corporation |
| Fujitsu |
| Juniper Networks |
| Infinera Corporation |
| Nokia |
| NEC Corporation |
| Furukawa Electric |
| Others |
Cost & Logistics Intelligence
Carrier-grade certification tiers separate submarine cable landing station equipment from data center interconnect commodities, with ITU-T G.698.4 compliance adding 40-60% cost premiums that flow from Taiwan and South Korea foundry qualification requirements through to final procurement contracts. This bifurcation concentrates margin capture in vertically integrated suppliers while commoditizing MEMS-based alternatives.
Pricing Analysis
Volume-vs-margin split separates hyperscale data center procurement from carrier infrastructure. Contract-based long-term offtake dominates submarine cable operators where ITU-T G.698.4 certification and MIL-STD-810G shock specifications create price premiums. Silicon photonics integration and foundry partnership exclusivity drive differentiation. Cost compression in MEMS switches is intensifying because Chinese rare earth processing volatility feeds indium phosphide substrate instability. Data center operators exhibit highest price sensitivity; military procurement shows lowest.
Supply Chain Analysis
Qualification gating through FCC equipment authorization, ETSI documentation, and China's MIIT licensing creates sequential approval bottlenecks that favor incumbent suppliers with established regulatory affairs infrastructure. Advanced silicon photonics fabrication draws from Taiwan, South Korea, and Japan foundry clusters. Indium phosphide substrates, silicon-on-insulator wafers, and LCoS backplanes constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan specialty foundries. Distribution runs through direct procurement channels expanding at distributor expense.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive silicon photonics foundry access determines cost structure control and insulates against wafer supply concentration risks.
For Market Incumbents: Deepen foundry partnership exclusivity agreements to lock wafer allocation ahead of hyperscale demand surges. Secure backward integration into indium phosphide substrate supply to offset Chinese rare earth processing volatility. Cisco Systems and Huawei Technologies exemplify this posture through vertically integrated fabrication strategies.
For New Entrants and Emerging Players: Launch via specialized wavelength selective switch designs targeting submarine cable landing station replacement cycles. Germany's industrial automation clusters present underpenetrated demand for compact liquid crystal switches in factory floor networks. Pursue ETSI certification pathways to bypass incumbent regulatory moats.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscale cloud operators seeking design collaboration control. Long-term viability hinges on silicon photonics fabrication autonomy over the next decade. Watch for MIIT licensing restrictions tightening as the inflection signal for foreign supplier displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Exclusivity | Secures wafer allocation from Taiwan and South Korea specialty fabs against supply concentration. |
| Silicon Photonics Integration | Collapses transceiver-to-switch cabling complexity for 51.2 Tbps co-packaged optical engines. |
| ETSI Certification Investment | Enables European telecommunications procurement under EU AI Act infrastructure transparency mandates. |
| Submarine Cable Landing Station Targeting | Captures wavelength selective switch replacement cycles across Atlantic and Pacific routes. |
| Liquid Crystal Platform Development | Addresses US Department of Defense MIL-STD-810G shock and vibration specifications. |
Research Approach
Multi-period observation of hyperscaler capex disclosures, foundry utilization rates, and carrier network equipment procurement anchored the trend analysis, supplemented by interviews with optical systems architects, data center infrastructure directors, submarine cable network planners, and silicon photonics process engineers. Secondary validation drew from FCC equipment authorization databases, ETSI technical specifications, MIIT network equipment licensing records, and SEC filings of publicly traded networking equipment suppliers. Bottom-up vendor shipment estimates and top-down infrastructure investment flows were triangulated.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework. CAGRs were derived from installed base replacement cycles and greenfield deployment trajectories across the projection horizon. Co-packaged optical engine adoption curves, F-Gas Regulation compliance deadlines, and 5G backbone densification schedules served as industry-specific forecast inputs.
Foundry capacity constraints, regulatory approval timeline extensions, and hyperscale demand forecast revisions are the dominant revision risks. A model refresh is warranted upon material change in Taiwan semiconductor export control enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Smart Circuit Breaker Market
Switches
Smart Pole-Mounted Switch Market
Switches
North America MV Switchgear Market
Switches
In-Wall Smart Switch Market
Switches
United States Switchgear Market
Switches
Temperature and Pressure Switches Market
Switches
Electric Switch Market
Switches
Mexico Rocker Switch Market
Switches
Oil Level Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Electromechanical Microwave Switch Market
Switches
Global High Voltage Switchgear Market
Switches
South Korea Reed Sensors Switches Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Vibration Level Switch Market
Switches
Europe Low Voltage Switchgear Market