
 Terbium Gallium Garnet Market | 2026-2036
Terbium Gallium Garnet Market Size, Share, and Industry Trends Forecast 2026-2036
Terbium Gallium Garnet Market Insights
REACH is consolidating the cost-of-entry calculus for European-sourced terbium feedstock, forcing crystal growers to document full supply-chain provenance. CASTECH anchors its position through captive Czochralski pulling capacity in Fujian. Northrop Grumman leverages long-term aerospace qualification pathways to sustain defense-grade garnet contracts. ALB Materials Inc specializes in precision doping chemistries for isolator-grade substrates.
Terbium Gallium Garnet is a synthetic ferrimagnetic oxide with composition Tb₃Ga₅O₁₂, exhibiting a Faraday rotation coefficient near 0.2 degrees per millimeter at 1064 nanometers and lattice-matching to gallium gadolinium garnet for epitaxial integration. Industrial purpose centers on non-reciprocal optical isolation in high-power laser chains and telecom amplifiers. Monocrystalline boules command the dominant share of isolator-grade volume, while fiber-form garnet grows fastest in integrated photonic packages where geometry flexibility outweighs rotation efficiency. Laser Systems application demand tracks directly to industrial cutting head deployments and directed-energy test beds.
EMA's extended substance evaluation under REACH and China's MEE rare-earth discharge permits both reshape feedstock availability and pricing predictability for garnet manufacturers. FDA laser product performance standards in the United States further constrain isolator designs for medical device integration. ISO 10110 surface quality specifications govern substrate acceptance across all major defense and telecom procurement channels. Stakeholders must weigh dual-sourcing strategies against the technical lock-in of qualified crystal growth partnerships.
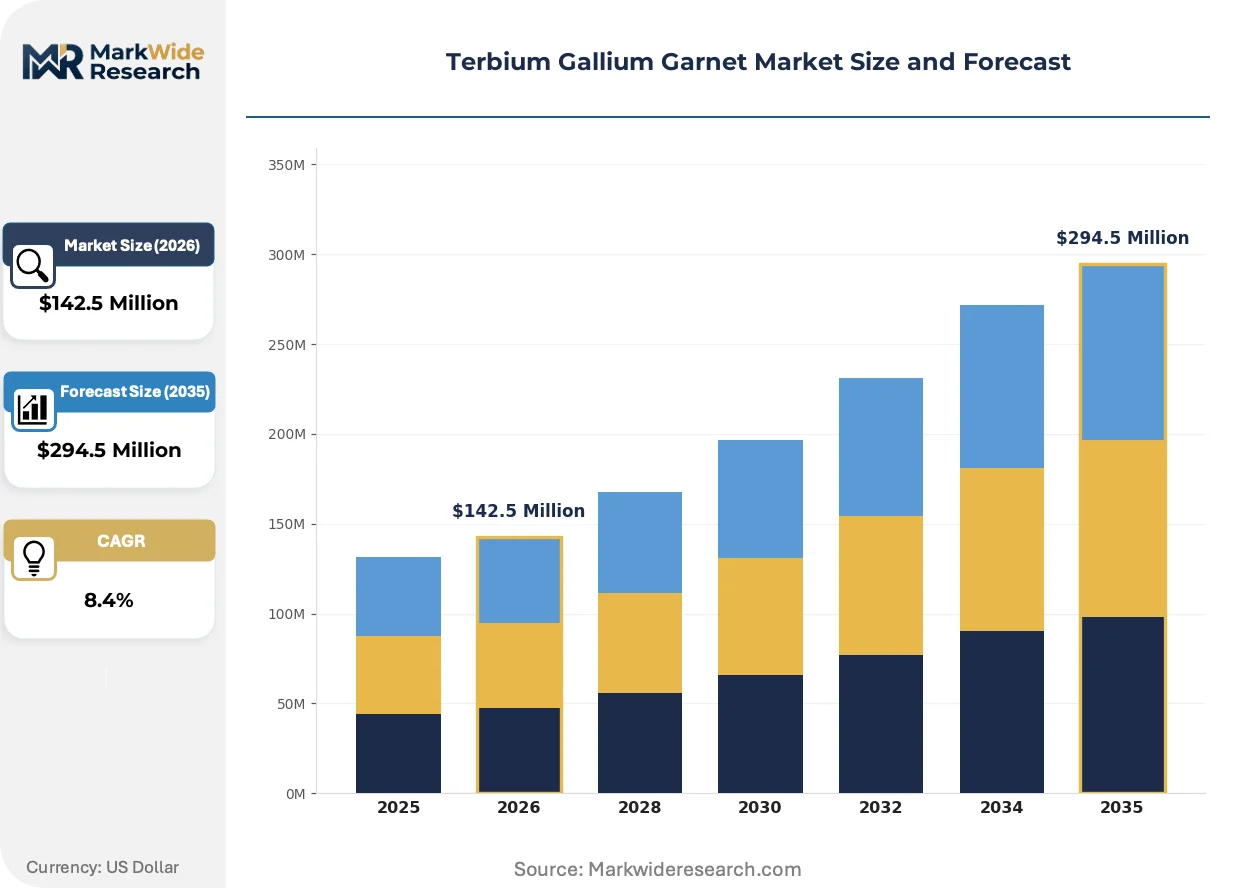
Market Dynamics
Faraday rotation efficiency requirements in high-power laser chains are compressing acceptable defect tolerances for Tb₃Ga₅O₁₂ boules, forcing crystal growers to retrofit Czochralski pullers with real-time diameter control systems.
Growth Catalysts
- Telecom amplifier deployment:Fiber optics manufacturers in East Asia are scaling erbium-doped fiber amplifier production, each requiring isolator-grade garnet substrates for back-reflection suppression.
- REACH substance evaluation:ECHA's extended dossier review for terbium compounds is accelerating documentation investments by European crystal growers, creating qualification barriers that protect incumbent suppliers.
- Directed-energy test beds:Aerospace primes in the United States are qualifying garnet isolators for multi-kilowatt laser weapon prototypes, establishing performance baselines for future procurement.
Market Restraints
- Rare-earth concentrate volatility:China's MEE discharge permit system constrains terbium oxide refining capacity, transmitting price shocks directly to garnet feedstock costs.
- Single-source Czochralski dependency:Boule growth expertise concentrates in Fujian and Shandong provinces, exposing supply continuity to regional environmental enforcement actions.
- Yttrium iron garnet substitution:YIG crystals compete for lower-rotation-efficiency applications above 1500 nanometers, capping garnet pricing power in mid-performance isolator segments.
Strategic Opportunities
- Integrated photonic packaging:Fiber-form garnet deposition onto silicon nitride waveguides enables miniaturized isolators for co-packaged optics in data center transceivers.
- Japan's green transformation bonds:METI financing for energy-efficient manufacturing equipment subsidizes furnace electrification for crystal growth facilities reducing carbon intensity.
- Medical laser certification:FDA 21 CFR 1040.10 performance standards for surgical laser systems create isolator specification lock-in for device OEMs seeking 510(k) clearance.
Industry Challenges
- Crucible degradation management:Iridium crucible lifetimes in Czochralski pulling limit batch economics, requiring predictive maintenance systems to prevent boule loss from platinum-group metal contamination.
- ISO 10110 surface qualification:Substrate vendors face 12-18 month acceptance cycles for defense procurement channels, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terbium Gallium Garnet Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Single-Crystal, Fiber Application: Optical Devices, Laser Systems, Aerospace, Electronics End User: Telecommunications, Defense, Medical, Industrial Technology: Fiber Optics, Laser Technology, Material Synthesis, Coating Techniques |
| Companies Covered | Northrop Grumman, CASTECH, YOFC, Shanghai Daheng Optics and Fine Mechanics, OXIDE, MTI Corporation, ALB Materials Inc, Ulti Photonics, NaKu Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terbium Gallium Garnet Market Trends and Innovations
Process convergence between telecom and defense qualification protocols is compressing development timelines for garnet substrate vendors serving dual-use applications.
Hybrid liquid-phase epitaxy on lattice-matched GGG substrates is unifying dislocation density control with Faraday rotation uniformity. Defense contractors in the United States are qualifying these composite structures for airborne laser systems. The approach is unifying previously separate crystal growth and substrate polishing supply chains into vertically integrated production cells.
China's GB 30982-2014 rare-earth industrial pollutant discharge standards are tightening effluent treatment requirements for terbium separation facilities. Fujian-based processors are retrofitting wastewater recovery systems to maintain operating licenses. Crystal growers in Japan and Germany are accelerating dual-source qualification to reduce dependency on single-origin feedstock.
Specification harmonization between telecom and medical laser OEMs is collapsing isolator design variants. Buyers now demand Tb₃Ga₅O₁₂ substrates certified simultaneously to Telcordia GR-468 and FDA biocompatibility protocols. This consolidation is most visible among North American contract manufacturers serving both communications infrastructure and surgical device markets.
Terbium Gallium Garnet Market Segmentation
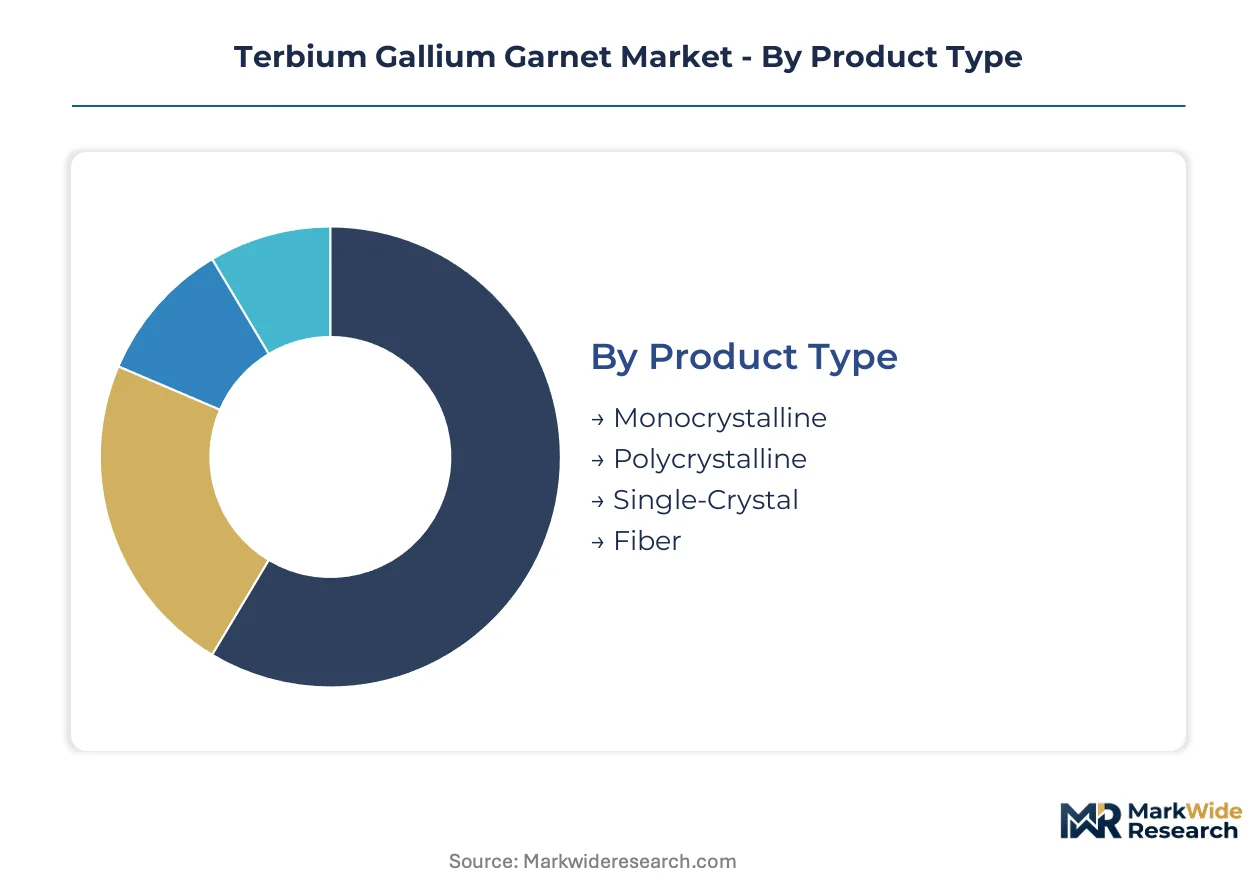
Segmentation in the Terbium Gallium Garnet market reveals how capital intensity and technical qualification requirements stratify competitive positioning across crystal growth formats and end-use channels. Each dimension carries distinct sourcing logic and margin profiles that shape supplier selection.
Product Type:
Capital intensity peaks with Czochralski pulling infrastructure, where iridium crucible costs and furnace electrification dominate upfront investment decisions across crystal formats.
- Monocrystalline:Tb₃Ga₅O₁₂ boules grown by Czochralski pulling deliver the highest Faraday rotation uniformity for isolator-grade substrates. Defense contractors in the United States specify these for multi-kilowatt laser chains where defect tolerance compresses with power scaling.
- Fiber:Deposited garnet onto silicon nitride waveguides sacrifices rotation efficiency for geometry flexibility in co-packaged optics. Data center transceiver manufacturers in Japan are qualifying these for miniaturized isolator integration.
- Polycrystalline:Sintered ceramic forms serve cost-sensitive optical applications with relaxed rotation specifications.
- Single-Crystal:Alternative designation emphasizing lattice-matched epitaxial substrates for hybrid liquid-phase epitaxy on GGG.
Monocrystalline boules absorb the bulk of installed capacity; fiber-form garnet is expanding most quickly.
Application:
Application segmentation tracks directly to qualification protocol divergence between telecom reliability standards and defense performance specifications.
- Laser Systems:Industrial cutting heads and directed-energy test beds drive demand for high-damage-threshold isolators. Aerospace primes in the United States are establishing performance baselines for future procurement through multi-kilowatt prototype qualification.
- Optical Devices:Erbium-doped fiber amplifiers in East Asian telecom infrastructure require back-reflection suppression at scale. Each amplifier node consumes isolator-grade garnet substrates certified to Telcordia GR-468.
- Aerospace:Airborne laser systems impose additional thermal and mechanical shock requirements beyond ground-based specifications.
- Electronics:Emerging integration opportunities in photonic integrated circuits with less mature qualification pathways.
Laser Systems command the deepest qualification investments; Optical Devices generate the highest unit volumes.
End User:
End-user segmentation exposes how procurement concentration in East Asian telecom clusters contrasts with defense purchasing through long-term aerospace qualification pathways.
- Telecommunications:Fiber optics manufacturers in East Asia scale erbium-doped fiber amplifier production with standardized isolator specifications. China's GB standards for rare-earth processing tighten material sourcing documentation requirements.
- Defense:Northrop Grumman and aerospace primes leverage decade-long qualification cycles to lock in garnet supply for directed-energy programs. ISO 10110 surface quality specifications govern substrate acceptance with 12-18 month evaluation timelines.
- Medical:Surgical laser OEMs require FDA 21 CFR 1040.10 compliance for 510(k) clearance, creating specification lock-in.
- Industrial:Cutting equipment manufacturers with less stringent rotation efficiency requirements and higher price elasticity.
Telecommunications concentrates procurement volume; Defense sustains the highest margin tiers.
Technology:
Technology segmentation distinguishes between mature crystal growth methods and emerging deposition techniques that reshape supply chain configuration.
- Fiber Optics:Telecom amplifier deployment scales demand for isolator substrates with standardized Faraday rotation coefficients. CASTECH anchors supply through captive Czochralski capacity in Fujian.
- Laser Technology:High-power chains compress defect tolerances and drive real-time diameter control retrofits in pulling furnaces.
- Material Synthesis:Terbium oxide refining faces constraints from China's MEE discharge permit system, transmitting volatility to feedstock costs.
- Coating Techniques:Anti-reflection and protective layer deposition for finished isolator assemblies.
Fiber Optics dominates current substrate consumption; Material Synthesis faces the tightest regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian's Xiamen Torch Hi-Tech Industrial Zone concentrates captive Czochralski pulling capacity for telecom-grade garnet substrates. China's MEE discharge permit system constrains terbium oxide refining, transmitting feedstock volatility to crystal growers. East Asian crystal growth clusters absorb the dominant share of qualified isolator volume.
United States
Aerospace primes in California and Arizona qualify garnet isolators for directed-energy test beds requiring multi-kilowatt damage thresholds. FDA 21 CFR 1040.10 performance standards govern surgical laser system integration, creating specification lock-in for medical device OEMs. Greater Boston's photonics corridor hosts defense contractors leveraging decade-long qualification cycles for aerospace contracts.
China
Fujian and Shandong provinces concentrate Czochralski pulling expertise for telecom amplifier substrates. GB 30982-2014 rare-earth industrial pollutant discharge standards tighten effluent treatment requirements for terbium separation facilities. Xiamen-based processors retrofit wastewater recovery systems to maintain operating licenses under MEE enforcement.
Japan
Data center transceiver manufacturers in Kanto scale fiber-form garnet deposition onto silicon nitride waveguides for miniaturized isolators. METI green transformation bonds subsidize furnace electrification for crystal growth facilities reducing carbon intensity. Nagoya's precision optics cluster integrates co-packaged optics for telecommunications infrastructure.
Germany
Crystal growers in Bavaria and Baden-Württemberg accelerate dual-source qualification to reduce dependency on single-origin terbium feedstock. ECHA's extended REACH dossier review for terbium compounds forces documentation investments creating qualification barriers. Stuttgart's laser technology hub serves industrial cutting head OEMs with ISO 10110-certified substrates.
Terbium Gallium Garnet Market Competitive Landscape
East Asian producers anchor the volume tier for telecom-grade substrates; European and North American specialists hold defense and medical certification positions. The structure splits between scale-driven crystal growers with captive pulling capacity and precision-doping specialists serving isolator-grade specifications. Three archetypes dominate: integrated boule-to-substrate vendors, feedstock-to-crystal refiners, and application-specific qualification partners. Capacity expansion and dual-source feedstock qualification represent the dominant competitive moves reshaping supply security.
Among China-based crystal growth enterprises, CASTECH and Shanghai Daheng Optics and Fine Mechanics exemplify the integrated boule-to-substrate archetype with captive Czochralski infrastructure. Northrop Grumman occupies a position within the defense qualification tier, leveraging long-term aerospace pathway relationships. These three entities represent the geographic and functional segmentation binding supply security to certification depth.
| Leading Market Players |
|---|
| Northrop Grumman |
| CASTECH |
| YOFC |
| Shanghai Daheng Optics and Fine Mechanics |
| OXIDE |
| MTI Corporation |
| ALB Materials Inc |
| Ulti Photonics |
| NaKu Technology Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Czochralski pulling specialists concentrated in Fujian and Shandong provinces command wage premiums that compress margin spreads between defense-certified and telecom-standard substrate tiers. Labor-cost differentials between these crystal growth clusters and emerging facilities in Vietnam or Eastern Europe translate directly into pricing-tier spreads, with qualified boules carrying 40-60% premiums over unqualified volume.
Pricing Analysis
Lead-time compression commands acute premiums in this market, with defense contractors paying substantial markups for qualified substrates delivered inside standard 12-18 month acceptance cycles. Spot inventory from secondary distributors trades at discounts to contract offtake, though material provenance documentation gaps limit buyer pools. Pricing stratifies across defense-certified, telecom-qualified, and industrial-grade tiers, with ISO 10110 surface quality specifications and FDA 510(k) pathway compliance as primary differentiation drivers. Cost compression in the telecom-standard tier intensifies because CASTECH and Shanghai Daheng anchor volume production with captive Fujian capacity. Industrial cutting equipment OEMs exhibit highest price sensitivity; directed-energy program offices within aerospace primes show least elasticity due to qualification lock-in.
Supply Chain Analysis
Refurbishment flows for iridium crucibles and platinum-group metal recovery from spent pulling assemblies constitute a specialized reverse-logistics channel that sustains batch economics for Czochralski operators. Geographic supply concentrates in China, Japan, and Germany, with terbium oxide refining capacity tethered to MEE discharge permit allocations in Inner Mongolia and Jiangxi. Raw material dependencies center on terbium oxide concentrate, iridium crucible fabrication, and gallium metal sourcing. Single-source vulnerability runs through Fujian-based Czochralski expertise, where environmental enforcement actions could disrupt qualified boule availability without notice. Distribution runs through long-term aerospace qualification pathways for defense contractors and direct mill relationships for East Asian telecom amplifier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
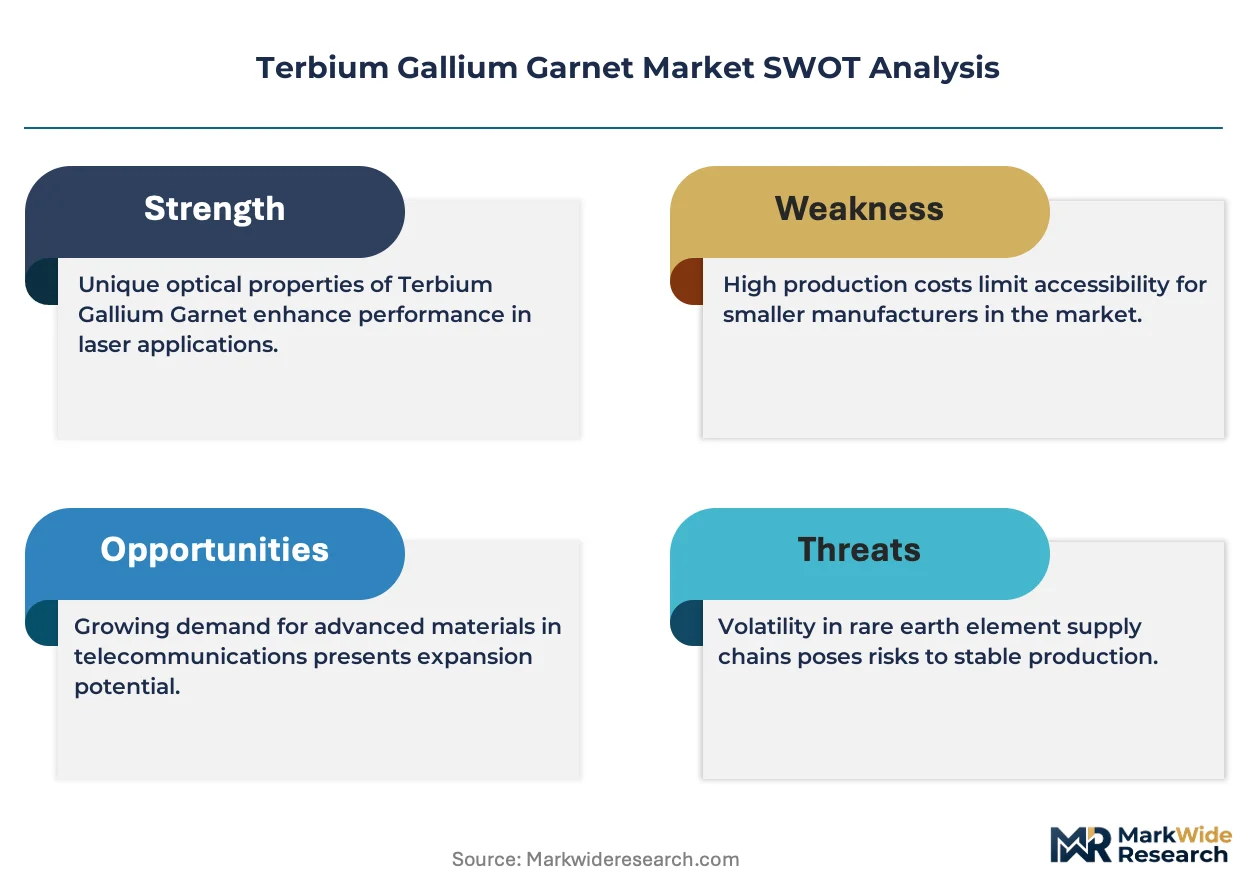
This market operates as a supply-constrained environment where Czochralski pulling capacity qualified to defense specifications props pricing power for incumbent substrate vendors. The iridium crucible bottleneck and 12-18 month qualification cycles create structural barriers that protect margins for certified suppliers.
For Market Incumbents: Hedge against Yttrium Iron Garnet substitution in wavelengths above 1500 nanometers by deepening captive terbium oxide refining relationships and accelerating dual-source feedstock qualification in Vietnam or Eastern Europe. Prioritize furnace electrification investments to capture Japan's METI green transformation bond subsidies and preempt carbon border adjustments. Certification depth remains the critical defensive lever against emerging Chinese volume players. For New Entrants and Emerging Players: Defense contractors in the United States seeking second-source qualification for directed-energy programs represent the most penetrable entry point, given decade-long incumbent relationships that have ossified supply security assumptions. Medical laser OEMs requiring simultaneous Telcordia GR-468 and FDA biocompatibility certification offer white-space opportunity where specification consolidation has outpaced supplier base adaptation. Pursue partnership structures with established crystal growth houses to bypass iridium crucible capital barriers. For Investors and Strategic Acquirers: The window for entry favors precision-doping specialists with isolator-grade substrate expertise rather than volume crystal growers facing margin compression. Long-term viability across the projection horizon rests on control over qualified Czochralski capacity and defense certification relationships that compound competitive moats. Monitor MEE discharge permit issuance rates and terbium oxide spot price volatility as early signals of feedstock availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Feedstock Qualification | Reduces dependency on single-origin terbium oxide from MEE-regulated Chinese refiners. |
| Furnace Electrification Investment | Captures METI green transformation bond financing for carbon-intensity reduction in crystal growth. |
| Defense Certification Pathway Expansion | Locks in multi-kilowatt laser weapon prototype relationships with aerospace primes. |
| Integrated Photonic Packaging Partnership | Enables fiber-form garnet deposition for data center transceiver miniaturization. |
| Crucible Refurbishment Network Buildout | Extends iridium crucible lifetimes through predictive maintenance and platinum-group metal recovery. |
Research Methodology
Multi-period observation of Czochralski furnace utilization rates, terbium oxide spot price movements, and defense procurement announcement flows anchored the trend analysis, supplemented by interviews with crystal growth engineers, telecom amplifier procurement leads, aerospace qualification officers, and rare-earth separation facility managers. Secondary validation drew from ECHA REACH dossier submissions, China's MEE discharge permit disclosures, FDA 510(k) clearance databases, and SEC filings from defense contractors. Bottom-up substrate demand modeling triangulated against top-down rare-earth oxide consumption forecasts.
Segment-weighting applied differential growth assumptions across monocrystalline boule, fiber-form, and polycrystalline ceramic formats, with further disaggregation by laser systems, optical devices, aerospace, and medical end-use channels. Technology dimensions incorporated Czochralski pulling, liquid-phase epitaxy, and fiber deposition methods. CAGRs derived from regression analysis against historical capacity expansion patterns and qualification cycle durations. Forecast inputs included directed-energy program budget trajectories and erbium-doped fiber amplifier deployment schedules from East Asian telecom infrastructure plans.
Caveats apply where MEE enforcement intensity, REACH substance evaluation timelines, or defense procurement prioritization shifts could materially shift the outlook. Forecasts embed assumptions regarding iridium supply continuity and qualification pathway stability that warrant ongoing validation. Practitioners should monitor terbium oxide refinery operating rates and aerospace prime second-source qualification announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Modulators Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Global Optical Measurement Market
Optical Components
North America Photonic Sensors Market
Optical Components
Europe Optical Film Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Optical Position Sensors Market
Optical Components
Global Adaptive Optics Market
Optical Components
North America Laser Diode Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Diode Laser Module Market
Optical Components
Global Optical Network Hardware Market
Optical Components
100G Optical Transceivers Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Cross Connect Market
Optical Components
Silicon Photonics Wafer Market