
 Asia Pacific Optical Sensors Market | 2026-2036
Asia Pacific Optical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Optical Sensors Market Outlook
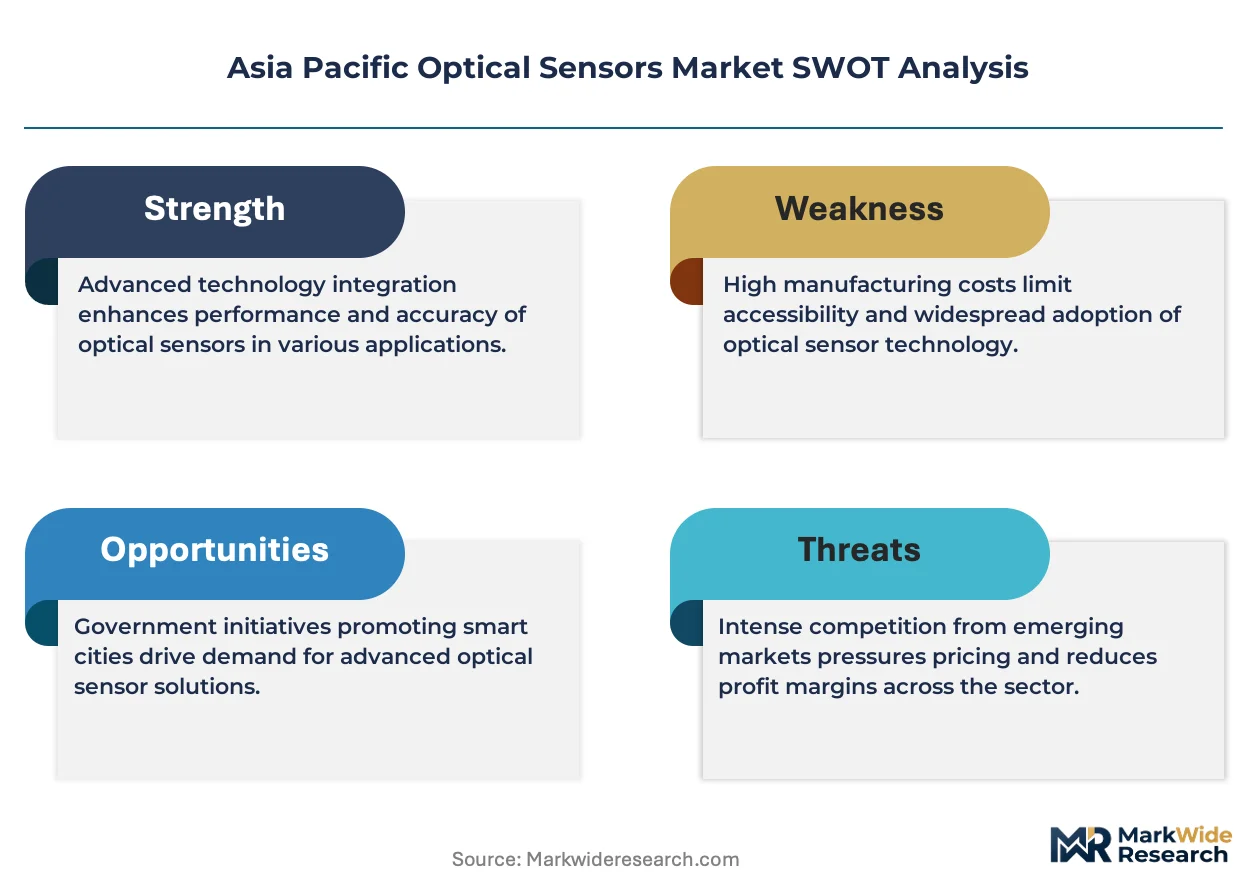
Software-defined calibration and remote diagnostics is consolidating into standard sensor offerings across the Asia Pacific region. Keyence Corporation leverages its direct sales force to sustain premium positioning in precision measurement applications. Omron Corporation anchors its competitive stance through deep integration with programmable logic controller ecosystems. STMicroelectronics NV competes on semiconductor-level cost structures for high-volume image sensor deployment.
Asia Pacific optical sensors detect, measure, and convert light signals into electrical outputs using photodiodes, charge-coupled devices, or complementary metal-oxide-semiconductor arrays operating across ultraviolet to infrared wavelengths, primarily serving industrial process control, consumer device imaging, and autonomous system navigation. Photoelectric sensors dominate factory floor installations where reliability under dust and vibration determines replacement cycles, while image sensors capture the fastest expansion as smartphone manufacturers and automotive camera module suppliers in the region scale multi-lens architectures. Fiber optic sensors occupy specialized niches in harsh-environment monitoring where electromagnetic immunity justifies unit cost premiums.
Japan's METI enforces JIS standards for industrial sensor interoperability, while China's MIIT mandates GB compliance for networked sensing equipment under smart manufacturing frameworks, and South Korea's MFDS oversees medical-grade optical sensor certifications that gate healthcare market entry. Regulatory divergence across these jurisdictions forces manufacturers to maintain multiple certification streams. Stakeholders must monitor evolving electromagnetic compatibility requirements and cross-border data transmission rules that increasingly govern sensor network deployments.
Market Dynamics
China's MIIT smart manufacturing mandates are forcing sensor suppliers to recertify entire product lines under GB standards, compressing product development cycles while opening state procurement channels for compliant vendors.
Growth Catalysts
- China MIIT Smart Manufacturing Framework:Mandatory GB compliance for networked sensing equipment in Yangtze River Delta electronics corridors accelerates specification upgrades across fiber optic and photoelectric product lines.
- Automotive camera module scaling:Multi-lens architectures in electric vehicle platforms across Japan and South Korea drive image sensor volume expansion through tier-one module suppliers.
- South Korea K-IoT certification:Wireless optical sensor integration requirements create pull for photoelectric systems with embedded connectivity in smart factory deployments.
Market Restraints
- Silicon photonics foundry concentration:Advanced CMOS image sensor fabrication depends on Taiwan and South Korea foundry capacity, exposing supply chains to geopolitical disruption and allocation constraints.
- Indium gallium arsenide cost volatility:Near-infrared sensor production faces input price swings from rare earth processing bottlenecks in Chinese refining operations.
- Regulatory divergence friction:Separate JIS, GB, and K-IoT certification streams force manufacturers to maintain three parallel testing workflows, inflating compliance overhead.
Strategic Opportunities
- Vietnam electronics manufacturing expansion:Relocation of smartphone and component assembly from China creates greenfield demand for photoelectric quality control systems in emerging industrial zones.
- Medical-grade optical sensing:South Korea MFDS certification pathways for pulse oximetry and endoscopic imaging open premium pricing tiers for biocompatible fiber optic probes.
- Edge AI convergence:On-sensor inference capabilities combining CMOS arrays with neural processing units enable predictive maintenance applications without cloud dependency.
Industry Challenges
- Photonics packaging skill scarcity:Precision alignment of optical components to semiconductor dies requires specialized technicians concentrated in Japanese and Taiwanese supplier bases.
- Legacy PLC integration complexity:Smart factory retrofits demand protocol translation layers between new optical sensors and existing Omron or Mitsubishi controller ecosystems.
- Cross-border data transmission rules:China's cybersecurity law and South Korea's data localization requirements complicate remote diagnostics for cloud-connected sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Optical Sensors Market |
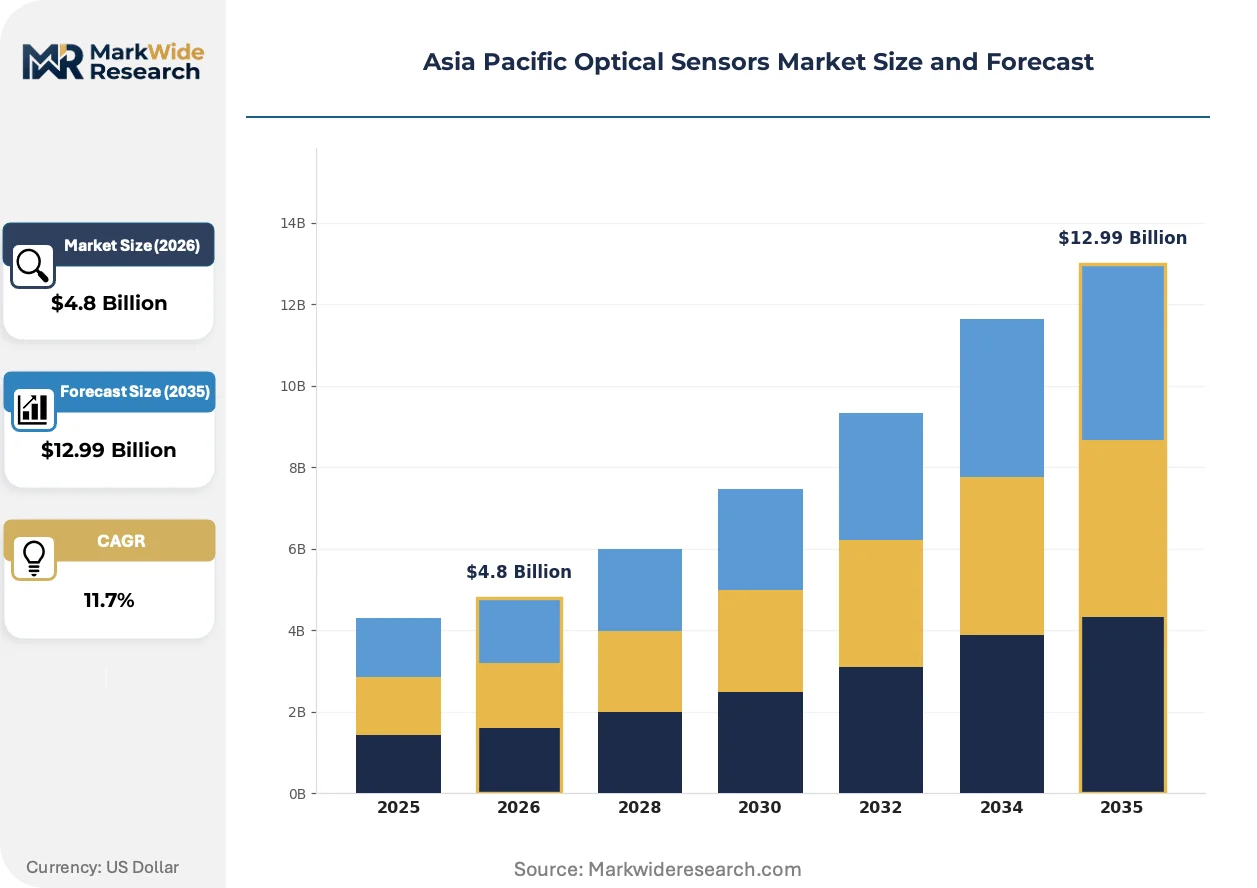
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoelectric Sensors, Image Sensors, Fiber Optic Sensors, Proximity Sensors End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: Analog, Digital, Hybrid, MEMS Application: Smart Homes, Robotics, Security Systems, Environmental Monitoring |
| Companies Covered | Honeywell International Inc., Rockwell Automation Inc., Omron Corporation, Keyence Corporation, STMicroelectronics NV, SICK AG, Panasonic Corporation, Robert Bosch GmbH, Autonics Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Optical Sensors Market Strategic Shifts
Software-defined functionality is redefining hardware value capture across the Asia Pacific optical sensor value chain, compressing traditional equipment margins while opening recurring revenue streams through firmware subscriptions and predictive analytics.
Spectral sensing arrays is converging with machine vision platforms to enable material composition analysis during production line inspection. Automotive battery manufacturers in Japan's Nagoya industrial cluster are deploying these systems to detect electrolyte contamination in real time. The technology is converging with edge computing architectures, displacing laboratory-based quality control and compressing inspection cycle times from hours to milliseconds.
Japan's METI JIS standards revision for industrial sensor interoperability mandates open communication protocols across vendor ecosystems. The regulation forces proprietary system vendors to expose data interfaces, eroding switching costs that previously locked in factory automation buyers. Automotive and electronics assembly lines in Toyota City and Osaka prefecture face the steepest compliance timelines, driving rapid procurement of certified replacement sensors.
Sensor-as-a-service contracting is displacing capital expenditure models among mid-sized Chinese electronics manufacturers. Third-party optical inspection providers in Shenzhen and Dongguan now lease photoelectric systems with per-unit pricing tied to defect detection outcomes. This restructuring concentrates vendor risk while transferring maintenance and calibration burdens to equipment financiers.
Asia Pacific Optical Sensors Market Segmentation
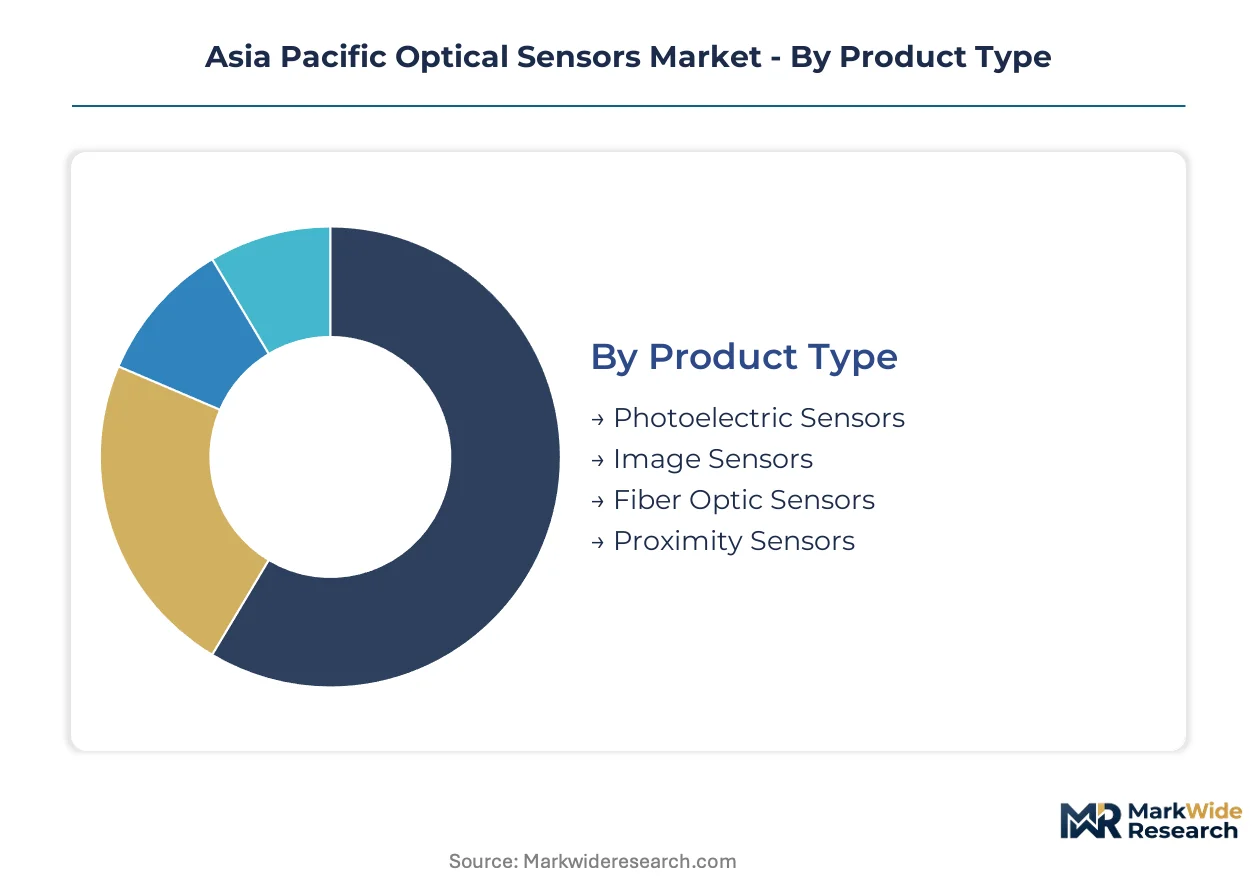
Segmentation across the Asia Pacific optical sensors market reveals how technical specifications, end-use requirements, and regulatory compliance reshape procurement patterns. Buyers prioritize electromagnetic immunity in factory floors, resolution density in consumer imaging, and biocompatibility in medical applications.
Product Type:
Technical differentiation across sensing modalities determines unit economics and replacement cycles in Asia Pacific deployments.
- Photoelectric Sensors:These devices detect object presence through emitted light beams and receiver interruption, operating reliably under dust and vibration conditions. Factory automation buyers in China's Yangtze River Delta electronics corridors specify these for conveyor quality control, where MIIT GB compliance for networked equipment accelerates specification upgrades.
- Image Sensors:CMOS and CCD arrays convert optical signals into digital outputs across ultraviolet to infrared wavelengths. Automotive camera module suppliers in Japan and South Korea scale multi-lens architectures for electric vehicle platforms, driving volume expansion through tier-one integrators.
- Fiber Optic Sensors:Glass or plastic fiber cables transmit light signals immune to electromagnetic interference, serving harsh-environment monitoring in steel mills and chemical plants.
- Proximity Sensors:Non-contact detection systems using infrared or laser triangulation measure distance without physical contact, deployed in robotic arms across South Korean smart factories.
Photoelectric sensors lead on scale; image sensors lead on momentum.
End User:
Cost tier segmentation separates premium-certified medical applications from high-volume consumer electronics procurement.
- Consumer Electronics:Smartphone manufacturers in Shenzhen and Dongguan specify compact CMOS arrays for multi-lens camera modules. South Korean display panel makers integrate ambient light sensors for automatic brightness adjustment.
- Automotive:Tier-one suppliers in Toyota City and Nagoya industrial clusters deploy LiDAR and camera fusion systems for advanced driver assistance. Japan's METI JIS interoperability mandates force open protocol adoption across vendor ecosystems.
- Industrial Automation:Smart factory retrofits in China's electronics manufacturing corridor demand photoelectric systems with embedded connectivity, driven by MIIT mandatory GB compliance for networked sensing equipment.
- Healthcare:South Korea's MFDS certification gates market entry for pulse oximetry and endoscopic imaging probes. Biocompatible fiber optic sensors command premium pricing in medical-grade applications.
Consumer electronics dominates volume; healthcare commands margin premiums.
Technology:
Signal processing architecture determines integration complexity and firmware upgrade pathways across Asia Pacific installations.
- Analog:Continuous voltage output sensors offer simplicity in legacy programmable logic controller environments. Japanese automotive suppliers maintain these for backward compatibility with existing Mitsubishi and Omron controller ecosystems.
- Digital:Discrete output systems with embedded microcontrollers enable software-defined calibration and remote diagnostics. China's MIIT smart manufacturing framework accelerates digital sensor procurement in state-backed industrial zones.
- Hybrid:Combined analog-digital architectures bridge legacy infrastructure and modern connectivity requirements in retrofit applications.
- MEMS:Microelectromechanical systems integrate optical components with semiconductor fabrication, enabling miniaturization for consumer device integration.
Digital technology is climbing the fastest; analog maintains installed base dominance.
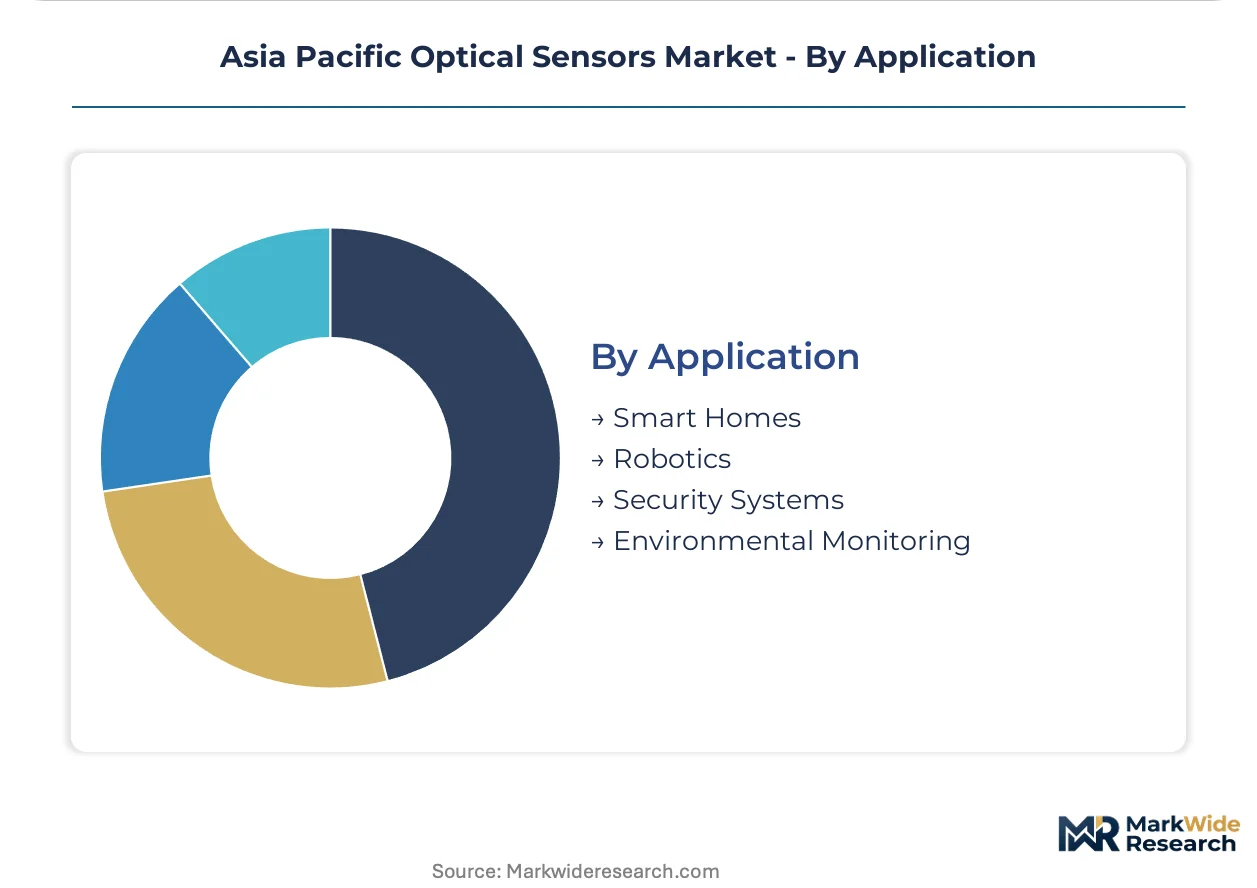
Application:
Deployment environment dictates packaging ruggedness, power consumption, and connectivity specifications across the region.
- Smart Homes:Occupancy detection and ambient light sensing systems integrate with building automation networks. South Korea's K-IoT certification requirements pull wireless photoelectric systems into residential construction.
- Robotics:Precision distance measurement and object recognition enable collaborative robot navigation. Japanese automotive assembly lines in Osaka prefecture deploy these for parts positioning under tight cycle time constraints.
- Security Systems:Infrared motion detection and perimeter monitoring applications serve commercial and critical infrastructure protection.
- Environmental Monitoring:Spectral sensing arrays detect air and water quality parameters. Battery manufacturers in Nagoya deploy real-time electrolyte contamination detection, compressing inspection cycles from laboratory hours to milliseconds.
Robotics applications expand most quickly; smart homes represent the largest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of industrial optical sensors, while Japan maintains the highest concentration of precision component fabricators. South Korea bridges both ecosystems through its automotive and semiconductor supply chains. Australia and Vietnam represent emerging demand poles with diverging regulatory frameworks.
China
MIIT smart manufacturing mandates drive GB-compliant sensor procurement across the Yangtze River Delta electronics corridor. The country's dual carbon goals accelerate fiber optic deployment in steel and chemical plants seeking electromagnetic immunity. Shenzhen and Dongguan manufacturers scale multi-lens CMOS integration for smartphone camera modules.
Japan
METI JIS interoperability standards force open protocol adoption among factory automation vendors. Nagoya automotive clusters deploy LiDAR-camera fusion systems for electric vehicle platforms. Osaka prefecture robotics lines integrate precision proximity sensors under tight cycle-time constraints.
South Korea
K-IoT certification requirements pull wireless photoelectric systems into smart factory retrofits. MFDS medical-grade pathways open premium tiers for biocompatible fiber optic probes in Seoul Capital Area healthcare manufacturing. Busan-Ulsan industrial zones anchor image sensor packaging for automotive tier-one suppliers.
Vietnam
Electronics assembly relocation from China generates greenfield demand for photoelectric quality control in northern industrial zones. The country's national standards body accelerates technical regulation alignment with ASEAN frameworks. Ho Chi Minh City and Bac Ninh provinces concentrate smartphone component testing facilities.
Australia
Mining automation drives fiber optic sensor deployment in Western Australia iron ore operations. The national communications regulator oversees spectrum allocation for wireless sensor networks in remote extraction sites. Queensland coal basins test spectral sensing arrays for real-time environmental monitoring.
Asia Pacific Optical Sensors Market Competitive Environment
Top-tier vendors anchor premium precision measurement, while mid-tier suppliers compete on PLC ecosystem integration and semiconductor cost structures. The market structures around three strategic archetypes: direct-sales precision specialists, programmable controller-integrated automation houses, and foundry-dependent semiconductor scale players. Competitive moves concentrate on certification streamlining for multi-jurisdiction compliance and edge AI firmware differentiation.
Within the precision-tier vector, Keyence Corporation and Omron Corporation exemplify divergent go-to-market architectures. STMicroelectronics NV occupies a position at the semiconductor-integration end of the value chain. These three entities represent the dominant competitive poles: direct industrial sales force deployment, deep controller ecosystem embedding, and high-volume CMOS fabrication cost leverage.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Omron Corporation |
| Keyence Corporation |
| STMicroelectronics NV |
| SICK AG |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Autonics Corporation |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive camera module suppliers across Japan and South Korea anchor pricing power through multi-year offtake contracts, compressing margin capture for upstream CMOS foundries while securing volume commitments for next-generation LiDAR fusion systems.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for advanced image sensors as foundry competition intensifies. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates premium JIS-compliant products from standard MIIT-certified and economy-tier alternatives. Cost compression in consumer CMOS segments is intensifying because smartphone OEMs in Shenzhen consolidate procurement around fewer suppliers. Automotive tier-ones exhibit lowest price sensitivity due to safety-critical reliability requirements, while Chinese electronics contract manufacturers demonstrate highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
China's domestic-content mandates under smart manufacturing frameworks are reshaping sourcing patterns for photoelectric assembly operations in the Yangtze River Delta. Advanced CMOS fabrication draws from Taiwan, South Korea, and Japan, while indium gallium arsenide refining rests on Chinese rare earth processing. Single-source vulnerability concentrates in Taiwan foundry capacity for automotive-grade image sensors. Distribution runs through tier-one module integrators in Toyota City and Nagoya who bundle sensor hardware with calibration software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because industrial automation retrofit cycles across Asia Pacific generate recurring replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Lock in certification pipeline advantages by accelerating parallel JIS, GB, and K-IoT testing workflows before regulatory divergence widens compliance gaps. Deepen backward integration into photonics packaging capabilities concentrated in Japanese and Taiwanese supplier bases to offset technician scarcity. Defend against edge AI firmware disruptors by embedding predictive maintenance algorithms directly into sensor silicon. For New Entrants and Emerging Players: Begin with Vietnam's greenfield electronics manufacturing zones where photoelectric quality control systems lack established vendor relationships. Medical-grade fiber optic probes for South Korean MFDS certification offer the most penetrable premium tier given biocompatibility expertise gaps among industrial sensor specialists. Pursue sensor-as-a-service leasing models with Shenzhen contract manufacturers to bypass capital expenditure barriers. For Investors and Strategic Acquirers: Industrial automation conglomerates seeking PLC ecosystem expansion represent the most active acquirer category in this space. Five-to-ten-year viability hinges on edge AI convergence capabilities combining CMOS arrays with neural processing units. Acquisition targets should demonstrate firmware-defined differentiation and multi-jurisdiction certification streams. Watch for MFDS medical-grade approval accelerations as inflection signals for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Streamlining | Parallel JIS, GB, and K-IoT workflows reduce compliance overhead for factory automation vendors. |
| Edge AI Firmware Development | On-sensor inference capabilities enable predictive maintenance without cloud dependency for Japanese automotive clusters. |
| Photonics Packaging Capability Acquisition | Precision alignment expertise concentrated in Taiwan addresses technician scarcity constraining regional supply. |
| Sensor-as-a-Service Platform Launch | Outcome-based leasing models transfer calibration burdens to equipment financiers in Chinese electronics corridors. |
| Medical-Grade Fiber Optic Probe Expansion | MFDS certification pathways unlock premium pricing tiers for Seoul Capital Area healthcare manufacturing. |
Study Parameters
Multiple input streams — factory automation procurement directors, tier-one automotive camera module suppliers, semiconductor foundry planning officers, and MIIT certification consultants — were reconciled against secondary validation from customs trade databases, METI JIS standard filings, and MFDS medical device registration records. Bottom-up sensor shipment tallies by application and top-down industrial automation capex flows were triangulated to establish market sizing boundaries.
Data-stream reconciliation across product type, end-use vertical, technology architecture, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporated MIIT smart manufacturing mandate implementation timelines and automotive camera module content-per-vehicle trajectories.
Caveats apply where geopolitical disruption of Taiwan foundry capacity or indium gallium arsenide supply bottlenecks could materially shift the outlook. Forecasts reflect documented assumptions about regulatory compliance timelines and edge AI adoption curves in factory automation environments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Photosensitive Glass Market
Optical Components
North America Optical Film Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Optical Fiber Array Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Europe Optical Imaging Market
Optical Components
ROADM WSS Component Market
Optical Components
Pancake Optical Module Market
Optical Components
Machine Vision Light Source Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Optical Dome Market
Optical Components
Italy Lithium Niobate Modulator Market