
 Optic Nerve Glioma Market | 2026-2036
Optic Nerve Glioma Market Size, Share, and Industry Trends Forecast 2026-2036
Optic Nerve Glioma Market Outlook
Maintenance and monitoring service contracts bundled with diagnostic imaging platforms is repositioning how hospitals procure optic nerve glioma care pathways. Merck & Co. leverages its oncology infrastructure to sustain clinical trial recruitment across North American pediatric networks. Novartis International AG anchors its position through specialized neuro-oncology drug development programs. Roche differentiates via integrated diagnostic-therapeutic platforms spanning biomarker identification through treatment monitoring.
Optic nerve glioma denotes a low-grade pilocytic astrocytoma arising from the optic nerve sheath, typically presenting in children with neurofibromatosis type 1 and requiring multimodal management to preserve visual function. These tumors exhibit biphasic growth patterns with spontaneous stabilization phases, complicating treatment timing decisions and necessitating longitudinal ophthalmologic and radiographic surveillance. Targeted therapy segments are capturing expanding margin pools as MEK inhibitors reshape first-line management for unresectable cases, while chemotherapy retains volume leadership in resource-constrained settings. Pediatric patients represent the structurally dominant end-user category given the disease's age-stratified epidemiology, though adult patient protocols are gaining protocol development attention.
FDA orphan drug designations and EMA pediatric investigation plans create parallel regulatory pathways that accelerate development timelines for optic nerve glioma therapeutics. The country's national pharmaceutical regulator in Japan imposes distinct local clinical data requirements that shape Asia-Pacific market entry sequencing for multinational sponsors. WHO essential medicines criteria and national cancer control program inclusion decisions determine reimbursement access in emerging health systems. Stakeholders must monitor biomarker-driven trial enrichment strategies and evolving visual outcome endpoints that will redefine competitive positioning in this indication.
Market Dynamics
MEK inhibitor adoption is compressing chemotherapy's historical dominance in first-line unresectable cases, forcing protocol redesign across pediatric neuro-oncology networks and reallocating clinical trial investment toward molecularly guided endpoints.
Growth Catalysts
- FDA Orphan Drug Designation:The designation accelerates development timelines through tax credits and seven-year market exclusivity, incentivizing sponsors to pursue pediatric indications despite small addressable populations.
- Neurofibromatosis Type 1 Screening:Expanded genetic screening programs in the United States and Germany are identifying optic nerve glioma cases earlier, extending the treatment window and surveillance revenue pool.
- Biomarker-Guided Enrichment:BRAF and NF1 mutation profiling is absorbing into standard diagnostic workups, enabling precision trial enrollment and expanding addressable populations for targeted agents.
Market Restraints
- Specialized Neuroradiologist Scarcity:Interpretation of optic pathway imaging requires fellowship-trained specialists concentrated in academic medical centers, creating diagnostic bottlenecks in community settings.
- EMA Pediatric Investigation Plan Compliance Costs:Mandatory pediatric study requirements impose parallel development burdens that deter smaller sponsors from entering the indication.
- Visual Function Assessment Variability:Lack of standardized endpoints across international cooperative groups complicates cross-trial comparison and regulatory review timelines.
Strategic Opportunities
- Japan PMDA Local Data Requirements:The mandate for domestic clinical evidence creates first-mover advantages for sponsors establishing Japanese pediatric neuro-oncology trial infrastructure early.
- Real-World Evidence Integration:Natural history registries and patient-reported visual outcome platforms are converging with regulatory science, enabling label expansion through post-marketing study designs.
- Maintenance Service Unbundling:Diagnostic imaging vendors are separating hardware procurement from longitudinal monitoring contracts, creating recurring revenue streams independent of capital equipment cycles.
Industry Challenges
- Neuro-Ophthalmology Fellowship Pipeline:The subspecialty training pathway produces fewer than fifty new specialists annually in the United States, constraining multidisciplinary clinic expansion.
- Longitudinal Visual Outcome Data Integration:Electronic health record fragmentation across ophthalmology, neurology, and oncology departments impedes unified patient tracking and protocol adherence monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optic Nerve Glioma Market |
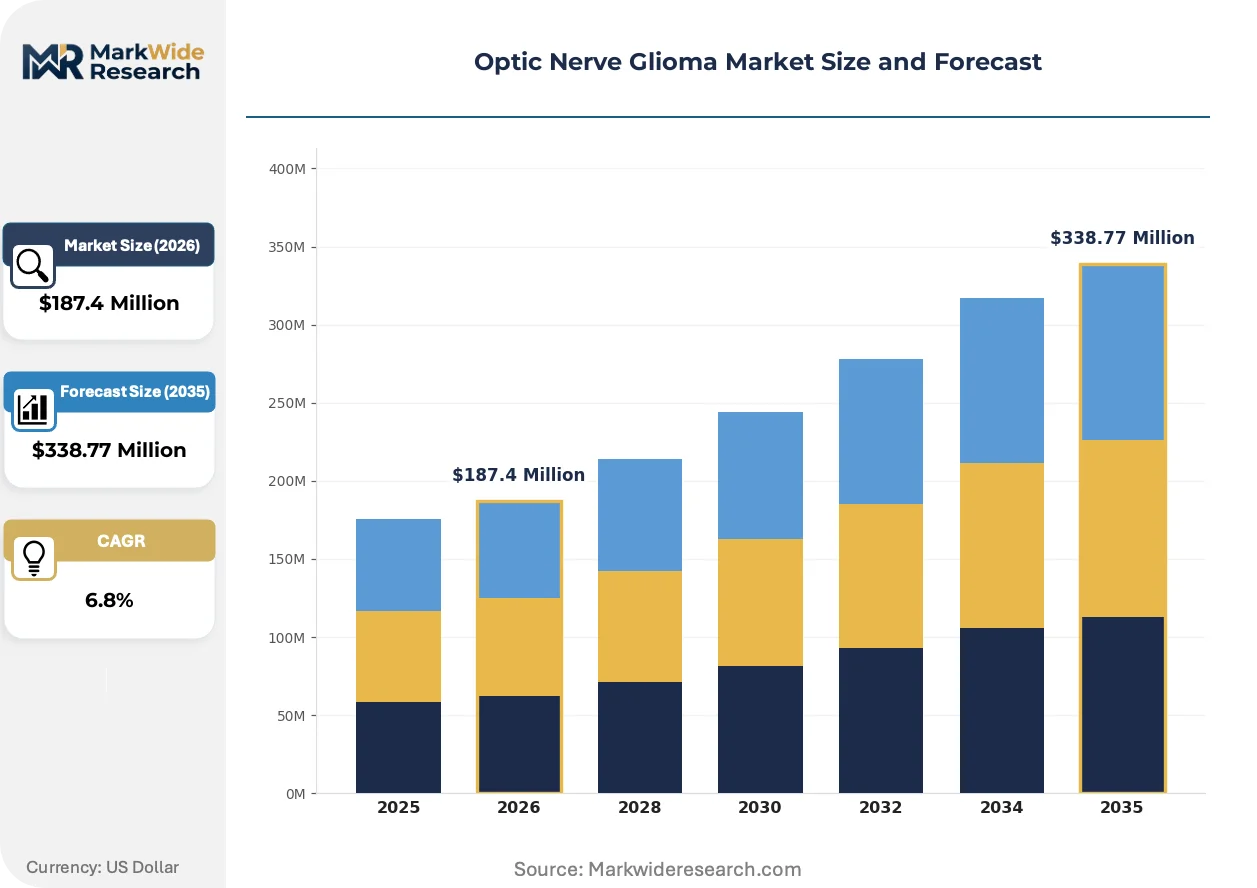
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
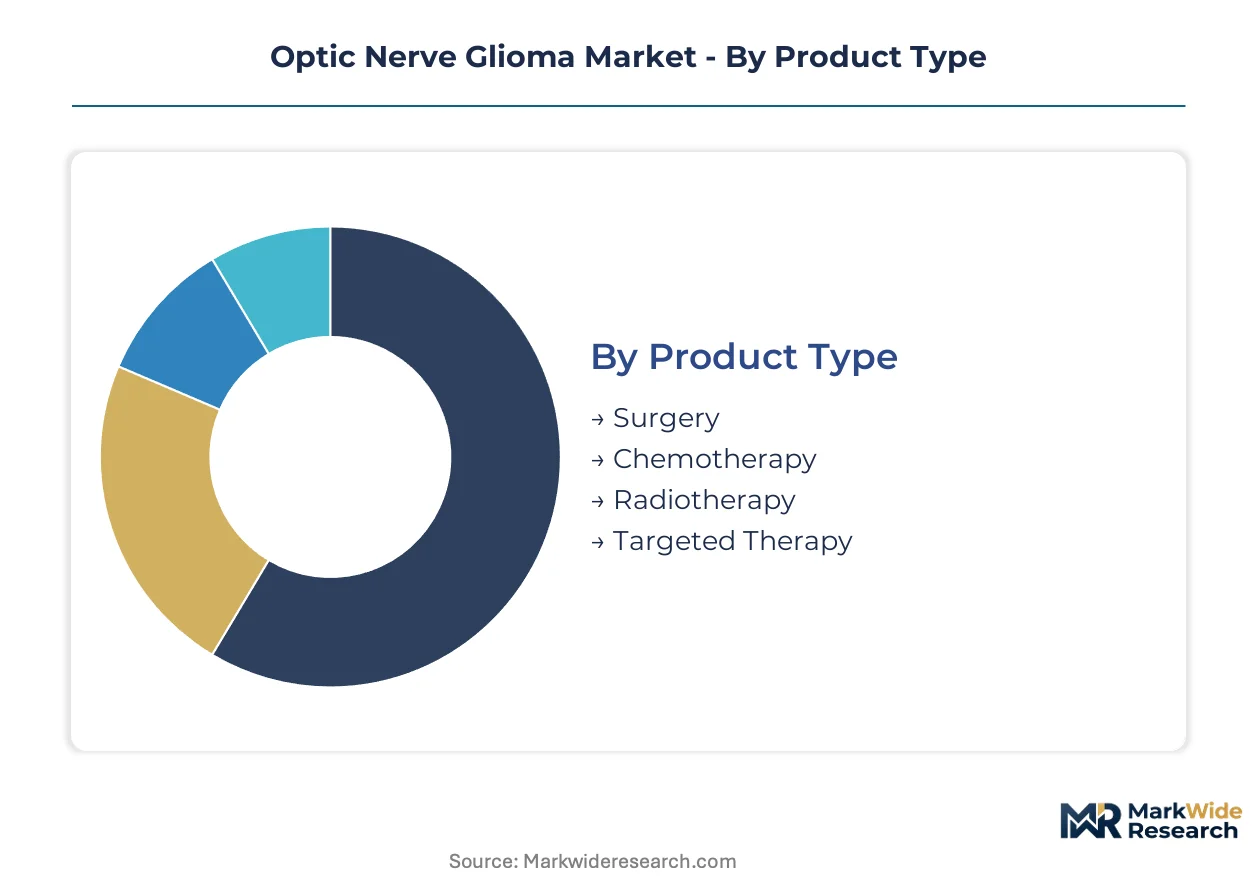
| Segmentation | Product Type: Surgery, Chemotherapy, Radiotherapy, Targeted Therapy End User: Pediatric Patients, Adult Patients, Hospitals, Clinics Delivery Mode: Intravenous, Oral, Topical, Subcutaneous Application: Cancer Treatment, Symptom Management, Clinical Trials, Diagnostic Imaging |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, Novartis International AG, Eli Lilly and Company, Amgen, Pfizer Inc, Roche, Teva Pharmaceutical Industries Ltd, Thermo Fisher Scientific Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optic Nerve Glioma Market Strategic Shifts
Liquid biopsy platforms and radiomic analysis are absorbing into surveillance protocols, displacing repetitive tissue sampling and enabling dynamic treatment response assessment without invasive procedures.
MEK inhibitor therapy is absorbing the first-line management role for progressive unresectable optic nerve glioma, with selumetinib and trametinib protocols now dominating pediatric neuro-oncology trial portfolios. Academic medical centers in the United States and Germany are adopting these agents ahead of formal label expansion, compressing the historical chemotherapy window and forcing infrastructure reconfiguration toward targeted therapy monitoring. The shift is absorbing capital from infusion center expansion into molecular diagnostic platform deployment.
EMA pediatric investigation plans and FDA orphan drug incentives are operating in parallel, creating dual-track regulatory strategies that accelerate timeline-sensitive development programs. Sponsors are structuring European submissions to leverage the EMA's pediatric committee scientific advice, while simultaneously positioning US applications for priority review vouchers. The regulatory convergence is most pronounced among mid-cap oncology specialists with existing neuro-oncology infrastructure.
Hospital procurement departments are unbundling diagnostic imaging hardware from longitudinal service contracts, separating capital expenditure approval cycles from recurring monitoring revenue streams. Pediatric oncology centers in Japan and Germany are piloting subscription-based MRI surveillance programs that align vendor incentives with patient retention. The model is displacing traditional equipment lease structures in high-volume referral networks where longitudinal follow-up exceeds ten years.
Optic Nerve Glioma Market Segmentation
Optic nerve glioma treatment pathways fragment across intervention modalities, patient demographics, and care delivery settings. Each segment carries distinct reimbursement profiles, regulatory requirements, and infrastructure dependencies that shape competitive positioning.
Product Type:
Surgery commands standalone procedural workflows while systemic therapies embed within longitudinal care protocols.
- Surgery:Resection of anterior optic nerve lesions preserves visual function when anatomically feasible. Academic medical centers in the United States and Germany concentrate expertise for nerve-sparing approaches, though tumor location often precludes complete excision.
- Targeted Therapy:MEK inhibitors deliver molecularly precise intervention for unresectable progressive disease. Pediatric neuro-oncology networks in Japan are prioritizing selumetinib and trametinib protocols, reallocating infusion center capacity toward oral drug monitoring infrastructure.
- Chemotherapy:Carboplatin-vincristine regimens retain volume leadership in resource-constrained health systems lacking molecular diagnostic platforms.
- Radiotherapy:Fractionated proton beam approaches spare adjacent neural tissue but require capital-intensive cyclotron facilities concentrated in major metropolitan clusters.
Chemotherapy leads volumes today; targeted therapy is gaining share fastest.
End User:
Patient age stratification drives protocol selection while care setting determines reimbursement mechanics and capital intensity.
- Pediatric Patients:Children under 18 constitute the structurally dominant population given NF1-associated disease epidemiology. Specialized pediatric oncology centers in the United States manage complex multimodal cases through multidisciplinary neuro-ophthalmology clinics.
- Hospitals:Tertiary referral institutions anchor comprehensive care pathways integrating surgery, systemic therapy, and surveillance. Japanese university hospitals are expanding dedicated optic pathway tumor units to capture longitudinal follow-up revenue.
- Adult Patients:Sporadic late-onset cases require adapted dosing protocols and distinct toxicity monitoring frameworks.
- Clinics:Community-based settings handle stable surveillance patients and chemotherapy administration, referring progression events to academic centers.
Pediatric patients absorb the majority of specialized care capacity; hospital-based delivery captures the premium reimbursement tier.
Delivery Mode:
Route of administration shapes patient compliance, monitoring burden, and site-of-care economics across treatment phases.
- Oral:MEK inhibitor tablets enable home-based administration with periodic ophthalmologic surveillance. German pediatric networks are piloting remote monitoring platforms to reduce travel burden for rural families.
- Intravenous:Chemotherapy infusion requires dedicated oncology nursing infrastructure and central line management. Academic medical centers in Japan concentrate this capacity within pediatric day hospital units.
- Subcutaneous:Limited current application in optic nerve glioma, though emerging depot formulations may shift maintenance phase delivery.
- Topical:No established therapeutic role; reserved for investigational intraocular delivery research protocols.
Intravenous delivery dominates current chemotherapy volumes; oral administration is expanding most quickly with targeted therapy adoption.
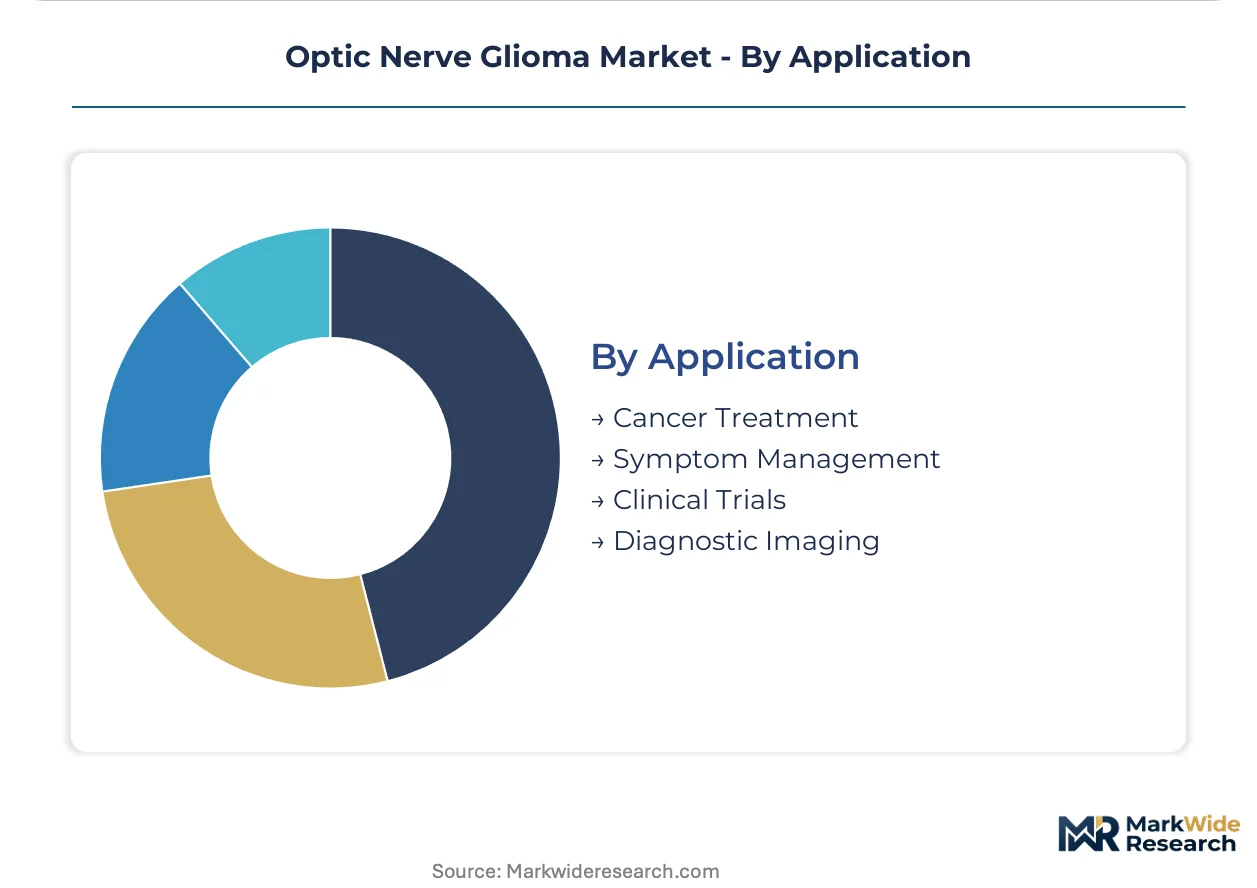
Application:
Clinical purpose determines endpoint selection, trial design, and regulatory pathway alignment.
- Cancer Treatment:Curative-intent or disease-modifying intervention targeting tumor control and visual preservation. FDA orphan drug designation accelerates development timelines for sponsors pursuing pediatric indications.
- Diagnostic Imaging:MRI surveillance with specialized optic pathway sequences enables treatment timing decisions. German referral networks are unbundling imaging hardware from longitudinal monitoring contracts.
- Symptom Management:Supportive care addressing visual field deficits, pain, and treatment-related toxicities.
- Clinical Trials:Biomarker-enriched enrollment for molecularly targeted agents, with visual function endpoints gaining regulatory acceptance.
Cancer treatment absorbs the majority of reimbursed activity; diagnostic imaging is climbing the fastest as surveillance intervals extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA orphan drug incentives and EMA pediatric investigation plans is concentrating clinical trial investment in jurisdictions with streamlined pediatric oncology pathways. Sponsors locate Phase II/III infrastructure where regulatory science alignment reduces compliance burden per patient enrolled.
United States
Pediatric neuro-oncology referral networks in Boston and Houston anchor multicenter trial recruitment for MEK inhibitor protocols. FDA orphan drug designation delivers tax credits and seven-year exclusivity that offset small addressable population economics. Memorial Sloan Kettering and St. Jude Children's Research Hospital concentrate specialized neuroradiology interpretation capacity for optic pathway surveillance.
Germany
Academic medical centers in Heidelberg and Berlin coordinate EU-wide pediatric brain tumor consortia under EMA pediatric investigation plan frameworks. The country's statutory health insurance system reimburses molecular diagnostic profiling for NF1-associated glioma cases. German referral networks unbundle MRI hardware procurement from longitudinal monitoring contracts.
Japan
PMDA mandates for domestic clinical evidence create first-mover advantages for sponsors establishing Japanese pediatric neuro-oncology infrastructure early. University hospitals in Tokyo and Osaka expand dedicated optic pathway tumor units to capture decade-long surveillance revenue. METI funding streams support proton beam facility expansion for neural tissue-sparing radiotherapy.
United Kingdom
NHS England specialized commissioning frameworks concentrate optic nerve glioma surgery in London and Manchester tertiary centers. The MHRA operates post-Brexit pediatric investigation plan pathways parallel to EMA requirements. Great Ormond Street Hospital anchors visual function endpoint standardization for international cooperative group trials.
Switzerland
Swissmedic pediatric medicine incentives attract sponsor headquarters for EU-accessible development programs. University Hospital Zurich and Geneva University Hospitals integrate ophthalmology-neurology-oncology multidisciplinary clinics. The country's precision medicine infrastructure supports biomarker-enriched trial enrollment for BRAF-mutant subpopulations.
Optic Nerve Glioma Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates dominating targeted therapy development while regional hospital networks control diagnostic imaging procurement. The market structure concentrates around oncology-focused conglomerates with existing pediatric infrastructure, supplemented by mid-cap neuro-oncology specialists. Three archetypes prevail: molecular diagnostic-therapeutic integrators, pediatric trial network operators, and surveillance service unbundlers. Competitive dynamics center on strategic partnerships for biomarker platform access and geographic expansion into Japanese pediatric neuro-oncology markets.
Among oncology conglomerates with pediatric infrastructure, Merck & Co., Novartis International AG, and Roche occupy positions spanning molecular diagnostic development through treatment monitoring. Merck & Co. exemplifies the trial network operator archetype through North American pediatric recruitment capacity. Novartis International AG represents molecularly guided protocol development with specialized neuro-oncology programs. Roche anchors the diagnostic-therapeutic integration model across biomarker identification and longitudinal surveillance platforms.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| Novartis International AG |
| Eli Lilly and Company |
| Amgen |
| Pfizer Inc |
| Roche |
| Teva Pharmaceutical Industries Ltd |
| Thermo Fisher Scientific Inc |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot indices for kinase inhibitors cascade through contract manufacturing tiers into MEK inhibitor pricing bands, compressing margins for oral targeted therapy while elevating cost barriers for intravenous chemotherapy procurement in community oncology settings.
Pricing Analysis
Distributor markups on oral oncology agents stratify across premium branded MEK inhibitors, standard generic chemotherapy vials, and economy-tier supportive care medications. Price differentiation hinges on FDA orphan drug exclusivity windows and biomarker companion diagnostic bundling. Pricing pressure stems from hospital procurement consolidation into centralized pharmacy benefit managers. Pediatric oncology centers exhibit highest price sensitivity due to constrained formulary budgets, while academic medical centers command volume-based rebates.
Supply Chain Analysis
Cold-chain logistics costs for biologic agents absorb margin across trans-Pacific lanes, elevating landed costs for Japanese pediatric networks sourcing from United States manufacturing sites. API production concentrates in India, China, and Switzerland, drawing from specialized fermentation capacity and synthetic chemistry expertise. Supply chain risk centers on single-source dependency for selumetinib active ingredients. Distribution runs through specialty pharmacy channels with direct-to-hospital drop-ship for clinical trial supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in optic nerve glioma therapeutics rests on oral formulation cost-down curves displacing infusion center overhead, while premium-tier positioning around biomarker-enriched protocols commands pricing power in United States and German referral networks.
For Market Incumbents: Anticipate MEK inhibitor commoditization by locking exclusive neuroradiology interpretation contracts with academic medical centers in Boston and Houston. Deepen backward integration into companion diagnostic development to defend against emerging liquid biopsy entrants. Prioritize Japanese PMDA trial infrastructure investment before local data mandates harden. For New Entrants and Emerging Players: Pediatric neuro-ophthalmology clinic partnerships offer lowest barrier-to-entry channels for surveillance service unbundling. White-space concentrates in remote monitoring platforms for rural German and Japanese families. Target adult sporadic optic nerve glioma protocols as the most penetrable indication segment with adapted toxicity frameworks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap oncology specialists possessing existing pediatric neuro-oncology trial networks and MEK inhibitor pipeline assets. Long-term viability favors platforms integrating diagnostic imaging with longitudinal therapeutic monitoring. Watch for FDA visual function endpoint guidance revision as inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Alignment | Parallel European development tracks accelerate timeline-sensitive MEK inhibitor programs. |
| Japan PMDA Local Trial Infrastructure | Domestic clinical evidence mandates create first-mover advantages for sponsors establishing early presence. |
| Biomarker Platform Licensing Agreement | BRAF and NF1 mutation profiling partnerships enable precision trial enrollment expansion. |
| Surveillance Service Unbundling | Subscription-based MRI monitoring separates hardware procurement from recurring revenue streams. |
| Neuro-Ophthalmology Fellowship Pipeline Investment | Specialist training partnerships address diagnostic bottleneck constraining multidisciplinary clinic expansion. |
Study Parameters
Multiple input streams — pediatric neuro-oncology protocol databases, FDA orphan drug designation filings, and EMA pediatric investigation plan submissions — were reconciled against primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov entries, formulary databases, and SEC oncology segment disclosures. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical protocol adoption curves were cross-referenced against expert panel inputs on MEK inhibitor penetration timelines. Segmentation dimensions spanned intervention modality, patient age stratum, administration route, and regional regulatory cluster across the projection horizon. CAGRs were derived from treatment-line shift assumptions and surveillance interval extension modeling, incorporating biomarker-guided enrichment rates and visual function endpoint standardization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory science shifts on visual outcome endpoints and Japan PMDA local data requirement evolution. Forecasts reflect documented assumptions on pediatric trial recruitment velocity and molecular diagnostic platform adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Blue Light Blocking Contact Lenses Market