
 Dacryocystitis Market | 2026-2036
Dacryocystitis Market Size, Share, and Industry Trends Forecast 2026-2036
Dacryocystitis Market Outlook
Post-procedural maintenance and antibiotic stewardship programs are consolidating into standard-of-care bundles for recurrent dacryocystitis management. Pfizer Inc. leverages its broad-spectrum antibiotic portfolio to anchor hospital formulary positioning. Novartis International AG sustains competitive presence through specialized ophthalmic care divisions. Bess Medizintechnik GmbH dominates precision surgical instrument manufacturing for lacrimal drainage procedures.
Dacryocystitis denotes acute or chronic inflammation of the lacrimal sac, typically secondary to nasolacrimal duct obstruction with Staphylococcus aureus or Streptococcus pneumoniae predominance, requiring microbiological culture for targeted therapy. The condition serves industrial purpose by driving demand for ophthalmic antibiotics, dacryocystorhinostomy instruments, and diagnostic imaging systems across acute and chronic presentation pathways. Antibiotics and surgical instruments represent mature revenue pools with stable hospital procurement volumes, while minimally invasive surgery and laser treatment segments capture faster expansion as ambulatory surgical centers upgrade capabilities. Diagnostic equipment margins concentrate in high-resolution digital imaging platforms replacing conventional dacryocystography.
FDA ophthalmic device regulations and EMA Medical Device Regulation frameworks elevate clinical evidence thresholds for surgical instrument market entry, compressing timelines for smaller manufacturers. The country's national pharmaceutical regulator in Japan applies PMDA consultation pathways that differentiate innovative lacrimal stent designs from commodity alternatives. Stakeholders must monitor evolving reimbursement codes for office-based laser procedures versus facility-based surgery as payers recalibrate site-of-service incentives.
Market Dynamics
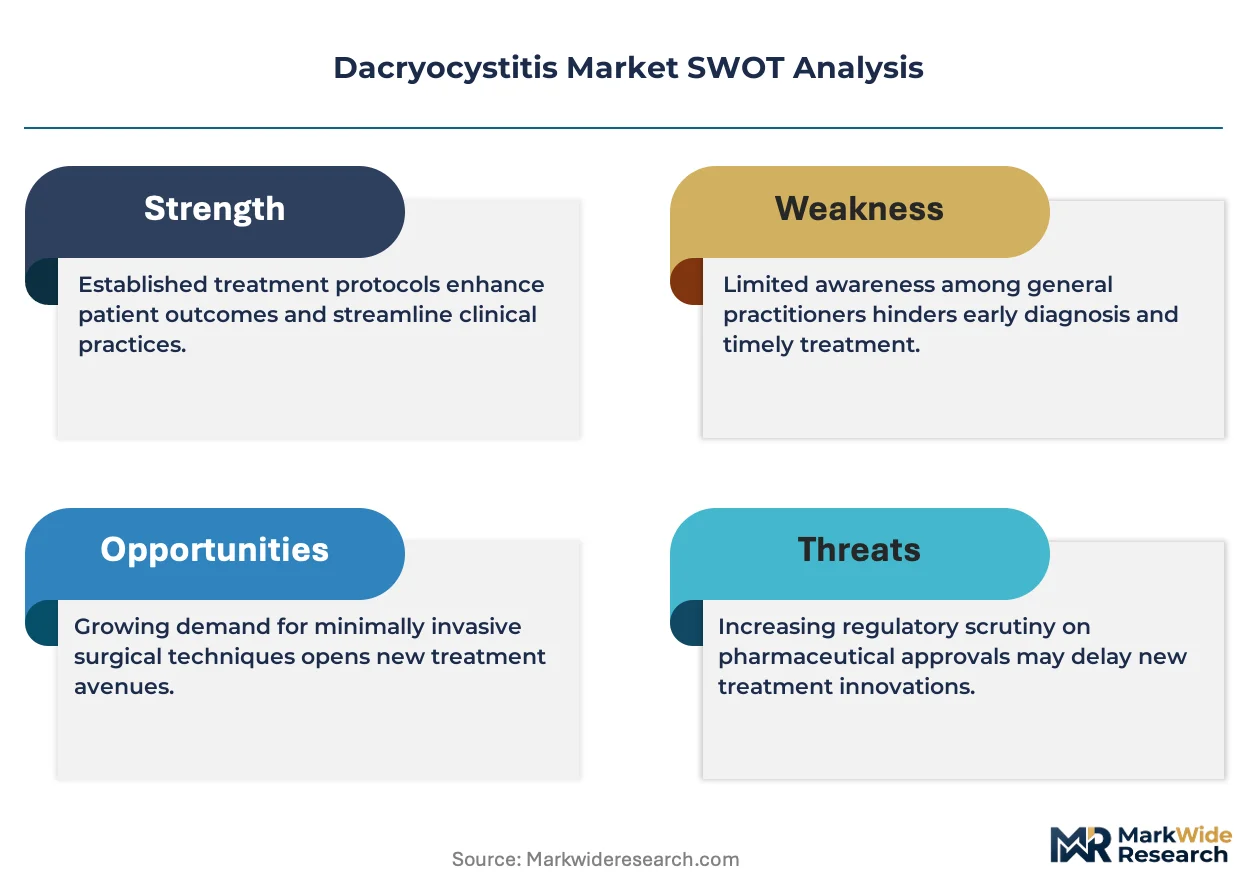
Minimally invasive dacryocystorhinostomy protocols are consolidating surgical volumes into ambulatory settings while FDA and EMA evidence requirements compress approval timelines for instrument manufacturers. This structural shift toward outpatient care is redistributing revenue across antibiotics, surgical devices, and diagnostic imaging segments.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States report rising incidence of acquired nasolacrimal duct obstruction as populations age past 65, expanding the addressable patient pool for intervention.
- EU Medical Device Regulation:MDR framework harmonization is streamlining CE marking pathways for innovative lacrimal stent designs, accelerating commercialization across European markets.
- Endoscopic instrumentation:High-definition visualization systems enable precise lacrimal sac access through nasal corridors, reducing operative trauma and recovery intervals.
Market Restraints
- Specialized surgeon scarcity:Oculoplastic fellowship training programs produce limited graduates annually, constraining procedural capacity in community hospital settings.
- Reimbursement compression:Medicare and commercial payers are narrowing site-of-service differentials between office-based and facility-based procedures, squeezing facility margins.
- Antibiotic resistance patterns:Methicillin-resistant Staphylococcus aureus predominance in chronic cases complicates empiric therapy selection and extends treatment duration.
Strategic Opportunities
- Office-based laser dacryocystorhinostomy:Infrared laser systems enable standalone ophthalmology practices to capture procedures previously referred to hospital outpatient departments.
- Japan PMDA Sakigake pathway:Breakthrough designation for novel biodegradable lacrimal stents offers expedited review and premium reimbursement positioning.
- Teleophthalmology integration:Remote postoperative monitoring platforms reduce follow-up burden while capturing real-world outcome data for payer negotiations.
Industry Challenges
- Microbiological culture turnaround:Delayed pathogen identification in acute presentations forces empiric broad-spectrum coverage, complicating antibiotic stewardship compliance.
- Legacy imaging infrastructure:Conventional dacryocystography equipment requires substantial capital replacement to achieve digital integration with electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dacryocystitis Market |
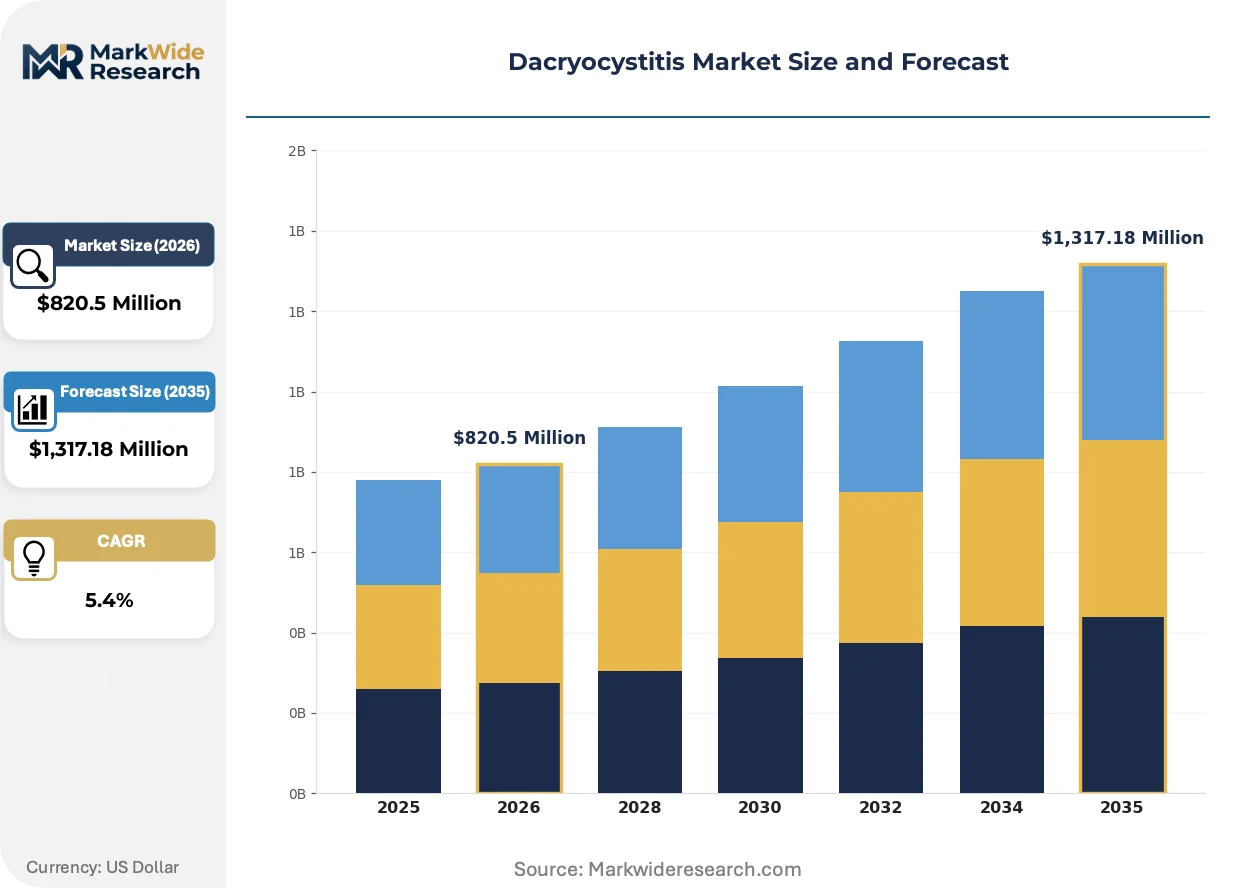
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,317.18 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Surgical Instruments, Diagnostic Equipment Application: Hospital Visits, Outpatient Treatment, Home Care, Emergency Services Technology: Minimally Invasive Surgery, Laser Treatment, Traditional Surgery, Diagnostic Imaging End User: Ophthalmology Clinics, Hospitals, Private Practices, Research Institutions |
| Companies Covered | Mylan NV, Kaneka Corporation, Pfizer Inc., Orex Pharma Pvt. Ltd., Novartis International AG, GlaxoSmithKline PLC, FCI Ophthalmics, Bess Medizintechnik GmbH, Aurobindo Pharma Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dacryocystitis Market Strategic Shifts
Technological convergence between endoscopic visualization and laser ablation systems is compressing the traditional surgical learning curve while regulatory frameworks recalibrate evidence requirements for market entry.
Multimodal imaging platforms combining high-definition endoscopy with indocyanine green angiography are unifying anatomical visualization and vascular assessment into single-procedure workflows. Ambulatory surgical centers in Germany and Japan are adopting these integrated systems to differentiate service offerings. The technology is unifying previously separate diagnostic and therapeutic steps, reducing operative time and instrument turnover requirements.
EMA Medical Device Regulation Article 61 clinical evidence mandates are elevating prospective trial requirements for lacrimal drainage stents and surgical instruments. Manufacturers must now submit PMCF (Post-Market Clinical Follow-up) protocols as condition of CE marking approval. Small-to-mid instrument suppliers in Switzerland and the Netherlands are responding by consolidating regulatory affairs functions and pursuing notified body partnerships.
Hospital procurement committees are consolidating antibiotic and surgical device purchasing into episode-based bundles for recurrent dacryocystitis management. Integrated delivery networks in the United States are replacing standalone product contracts with vendor partnerships spanning preoperative imaging through postoperative care. This consolidation is most visible in Medicare Advantage–dominated markets where risk-bearing entities seek to internalize procedural margins.
Dacryocystitis Market Segmentation
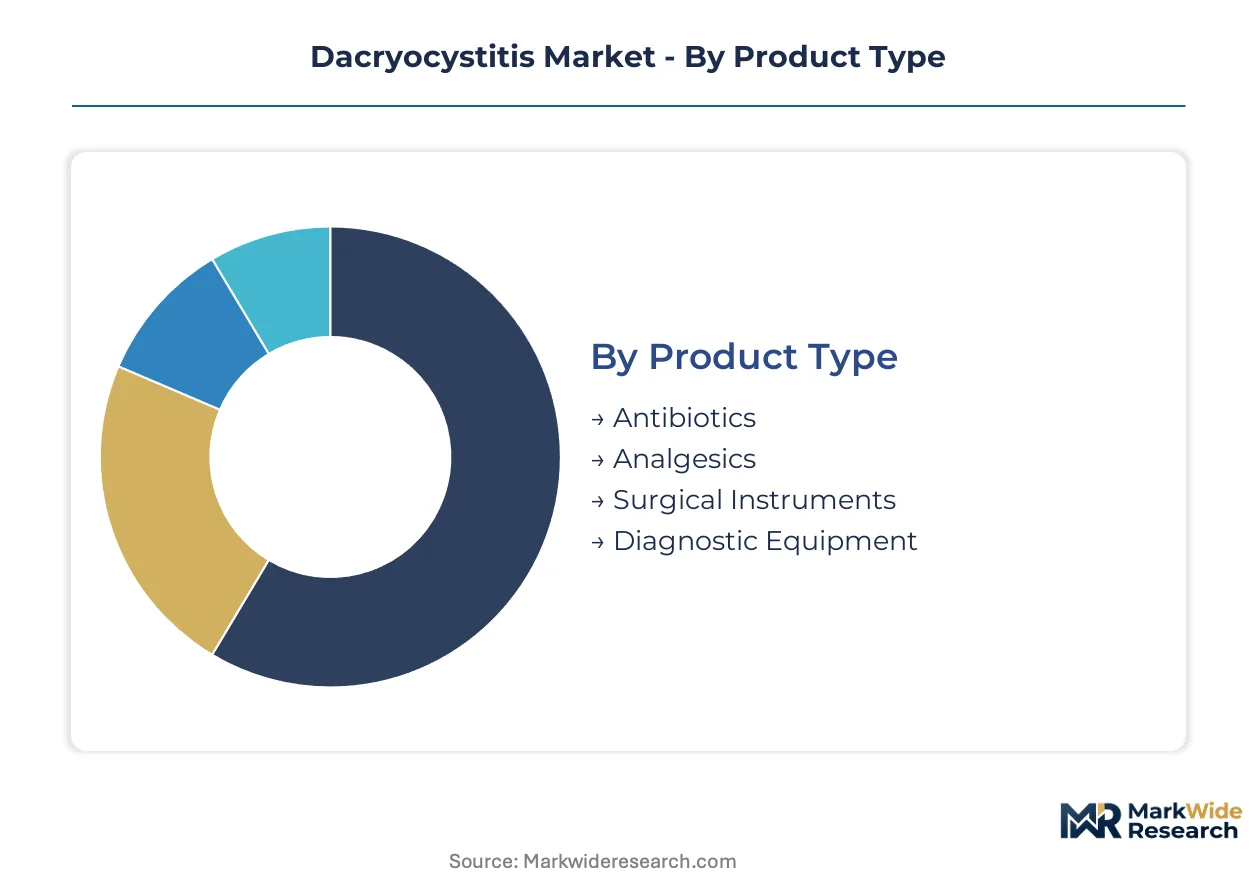
Dacryocystitis treatment pathways fragment across acute intervention, chronic management, and diagnostic workup stages. Procurement committees evaluate segments through distinct lenses: formulary compliance for pharmaceuticals, capital efficiency for equipment, and reimbursement yield for procedural technologies.
Product Type:
Hospital formulary committees weight acquisition cost against resistance profiles and stewardship compliance when selecting therapeutic categories.
- Antibiotics:Broad-spectrum agents dominate empiric therapy for acute presentations, with targeted therapy following culture results. Demand concentrates in hospital outpatient departments managing recurrent cases, constrained by MRSA prevalence extending treatment duration.
- Surgical Instruments:Precision-manufactured dacryocystorhinostomy sets include punches, probes, and stent inserters. German and Japanese manufacturers capture premium positioning through EMA MDR compliance and PMDA consultation pathways.
- Analgesics:Topical and systemic pain management supports preoperative and postoperative protocols.
- Diagnostic Equipment:Digital dacryocystography systems and high-resolution imaging platforms replace legacy infrastructure.
Volume sits with Antibiotics; growth tilts toward Surgical Instruments.
Application:
Site-of-service economics drive patient routing decisions as payers recalibrate reimbursement differentials between settings.
- Hospital Visits:Complex cases requiring general anesthesia or concurrent procedures route through hospital outpatient departments. United States Medicare Advantage plans increasingly steer patients toward lower-acuity settings where clinically appropriate.
- Outpatient Treatment:Office-based laser dacryocystorhinostomy and endoscopic procedures capture cases previously referred to facilities. Germany's ambulatory surgery centers upgrade visualization systems to compete for these volumes.
- Home Care:Post-procedural irrigation and antibiotic drop regimens extend care beyond clinical encounters.
- Emergency Services:Acute dacryocystitis with orbital cellulitis requires urgent intervention and intravenous antibiotics.
Revenue concentrates in Hospital Visits; margin expansion favors Outpatient Treatment.
Technology:
Surgeon training and capital availability determine technology adoption curves across practice settings.
- Minimally Invasive Surgery:Endoscopic dacryocystorhinostomy through nasal corridors reduces operative trauma and recovery intervals. Japanese clinics adopt these protocols fastest, supported by PMDA Sakigake pathway incentives for innovative instrumentation.
- Laser Treatment:Infrared laser systems enable standalone ophthalmology practices to perform procedures without facility referral. United States private practices invest in these platforms to capture facility fees internally.
- Traditional Surgery:External dacryocystorhinostomy remains the reference standard for complex revision cases.
- Diagnostic Imaging:Multimodal platforms combining endoscopy with indocyanine green angiography unify visualization workflows.
Procedure volume remains with Traditional Surgery; technology substitution accelerates in Laser Treatment.
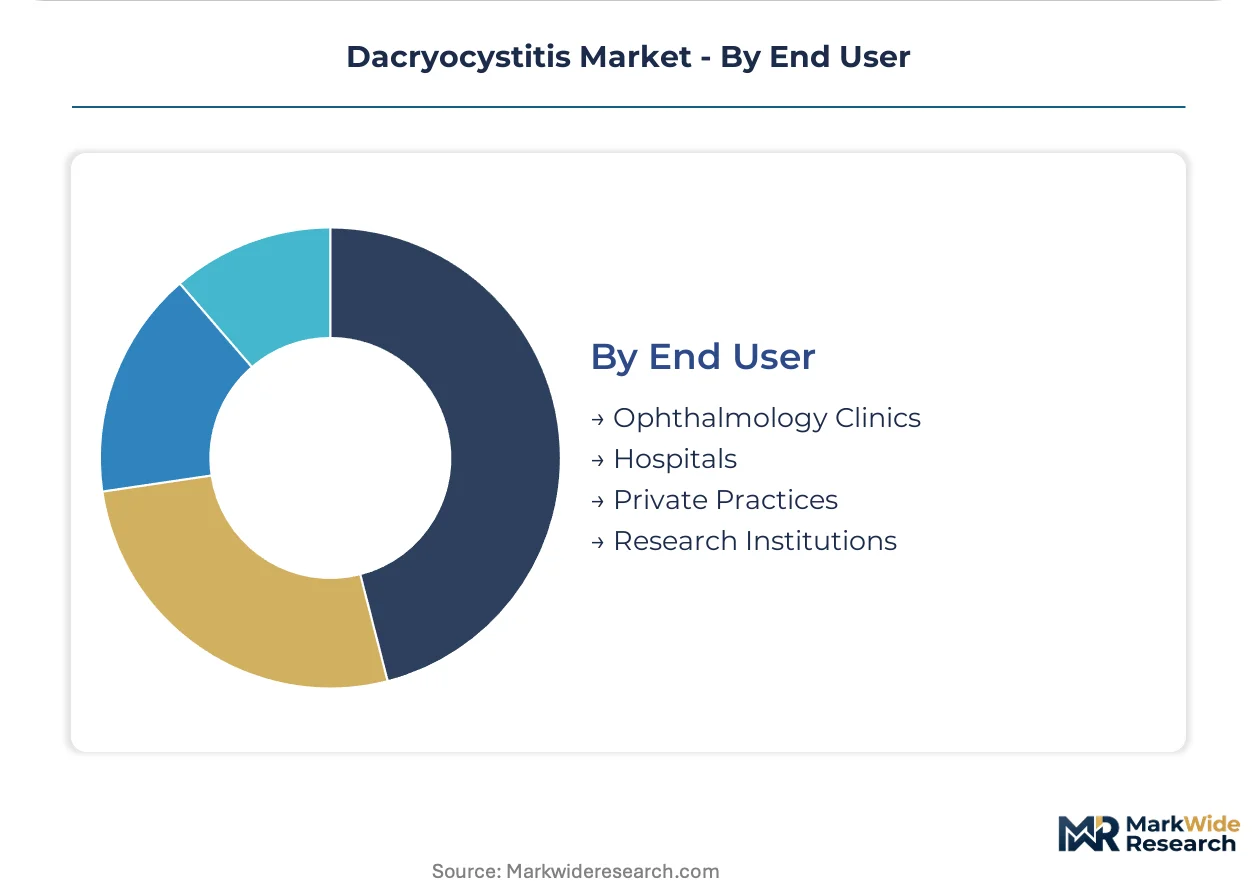
End User:
Capital intensity and reimbursement structure shape competitive positioning across provider types.
- Ophthalmology Clinics:Specialized oculoplastic practices concentrate procedural expertise and advanced instrumentation. Fellowship-trained surgeon scarcity limits expansion in community settings across all three major markets.
- Hospitals:Integrated delivery networks bundle imaging, surgery, and postoperative care into episode-based contracts. United States Medicare Advantage penetration drives this consolidation most aggressively.
- Private Practices:Solo and small-group ophthalmologists rely on referral relationships for complex cases.
- Research Institutions:Academic medical centers generate clinical evidence supporting regulatory submissions and payer negotiations.
Patient volume flows through Hospitals; service line expansion concentrates in Ophthalmology Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical instrument production concentrates in Germany and Japan while antibiotic consumption dominates hospital formularies across the United States. This geographic split between manufacturing expertise and clinical demand shapes procurement patterns and regulatory engagement strategies.
United States
Medicare Advantage penetration drives site-of-service arbitrage between office-based laser procedures and hospital outpatient departments. FDA ophthalmic device regulations tighten clinical evidence requirements for lacrimal stent approvals. The Cleveland Clinic and Mayo Clinic anchor oculoplastic fellowship training pipelines that constrain national procedural capacity.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia upgrade endoscopic visualization systems to capture dacryocystorhinostomy volumes from hospital networks. EMA Medical Device Regulation harmonization streamlines CE marking for innovative lacrimal drainage instruments. Stuttgart and Tübingen host precision surgical instrument clusters serving European export markets.
Japan
Aging demographics past 65 expand the addressable patient pool for acquired nasolacrimal duct obstruction interventions. PMDA Sakigake breakthrough designation offers expedited review pathways for biodegradable lacrimal stent innovations. Tokyo and Osaka metropolitan areas concentrate oculoplastic specialist practices with advanced endoscopic capabilities.
United Kingdom
NHS Integrated Care Systems bundle antibiotic procurement with surgical device purchasing for recurrent dacryocystitis episodes. MHRA convergence with EMA MDR frameworks elevates post-market surveillance requirements for imported instruments. Moorfields Eye Hospital anchors national training and referral pathways for complex lacrimal cases.
India
Domestic generic antibiotic production serves acute dacryocystitis management across tier-2 and tier-3 city hospital networks. CDSCO ophthalmic device registration pathways differentiate innovative stent designs from commodity surgical instruments. Hyderabad and Ahmedabad clusters manufacture precision lacrimal probes for Middle East and Southeast Asian export markets.
Dacryocystitis Market Competitive Environment
Capital-heavy surgical instrument manufacturers compete with asset-light pharmaceutical formulators across distinct value capture models. Market structure tilts toward consolidation in antibiotics alongside fragmentation in specialized surgical devices. Three archetypes dominate: broad-spectrum antibiotic portfolio holders, precision instrument fabricators, and diversified ophthalmic care divisions. M&A activity concentrates on vertical integration of surgical visualization with laser ablation platforms, while strategic partnerships link antibiotic developers with hospital stewardship programs.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis International AG occupy positions anchoring hospital formulary relationships through broad-spectrum and specialized ophthalmic portfolios respectively. Bess Medizintechnik GmbH exemplifies the precision instrument archetype, representing German manufacturing concentration in lacrimal drainage procedure sets. These three entities collectively illustrate the competitive tension between pharmaceutical scale economies and surgical device technical specialization.
| Leading Market Players |
|---|
| Mylan NV |
| Kaneka Corporation |
| Pfizer Inc. |
| Orex Pharma Pvt. Ltd. |
| Novartis International AG |
| GlaxoSmithKline PLC |
| FCI Ophthalmics |
| Bess Medizintechnik GmbH |
| Aurobindo Pharma Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between EMA MDR-compliant precision instruments and commodity surgical sets manifests in divergent pricing power across German manufacturing clusters versus Indian export hubs, with procurement committees weighting clinical evidence thresholds against landed cost differentials in hospital formulary decisions.
Pricing Analysis
Margin tightening in commodity antibiotic tiers reflects MRSA-driven treatment extension and formulary stewardship compliance costs, while premium surgical instrument pricing holds firm through PMDA Sakigake pathway incentives. Three-tier pricing structure across premium, standard, and economy levels separates EMA-notified manufacturers from regional CE-mark suppliers and unbranded Asian exporters. Cost-down pressure on generic antibiotic portfolios accelerates because hospital procurement committees consolidate episode-based bundles. Academic medical centers exhibit lowest price sensitivity; community hospital outpatient departments face highest budget constraints.
Supply Chain Analysis
Japan's PMDA domestic-content consultation pathways and Germany's MDR notified-body proximity requirements are reshaping sourcing patterns for lacrimal stent and precision instrument categories. Manufacturing gravity centers on Germany, Japan, and Switzerland for high-compliance surgical sets, while India and China feed generic antibiotic active pharmaceutical ingredients. Raw material dependencies span medical-grade stainless steel, biodegradable polymers, and ophthalmic-grade silicone. Single-source vulnerability concentrates in PMDA-registered stent innovators. Distribution runs through hospital procurement committees and integrated delivery network formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oculoplastic surgeon scarcity constrains procedural capacity expansion, propping pricing power for fellowship-trained specialists and their preferred instrument suppliers across all three major markets.
For Market Incumbents: To counter ambulatory surgical center capture of previously hospital-based volumes, Bess Medizintechnik GmbH and precision instrument archetypes should deepen backward integration into endoscopic visualization systems while securing PMDA Sakigake designations for biodegradable stent platforms. Hospital formulary anchoring through antibiotic stewardship program partnerships defends against generic substitution. For New Entrants and Emerging Players: A mid-tier pricing gap between German EMA-compliant manufacturers and Indian commodity suppliers creates entry space for CDSCO-registered precision instrument specialists targeting Middle East and Southeast Asian export markets. White-space concentration sits with office-based laser dacryocystorhinostomy platforms for United States private practice ophthalmology. Go-to-market leverage through teleophthalmology-enabled remote monitoring bundles differentiates against established hospital referral relationships. For Investors and Strategic Acquirers: Re-rating potential sits with diversified ophthalmic care divisions given laser-surgical convergence catalysts and ambulatory site-of-service expansion. Long-term viability frames around 5-10 year procedure volume shifts toward outpatient settings. Acquisition target archetype: precision instrument manufacturers with PMDA consultation pathway experience and endoscopic visualization integration capabilities. Signal to watch: Medicare Advantage site-of-service differential compression accelerating office-based laser adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR Article 61 compliance unlocks European hospital procurement access for lacrimal stent innovators. |
| Hospital System Partnership | Integrated delivery network formulary anchoring secures antibiotic bundle positioning against generic substitution. |
| Software Companion Development | Teleophthalmology postoperative platforms capture real-world outcome data for Medicare Advantage negotiations. |
| Reimbursement Strategy | Office-based laser procedure code optimization shifts site-of-service economics toward private practice capture. |
| FDA Submission | Breakthrough device designation for biodegradable stents accelerates United States market entry timelines. |
Study Parameters
Multi-period observation of PMDA consultation pathway outcomes, EMA MDR CE marking timelines, and Medicare Advantage site-of-service differentials anchored the trend analysis, supplemented by interviews with oculoplastic fellowship program directors, hospital procurement committee chairs, biomedical engineers specializing in lacrimal drainage instrumentation, and GPO contracts managers. Secondary validation drew from FDA 510(k) ophthalmic device filings, EMA MDR notified body guidance documents, CMS Medicare physician fee schedule data, and Japanese Ministry of Health reimbursement bulletins. Bottom-up procedure volume modeling triangulated against top-down pharmaceutical consumption forecasts.
Segment-weighting across antibiotics, surgical instruments, diagnostic equipment, and laser treatment platforms calibrated revenue distribution assumptions over the projection horizon. Technology substitution curves for endoscopic versus external dacryocystorhinostomy, ambulatory versus hospital outpatient routing patterns, and generic versus branded antibiotic formulary positioning shaped analytical framework inputs. CAGRs derived from patient demographic projections intersecting with procedure adoption elasticity estimates.
Inputs from PMDA, EMA, and FDA regulatory databases were available through the study window; gaps in real-time Medicare Advantage plan-specific site-of-service policy changes introduce uncertainty bands around outpatient procedure volume forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Cataract Treatment Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Eye Allergy Treatment Market