
 US Ophthalmic Sutures Market | 2026-2036
US Ophthalmic Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
US Ophthalmic Sutures Market Analysis
US-based surgical suture manufacturers is repositioning production capacity toward specialized ophthalmic threads with finer gauge profiles and enhanced tensile consistency. Ethicon leverages its Johnson & Johnson parent infrastructure to sustain broad hospital formulary access across the Southeast and Midwest. B. Braun Melsungen AG anchors its competitive stance through precision extrusion capabilities for monofilament nylon lines. DemeTECH Corporation differentiates via cost-efficient braided silk alternatives that compete aggressively in academic medical center procurement cycles.
Ophthalmic sutures are ultra-fine surgical threads, typically ranging from 8-0 to 11-0 in USP gauge, designed for wound closure in delicate ocular tissues where minimal tissue reaction and precise approximation are critical. Polyglactin absorbable sutures dominate hospital purchasing volumes due to predictable hydrolytic degradation profiles that eliminate removal procedures in cataract and corneal applications. Nylon monofilament variants command premium positioning in vitreoretinal surgery where long-term tensile strength and minimal inflammatory response are essential. Braided polyester threads retain stable share in lacrimal duct and external ocular procedures where handling characteristics outweigh absorption benefits.
FDA 510(k) premarket notification requirements and ISO 13485 quality management standards govern domestic manufacturing compliance, with recent guidance emphasis on biocompatibility testing for synthetic polymer coatings reshaping R&D allocation. State-level certificate-of-need regulations in New York and Illinois constrain ambulatory surgical center expansion, indirectly filtering suture demand patterns across metropolitan statistical areas. Stakeholders must monitor CMS reimbursement rate adjustments for office-based surgical procedures and evolving FDA digital health integration policies that may redefine suture-adjacent device classification boundaries.
Market Dynamics
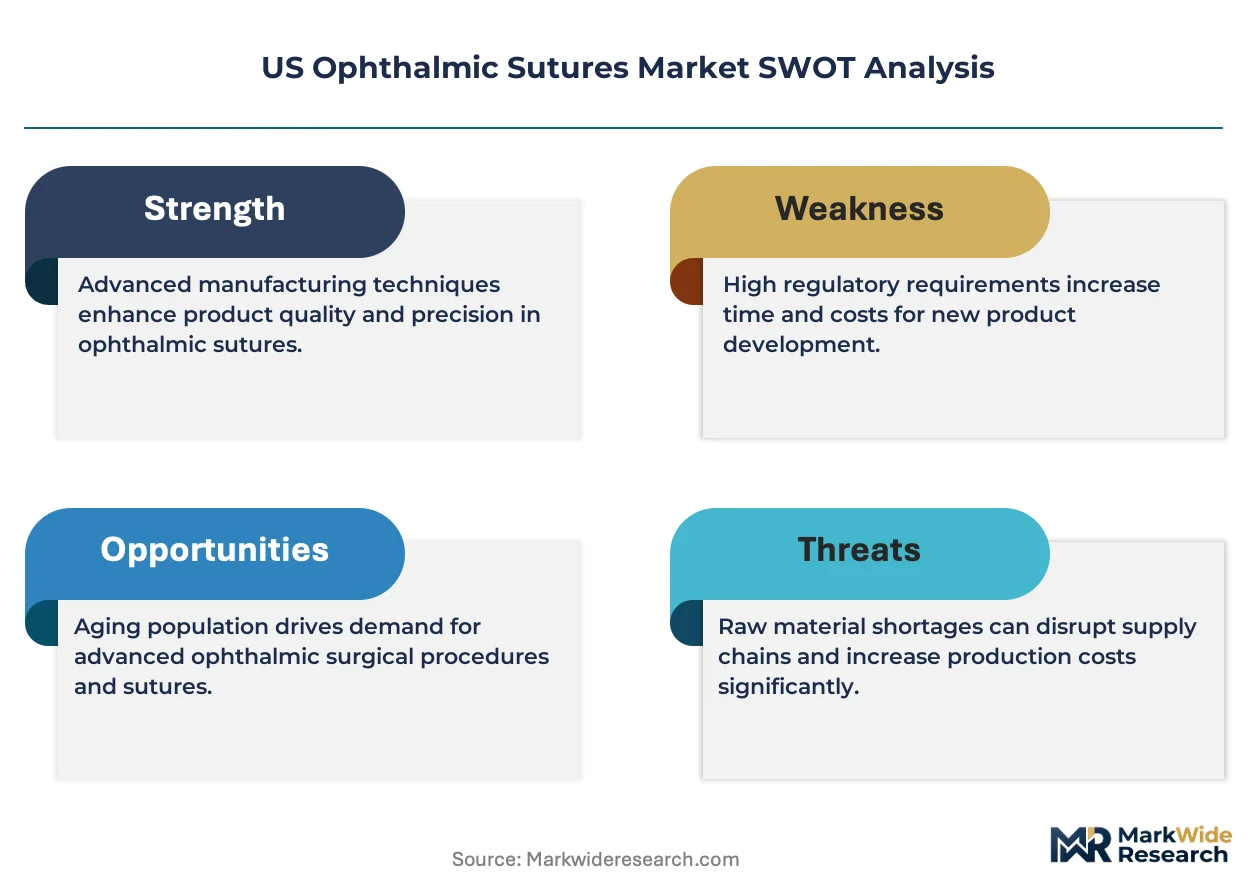
FDA Class II device controls and updated 510(k) pathway requirements are tightening compliance obligations for domestic ophthalmic suture manufacturers, forcing production line reconfigurations and extended validation timelines.
Growth Catalysts
- Aging Demographics:Sun Belt states including Florida, Arizona, and Texas are experiencing concentrated population aging, expanding the addressable patient base for cataract procedures requiring absorbable polyglactin sutures.
- Ambulatory Surgical Center Expansion:Certificate-of-need exemptions in southeastern states are accelerating ASC network buildouts, creating dedicated procurement channels for ultra-fine gauge suture inventories.
- Biocompatibility Testing Standards:Updated ISO 10993 guidance for synthetic polymer coatings is elevating product differentiation thresholds, rewarding manufacturers with validated hydrolytic degradation profiles.
Market Restraints
- Raw Material Concentration:Medical-grade polyglactin polymer supply concentrates among three specialty chemical producers, exposing suture manufacturers to input cost volatility and allocation constraints.
- Regulatory Friction:FDA 510(k) premarket notification timelines for ophthalmic surgical instruments have extended by four to six months, compressing product launch windows and R&D amortization periods.
- Substitution Pressure:Tissue adhesives and femtosecond laser-assisted wound closure techniques are gaining traction in corneal applications, threatening suture volume in anterior segment procedures.
Strategic Opportunities
- Office-Based Surgical Procedures:CMS reimbursement rate adjustments for in-office anterior segment interventions are creating demand for compact, sterile-packaged suture kits suited to clinic-based settings.
- Digital Health Integration:FDA digital health policies are redefining device classification boundaries, opening pathways for smart suture systems with embedded tensile sensors in vitreoretinal applications.
- Academic Medical Center Procurement:Cost-efficient braided silk alternatives are penetrating tier-one teaching hospitals through value-based purchasing agreements that prioritize handling characteristics over absorption benefits.
Industry Challenges
- Precision Extrusion Talent Scarcity:Monofilament nylon production requires specialized polymer engineering expertise that concentrates among a shrinking cohort of US-based medical device technicians.
- ISO 13485 Certification Timelines:Quality management system audits for ophthalmic suture manufacturing facilities are backlogged, delaying market entry for emerging domestic producers.
- Legacy Inventory Integration:Hospital outpatient departments face friction consolidating suture specifications across expanding cataract surgery suites with incompatible procurement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ophthalmic Sutures Market |
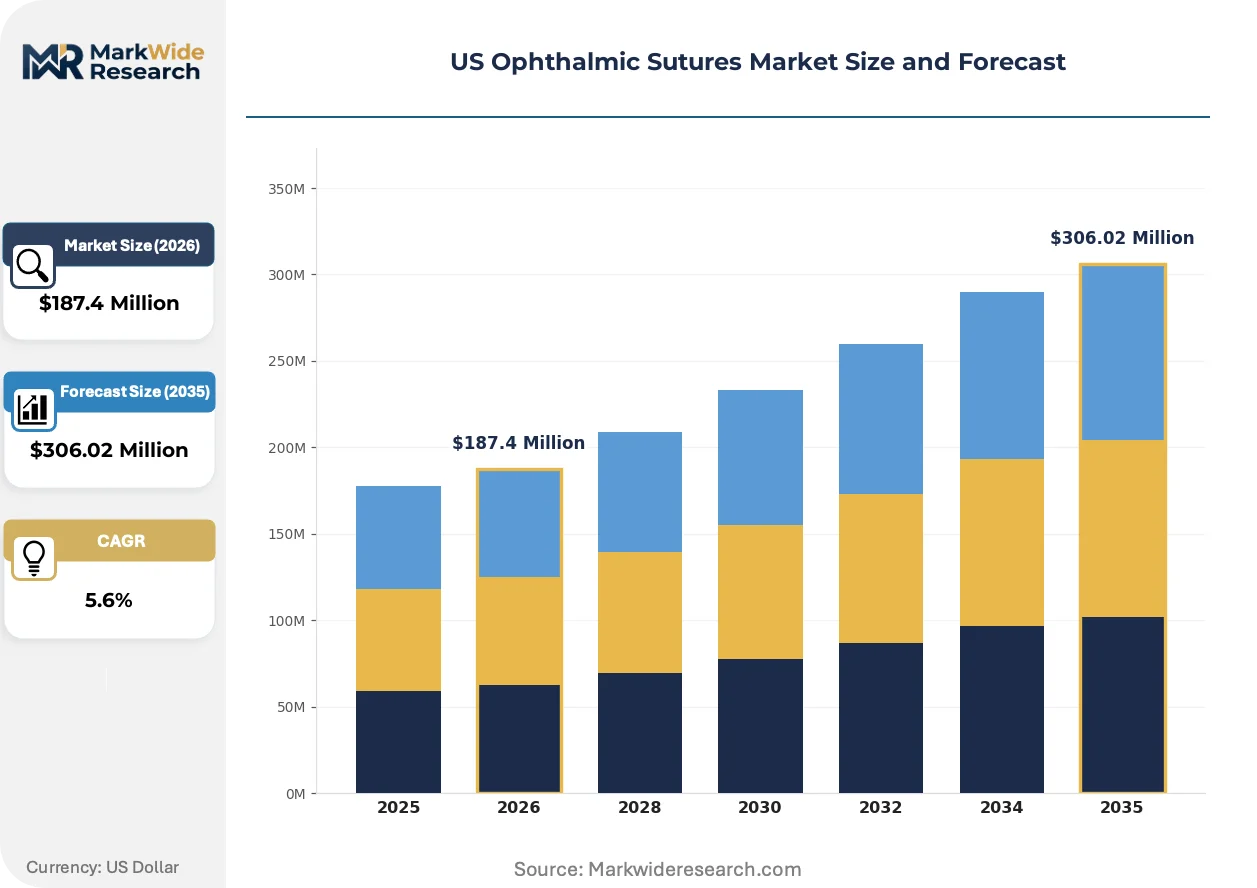
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $306.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-Absorbable Sutures, Monofilament Sutures, Braided Sutures Material: Polyglactin, Nylon, Silk, Polyester Application: Cataract Surgery, Corneal Surgery, Vitreoretinal Surgery, Laqueation Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Academic Institutions |
| Companies Covered | Ethicon (Johnson & Johnson), Medtronic, B. Braun Melsungen AG, Corza Medical, Mani, Teleflex Incorporated, DemeTECH Corporation, Alcon Inc., Aurolab, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ophthalmic Sutures Market Emerging Trajectories
Manufacturing precision and regulatory digitization are converging to reshape how ophthalmic sutures are produced, validated, and procured across US healthcare networks.
Antibacterial-coated synthetic absorbable sutures are expanding into hospital outpatient departments as infection control protocols tighten for intraocular procedures. Cataract surgery suites in the Southeast are adopting these modified polyglactin threads at accelerated rates. The technology is expanding into premium product tiers that command formulary preference through documented biocompatibility advantages.
FDA guidance emphasis on biocompatibility testing for synthetic polymer coatings is redirecting R&D allocation toward validated coating chemistries. Domestic manufacturers are reconfiguring quality management systems to accommodate expanded cytotoxicity and sensitization protocols. Ophthalmic suture lines with Class II device controls face the steepest compliance burden, driving consolidation among mid-tier producers.
Hospital formulary committees are unbundling suture procurement from broader surgical instrument contracts, creating direct negotiation channels with specialty manufacturers. Academic medical centers in the Midwest are leading this disintermediation, establishing dedicated vendor relationships for ultra-fine gauge inventories. The shift is most visible in metropolitan statistical areas with concentrated ASC network competition.
US Ophthalmic Sutures Market Segmentation
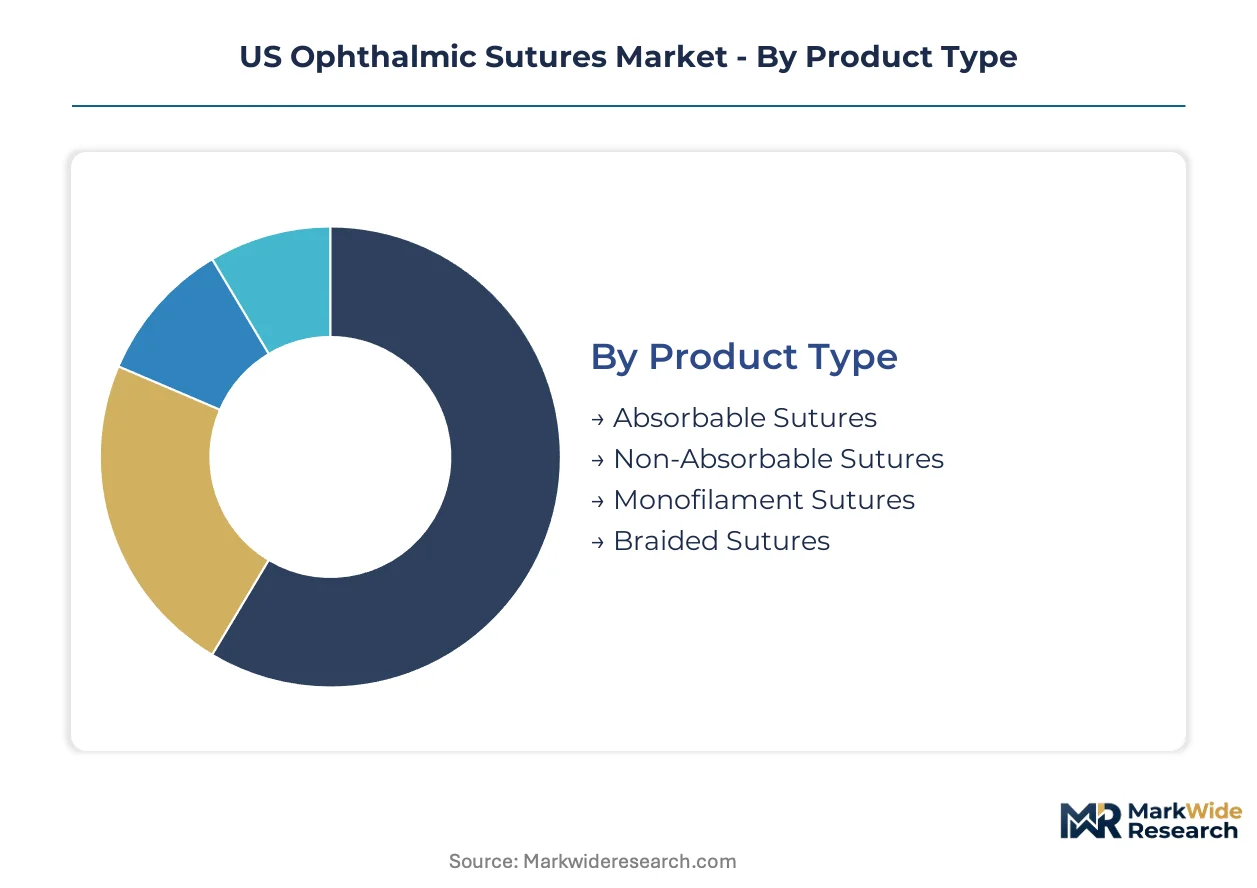
Ophthalmic suture procurement patterns diverge sharply between high-volume absorbable lines for cataract suites and premium monofilament inventories for specialized vitreoretinal centers. Understanding these segment boundaries reveals where manufacturers must calibrate gauge precision, coating chemistry, and packaging formats to match distinct clinical workflows and reimbursement environments.
Product Type:
Volume concentration sits with absorbable formats that eliminate removal procedures, while premium positioning attaches to non-absorbable variants where long-term tensile integrity commands formulary preference.
- Absorbable Sutures:Synthetic polymers such as polyglactin undergo predictable hydrolytic degradation, eliminating suture removal in cataract and corneal procedures. Hospital outpatient departments in Florida and Arizona are expanding formulary commitments to these lines as procedure volumes climb among aging demographics.
- Non-Absorbable Sutures:Nylon and polyester constructions retain tensile strength indefinitely, serving vitreoretinal applications where wound closure must withstand chronic intraocular forces. Academic medical centers in the Midwest maintain dedicated inventory for complex posterior segment repairs.
- Monofilament Sutures:Single-strand polymer extrusion minimizes tissue drag and bacterial wicking. The format dominates premium tier positioning for microsurgical precision.
- Braided Sutures:Multi-filament weaving delivers superior handling characteristics and knot security. Demand concentrates in lacrimal duct and external ocular procedures where surgeon tactile feedback outweighs absorption benefits.
Today's leader: Absorbable Sutures. Tomorrow's challenger: Monofilament Sutures.
Material:
Raw material selection determines degradation kinetics, inflammatory response profiles, and ultimate reimbursement coding for ophthalmic wound closure.
- Polyglactin:Copolymer of glycolide and lactide delivers 60-90 day absorption with minimal tissue reaction. Cataract surgery suites across Texas ASC networks are standardizing on this chemistry for anterior segment efficiency.
- Nylon:Polyamide monofilament provides indefinite tensile retention with low immunogenicity. Vitreoretinal specialists in metropolitan New York centers specify this material for complex retinal detachment repairs requiring chronic structural support.
- Silk:Natural protein fiber offers unmatched handling and knot security despite inflammatory potential. Academic procurement committees in the Southeast are revisiting silk for teaching applications where technique demonstration matters.
- Polyester:Synthetic braided construction combines durability with controlled elasticity. External ocular and oculoplastic procedures in California hospital systems favor this material for eyelid and lacrimal applications.
Polyglactin anchors current hospital purchasing volumes. Nylon claims the steepest expansion trajectory in premium surgical segments.
Application:
Procedure-specific anatomical demands dictate gauge selection, curvature design, and coating requirements across ophthalmic subspecialties.
- Cataract Surgery:Clear corneal and scleral tunnel incisions require 10-0 to 11-0 absorbable sutures with minimal induced astigmatism. ASC networks in the Sun Belt are driving unit volume expansion for this application.
- Corneal Surgery:Penetrating keratoplasty and lamellar procedures demand precise apposition without vascularization. The segment rewards manufacturers with validated endothelial cell preservation data.
- Vitreoretinal Surgery:Scleral buckling and sclerotomy closure require 5-0 to 7-0 non-absorbable strength. Teaching hospitals in Illinois maintain specialized inventories for these complex posterior interventions.
- Laqueation Procedures:Lacrimal drainage system reconstruction balances absorbable convenience with long-term patency needs. Oculoplastic specialists in academic centers drive specification diversity here.
Cataract Surgery commands absolute unit volumes. Vitreoretinal Surgery offers the highest revenue per procedure.
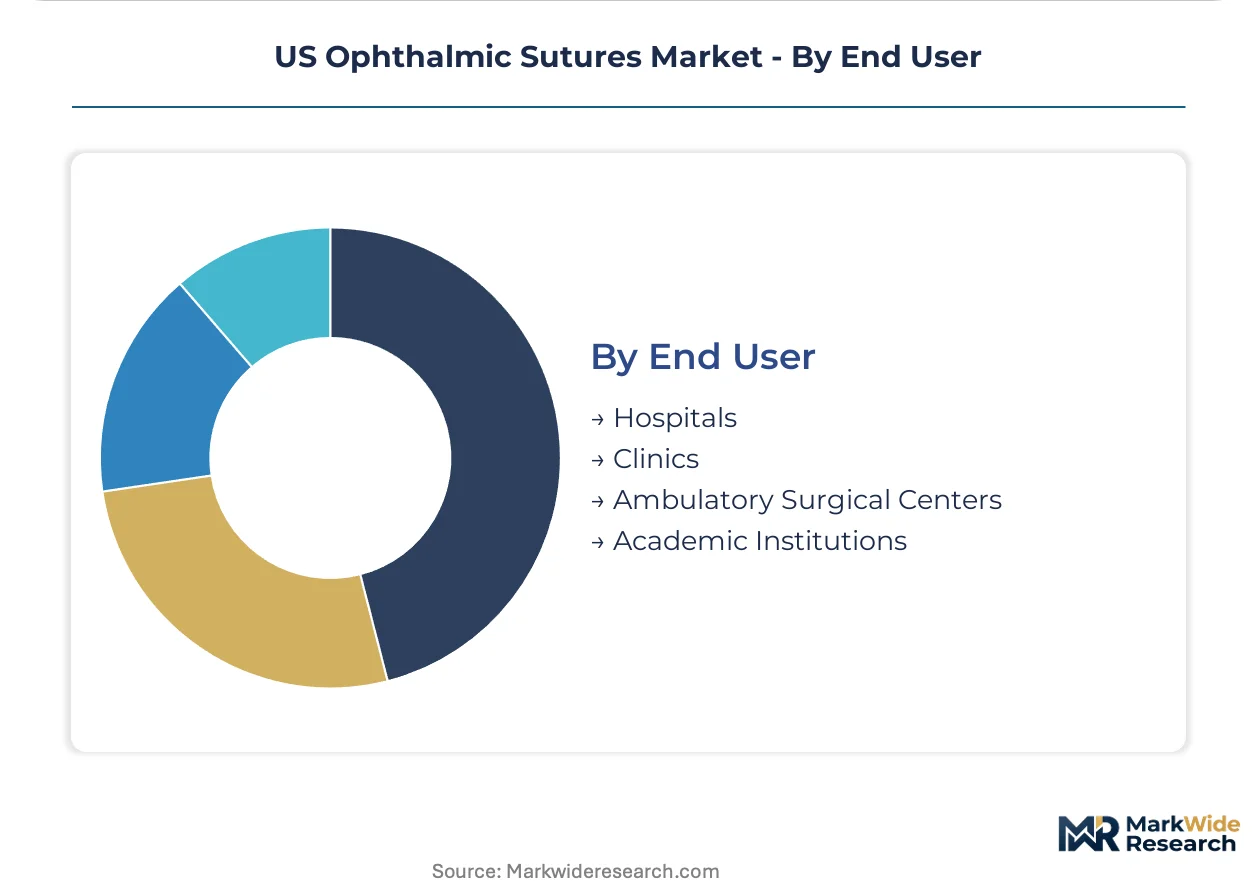
End User:
Procurement authority and inventory sophistication vary dramatically across institutional settings, from centralized hospital supply chains to independent clinic purchasing.
- Hospitals:Integrated delivery networks leverage volume contracting for broad formulary coverage. Certificate-of-need states like New York concentrate purchasing power within fewer institutional buyers.
- Clinics:Office-based surgical procedures are expanding under CMS reimbursement adjustments, creating demand for compact sterile kits. Ophthalmology practices in Florida are leading this channel shift.
- Ambulatory Surgical Centers:Specialized cataract-focused facilities in Texas and Arizona optimize inventory turns for high-throughput absorbable suture consumption. The segment rewards just-in-time delivery capabilities.
- Academic Institutions:Teaching hospitals balance cost efficiency with training requirements for multiple suture techniques. Midwest medical centers maintain the most diverse specification portfolios.
ASCs are gaining share fastest in absolute volume expansion. Academic Institutions retain pricing power through specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturers face diverging compliance costs across state jurisdictions, creating production migration incentives toward regions with streamlined FDA inspection schedules and lower facility certification overhead.
Southeast (Florida/Georgia)
Ambulatory surgical center networks in Tampa and Atlanta are absorbing the fastest cataract procedure volume growth. Certificate-of-need exemptions in Georgia accelerate ASC licensing compared to Florida's moderate restrictions. Orlando-area distributors maintain just-in-time polyglactin suture inventories for high-throughput cataract suites.
Southwest (Texas/Arizona)
Phoenix and Dallas-Fort Worth metro areas concentrate aging demographic expansion driving absorbable suture procurement. Texas Health and Human Services streamlined ASC accreditation reduces entry friction for new surgical facilities. San Antonio medical device clusters host specialty polymer extrusion subcontractors serving regional manufacturers.
Midwest (Illinois/Michigan/Ohio)
Academic medical centers in Chicago and Cleveland maintain diverse suture specifications for training programs. Illinois certificate-of-need regulations constrain ASC expansion, filtering demand through established hospital outpatient departments. Detroit-area procurement consortia negotiate volume contracts for braided polyester inventories.
Northeast Corridor
Metropolitan New York vitreoretinal specialists specify premium nylon monofilament for complex posterior segment repairs. New York State CON laws limit ambulatory facility growth, concentrating purchasing within integrated delivery networks. Boston-area teaching hospitals drive specification diversity through research protocol requirements.
Pacific Coast (California)
Los Angeles and San Francisco Bay Area oculoplastic practices favor braided polyester for eyelid and lacrimal procedures. California Office of Statewide Health Planning and Development facility licensing adds compliance layers distinct from federal requirements. San Diego medical device startups pilot antibacterial coating technologies for specialized suture lines.
US Ophthalmic Sutures Market Vendor Landscape
US-based producers anchor one tier through FDA-established quality systems; European and Asian specialists hold differentiated positions through precision manufacturing heritage and cost-optimized alternatives. The vendor base concentrates among diversified medical device conglomerates with suture divisions, mid-tier regional manufacturers, and emerging domestic challengers. Three strategic archetypes dominate: integrated hospital supply conglomerates leveraging formulary access, precision extrusion specialists commanding premium tiers, and cost-efficient alternatives penetrating academic procurement cycles. Competitive moves center on capacity reconfiguration for finer gauge production and strategic partnerships with antibacterial coating technology providers.
Within the integrated conglomerate tier, Ethicon and Medtronic exemplify market positions built through parent-company infrastructure and broad hospital system relationships. B. Braun Melsungen AG anchors the European specialist archetype with precision manufacturing lineage. DemeTECH Corporation occupies a position among emerging domestic alternatives competing on value-based purchasing metrics. Alcon Inc. represents the ophthalmic-focused diversification play, leveraging adjacent surgical instrument relationships for suture bundling opportunities.
| Leading Market Players |
|---|
| Ethicon (Johnson & Johnson) |
| Medtronic |
| B. Braun Melsungen AG |
| Corza Medical |
| Mani |
| Teleflex Incorporated |
| DemeTECH Corporation |
| Alcon Inc. |
| Aurolab |
| Others |
Supply Flow & Price Mechanics
Absorbable polyglactin premium-versus-commodity bifurcation manifests in divergent margin structures and procurement channel configurations across hospital outpatient departments and ambulatory surgical centers. FDA Class II device controls enforce quality tier separation that concentrates pricing power among manufacturers with validated ISO 13485 systems, while cost-efficient braided silk alternatives penetrate academic medical centers through distributor-mediated volume contracts.
Pricing Analysis
Distributor margin layers absorb 15-35 points before hospital formulary placement, with GPO-negotiated direct contracts compressing this spread for high-volume absorbable lines. Three-tier pricing structure across premium monofilament, standard braided synthetic, and economy silk tiers differentiates by tensile consistency certification and coating validation depth. Pricing pressure stems from tissue adhesive substitution in corneal applications, forcing suture manufacturers to bundle antibacterial coatings without commensurate price escalation. Academic medical centers exhibit highest price sensitivity through value-based purchasing agreements, while vitreoretinal specialists in metropolitan New York maintain lowest sensitivity due to procedure complexity requirements.
Supply Chain Analysis
Precision polymer engineering talent scarcity in San Antonio and Boston medical device clusters constrains domestic monofilament nylon expansion despite demand acceleration. Medical-grade polyglactin polymer supply draws from three specialty chemical producers concentrated in Germany, Japan, and the United States, with braided silk threads sourcing from Indian and Chinese natural fiber processors. Single-source vulnerability in hydrolytic degradation catalysts exposes manufacturers to allocation constraints during pharmaceutical polymer demand spikes. Distribution runs through regional medical-surgical distributors with just-in-time ASC servicing capabilities, supplemented by direct hospital system contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US ophthalmic sutures market compounds steadily through aging demographic tailwinds in Sun Belt states that guarantee procedure volume expansion regardless of macroeconomic fluctuation.
For Market Incumbents: Acquire precision extrusion engineering capabilities in San Antonio and Phoenix manufacturing corridors to secure monofilament nylon talent pools before competitor consolidation. Defend against tissue adhesive substitution by embedding antibacterial coating R&D within existing quality management systems, prioritizing FDA 510(k) pathway pre-submissions for modified polymer chemistries. Channel control through exclusive GPO contracts for absorbable polyglactin lines protects volume share against cost-efficient braided silk entrants. For New Entrants and Emerging Players: Capture office-based surgical procedure demand in Florida ophthalmology practices through compact sterile suture kit formats optimized for CMS reimbursement-adjusted clinic settings. White-space penetration concentrates in antibacterial-coated synthetic absorbable lines where biocompatibility testing requirements deter commodity competitors. Go-to-market execution partners with regional medical-surgical distributors possessing established ASC relationships in Texas and Arizona certificate-of-need exemption zones. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers face extended FDA 510(k) validation timelines that compress R&D amortization windows below sustainable thresholds. Five-to-ten year viability favors precision extrusion specialists with captive polymer supply agreements and validated coating chemistries. Acquisition target archetype: domestic manufacturers with ISO 13485 certification backlog clearance and established hospital formulary positions in Midwest academic medical centers. Signal to monitor: CMS reimbursement rate adjustments for in-office anterior segment procedures that would accelerate clinic channel suture kit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Antibacterial Coating Validation | FDA biocompatibility testing investments differentiate premium polyglactin tiers in hospital formulary competitions. |
| Precision Extrusion Capacity Addition | Monofilament nylon production expansion in San Antonio medical device clusters secures vitreoretinal surgery supply. |
| ASC Direct Distribution Partnership | Just-in-time delivery capabilities in Texas and Arizona certificate-of-need exemption zones capture volume growth. |
| ISO 13485 Quality System Enhancement | Accelerated certification timelines reduce market entry friction for emerging domestic suture manufacturers. |
| Office-Based Procedure Kit Development | Compact sterile packaging formats align with CMS reimbursement adjustments for Florida clinic-based interventions. |
Methodological Framework
Direct dialogue with ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative assessment of suture specification priorities and procurement decision frameworks. Secondary validation drew from FDA 510(k) premarket notification databases, hospital procurement records, CMS Medicare reimbursement filings, and ISO 13485 certification registries. Bottom-up demand modeling across absorbable and non-absorbable product categories triangulated against top-down manufacturer capacity assessments.
Segment-level value and volume trajectories across the projection horizon reflect procedure volume elasticity to demographic aging, reimbursement rate sensitivity, and substitution threat intensity from tissue adhesives. Modeled dimensions span product type, material chemistry, application specialty, and end-user institutional category. CAGRs derived from logarithmic trend fitting to historical hospital purchasing data and ASC expansion forecasts, with ophthalmic procedure coding changes and FDA digital health policy evolution incorporated as scenario variables.
Regulatory timeline delays, raw material allocation shocks, and reimbursement coding revisions are the dominant revision risks for forecast stability. Forecasts reflect assumptions regarding certificate-of-need exemption persistence and biocompatibility testing standard evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Eye Allergy Treatment Market