
 Global Proliferative Vitreoretinopathy Market | 2026-2036
Global Proliferative Vitreoretinopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proliferative Vitreoretinopathy Market Intelligence
A divergence in R&D investment for novel biologics versus reliance on established surgical adjuncts is rotating competitive dynamics. Novartis AG leverages its extensive pipeline in ophthalmic biologics to capture value. In contrast, Regeneron Pharmaceuticals, Inc. competes through its specialized focus on anti-VEGF therapies. Bayer AG sustains its position through a formidable global distribution network for its established pharmacological agents.
Proliferative vitreoretinopathy is a fibrotic condition complicating retinal surgery, characterized by the formation of contractile cellular membranes on and under the retina. These membranes, composed of retinal pigment epithelial cells and glial cells, exert traction leading to recurrent retinal detachment. Pharmacological agents and biologics represent the most dynamic product segments, driven by research into anti-proliferative pathways. Ophthalmology hospitals remain the primary end-user channel, concentrating both surgical procedures and post-operative patient management.
Market access for new therapies is contingent on rigorous clinical trial data and subsequent approval from regulatory bodies like the US FDA and the EMA in Europe. In Japan, the PMDA sets stringent standards for the safety and efficacy of new pharmacological agents. Stakeholders must therefore track the evolving standard of care as adjunctive pharmacotherapies aim to reduce the need for repeat complex surgical interventions.
Market Dynamics
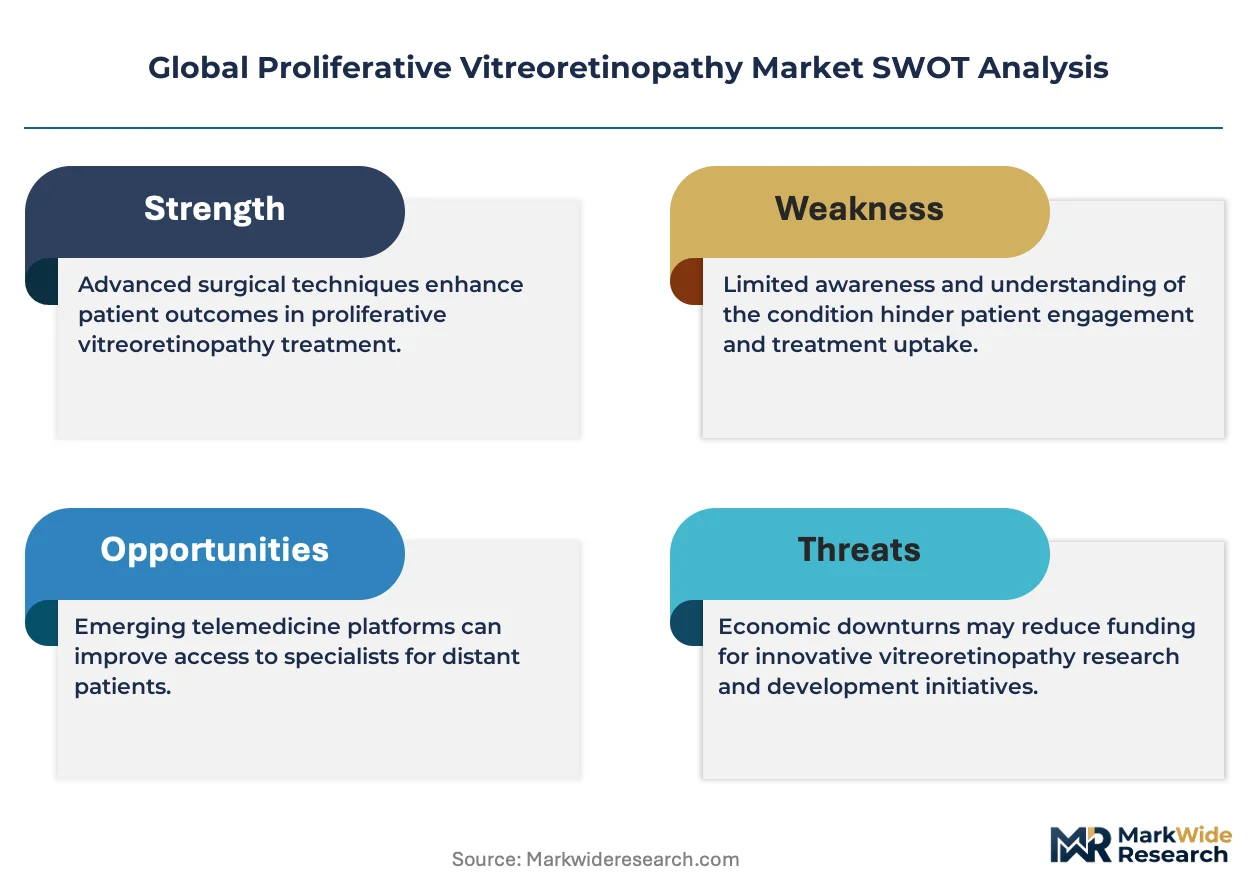
The divergence between R&D into novel biologics and reliance on established surgical adjuncts is the central force shaping the market. This dynamic influences investment priorities, clinical trial design, and the evolving standard of care for complex retinal detachments.
Growth Catalysts
- Advanced Biologics:Research into anti-proliferative and anti-inflammatory pathways is fueling the development of targeted pharmacological agents that inhibit membrane formation post-surgery.
- Diabetic Retinopathy Prevalence:A rising incidence of diabetic retinopathy, particularly in the United States, increases the pool of patients at high risk for developing PVR following vitrectomy procedures.
- Surgical Specialization:The concentration of complex retinal detachment repairs within dedicated ophthalmology hospitals improves patient outcomes and centralizes demand for advanced adjunctive therapies.
Market Restraints
- High Development Costs:The significant financial investment required for clinical trials of novel biologics presents a substantial barrier to entry for smaller pharmaceutical companies.
- Stringent Regulatory Hurdles:Navigating the rigorous approval processes of the US FDA, EMA, and Japan's PMDA creates long and uncertain development timelines for new therapies.
- Surgical Complexity:The technical difficulty and inherent risks of vitreoretinal surgery mean that PVR can recur even with the use of advanced adjunctive agents.
Strategic Opportunities
- Combination Therapies:Integrating new pharmacological agents with existing surgical techniques offers a pathway to improve efficacy and reduce the need for repeat interventions.
- Orphan Drug Designations:Securing regulatory incentives from bodies like the EMA or FDA for treating PVR as a rare condition can accelerate development and market access.
- Emerging Market Access:Expanding surgical training and infrastructure in regions like Brazil and India creates new channels for both surgical adjuncts and pharmacological treatments.
Industry Challenges
- Vitreoretinal Surgeon Scarcity:A global shortage of surgeons with the specialized training required for complex PVR cases limits procedural volume and access to care in many regions.
- Reimbursement Heterogeneity:Gaining consistent reimbursement for novel, high-cost adjunctive pharmacotherapies across different national and private payer systems is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proliferative Vitreoretinopathy Market |
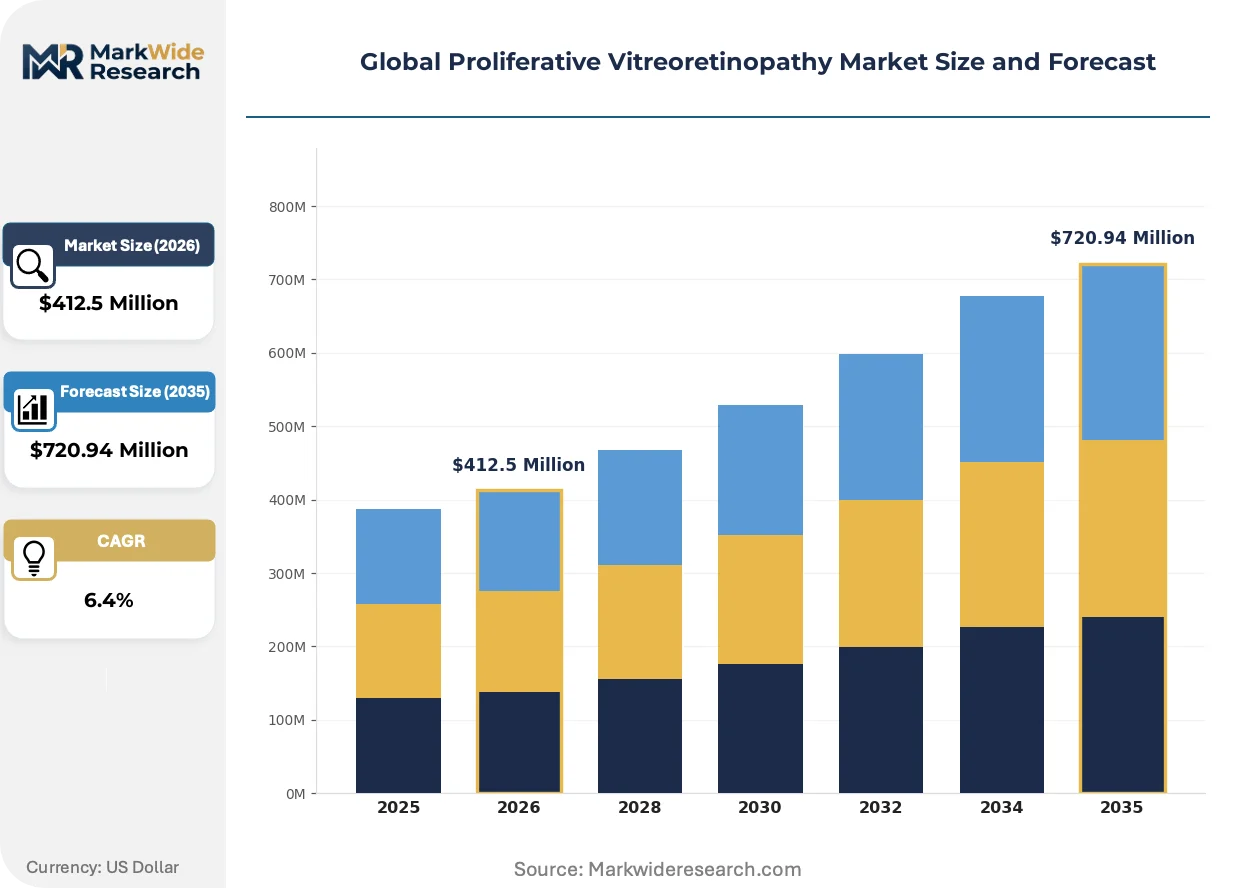
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacological Agents, Surgical Instruments, Biologics, Diagnostic Kits Application: Retinal Detachment Repair, Membrane Peeling, Vitrectomy, Silicone Oil Injection End User: Specialty Eye Clinics, Research Laboratories, Ambulatory Surgical Centers, Ophthalmology Hospitals Delivery Mode: Intravitreal Injection, Subretinal Injection, Topical Application, Systemic Therapy |
| Companies Covered | Novartis AG, Regeneron Pharmaceuticals, Inc., Genentech, Inc., Roche, Allergan plc, Bayer AG, Promedior Inc, RXi Pharmaceuticals Corp, Aldeyra Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proliferative Vitreoretinopathy Market Strategic Shifts & Innovations
A fundamental shift is underway from purely surgical management to a hybrid therapeutic model. This evolution is driven by a deeper understanding of fibrotic pathways, enabling more targeted pharmacological interventions.
Targeted anti-fibrotic biologics inhibit specific cellular signaling pathways involved in membrane formation. Specialized ophthalmology hospitals are the primary adopters for patients with high-risk PVR characteristics. This precision approach is fragmenting the monolithic treatment model, creating distinct protocols based on disease severity.
Regulatory frameworks like the FDA's Breakthrough Therapy designation and the EMA's PRIME scheme create expedited pathways for PVR therapies. These programs accelerate review timelines for drugs demonstrating substantial improvement over available care. The biologics segment is most affected, as these designations incentivize investment in novel agents.
Hospital purchasing is shifting toward evidence-based models, prioritizing outcomes data over historical surgeon preference. This procurement pattern disrupts the market for older surgical adjuncts, favoring new biologics with proven efficacy. The trend is most visible in health systems with strong technology assessment functions, like those in Germany and the United States.
Global Proliferative Vitreoretinopathy Market Segmentation
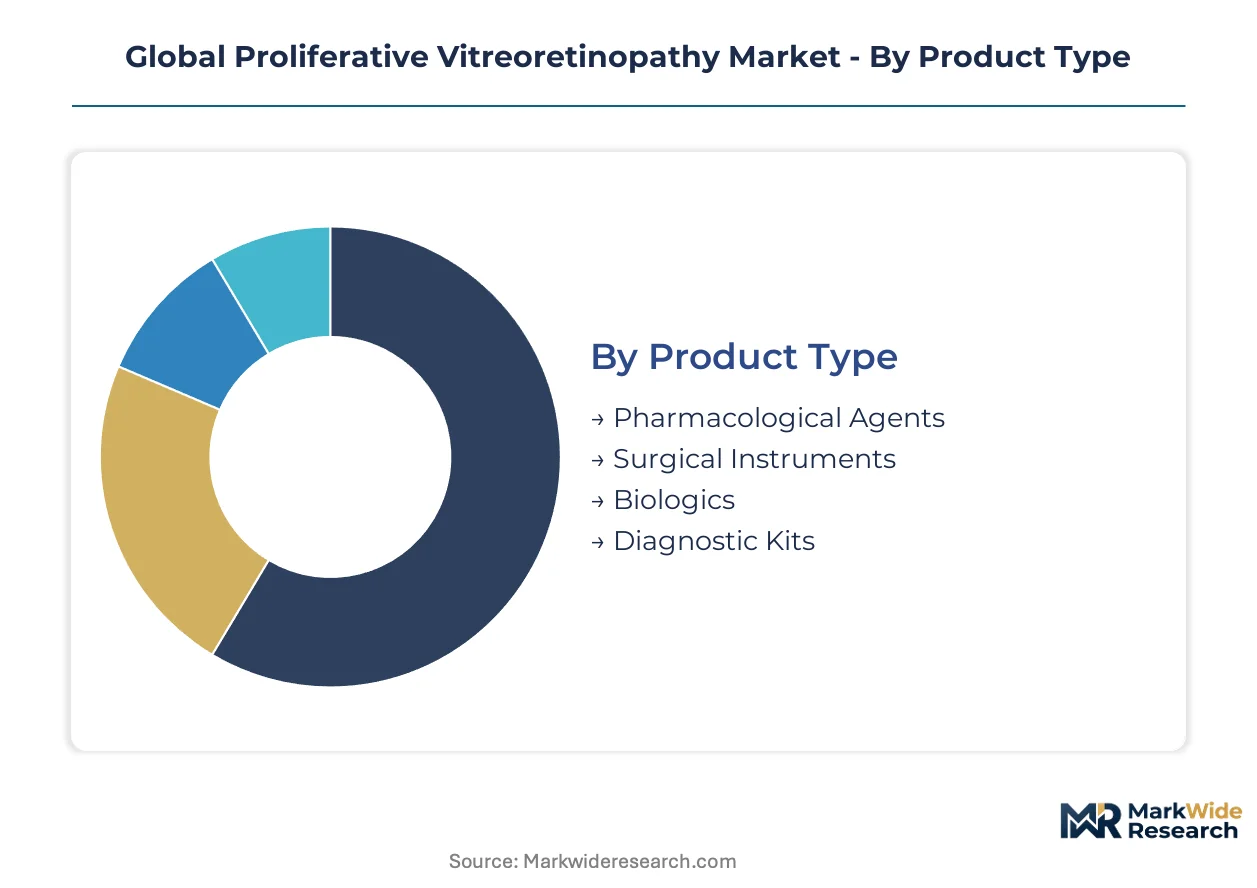
The Proliferative Vitreoretinopathy market's segmentation reveals the diverse therapeutic approaches and specialized care pathways for managing this complex retinal condition. Understanding these distinct segments helps stakeholders identify areas of high innovation and established procedural volumes. This granular view informs strategic investments in novel treatments and healthcare infrastructure.
Product Type:
The product type segments face substitution pressure from advanced biologics challenging traditional surgical adjuncts.
- Pharmacological Agents:These include anti-inflammatory steroids and anti-metabolites administered to inhibit cellular proliferation and membrane formation. Demand for these agents is concentrated in post-surgical management to prevent recurrence, particularly in high-risk patients.
- Biologics:Targeted biologics, such as anti-VEGF therapies or anti-fibrotic agents, interfere with specific cellular pathways involved in PVR development. Research into these novel compounds drives significant investment, aiming to reduce the need for repeat surgeries.
- Surgical Instruments:This segment encompasses a wide array of tools used in vitrectomy and membrane peeling procedures. Vitreoretinal surgeons rely on specialized instruments for precise removal of fibrotic membranes.
- Diagnostic Kits:These kits aid in the early detection and characterization of PVR, often involving molecular markers or imaging agents. Early diagnosis can guide more effective treatment strategies.
Pharmacological Agents anchors the volume base while Biologics gains share at the steepest rate.
Application:
Volume considerations heavily influence the application segments, as certain procedures are more frequently performed in PVR management.
- Retinal Detachment Repair:This primary application involves surgical reattachment of the retina, often complicated by PVR. The United States exhibits significant demand for these complex repairs due to advanced infrastructure.
- Vitrectomy:This surgical procedure removes the vitreous humor, often a prerequisite for addressing retinal detachment and PVR membranes. Ophthalmology hospitals are the primary sites for these intricate operations.
- Membrane Peeling:This delicate surgical technique involves removing fibrotic membranes from the retinal surface. Specialized vitreoretinal surgeons perform these procedures.
- Silicone Oil Injection:Silicone oil is injected into the vitreous cavity to provide internal tamponade, stabilizing the retina after complex repairs. This is a common adjunctive measure in severe PVR cases.
The demand for Retinal Detachment Repair is expanding most quickly, driven by the increasing incidence of diabetic retinopathy, while Vitrectomy maintains a stable base.
End User:
Specialization among end users dictates procurement patterns for PVR therapies and surgical equipment.
- Ophthalmology Hospitals:These institutions serve as primary referral centers for complex retinal detachments and PVR, concentrating advanced surgical procedures and post-operative care. Their procurement prioritizes evidence-based adjunctive therapies.
- Specialty Eye Clinics:These clinics often manage less severe PVR cases or provide follow-up care for patients who have undergone surgery. They focus on accessible and effective pharmacological management.
- Research Laboratories:Academic and industry research laboratories drive the discovery and development of new PVR treatments. These facilities require specialized reagents and diagnostic tools.
- Ambulatory Surgical Centers:These centers perform a limited scope of less complex vitreoretinal procedures. Their focus is on efficiency and patient convenience for suitable cases.
Procurement patterns among end users prioritize Ophthalmology Hospitals for complex cases, while Specialty Eye Clinics support routine procedures.
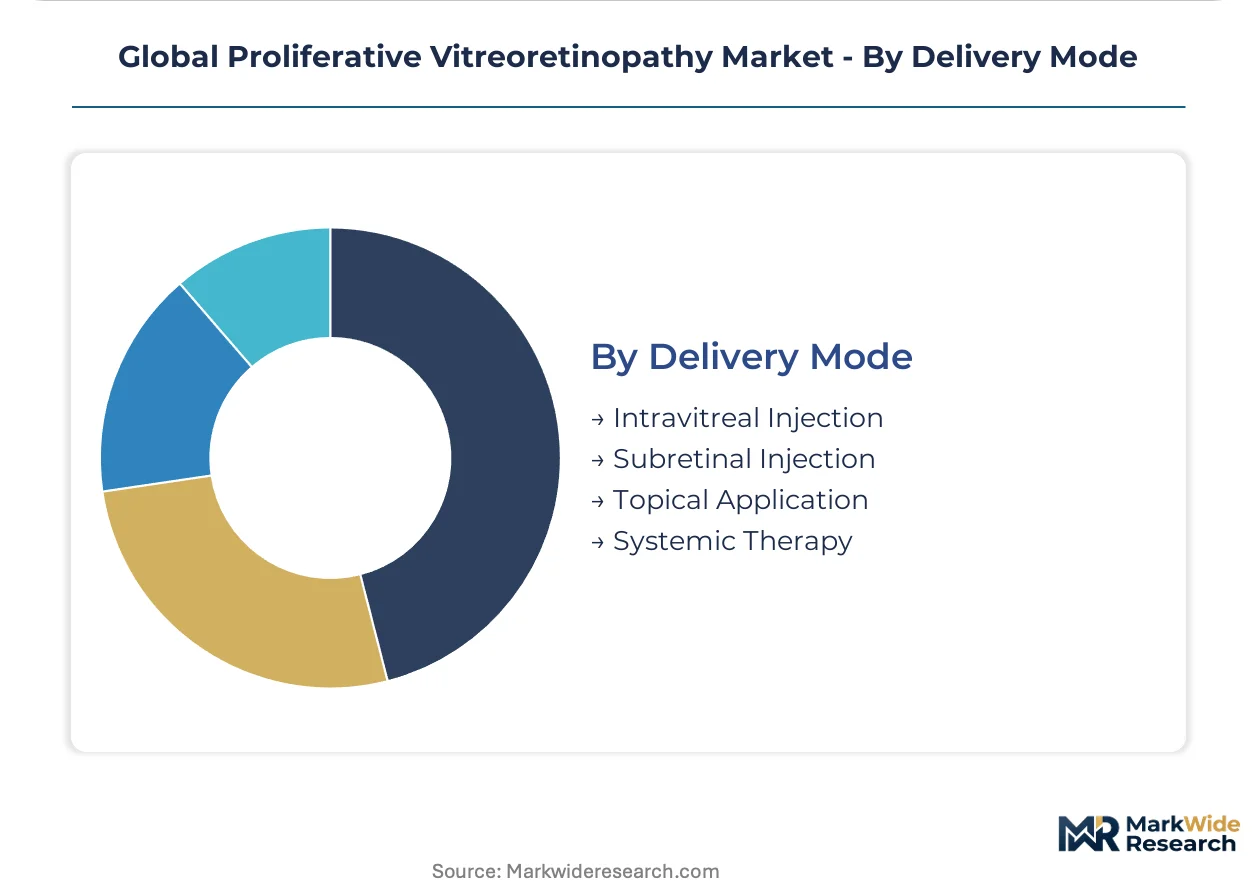
Delivery Mode:
Innovation in delivery modes focuses on maximizing therapeutic efficacy and patient convenience.
- Intravitreal Injection:This direct delivery method administers pharmacological agents and biologics into the vitreous cavity, ensuring high local drug concentrations. This mode is widely adopted for targeted anti-proliferative therapies.
- Subretinal Injection:A more invasive technique, this mode delivers therapies directly beneath the retina for highly localized action. Research into gene therapies for PVR often explores this precise delivery route.
- Topical Application:Eye drops or ointments deliver drugs to the ocular surface, suitable for managing inflammation or preventing infection. This method is generally less effective for deep-seated PVR.
- Systemic Therapy:Oral or intravenous medications provide a generalized drug distribution throughout the body. Systemic approaches are less common for PVR due to potential side effects and lower ocular bioavailability.
The efficacy of Intravitreal Injection drives its widespread adoption, while Subretinal Injection represents an area of targeted innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Proliferative Vitreoretinopathy market exhibits varied import-export dynamics for advanced therapies. Developed nations often drive the innovation and initial adoption of novel biologics and specialized surgical instruments. Emerging economies increasingly import these advanced solutions while simultaneously developing their own healthcare infrastructure for complex retinal care.
United States
High prevalence of diabetic retinopathy and advanced surgical infrastructure drive demand for PVR treatments. US FDA approval is critical for market access, ensuring rigorous safety and efficacy standards. Boston and San Francisco Bay Area biotechnology hubs concentrate research into novel PVR treatments.
Germany
Germany's strong healthcare system and focus on evidence-based procurement influence the adoption of new PVR therapies. EMA approval and national health technology assessments significantly impact market entry for pharmaceutical agents. Munich and Berlin are centers for ophthalmic research and specialized vitreoretinal surgery.
Japan
Japan's aging population and rapid adoption of advanced medical technology contribute to demand for PVR solutions. The PMDA sets stringent standards for new pharmacological agents and biologics, affecting development timelines. Tokyo and Osaka host leading ophthalmology clinics and pharmaceutical R&D facilities.
India
India presents a large patient pool and increasing incidence of diabetes, expanding the need for PVR management. The CDSCO regulates the approval of new drugs and medical devices within the country. Bengaluru and Hyderabad are emerging as medical technology and pharmaceutical manufacturing centers.
Brazil
Growing middle-class populations and increasing investment in specialized medical facilities characterize Brazil's PVR market. ANVISA oversees the registration and commercialization of new therapies, impacting market access for international players. São Paulo and Rio de Janeiro possess advanced ophthalmology hospitals performing complex retinal procedures.
Global Proliferative Vitreoretinopathy Market Key Industry Players
Concentration sits with established pharmaceutical giants and specialized biotech firms in the Proliferative Vitreoretinopathy market. The market exhibits a tiered structure, with a few large players dominating the biologics segment. Strategic archetypes include diversified pharmaceutical conglomerates, focused anti-VEGF specialists, and surgical instrument manufacturers. Portfolio diversification and strategic partnerships are dominant competitive moves among these entities.
Within the diversified pharmaceutical conglomerate tier, Swiss-based Novartis AG represents a broad approach to ophthalmic biologics. US-based Regeneron Pharmaceuticals, Inc. exemplifies a specialized focus on anti-VEGF therapies. German multinational Bayer AG maintains its position through established pharmacological agents and a formidable global distribution network.
| Leading Market Players |
|---|
| Novartis AG |
| Regeneron Pharmaceuticals, Inc. |
| Genentech, Inc. |
| Roche |
| Allergan plc |
| Bayer AG |
| Promedior Inc |
| RXi Pharmaceuticals Corp |
| Aldeyra Therapeutics |
| Others |
Cost & Logistics Intelligence
Contract-based long-term offtake agreements for specialized biologics lock in supply access and provide price visibility for complex PVR treatments. This structure stabilizes procurement for high-value therapies amidst evolving market dynamics.
Pricing Analysis
Ophthalmology hospitals anchor the value-based pricing structure for novel PVR therapies. Price differentiation stems from demonstrated clinical efficacy and the specific regulatory approvals from bodies like the US FDA or EMA. Pricing pressure stems from the heterogeneity of reimbursement policies across national systems. Specialty eye clinics exhibit higher price sensitivity for adjunctive pharmacological agents compared to major referral hospitals for complex surgical interventions.
Supply Chain Analysis
Specialized cold chain logistics costs for biologics impact the inbound supply chain for PVR treatments. Supply concentration for advanced pharmacological agents and biologics resides primarily in the United States, Germany, and Japan. Raw material dependencies include highly purified chemical precursors and specialized sterile packaging components. Single-source vulnerability for certain rare active pharmaceutical ingredients represents a structural supply chain risk. Distribution runs through a network of specialized pharmaceutical distributors and direct-to-hospital channels for high-value products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Proliferative Vitreoretinopathy market is experiencing a buyer-power shift as ophthalmology hospitals consolidate procurement, influencing therapeutic development and market access strategies.
For Market Incumbents: Shield existing market share by accelerating clinical trials for next-generation anti-fibrotic agents. Invest in combination therapies that integrate with established surgical techniques to counter emerging targeted biologics. Secure expedited regulatory designations, such as the FDA's Breakthrough Therapy, to maintain a competitive edge. Diversify pipelines to address a broader spectrum of PVR severity, mitigating margin pressure from generic competition for older agents.
For New Entrants and Emerging Players: Lead with innovative delivery mechanisms for existing pharmacological agents to improve patient adherence and outcomes. Target niche patient populations with specific genetic markers for PVR, offering highly specialized solutions. Focus on cost-effectiveness and improved patient convenience to penetrate specialty eye clinics for less severe PVR cases. Develop go-to-market strategies emphasizing superior safety profiles or reduced treatment burden.
For Investors and Strategic Acquirers: Early-stage biotech firms specializing in gene therapy or novel anti-inflammatory pathways offer long-term viability in the PVR market. Acquisition targets should possess strong intellectual property in targeted biologics or advanced subretinal delivery technologies. Positive Phase 2 clinical trial data for novel anti-fibrotic compounds serves as a critical signal to watch for inflection. Invest in companies addressing the significant unmet medical need for recurrent PVR cases.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expedites regulatory approval for novel biologics addressing unmet PVR needs. |
| Orphan Drug Designation | Provides regulatory incentives and market exclusivity for PVR therapies. |
| Strategic Partnerships | Accesses specialized R&D capabilities and expands global distribution networks. |
| Manufacturing Scale-Up | Ensures consistent supply of complex biologics to meet rising demand. |
| Digital Health Integration | Enhances patient monitoring and post-operative management in ophthalmology hospitals. |
Research Approach
A spread of perspectives from vitreoretinal surgeons, pharmaceutical R&D executives, hospital procurement managers, and regulatory affairs specialists converged on the working assumptions for the PVR market. Primary interviews were combined with secondary validation from US FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed ophthalmology journals. Triangulation from both bottom-up and top-down approaches ensured data robustness and market sizing accuracy.
Product type, application, end user, delivery mode, and regional regulatory frameworks formed the core segmentation dimensions modeled. The analytical framework projected market values across the analysis window. Compound annual growth rates were derived from historical data and projected adoption curves for new therapies. Diabetic retinopathy prevalence rates and vitreoretinal surgical procedure volumes served as key forecast inputs.
Forecasts assume regulatory continuity in US FDA, EMA, and Japan's PMDA regimes; material policy shifts would require re-modeling. Unexpected clinical trial failures or significant changes in reimbursement policies represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Uveitis Treatment Market