
 Retinal Drugs Market | 2026-2036
Retinal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Drugs Market Outlook
Modular combination therapy packaging is expanding buyer choice in retinal care, as physicians sequence anti-VEGF and corticosteroid agents within single treatment plans. Regeneron Pharmaceuticals leverages its Eylea franchise to anchor geographic dominance in North American retinal practices. Bayer AG competes through sustained manufacturing scale across European and Asian distribution networks. Novartis AG differentiates via technology leadership in sustained-release delivery platforms.
Retinal drugs comprise pharmacologic agents engineered to modulate vascular endothelial growth factor signaling, inflammatory cytokine cascades, or retinal pigment epithelium metabolism, typically formulated as sterile intravitreal solutions with osmolality calibrated to vitreous humor parameters. These therapeutics halt neovascularization and edema progression in sight-threatening posterior segment diseases. Anti-VEGF agents dominate current prescription volumes due to established efficacy in age-related macular degeneration, though corticosteroid demand is accelerating fastest among diabetic macular edema cases where VEGF inhibition alone proves insufficient. Ophthalmology centers capture concentrated margin pools by consolidating injection services and imaging diagnostics under single-site care models.
The FDA and EMA govern biologic licensing and post-market surveillance for intravitreal therapies, while the EU MDR tightens clinical evidence requirements for legacy device-drug combinations. HIPAA and GDPR frameworks constrain real-world data collection from retinal imaging databases, shaping how manufacturers access treatment outcome evidence. Stakeholders must monitor how CMS reimbursement thresholds for biosimilar anti-VEGF agents reshape physician prescribing economics and site-of-care decisions.
Market Dynamics
Intravitreal injection protocols are consolidating treatment delivery around anti-VEGF biologics, with Medicare reimbursement thresholds compressing site-of-care economics and forcing ophthalmology centers to merge imaging diagnostics with injection services under single-roof models.
Growth Catalysts
- FDA Accelerated Approval Pathway:The breakthrough therapy designation compresses development timelines for novel biologics targeting wet age-related macular degeneration, enabling faster patient access to sustained-release formulations.
- Medicare Office-Based Reimbursement:Sustained payment policies for retinal procedures in the United States anchor treatment volumes and incentivize physician investment in intravitreal injection infrastructure.
- Diabetic Macular Edema Expansion:Rising prevalence of diabetes-related retinal complications is pulling corticosteroid demand upward where VEGF inhibition alone proves insufficient.
Market Restraints
- Biologic Manufacturing Concentration:Production of sterile intravitreal solutions depends on a limited network of contract manufacturing organizations with validated aseptic filling lines, creating supply vulnerability.
- EU MDR Compliance Burden:The tightened clinical evidence requirements for legacy device-drug combinations force costly post-market surveillance upgrades on sustained-delivery platform manufacturers.
- Real-World Data Access Friction:HIPAA and GDPR frameworks constrain retinal imaging database mining, limiting manufacturers' ability to generate treatment outcome evidence for payer negotiations.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan's aging demographic and South Korea's diabetic population growth create demand pockets where anti-VEGF therapy adoption lags Western benchmarks.
- Sustained-Release Technology Convergence:Combination of biodegradable polymer matrices with anti-VEGF biologics enables dosing interval extension from monthly to quarterly or semi-annual administration.
- IRA Medicare Price Negotiation Entry:The Inflation Reduction Act's biologic pricing provisions create entry pathways for biosimilar anti-VEGF agents through established reimbursement benchmarks.
Industry Challenges
- Vitreoretinal Surgeon Training Pipeline:The specialized skill set required for safe intravitreal injection delivery faces supply constraints as fellowship programs fail to match patient volume growth.
- Cold Chain Integrity Maintenance:Biologic stability requirements demand uninterrupted temperature-controlled distribution from manufacturing through point-of-care, elevating logistics complexity and capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Drugs Market |
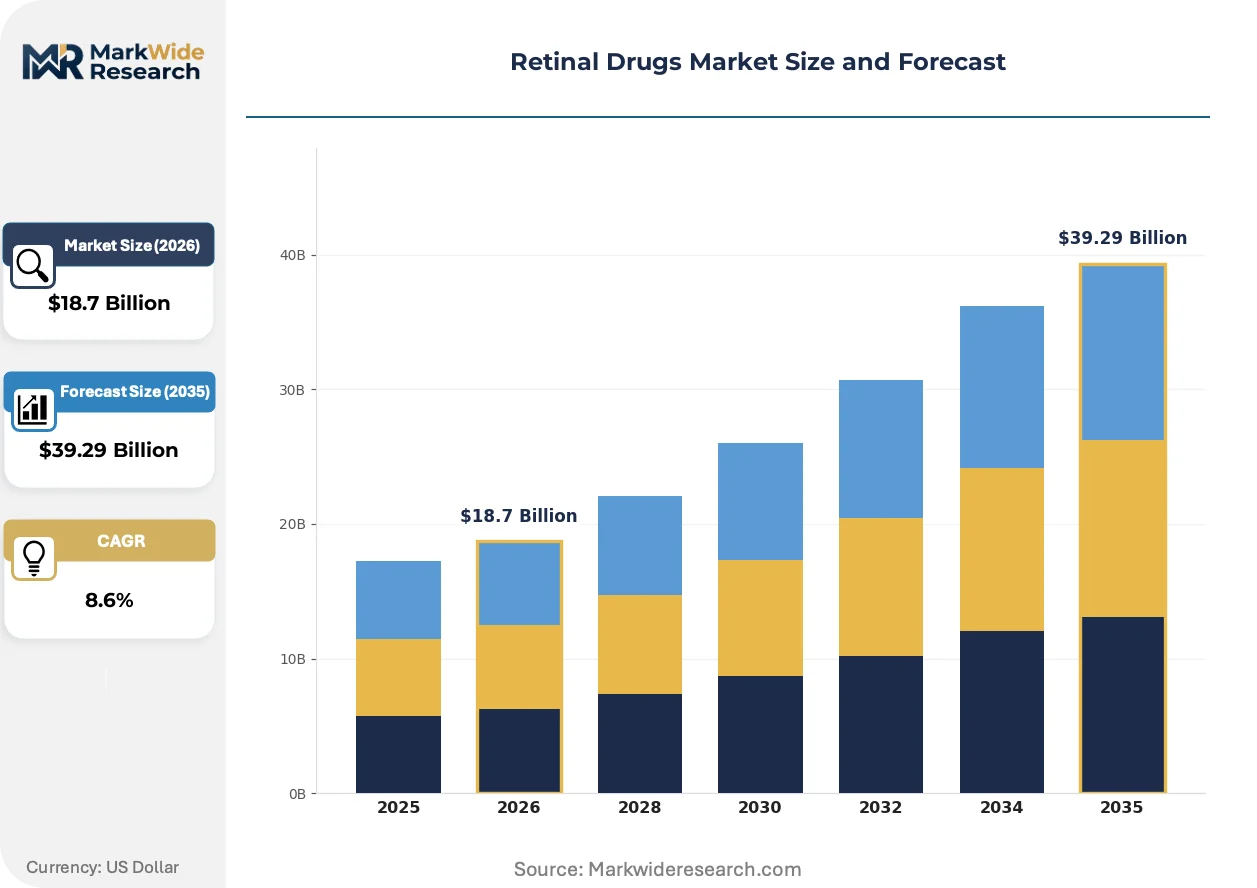
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Retinoids, Laser Treatments Application: Age-Related Macular Degeneration, Diabetic Retinopathy, Retinal Vein Occlusion, Macular Edema End User: Hospitals, Clinics, Research Institutes, Ophthalmology Centers Delivery Mode: Intravitreal Injections, Systemic Administration, Topical Solutions, Laser Intervention |
| Companies Covered | AbbVie Inc., Pfizer Inc., Regeneron Pharmaceuticals Inc., Apellis Pharmaceuticals Inc., Santen Pharmaceutical Co. Ltd., F. Hoffmann-La Roche Ltd, Bayer AG, Genentech Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Drugs Market Strategic Shifts
Retinal therapeutics are pivoting from acute intervention toward chronic disease management architectures, with sustained-release formulations and diagnostic-treatment integration compressing patient visit burdens while extending therapeutic durability.
Gene therapy vectors targeting vascular endothelial growth factor pathway modulation are converging with established anti-VEGF biologic protocols, enabling retinal specialists to sequence treatments across longer intervals. Academic medical centers in the United States and Germany are piloting these combination regimens for inherited retinal dystrophies. This convergence is compressing the traditional monthly injection cycle into semi-annual or annual intervention windows, reshaping practice revenue models and patient compliance economics.
The EU Medical Device Regulation's tightened clinical evidence requirements for drug-device combinations is forcing manufacturers to generate new prospective data on legacy sustained-delivery implants. European ophthalmology centers face documentation burdens for existing port delivery systems already in commercial use. German and French regulatory authorities are requiring post-market clinical follow-up studies that extend approval timelines and elevate compliance costs for combination product developers.
Hospital-based ophthalmology departments are unbundling diagnostic imaging from injection services, creating standalone retinal imaging centers that feed treatment decisions to distributed injection sites. This channel fragmentation is displacing the traditional comprehensive retina practice model in the United States. Medicare site-of-care differentials are accelerating this split, with freestanding ambulatory surgical centers capturing margin from hospital outpatient departments through procedure consolidation.
Retinal Drugs Market Segmentation
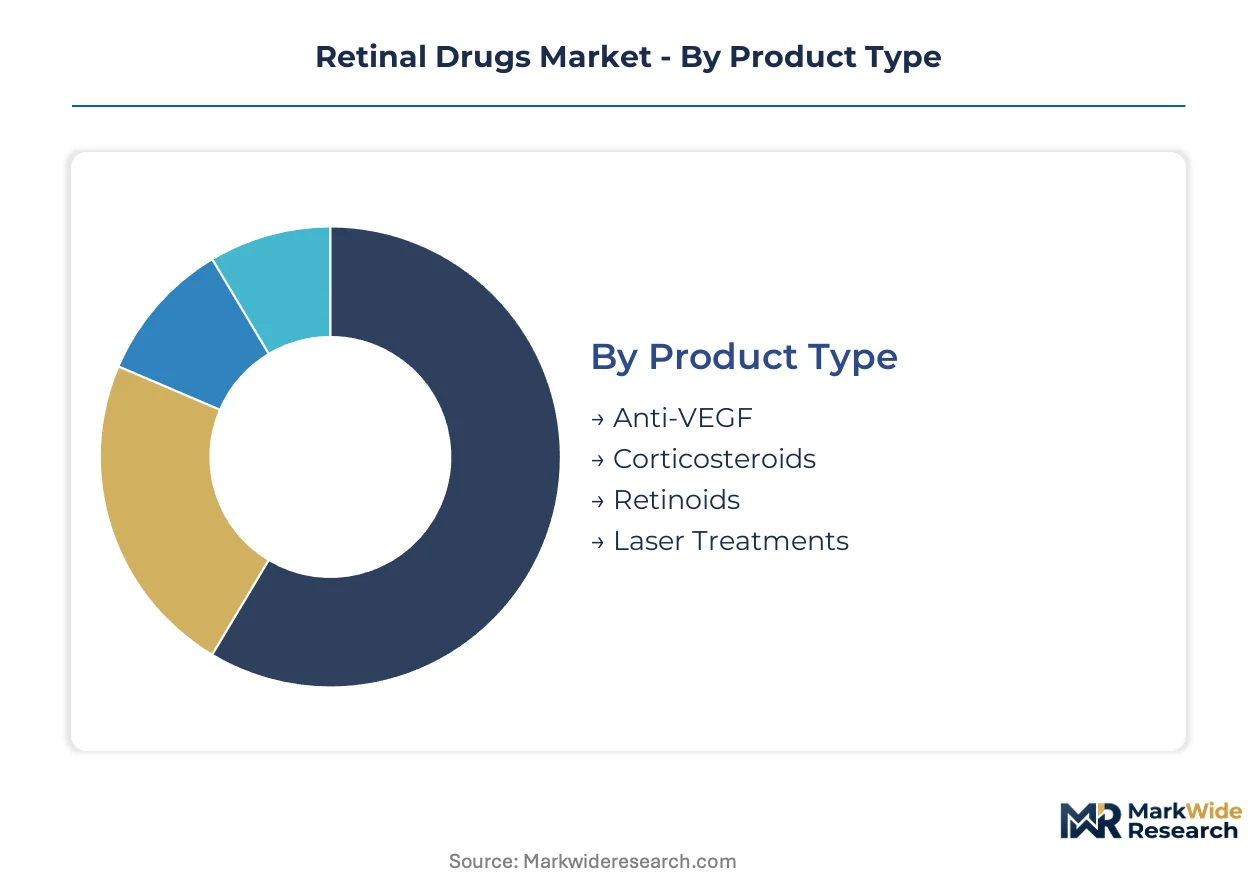
Retinal drug segmentation reveals distinct upgrade cycles across therapeutic modalities, with injection frequency and formulation durability driving physician switching behavior between product classes. Treatment protocols are fragmenting by disease severity and comorbidity profile, creating parallel demand tracks that manufacturers must address through portfolio breadth rather than single-product dominance.
Product Type:
Upgrade cycles in retinal therapeutics center on dosing interval extension and side-effect profile improvements, with physicians sequencing patients through multiple drug classes before settling on long-term maintenance regimens.
- Anti-VEGF:Engineered monoclonal antibodies and fusion proteins that bind vascular endothelial growth factor isoforms to inhibit choroidal neovascularization. Demand concentrates in United States Medicare-funded practices where monthly injection reimbursement sustains high treatment volumes, though physician burnout from injection frequency is accelerating switches to sustained-release alternatives.
- Corticosteroids:Synthetic glucocorticoid formulations delivered via intravitreal implant or injection to suppress inflammatory cytokine cascades in refractory macular edema. United States retinal specialists are expanding corticosteroid use fastest among diabetic patient subpopulations where anti-VEGF monotherapy underperforms, pulling demand upward in the Southeast and Midwest diabetes belts.
- Retinoids:Vitamin A derivatives modulating retinal pigment epithelium metabolism and photoreceptor renewal cycles.
- Laser Treatments:Photocoagulation and photodynamic protocols for focal retinal pathology.
Anti-VEGF sits at the top of the volume ranking, with corticosteroids climbing the fastest.
Application:
Cost tier stratification in retinal disease management separates acute neovascular intervention from chronic edema control, with reimbursement differentials shaping site-of-care decisions across patient populations.
- Age-Related Macular Degeneration:Neovascular and atrophic subtypes driving anti-VEGF prescription volumes in Medicare-eligible populations. United States retinal practices in Florida and Arizona retirement corridors capture concentrated patient flows, with wet AMD injection services generating procedure economics that sustain standalone ophthalmology center viability.
- Diabetic Retinopathy:Progressive microvascular damage requiring escalating intervention intensity from pan-retinal photocoagulation to intravitreal pharmacotherapy. United States endocrinology-retina co-management models in Texas and California are compressing time-to-treatment for proliferative cases, expanding the addressable patient pool beyond traditional ophthalmology referral pathways.
- Retinal Vein Occlusion:Macular edema and neovascular complications following branch or central vessel occlusion.
- Macular Edema:Fluid accumulation in central retina from multiple etiologies requiring anti-inflammatory or anti-permeability therapy.
Age-Related Macular Degeneration commands the largest patient population, with Diabetic Retinopathy expanding most quickly as diabetes prevalence climbs.
End User:
Customer type fragmentation in retinal care delivery splits high-acuity surgical intervention from chronic disease monitoring, with reimbursement site-of-care differentials determining where injection services concentrate geographically.
- Hospitals:Academic medical centers and community hospital systems integrating retinal surgery with comprehensive ophthalmology departments. United States hospital outpatient departments in urban corridors maintain captive referral networks for complex surgical cases, though Medicare site-of-care payment differentials are eroding their share of routine anti-VEGF injections.
- Ophthalmology Centers:Dedicated retina practices consolidating imaging diagnostics with injection services under single-roof models. United States freestanding centers in suburban markets are capturing volume from hospital-based competitors through procedure consolidation and faster appointment access, particularly in Sun Belt retirement destinations.
- Clinics:General ophthalmology and optometry practices screening for retinal disease.
- Research Institutes:Academic and commercial trial sites investigating novel therapeutic modalities.
Ophthalmology Centers are gaining share fastest from hospital-based delivery, with Clinics serving as the primary screening entry point.
Delivery Mode:
Supply concentration in aseptic manufacturing and specialized surgical training is concentrating intravitreal injection capacity among validated provider networks, while alternative delivery routes remain niche.
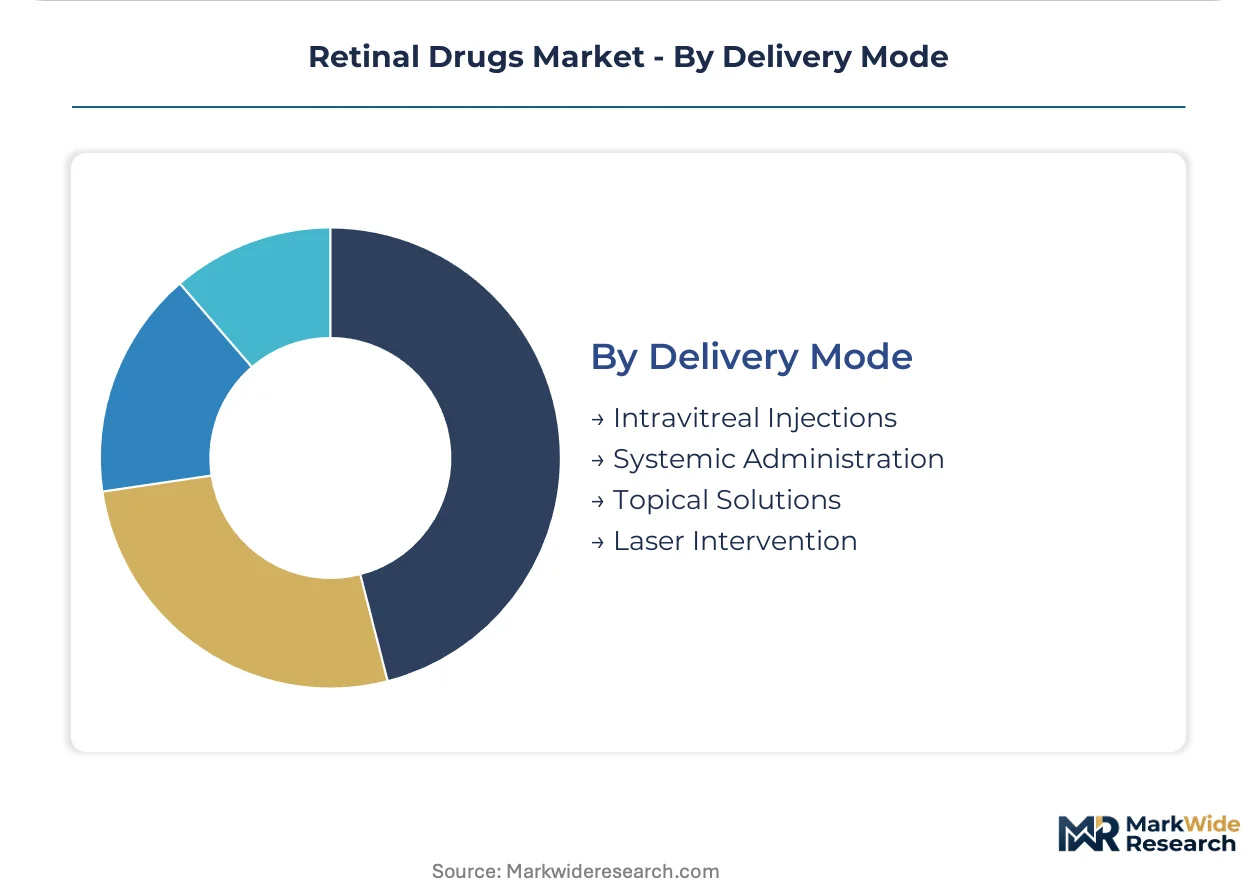
- Intravitreal Injections:Direct drug delivery into vitreous cavity via pars plana needle insertion requiring sterile compounding and surgical precision. United States retina specialists in metropolitan markets dominate procedure volume, with fellowship-trained surgeon supply constraints limiting expansion into underserved rural and exurban territories.
- Systemic Administration:Oral or intravenous drug delivery for select retinal vascular indications with posterior segment penetration.
- Topical Solutions:Anterior segment formulations with limited posterior penetration for surface pathology.
- Laser Intervention:Photocoagulation and photodynamic therapy requiring specialized equipment and operator certification.
Intravitreal Injections dominate procedure economics, with Laser Intervention retaining niche utility for specific vascular indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The retinal drugs industry traces its commercial roots to United States academic medical centers that pioneered anti-VEGF intravitreal injection protocols during the early 2000s. This foundation established Medicare reimbursement frameworks that now sustain treatment volumes across multiple continents. Geographic expansion follows aging demographic corridors and diabetic population concentrations.
United States
Florida and Arizona retirement corridors generate concentrated wet AMD patient flows that sustain standalone ophthalmology center economics. The Inflation Reduction Act's Medicare price negotiation provisions reshape biosimilar entry pathways for anti-VEGF agents. Retina specialists in metropolitan Sun Belt markets dominate procedure volume, though fellowship-trained surgeon supply constraints limit rural expansion.
Germany
Academic medical centers in Heidelberg and Berlin pilot gene therapy vector sequencing alongside established biologic protocols for inherited retinal dystrophies. The EU Medical Device Regulation forces costly post-market clinical follow-up studies on legacy sustained-delivery implant manufacturers. Bavarian and Baden-Württemberg ophthalmology clusters face documentation burdens for existing port delivery systems already in commercial use.
Japan
Aging demographics and diabetic population growth create demand pockets where anti-VEGF therapy adoption lags Western benchmarks. The Pharmaceuticals and Medical Devices Agency governs biologic licensing timelines for novel sustained-release formulations. Tokyo and Osaka metropolitan retina practices concentrate injection capacity, with PMDA accelerated review pathways compressing development-to-commercialization windows.
India
Rising diabetes prevalence expands the addressable patient pool for corticosteroid interventions where VEGF inhibition alone proves insufficient. The Central Drugs Standard Control Organization regulates intravitreal biologic import and manufacturing licensing. Maharashtra and Karnataka ophthalmology networks scale screening-to-treatment pathways, though cold chain infrastructure gaps constrain biologic distribution beyond tier-one cities.
United Kingdom
National Health Service cost-effectiveness thresholds compress prescribing economics for premium anti-VEGF agents against biosimilar alternatives. The Medicines and Healthcare products Regulatory Agency governs post-Brexit biologic licensing divergence from EMA frameworks. London and Southeast England retina centers consolidate imaging diagnostics with injection services, while Midlands and North England face specialist access disparities.
Retinal Drugs Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation durability and dosing interval extension capabilities. The competitive structure concentrates around biologic originators with established anti-VEGF franchises and sustained-release platform specialists seeking interval expansion. Three archetypes dominate: large-cap pharmaceutical conglomerates with ophthalmology divisions, mid-cap biotechnology firms with single-product focus, and emerging gene therapy developers. Consolidation activity centers on sustained-delivery technology acquisitions and geographic distribution partnerships.
Among United States-based biopharmaceutical developers, Regeneron Pharmaceuticals and Apellis Pharmaceuticals occupy positions within the innovation-driven tier, while Swiss-domiciled Novartis AG and Germany's Bayer AG exemplify geographic diversification strategies across European and Asian distribution networks. These entities represent contrasting archetypes in portfolio breadth versus therapeutic focus.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Regeneron Pharmaceuticals Inc. |
| Apellis Pharmaceuticals Inc. |
| Santen Pharmaceutical Co. Ltd. |
| F. Hoffmann-La Roche Ltd |
| Bayer AG |
| Genentech Inc. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Sterile aseptic filling capacity costs flow from contract manufacturing organization validation investments through anti-VEGF biologic pricing tiers, with United States Medicare reimbursement benchmarks anchoring physician site-of-care economics while EU MDR compliance expenditures compress margin structures for sustained-release platform developers.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilar alternatives, and corticosteroid adjuncts separates reimbursement-driven United States practices from cost-constrained European hospital systems and out-of-pocket Asian markets. Price differentiation hinges on dosing interval extension capabilities and FDA breakthrough therapy designation status. Cost compression in the biosimilar tier is intensifying because IRA Medicare price negotiation provisions establish transparent reimbursement ceilings. United States retina specialists exhibit lowest price sensitivity due to procedure-based revenue models, while Indian ophthalmology networks face acute affordability constraints.
Supply Chain Analysis
Dual-sourcing requirements for sterile intravitreal solutions mandate qualified backup contract manufacturing organizations, with production gravity centering on United States, Germany, and Singapore facilities possessing validated isolator filling lines. Biologic active pharmaceutical ingredients draw from Swiss and Irish fermentation capacity, while biodegradable polymer matrices for sustained-release implants source from Massachusetts and Bavarian specialty chemical networks. Single-source vulnerability concentrates around aseptic filling line validation timelines. Cold chain distribution runs through temperature-controlled logistics partnerships from manufacturing through hospital pharmacy and ophthalmology center point-of-care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retinal drugs market functions as a stable compounder anchored by irreversible demographic aging and diabetes prevalence trajectories that sustain chronic disease management demand across decades-long patient lifecycles.
For Market Incumbents: Acquire sustained-release delivery platform specialists to extend dosing intervals beyond quarterly administration. Gene therapy vector developers represent critical capability gaps threatening long-term anti-VEGF franchise erosion. Backward integration into sterile aseptic filling capacity insulates against contract manufacturing organization supply vulnerability.
For New Entrants and Emerging Players: Ophthalmology center networks in Japan's aging metropolitan corridors offer partnership pathways for biosimilar anti-VEGF agents facing Western benchmark adoption gaps. Diabetic macular edema corticosteroid combinations in India's tier-two cities present accessible white-space expansion. Co-development agreements with established retina specialists accelerate clinical validation credibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where sustained-release technology convergence outpaces standalone biologic development economics. Five-to-ten-year viability favors platform-integrated developers over single-product biotechnology firms. Watch FDA accelerated approval pathway utilization rates as inflection indicators for development timeline compression value.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Release Formulation Development | Quarterly-to-annual dosing intervals reshape practice economics and patient compliance. |
| EU MDR Compliance Investment | Post-market clinical follow-up studies secure legacy port delivery system market access. |
| Biosimilar Anti-VEGF Entry Strategy | IRA Medicare price negotiation benchmarks create transparent reimbursement pathways. |
| Gene Therapy Vector Sequencing | Academic medical center pilots in Heidelberg and Berlin validate combination regimens. |
| Cold Chain Infrastructure Partnership | Uninterrupted temperature control from manufacturing through point-of-care ensures biologic stability. |
Study Parameters
Direct dialogue with retinal specialists, formulary directors at United States hospital systems, regulatory affairs leads at EMA and PMDA, and contract manufacturing organization executives grounded qualitative findings. Secondary validation drew from FDA biologic licensing application filings, ClinicalTrials.gov protocol registries, CMS Medicare reimbursement databases, and EU MDR technical documentation requirements. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated market estimates.
Segment-level value outputs across anti-VEGF, corticosteroid, and emerging gene therapy modalities reflect patient population epidemiology, treatment penetration assumptions, and pricing tier dynamics throughout the forecast period. Analytical frameworks incorporated dosing frequency evolution, site-of-care migration patterns, and biosimilar adoption curves. CAGRs derived from longitudinal procedure volume analysis and reimbursement policy trajectory modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to vitreoretinal surgeon training pipeline constraints and gene therapy regulatory pathway maturation. Deviation in sustained-release formulation clinical trial readouts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Ocular Excipients Market