
 Optometry/Eye Exam Equipment Market | 2026-2036
Optometry/Eye Exam Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Optometry/Eye Exam Equipment Market Intelligence
The influence of large optical retailers is consolidating purchasing power for standard diagnostic tools like autorefractors and lensmeters. In the high-end diagnostic space, Carl Zeiss Meditec AG leverages its expertise in advanced optics and imaging. Topcon Corporation specializes in integrated eye care solutions, connecting diagnostic devices through software platforms. EssilorLuxottica dominates the retail channel, influencing equipment choices through its extensive network.
Optometry and eye exam equipment encompasses a range of diagnostic instruments used to assess vision, measure refractive errors, and detect ocular diseases. These devices often incorporate precise optical systems, with some, like OCT scanners, achieving axial resolutions below 10 micrometers to visualize retinal layers. Demand for advanced technology like Optical Coherence Tomography is growing for applications in retinal disease diagnosis. Conversely, the market for basic retinoscopes is mature, serving specific needs in optometry clinics.
Market access is governed by medical device regulations, including the FDA's 510(k) process in the United States and the EU's Medical Device Regulation (MDR). Approvals from China's NMPA and Japan's PMDA are critical for commercial entry, setting standards for clinical data and safety. Navigating the varied requirements for software-as-a-medical-device across these jurisdictions is a key strategic consideration for manufacturers.
Market Dynamics
The central force shaping the optometry equipment market is the push toward preventative, data-intensive diagnostics. This is driven by the convergence of AI-enhanced imaging technologies and demographic pressures from aging populations and expanding healthcare access in major economies.
Growth Catalysts
- Advanced Imaging Technology:The integration of artificial intelligence with Optical Coherence Tomography (OCT) improves diagnostic accuracy and workflow efficiency in ophthalmology centers, stimulating replacement and upgrade cycles for retinal disease management.
- Demographic Shifts:An aging global population and rising chronic disease prevalence, particularly in countries like China with expanding healthcare infrastructure, increase the patient base requiring regular and sophisticated eye examinations.
- Preventative Health Policies:Government and public health initiatives promoting routine eye screenings for conditions like diabetic retinopathy and glaucoma encourage investment in diagnostic equipment by clinics and hospitals to meet screening mandates.
Market Restraints
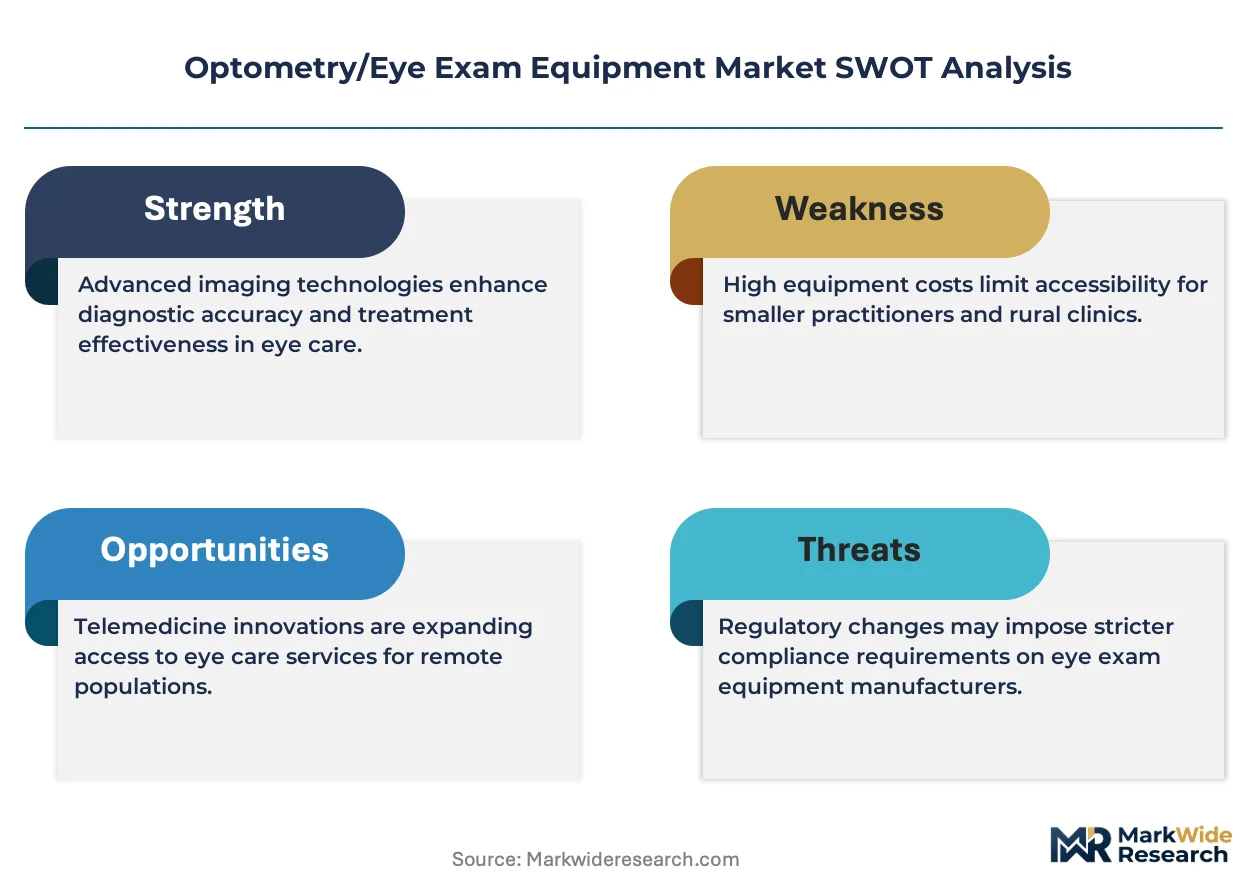
- High Capital Investment:The significant upfront cost of advanced diagnostic systems, such as high-resolution OCT scanners and integrated phoropters, presents a substantial barrier to adoption for smaller independent optometry practices and clinics in emerging markets.
- Regulatory Hurdles:Navigating the stringent and lengthy medical device approval pathways, including the FDA's 510(k) process and the EU's Medical Device Regulation (MDR), delays product launches and increases development costs for manufacturers.
- Mature Product Segments:The market for basic diagnostic tools like manual retinoscopes and lensmeters is saturated, characterized by intense price competition from low-cost manufacturers and limited technological innovation, which constrains revenue growth in this segment.
Strategic Opportunities
- Tele-Optometry Expansion:The convergence of portable, handheld diagnostic devices with telehealth software platforms creates an opportunity to deliver eye care services to remote and underserved populations, bypassing traditional clinic infrastructure.
- New Diagnostic Applications:Expanding the clinical applications of existing technologies, such as using OCT for detailed anterior segment analysis or glaucoma progression monitoring, opens new revenue streams and increases the value proposition of the equipment.
- Emerging Market Penetration:Developing and marketing mid-tier, robust equipment tailored to the economic and infrastructure realities of underpenetrated regions in Latin America and Southeast Asia presents a significant volume growth opportunity.
Industry Challenges
- Specialized Skills Shortage:A lack of trained technicians and optometrists proficient in operating complex diagnostic instruments and interpreting the large datasets they produce can limit the effective utilization of advanced equipment.
- System Interoperability:Integrating new diagnostic devices with disparate legacy Electronic Health Record (EHR) and Picture Archiving and Communication Systems (PACS) in hospitals remains a significant technical and logistical challenge for vendors.
- Software Regulation Complexity:Manufacturers face difficulties in navigating the varied and evolving global regulations for software-as-a-medical-device (SaMD), particularly concerning AI algorithms, across key authorities like the FDA, EU (MDR), and China's NMPA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optometry/Eye Exam Equipment Market |
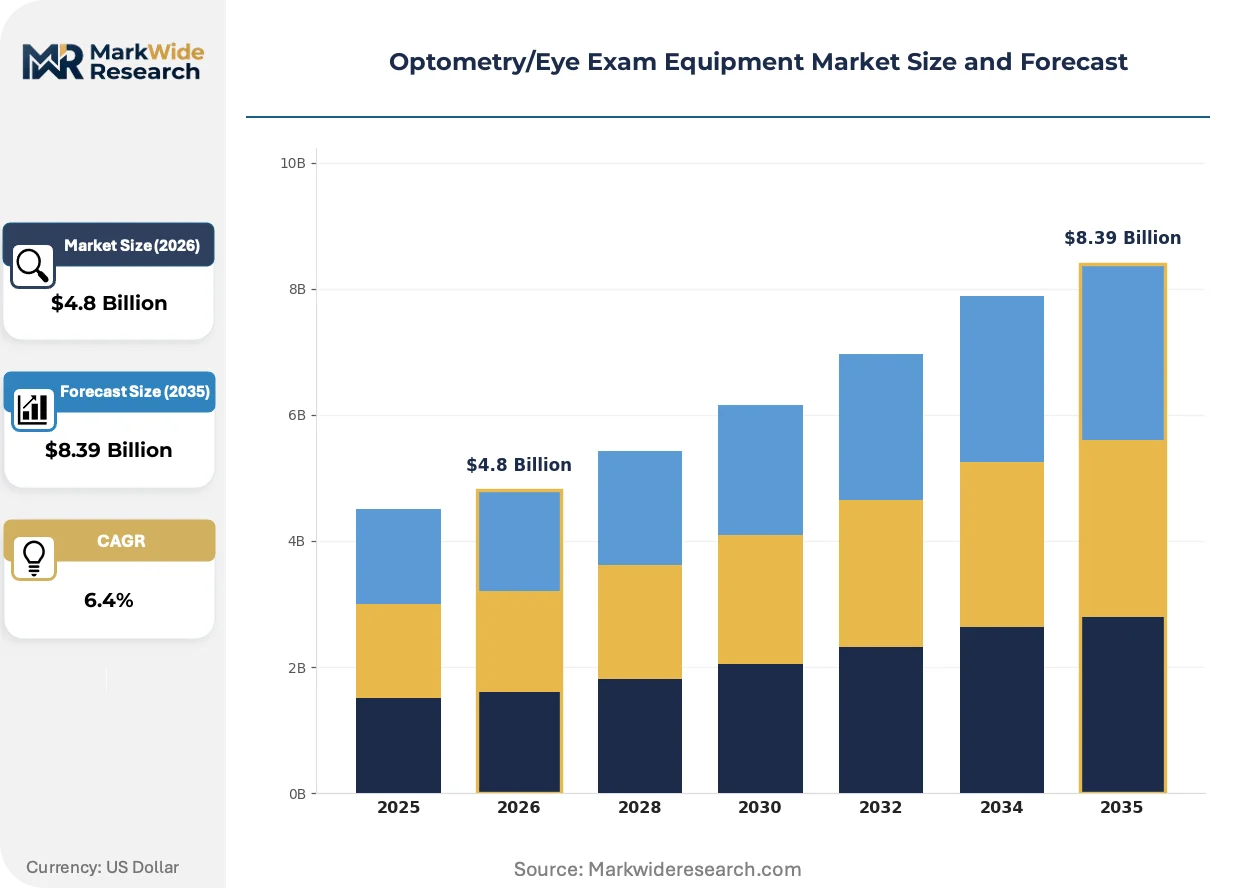
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autorefractors, Phoropters, Retinoscopes, Slit Lamps, Lensmeters Technology: Digital Imaging, Wavefront Aberrometry, Optical Coherence Tomography, Fundus Photography, Corneal Topography Application: Vision Screening, Glaucoma Detection, Cataract Assessment, Retinal Disease Diagnosis, Refractive Error Analysis End User: Optometry Clinics, Ophthalmology Centers, Vision Therapy Facilities, Optical Retailers, Research Laboratories |
| Companies Covered | Carl Zeiss Meditec AG, EssilorLuxottica, Topcon Corporation, NIDEK Co., Ltd., Alcon, Bausch Health Companies Inc., Haag-Streit, Heidelberg Engineering, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optometry/Eye Exam Equipment Market Strategic Shifts & Innovations
Market evolution is defined by a shift from isolated vision correction to integrated, software-driven ocular health management. Connectivity and data analytics are becoming as critical as optical precision in defining equipment value and clinical utility for ophthalmology centers and retail clinics alike.
Artificial intelligence algorithms are a key technology for automated analysis of retinal images and OCT scans. Ophthalmology centers and large optical groups are adopting this for faster screening and to provide diagnostic support for less experienced clinicians. This technology is integrating diagnostic hardware with clinical decision support software, creating more powerful and unified eye care ecosystems that improve patient throughput.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence, risk management, and post-market surveillance. This directive increases the compliance burden and costs for all medical device manufacturers selling into the EU market. Equipment categories with embedded software, such as OCT scanners and digital phoropters, are particularly affected, requiring extensive updates to technical documentation to maintain their CE marking.
A significant demand-side shift involves the consolidation of purchasing within large optical retail corporations and integrated hospital delivery networks. This pattern disrupts traditional sales models that targeted individual private practices, replacing them with centralized procurement processes demanding volume discounts and proven interoperability. This trend is most prominent in North America and Western Europe, where corporate optometry continues to expand its footprint.
Optometry/Eye Exam Equipment Market Segmentation
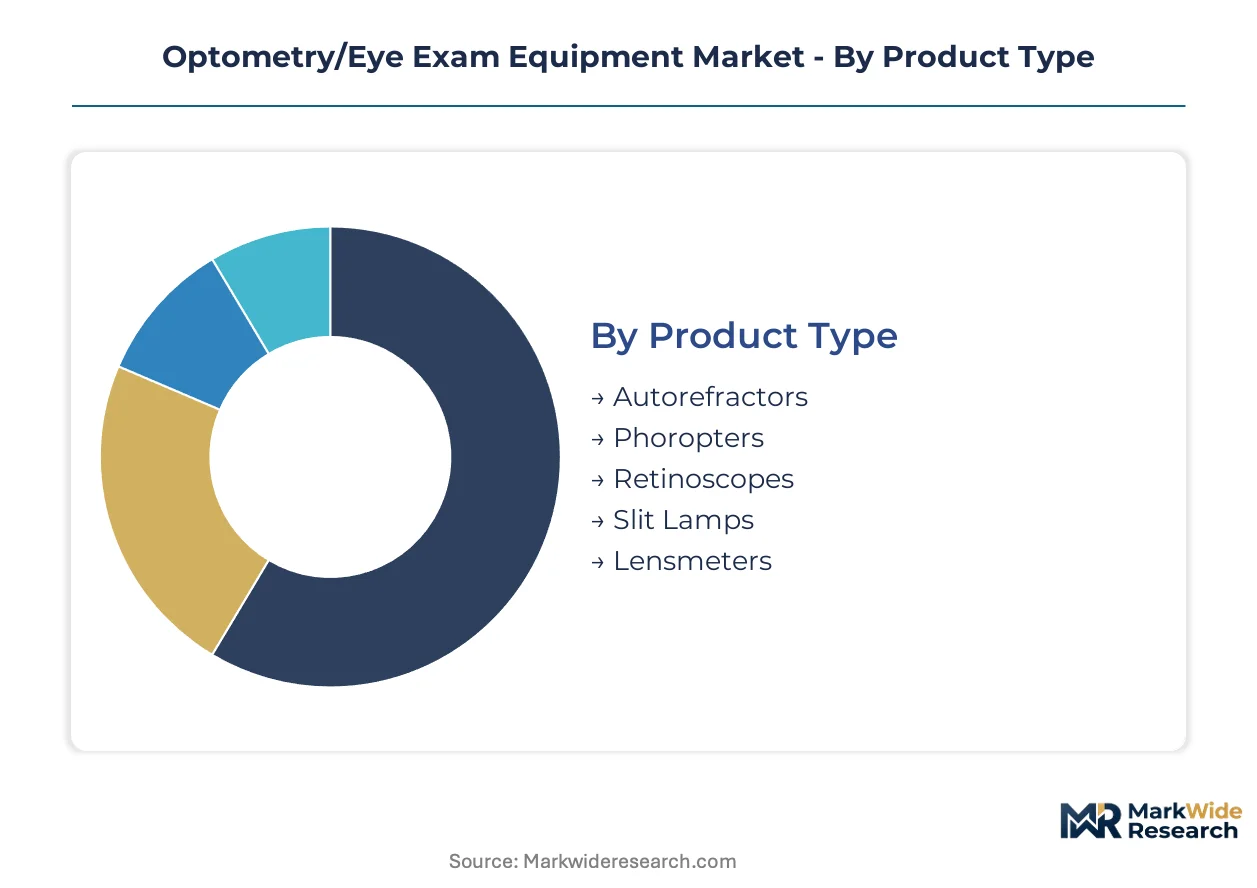
The segmentation of the optometry and eye exam equipment market provides a granular view of product utility and technological adoption. Understanding these distinct categories helps manufacturers align product development with specific clinical needs and regulatory pathways. This detailed analysis supports strategic decision-making across diverse end-user environments globally.
Product Type:
Regulatory frameworks heavily influence specific product types, with advanced diagnostic tools requiring stringent approvals from bodies like the FDA, EU MDR, NMPA, and PMDA.
- Autorefractors:These automated devices objectively measure refractive error by analyzing light changes entering the eye. Demand concentrates in China, driven by expanding healthcare access and efficient preliminary screenings.
- Phoropters:These instruments contain multiple lenses and prisms, used to subjectively refine a patient's refractive correction and assess binocular vision. Their precision is essential in established optometry clinics across Western Europe.
- Retinoscopes:Manual retinoscopes provide a basic, objective measurement of refractive error, particularly useful for pediatric patients.
- Slit Lamps:These biomicroscopes offer high-magnification views of the anterior and posterior segments of the eye for detailed assessment.
- Lensmeters:Lensmeters accurately measure the optical power of spectacle and contact lenses, essential for verifying prescriptions.
Retinoscopes sits at the top of the volume ranking, with Autorefractors climbing the fastest.
Technology:
The application of various technologies directly correlates with their diagnostic capabilities and the specific ocular conditions they are designed to address.
- Optical Coherence Tomography:OCT produces high-resolution cross-sectional images of the retina and optic nerve, critical for diagnosing and monitoring retinal diseases. AI integration enhances accuracy for ophthalmology centers.
- Wavefront Aberrometry:This technology measures optical aberrations across the pupil, providing detailed information for customized vision correction procedures. Ophthalmology centers in the United States adopt it for advanced corneal mapping.
- Digital Imaging:Digital cameras integrated with slit lamps capture high-resolution images for documentation and telemedicine.
- Fundus Photography:This technique captures color images of the fundus, primarily for documenting and screening diabetic retinopathy.
- Corneal Topography:Corneal topography maps the curvature of the cornea, vital for contact lens fitting and refractive surgery planning.
The adoption of Optical Coherence Tomography is expanding most quickly, driven by its enhanced diagnostic accuracy for retinal conditions.
Application:
Different applications cater to distinct end-user requirements, ranging from routine screenings in retail settings to specialized diagnostics within clinical environments.
- Retinal Disease Diagnosis:This application leverages advanced imaging technologies like OCT to detect and monitor conditions such as age-related macular degeneration. Demand is strong in ophthalmology centers due to aging populations.
- Glaucoma Detection:Equipment for glaucoma detection measures intraocular pressure and assesses optic nerve health. Preventative health policies in Europe encourage widespread screening for this application.
- Vision Screening:Basic vision screening identifies individuals who may require further comprehensive eye examinations.
- Cataract Assessment:This application involves evaluating the clarity of the eye's lens to determine the presence and severity of cataracts.
- Refractive Error Analysis:This application focuses on precisely measuring and correcting common vision impairments like myopia.
Demand for Vision Screening remains consistent, while Retinal Disease Diagnosis is experiencing rapid uptake.
End User:
The maturity of different end-user segments dictates their procurement patterns and the sophistication of the equipment they prioritize for patient care.
- Ophthalmology Centers:These specialized medical facilities require high-end diagnostic and surgical equipment to manage complex ocular diseases. They prioritize precision and EHR integration in countries like Germany and Japan.
- Optical Retailers:Large optical retail chains integrate diagnostic equipment like autorefractors to offer comprehensive eye exams alongside eyewear sales. Their procurement in North America emphasizes cost-efficiency.
- Optometry Clinics:Independent optometry clinics utilize a broad range of diagnostic tools for routine eye exams and basic vision correction.
- Vision Therapy Facilities:These centers employ specialized equipment for visual training and rehabilitation, improving visual skills.
- Research Laboratories:Academic and private research labs utilize highly specialized imaging equipment for studying ocular diseases and developing treatments.
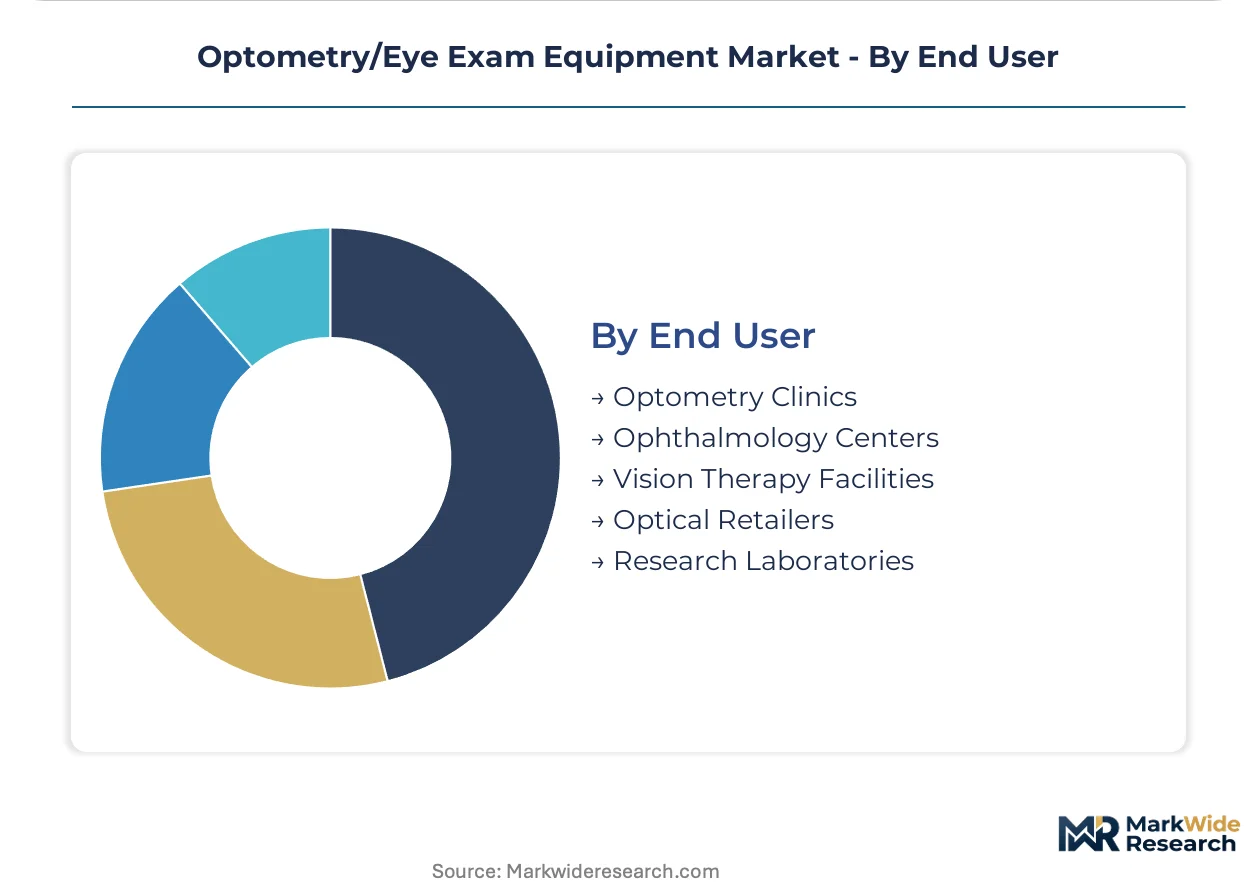
Ophthalmology Centers lead in advanced equipment procurement, with Optical Retailers expanding their diagnostic capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding healthcare infrastructure and aging demographic profile contribute significantly to regional demand for optometry and eye exam equipment. This market shows varied maturity across different global regions, reflecting diverse healthcare systems and regulatory landscapes. Advanced diagnostic technologies find strong procurement in established economies.
United States
Demand for advanced diagnostic systems, particularly AI-enhanced OCT, drives equipment procurement in the United States. The FDA's 510(k) process governs market access for medical devices, influencing product development cycles. The Boston-Cambridge region remains a hub for ophthalmic innovation, attracting significant research and development investment.
Germany
Ophthalmology centers in Germany prioritize high-precision diagnostic tools and integrated EHR systems for complex ocular disease management. The EU's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence and post-market surveillance. Southern Germany, particularly around Jena, hosts a strong cluster of optical and medical technology manufacturers.
China
Expanding healthcare access and a rapidly aging population fuel substantial demand for both basic and advanced eye exam equipment across China. Approvals from China's NMPA are critical for commercial entry, setting national standards for device safety. The Yangtze River Delta region demonstrates strong growth in medical device manufacturing and ophthalmic technology adoption.
Japan
Japanese ophthalmology centers require high-end diagnostic and surgical equipment, emphasizing precision and technological sophistication. Japan's PMDA provides critical regulatory oversight for medical devices, ensuring compliance with strict quality standards. The Tokyo metropolitan area features a concentration of medical device companies and advanced research institutions.
Optometry/Eye Exam Equipment Market Key Industry Players
Strategic partnerships and consolidation activities dominate the current landscape, particularly among large optical retail chains and integrated healthcare networks. The market features a tiered structure, with established multinational corporations commanding the high-end diagnostic segment. Mid-tier specialists focus on specific product categories or regional markets. Emerging players often compete on price in basic diagnostic tools. Companies are pursuing both technological diversification and geographic expansion to secure market share.
Within the high-end diagnostic equipment segment, Carl Zeiss Meditec AG exemplifies a focus on advanced optics and precision imaging solutions for complex ocular conditions. Topcon Corporation represents a comprehensive integrated eye care solution provider, connecting diverse diagnostic devices through unified software platforms and data management. EssilorLuxottica, a global eyewear leader, occupies a strong position in the retail channel, influencing equipment choices through its extensive network and procurement patterns. These entities collectively anchor different strategic vectors within the market, shaping technology adoption and distribution channels across various end-user environments.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| EssilorLuxottica |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| Alcon |
| Bausch Health Companies Inc. |
| Haag-Streit |
| Heidelberg Engineering |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
AI-enhanced imaging technologies reshape cost economics for advanced optometry equipment, simultaneously concentrating specialized component supply chains. This technological evolution drives demand for high-precision manufacturing, influencing pricing power across the market.
Pricing Analysis
Input-cost pass-through remains significant for advanced diagnostic systems, particularly for specialized optical components and AI development. Pricing stratifies across premium, standard, and economy tiers, reflecting equipment sophistication and regulatory approvals like FDA 510(k) or EU MDR. Price differentiation stems from advanced optics and integrated software platforms. Cost compression intensifies within the basic diagnostic tools segment due to competition from low-cost manufacturers. Small independent optometry practices exhibit the highest price sensitivity, while large ophthalmology centers prioritize advanced features over initial cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers for high-precision optical components and advanced sensors. Supply concentration for sophisticated equipment largely rests in Germany and Japan, while China dominates basic diagnostic tool manufacturing and raw material supply. The industry sources precision optics, advanced sensors, and AI processing units globally. Regulatory restrictions and logistics chokepoints represent a structural supply chain risk for complex devices. Distribution runs through direct sales channels for large ophthalmology centers and retail chains, complemented by regional distributors serving independent optometry clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optometry and eye exam equipment market functions as a stable compounder, driven by the persistent demographic pressure of an aging global population. This consistent demand underpins sustained growth for advanced diagnostic solutions.
For Market Incumbents: Extend existing product ecosystems through software integration, solidifying data interoperability with EHR and PACS systems. This defends against emerging software-as-a-medical-device competitors and enhances clinical workflow efficiency. Invest in robust post-market surveillance capabilities to navigate evolving EU MDR requirements. Deepen vertical integration for critical components like advanced optics to mitigate supply chain disruptions.
For New Entrants and Emerging Players: Telehealth software platforms offer a direct route to remote and underserved populations, bypassing traditional clinic infrastructure. Target the mid-tier equipment segment in Southeast Asia with robust, portable diagnostic devices. Focus on new diagnostic applications for existing technologies, such as anterior segment analysis using portable OCT devices. A value-based pricing model bundled with training and support provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among established manufacturers of basic diagnostic tools facing intense price competition. The market offers long-term viability over the next decade due to persistent demographic tailwinds and technological innovation. Target acquisition archetypes include specialized software firms enhancing AI diagnostic capabilities or mid-sized manufacturers with strong regional distribution networks in emerging markets. The signal to watch for inflection is widespread reimbursement for AI-assisted diagnostic procedures.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-integrated OCT platforms | Enhances diagnostic accuracy for retinal diseases, improving patient outcomes in ophthalmology centers. |
| Expand tele-optometry solution offerings | Extends eye care access to remote populations, creating new revenue streams for optical retailers. |
| Secure NMPA and PMDA approvals | Facilitates commercial entry into high-growth markets like China and Japan, expanding market reach. |
| Invest in advanced optics R&D | Maintains technological leadership and differentiates high-end diagnostic equipment from basic tools. |
| Acquire specialized software developers | Strengthens clinical decision support capabilities and improves EHR integration for hospital networks. |
Research Approach
Bottom-up ophthalmology center and optical retailer modeling reconciled against top-down equipment manufacturer tracking forms the analytical core. This approach combined primary interviews with industry stakeholders and secondary validation. Interviews included optometrists, hospital procurement managers, R&D directors, and regulatory affairs specialists. Secondary data sources encompassed medical device filings, industry association reports, academic literature, and government healthcare statistics.
An input-output matrix framing guided the quantitative modeling across the analysis window. Segmentation dimensions included product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included demographic shifts in aging populations and government preventative health policies encouraging screenings.
Regulatory policy changes, technological breakthroughs, and shifts in healthcare expenditure are the dominant revision risks. Forecasts reflect assumptions regarding market access and adoption rates for advanced equipment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Global Retinal Vein Occlusion Market