
 Fungal Eye Infection Market | 2026-2036
Fungal Eye Infection Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Eye Infection Market Foresight
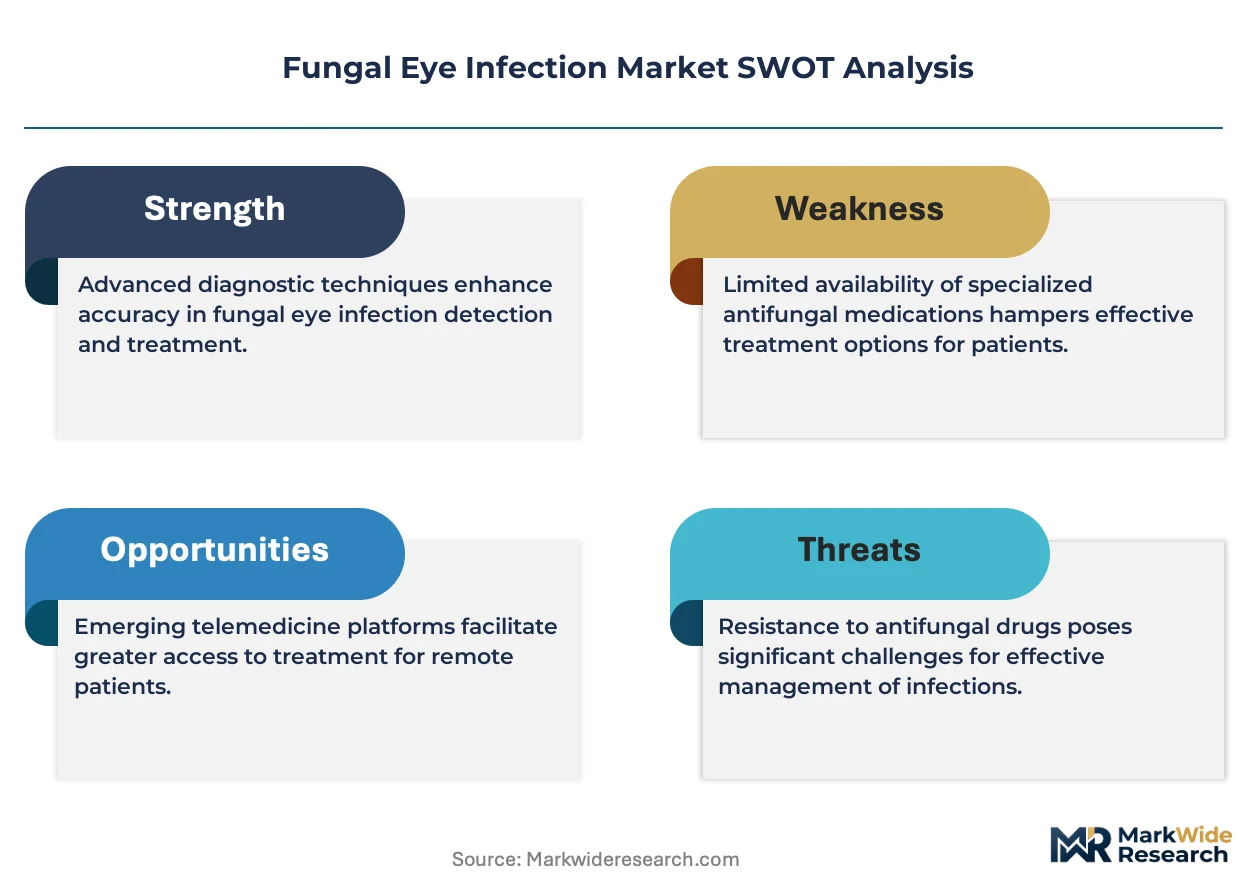
CE marking under the EU Medical Device Regulation is collapsing the competitive field for intravitreal antifungal formulations, forcing smaller manufacturers toward contract manufacturing or exit. Pfizer Inc. leverages its sterile injectable infrastructure to sustain European supply continuity. Merck & Co., Inc. anchors its position through backward integration into active pharmaceutical ingredient production for natamycin. Bausch Health differentiates via dedicated ophthalmology sales channels that control formulary access in North American eye care institutes.
Fungal eye infection comprises invasive mycotic conditions of the ocular surface, anterior chamber, or vitreous cavity, typically requiring topical amphotericin B, natamycin, or voriconazole with minimum inhibitory concentration-guided dosing to preserve corneal clarity or intraocular viability. These therapies address vision-threatening pathology in immunocompromised patients, contact lens wearers, and trauma cases where bacterial coverage proves inadequate. Keratitis dominates therapy area volume due to agricultural trauma and contact lens-related Fusarium outbreaks, while endophthalmitis commands premium pricing despite smaller case volumes. Topical administration leads route of administration utilization for superficial infections, though intravitreal injection growth accelerates alongside vitreoretinal surgical expansion in specialized eye hospitals.
FDA antifungal susceptibility testing requirements and EMA MDR quality standards shape product development timelines and market access barriers for novel formulations. India's CDSCO and the US FDA both mandate stringent sterility assurance for intraocular products, elevating capital requirements for new entrants. Stakeholders must monitor WHO fungal pathogen priority list revisions and diagnostic reimbursement policy shifts to anticipate shifts in empirical versus targeted therapy protocols.
Market Dynamics
CE marking under the EU Medical Device Regulation is collapsing the competitive field for intravitreal antifungal formulations, forcing smaller manufacturers toward contract manufacturing or exit while sterile injectable infrastructure becomes the decisive moat for surviving suppliers.
Growth Catalysts
- WHO fungal priority pathogens list:The 2022 revision elevated Candida auris and Aspergillus fumigatus to critical status, prompting national formularies to stock broader-spectrum azoles and driving diagnostic PCR platform procurement in tertiary eye hospitals.
- Agricultural trauma incidence:Fusarium keratitis clusters among Tamil Nadu and Karnataka agricultural workers generate sustained demand for natamycin at specialty ophthalmology clinics across South India.
- Vitreoretinal surgical expansion:Dedicated eye hospitals in the US Sun Belt are adding intravitreal injection suites, creating pull-through demand for compounded voriconazole and amphotericin B lipid complex.
Market Restraints
- API supply concentration:Natamycin active pharmaceutical ingredient production concentrates in three Chinese fermentation facilities, exposing formulators to sporadic export license suspensions under NMPA environmental compliance audits.
- Sterility assurance capital intensity:EMA MDR Annex I requirements for aseptic processing validation demand ISO 5 cleanroom suites costing $12-18 million per filling line, freezing out mid-scale entrants.
- Topical corticosteroid substitution:Misdiagnosed fungal keratitis receiving empirical steroid monotherapy delays appropriate antifungal initiation, compressing addressable case volumes in primary care settings.
Strategic Opportunities
- Underpenetrated sub-Saharan Africa:Trauma-related fungal keratitis in Ethiopian and Nigerian agricultural belts lacks access to natamycin, creating white space for WHO prequalification pathways and nonprofit distribution partnerships.
- Point-of-care diagnostic convergence:LAMP-based fungal identification platforms combining with smartphone-connected slit-lamp adapters enable same-day targeted therapy initiation in rural Indian clinics.
- India PLI scheme for APIs:Production-linked incentives for critical drug intermediates are attracting fermentation capacity investments that could diversify natamycin supply chains beyond current Chinese dominance.
Industry Challenges
- Compounded pharmacy compliance:US 503B outsourcing facilities face FDA intensified inspection schedules for sterile ophthalmic preparations, with warning letter trends elevating batch release timelines from 72 hours to 14 days.
- Antifungal susceptibility testing integration:Clinical laboratories lack standardized broth microdilution protocols for filamentous fungi, delaying MIC-guided voriconazole dosing in endophthalmitis cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Eye Infection Market |
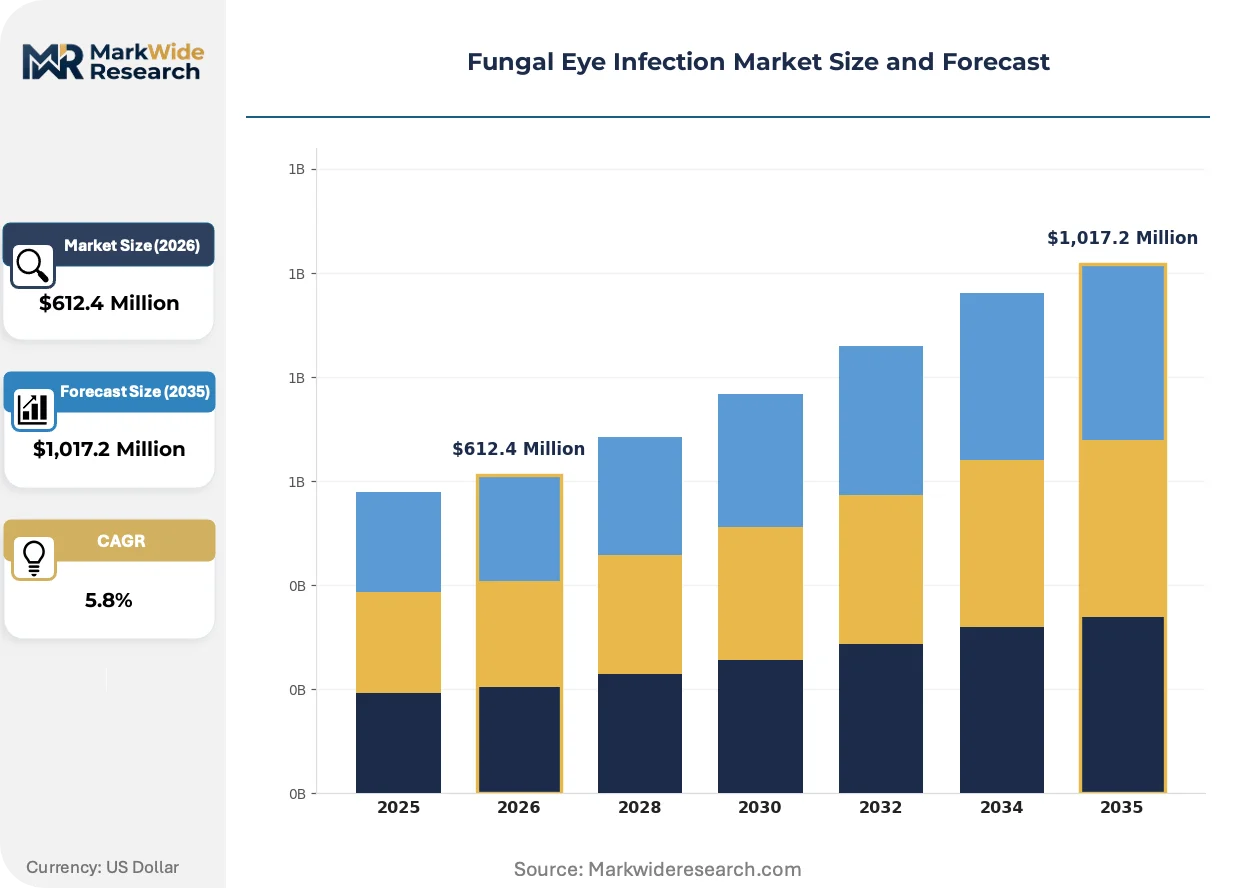
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Candidiasis, Aspergillosis, Fusariosis, Cryptococcosis, Others Therapy Area: Keratitis, Endophthalmitis, Conjunctivitis, Blepharitis End User: Ophthalmology Clinics, Specialized Eye Hospitals, Ambulatory Surgical Centers, Eye Care Institutes Route of Administration: Topical, Oral, Intravitreal Injection, Subconjunctival Injection |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Bausch Health, Gilead Biosciences Inc., Glenmark Pharmaceuticals, Alvogen, Astellas Pharma, Inc., Bayer AG, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Eye Infection Market Shifts & Advancements
Diagnostic automation and formulation delivery precision are compressing the window between presentation and targeted therapy, altering how specialty eye hospitals configure their microbiology laboratories and pharmacy compounding workflows.
Confocal microscopy with integrated artificial intelligence classification algorithms is miniaturizing from tabletop laboratory systems to portable handheld units deployable in rural ophthalmology camps. Indian specialty hospitals in Madurai and Hyderabad are piloting these devices for immediate Fusarium versus Aspergillus differentiation. The technology is miniaturizing capital requirements for diagnostic capacity, enabling mid-tier clinics to bypass centralized reference laboratory dependence.
EMA MDR post-market surveillance requirements now mandate systematic collection of device-related adverse events across all CE-marked intraocular drug delivery systems. Sterile injectable manufacturers must maintain pharmacovigilance databases with 15-year retention periods. European ophthalmology clinics are responding by consolidating supplier relationships toward vertically integrated manufacturers with established QMS infrastructure.
Contact lens wearers in the US Sun Belt are compressing their switching cycles from monthly to daily disposable modalities following multistate Fusarium outbreaks linked to multipurpose solution contamination. Retail optical chains are reallocating shelf space toward single-use lens portfolios. This behavioral pivot is most visible in Florida and Texas, where humidity-driven fungal keratitis incidence exceeds national baselines by 40 percent.
Fungal Eye Infection Market Segmentation
Therapy selection in fungal eye infections hinges on anatomical depth of invasion and host immune status, creating distinct procurement patterns across superficial versus intraocular presentations. Segmentation reveals how diagnostic capacity and surgical infrastructure shape demand concentration by geography and care setting.
Type:
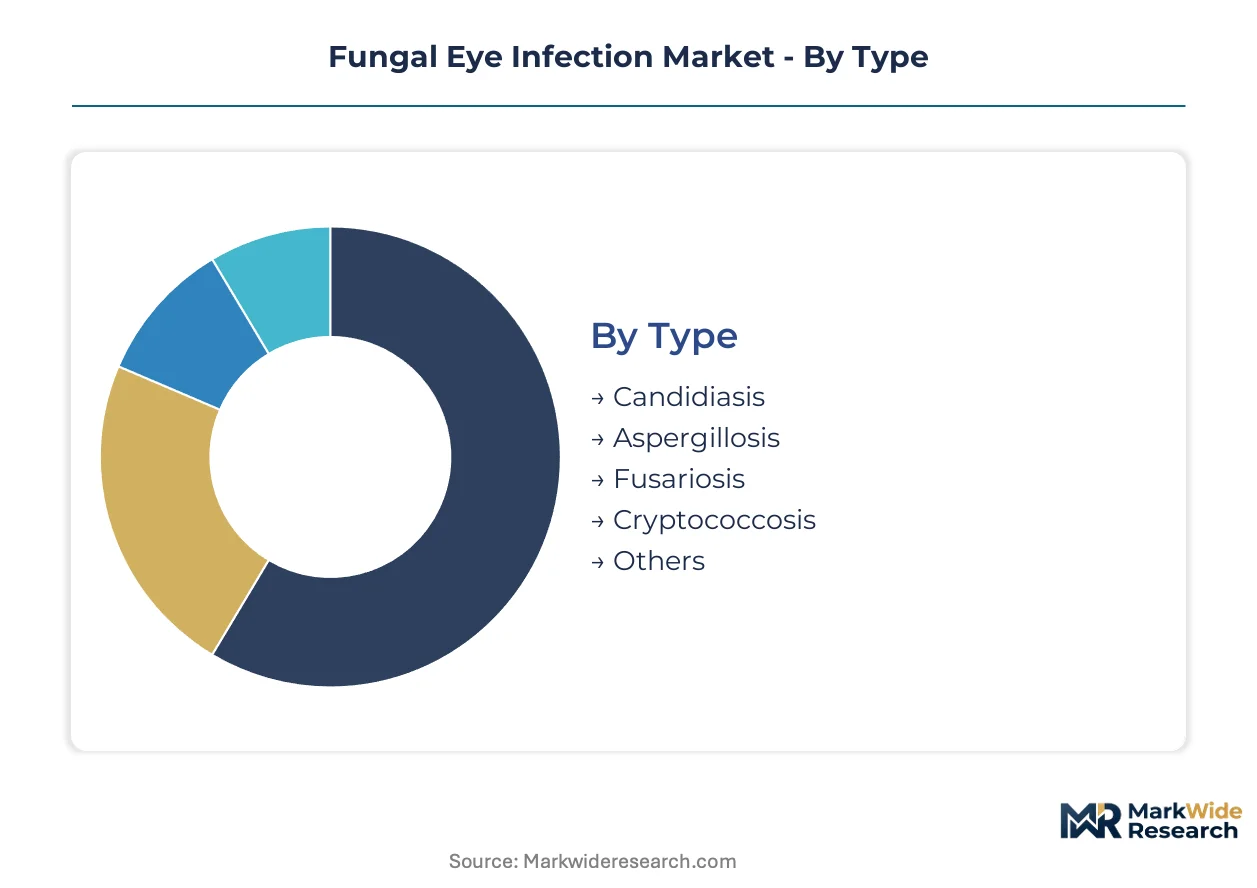
Fusariosis clusters in agricultural trauma corridors across India and the US Sun Belt, while Candidiasis dominates hospital-acquired cases in tertiary centers with broad-spectrum antibiotic exposure.
- Candidiasis:Yeast-form infections typically arise from hematogenous seeding in immunocompromised hosts or prolonged corticosteroid use. Demand concentrates in specialized eye hospitals across Florida and Texas, where diabetes prevalence drives endogenous endophthalmitis caseloads requiring systemic fluconazole or intravitreal amphotericin B.
- Aspergillosis:Filamentous mold causing aggressive scleritis and orbital apex syndrome in neutropenic patients. Tertiary oncology centers in Hyderabad and Mumbai generate concentrated demand for voriconazole therapy guided by EUCAST broth microdilution protocols.
- Fusariosis:Trauma-associated keratitis in agricultural workers across Tamil Nadu and Karnataka agricultural belts.
- Cryptococcosis:Subacute meningoencephalitis with choroidal involvement in HIV/AIDS patients.
- Others:Rare dematiaceous molds including Curvularia and Exserohilum species.
Fusariosis commands the established base. The steepest expansion runs through Candidiasis.
Therapy Area:
Volume distribution splits between high-frequency superficial infections managed in outpatient settings and low-volume, high-acuity intraocular emergencies requiring surgical intervention.
- Keratitis:Corneal stromal invasion by filamentous fungi or yeasts following trauma or contact lens wear. Agricultural workers in South India and daily disposable lens converts in the US Sun Belt drive natamycin and voriconazole demand at ophthalmology clinics with confocal microscopy capability.
- Endophthalmitis:Vitreous cavity infection threatening vision and globe viability. Specialized eye hospitals in the US Sun Belt and Indian metro corridors command premium pricing for intravitreal injection suites and compounded antifungal formulations.
- Conjunctivitis:Superficial fungal colonization of bulbar or palpebral conjunctiva.
- Blepharitis:Chronic lid margin inflammation with Malassezia or dermatophyte involvement.
Keratitis captures volume leadership. Endophthalmitis delivers margin concentration.
End User:
Facility type determines formulary depth, with dedicated eye hospitals maintaining broader-spectrum stock than general ophthalmology clinics.
- Specialized Eye Hospitals:Dedicated vitreoretinal surgical infrastructure with ISO 5 compounding pharmacies and in-house microbiology laboratories. Aravind Eye Care System in Madurai and Bascom Palmer Eye Institute in Miami anchor regional referral networks for complex fungal endophthalmitis.
- Ophthalmology Clinics:Community-based diagnostic and medical management capacity for uncomplicated keratitis. Clinics across Tamil Nadu and Karnataka agricultural belts sustain natamycin demand through direct patient access.
- Ambulatory Surgical Centers:Outpatient surgical facilities with limited overnight observation capacity.
- Eye Care Institutes:Academic medical center affiliates with fellowship training programs and research protocols.
Specialized Eye Hospitals command the established base. The steepest expansion runs through Ophthalmology Clinics.
Route of Administration:
Anatomical penetration requirements and infection depth dictate delivery modality selection, with topical formulations serving superficial disease and intraocular injection reserved for sight-threatening posterior segment involvement.
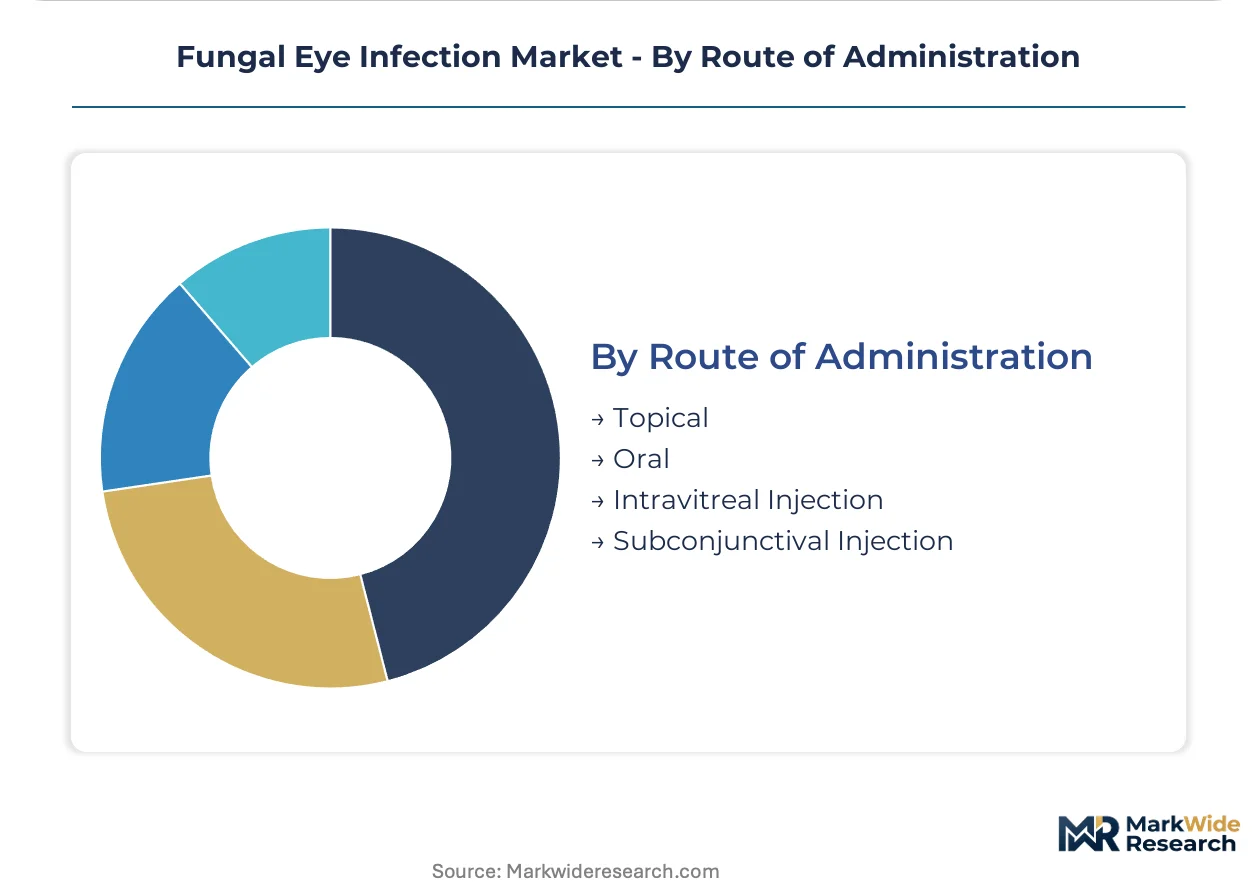
- Topical:Natamycin 5% suspension and amphotericin B 0.15% drops for epithelial and anterior stromal keratitis. Ophthalmology clinics across South India and retail pharmacies in the US Sun Belt drive volume through direct patient dispensing.
- Intravitreal Injection:Direct vitreous cavity delivery of voriconazole 100 mcg/0.1 mL or amphotericin B 5-10 mcg. Specialized eye hospitals in Hyderabad, Mumbai, and Florida surgical corridors invest in dedicated injection suites.
- Oral:Systemic azole therapy for deep stromal keratitis or endogenous endophthalmitis.
- Subconjunctival Injection:Periocular depot administration for scleritis or limbal involvement.
Topical administration commands the established base. Intravitreal Injection shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for critical drug intermediates is attracting fermentation capacity investments that could diversify natamycin supply chains beyond current Chinese dominance. The United States maintains sterile injectable infrastructure advantages through FDA-regulated 503B outsourcing facilities. European EMA MDR compliance costs are collapsing competitive fields for intravitreal formulations.
United States
Florida and Texas humidity drives fungal keratitis incidence 40 percent above national baselines, concentrating demand at Bascom Palmer Eye Institute in Miami and Texas Medical Center corridors. FDA intensified inspection schedules for 503B outsourcing facilities extend batch release timelines from 72 hours to 14 days, favoring manufacturers with established quality management systems. Vitreoretinal surgical expansion across Sun Belt dedicated eye hospitals accelerates intravitreal injection suite investments.
India
Tamil Nadu and Karnataka agricultural belts generate sustained Fusarium keratitis clusters among trauma-exposed workers, anchoring natamycin demand at Aravind Eye Care System in Madurai and Hyderabad specialty networks. CDSCO mandates stringent sterility assurance for intraocular products, elevating capital requirements for domestic formulators. South Indian ophthalmology clinics pilot AI-integrated confocal microscopy for immediate Fusarium versus Aspergillus differentiation.
China
Natamycin active pharmaceutical ingredient production concentrates in three fermentation facilities exposed to NMPA environmental compliance audit suspensions. Zhejiang and Jiangsu province chemical parks host bulk fermentation capacity serving global formulators. NMPA export license irregularities under environmental enforcement campaigns create sporadic supply disruptions for international natamycin buyers.
Germany
EMA MDR Annex I aseptic processing validation demands ISO 5 cleanroom suites costing 12-18 million euros per filling line, freezing out mid-scale intravitreal entrants. Bavaria and Baden-Württemberg pharmaceutical clusters maintain vertically integrated sterile injectable infrastructure. German tertiary eye hospitals anchor European demand for EUCAST broth microdilution-guided voriconazole therapy in aggressive scleritis cases.
Brazil
ANVISA regulatory pathways for sterile ophthalmic products remain underdeveloped relative to North American and European benchmarks, delaying novel formulation market access. São Paulo and Minas Gerais academic medical centers generate concentrated demand for amphotericin B lipid complex in HIV/AIDS-associated cryptococcal choroidal involvement. Brazilian ophthalmology residency programs drive adoption of PCR-based fungal identification platforms.
Fungal Eye Infection Market Competitive Landscape
Player mix skews toward pharmaceutical conglomerates with captive sterile manufacturing infrastructure and mid-scale formulators dependent on contract manufacturing partnerships. Market structure concentrates around three to five integrated manufacturers capable of EMA MDR compliance, with remaining participants occupying regional niches or exit-bound positions. Strategic archetypes include vertically integrated API-to-finished-dose manufacturers, sterile injectable specialists with ophthalmology-dedicated sales channels, and diversified pharma conglomerates leveraging hospital formulary relationships. Dominant competitive moves encompass backward integration into fermentation capacity and geographic expansion through WHO prequalification pathways for underserved markets.
Among US-based pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions reflecting sterile injectable infrastructure scale and API production control respectively. Bausch Health represents the ophthalmology-dedicated channel archetype, with North American eye care institute formulary access shaping its competitive positioning. These three entities exemplify how regulatory compliance capability and vertical integration depth determine survival under EMA MDR and FDA intensified inspection regimes.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bausch Health |
| Gilead Biosciences Inc. |
| Glenmark Pharmaceuticals |
| Alvogen |
| Astellas Pharma, Inc. |
| Bayer AG |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Fermentation capacity utilization at Chinese natamycin API facilities anchors price floors for finished formulations, with scale advantages concentrating supply power among three dominant producers while EMA MDR compliance costs erect premium-tier barriers for European intravitreal products.
Pricing Analysis
Certification level (ISO 5/CE-marked/FDA-grade) creates the primary spread between commodity topical suspensions and premium intravitreal formulations. Three-tier pricing structure across premium, standard, and economy levels separates EMA MDR-compliant sterile injectables from 503B-compounded alternatives and basic natamycin drops. Cost compression in the standard tier intensifies because Indian CDSCO sterility mandates elevate domestic capital requirements. Ophthalmology clinics across South India exhibit highest price sensitivity, while specialized eye hospitals in the US Sun Belt absorb premium intravitreal pricing.
Supply Chain Analysis
NMPA environmental audit exposure at Zhejiang and Jiangsu fermentation facilities underwrites supply volatility for international natamycin formulators. API production concentrates in China, India, and the United States, with finished dose formulation anchored in Germany and the United States. Raw material dependencies span fermentation substrates, specialized glass vials, and aseptic filling equipment. Single-source vulnerability concentrates at Chinese fermentation sites subject to export license suspensions. Distribution runs through hospital pharmacy procurement and specialty distributor networks serving eye care institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough driven by post-pandemic surgical backlog clearance and WHO fungal pathogen priority list revisions that expanded formulary stocking requirements.
For Market Incumbents: Consolidate sterile injectable infrastructure through captive fermentation capacity or exclusive 503B outsourcing partnerships. Threats from compounded pharmacy compliance failures create acquisition opportunities for quality-verified facilities. Backward integration into natamycin API production secures supply continuity against NMPA audit disruptions.
For New Entrants and Emerging Players: WHO prequalification fast-track pathways unlock sub-Saharan African distribution partnerships for trauma-related fungal keratitis. Ethiopian and Nigerian agricultural belts represent the most penetrable geography lacking natamycin access. Point-of-care diagnostic bundling with nonprofit distribution channels offers viable go-to-market positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with EMA MDR compliance infrastructure and ophthalmology-dedicated sales channels. Long-term viability over the next decade rests on diagnostic-therapy convergence and regional supply chain diversification. Monitor WHO fungal priority pathogen list revisions as inflection indicators for formulary expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Compliance Investment | ISO 5 cleanroom certification preserves European market access for intravitreal formulations. |
| Backward Integration into API Production | Captive natamycin fermentation capacity insulates against NMPA export license suspensions. |
| Point-of-Care Diagnostic Partnership | AI-integrated confocal microscopy deployment accelerates targeted therapy initiation in rural clinics. |
| WHO Prequalification Pathway | Nonprofit distribution partnerships unlock trauma-related keratitis demand in sub-Saharan Africa. |
| Sterile Injectable Infrastructure Expansion | Dedicated intravitreal injection suites at Sun Belt eye hospitals capture premium endophthalmitis caseloads. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and vitreoretinal surgeons; and secondary validation through FDA 503B facility inspection records, EMA MDR submission databases, CDSCO sterility guidance documents, and WHO prequalification listings. Bottom-up patient caseload modeling triangulated against top-down pharmaceutical sales audit data.
Across the analysis window, forecasts applied epidemiological incidence projections, surgical volume expansion rates, and formulary stocking policy shifts. Segmentation dimensions covered infection type, therapy area, end-user facility tier, and route of administration. CAGRs derived from regression against historical antifungal utilization curves and diagnostic platform deployment timelines. Forecast inputs incorporated agricultural trauma incidence patterns and contact lens modality switching behaviors.
Underlying assumptions cover sustained WHO fungal pathogen priority status, stable NMPA export licensing, and EMA MDR enforcement continuity, with deviation risk concentrated in environmental audit disruptions and diagnostic reimbursement policy reversals. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and pathogen emergence patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Nystagmus Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Ophthalmic Clinical Trials Market