
 Extended Oral Antibiotics Market | 2026-2036
Extended Oral Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Oral Antibiotics Market Foresight
EU Green Deal antimicrobial resistance reduction targets is hardening demand for formulations that support shorter hospital stays and reduced environmental discharge. Pfizer Inc. leverages its global manufacturing footprint to supply extended-release oral formulations across regulated markets. GlaxoSmithKline anchors its position through sustained investment in respiratory and pediatric infection portfolios. Sun Pharmaceutical Industries competes aggressively on cost structure in emerging markets with high generic penetration.
Extended oral antibiotics are pharmaceutical formulations engineered for prolonged systemic exposure through modified-release mechanisms, typically achieving therapeutic plasma concentrations over twelve to twenty-four hours to improve adherence and reduce dosing frequency. These products serve primarily to transition patients from intravenous to oral therapy while maintaining bactericidal or bacteriostatic efficacy against targeted pathogens. Tablet formulations dominate value capture due to manufacturing economies and patient preference, while liquid and suspension formats sustain growth in pediatric infections where swallowing capability limits solid-dose adoption. Respiratory infections represent the most mature therapy area with established prescribing patterns, whereas urinary tract infections concentrate margin pools where resistance surveillance drives premium positioning for newer agents.
FDA qualified infectious disease product incentives and EMA's antimicrobial resistance framework jointly shape clinical trial design and commercial prioritization for developers seeking accelerated pathways. India's CDSCO and BIS standards govern local manufacturing quality for export-oriented generic producers supplying regulated markets. WHO's essential medicines list revisions influence national procurement tenders and access programs across low- and middle-income countries. Stakeholders must monitor resistance surveillance data from EARS-Net and NARMS to anticipate shifts in formulary coverage and reimbursement thresholds for specific drug-bug combinations.
Market Dynamics
Hospital outpatient departments are aggressively compressing intravenous therapy days through oral step-down protocols, creating structural pull for extended-release formulations that maintain therapeutic exposure without nursing supervision.
Growth Catalysts
- FDA Qualified Infectious Disease Product incentives:Developers gain priority review and extended exclusivity for novel antibiotics targeting resistant pathogens, redirecting R&D investment toward oral formulations with superior resistance profiles.
- Germany's antimicrobial stewardship mandates:Hospital reimbursement now ties to IV-to-oral conversion timelines, forcing formulary committees to stock extended-release options with pharmacokinetic equivalence to parenteral therapy.
- Modified-release polymer matrix technology:Hydrophilic gel systems enable true once-daily dosing for beta-lactams previously requiring multiple daily administrations, improving adherence in outpatient cellulitis and pneumonia protocols.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India supply over seventy percent of oral antibiotic intermediates, exposing formulators to export restriction risk and price volatility in penicillin and cephalosporin starting materials.
- Bioequivalence study complexity:EMA's revised guideline on modified-release generics demands multiple dissolution specifications and food-effect trials, extending development timelines and elevating capital requirements for follow-on entrants.
- Phage therapy and monoclonal antibodies:These targeted alternatives for resistant Gram-negative infections threaten to displace broad-spectrum oral antibiotics in hospital discharge protocols for complicated intra-abdominal infections.
Strategic Opportunities
- India's CDSCO fast-track pathway:Domestic manufacturers can secure accelerated approval for qualified infectious disease products targeting WHO priority pathogens, creating export-ready capacity for regulated markets.
- Pediatric liquid extended-release formats:Mini-tablet-in-capsule and multiparticulate technologies address the unmet need for age-appropriate formulations in acute otitis media where compliance failures drive treatment escalation.
- EU Green Deal discharge limits:Formulations enabling shorter hospital stays reduce environmental antibiotic release through wastewater, aligning procurement criteria with sustainability targets in German and Dutch tenders.
Industry Challenges
- Clinical pharmacology expertise scarcity:Extended-release development demands specialized capability in physiologically-based pharmacokinetic modeling and food-effect prediction, talent concentrated at a handful of contract research organizations.
- Legacy manufacturing line retrofit costs:Fluid-bed coating and hot-melt extrusion equipment for modified-release layers requires seven-figure capital deployment, disadvantaging mid-scale generic houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Oral Antibiotics Market |
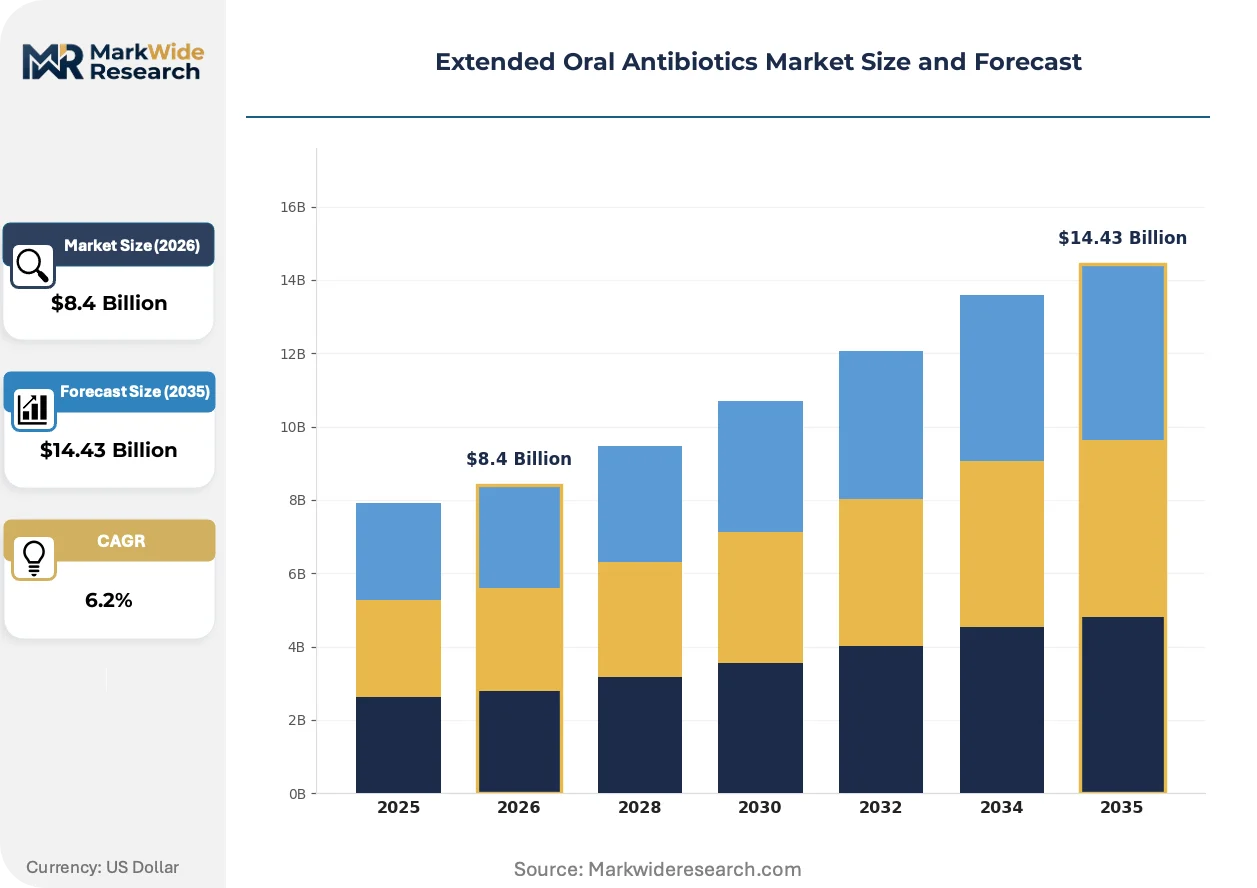
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amoxicillin, Ciprofloxacin, Azithromycin, Cefpodoxime End User: Clinics, Hospitals, Pharmacies, Homecare Formulation: Tablet, Capsule, Liquid, Suspension Therapy Area: Pediatric Infections, Skin Infections, Respiratory Infections, Urinary Tract Infections |
| Companies Covered | Pfizer Inc., GlaxoSmithKline, Abbott Laboratories, Cipla Limited, Novartis AG, Sun Pharmaceutical Industries, Bayer AG, Johnson & Johnson, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Oral Antibiotics Market Shifts & Advancements
Formulation science and regulatory science are converging to redefine what oral antibiotics can achieve in outpatient settings, with three distinct vectors reshaping competitive positioning.
Osmotic pump tablet technology is expanding into respiratory and complicated urinary tract infection categories where sustained plasma concentrations above MIC are critical for pathogen eradication. Large hospital systems in the United States are standardizing on osmotic pump amoxicillin-clavulanate for community-acquired pneumonia discharge, compressing the market for conventional immediate-release generics in this high-volume segment.
EMA's antimicrobial resistance framework now requires environmental risk assessments for all new antibiotic applications, including predicted wastewater concentrations and ecotoxicity profiles. This regulatory burden is filtering development portfolios toward agents with rapid metabolic clearance and minimal environmental persistence, disadvantaging lipophilic extended-release candidates with long half-lives.
Hospital procurement consortia are consolidating formularies around single-source extended-release antibiotics with demonstrated IV-to-oral conversion protocols, displacing fragmented multi-source purchasing. This concentration is most visible in United States integrated delivery networks where pharmacy and therapeutics committees now mandate therapeutic interchange policies that automatically substitute extended-release oral agents at discharge.
Extended Oral Antibiotics Market Segmentation
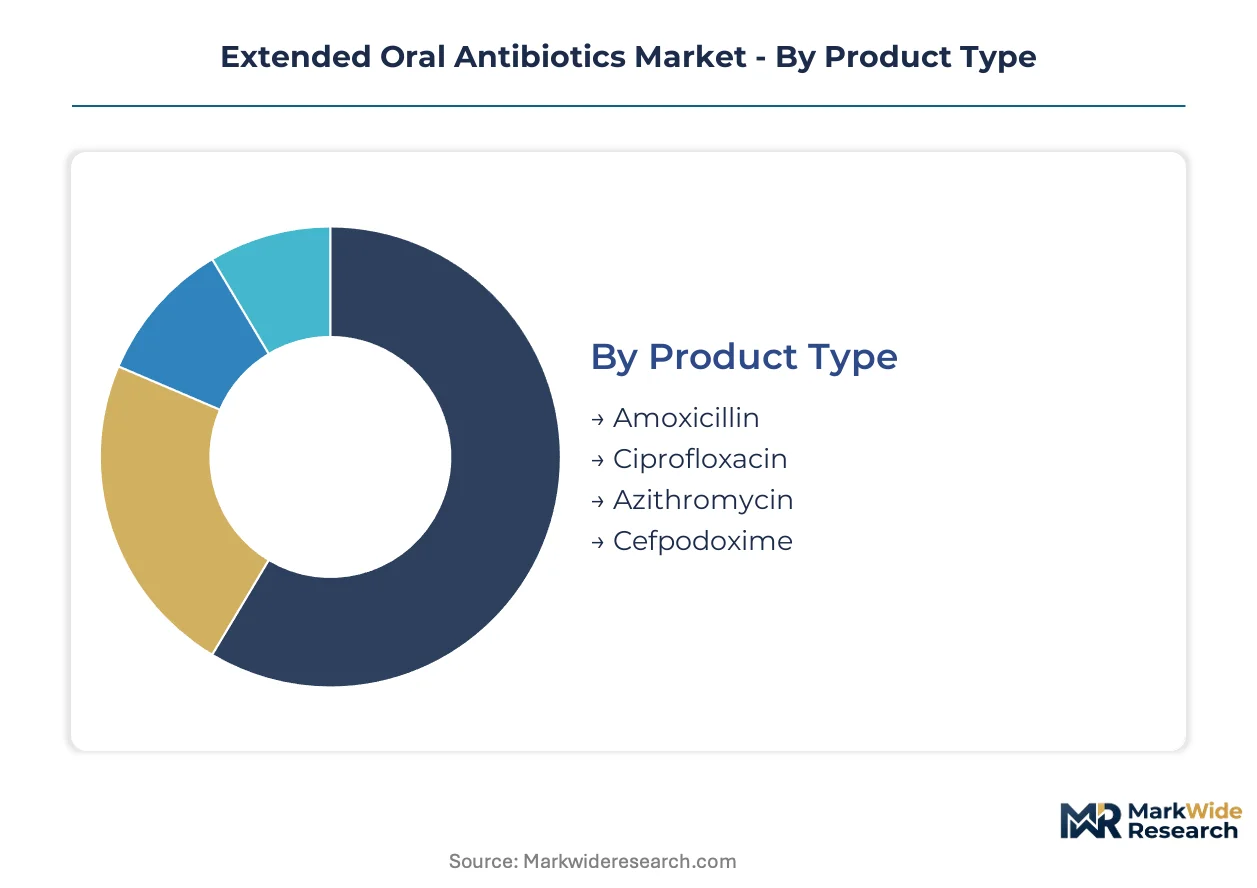
Segmentation in extended oral antibiotics reveals how formulation science, prescribing site economics, and resistance surveillance intersect to determine commercial viability. Each dimension carries distinct margin structures and regulatory exposure that shape portfolio prioritization for manufacturers.
Product Type:
Supply concentration for key active pharmaceutical ingredients tilts competitive dynamics toward molecules with backward-integrated or dual-sourced raw material pathways.
- Amoxicillin:Beta-lactam penicillin derivative formulated in extended-release matrices using hydrophilic gel systems. Demand concentrates in United States hospital discharge protocols where IV-to-oral conversion mandates favor its established pharmacokinetic profile. The molecule's mature generic base exposes margins to API price volatility from Indian and Chinese intermediate suppliers.
- Ciprofloxacin:Fluoroquinolone with osmotic pump formulations achieving true once-daily dosing for complicated urinary tract infections. German antimicrobial stewardship programs drive preferential formulary placement where resistance surveillance data supports its spectrum against Gram-negative pathogens. EMA environmental risk assessments now scrutinize its ecotoxicity profile, filtering development toward rapid-clearance derivatives.
- Azithromycin:Macrolide antibiotic with established multiparticulate extended-release technology.
- Cefpodoxime:Third-generation oral cephalosporin concentrated in pediatric and respiratory applications.
Today's leader: Amoxicillin. Tomorrow's challenger: Ciprofloxacin.
End User:
Cost tier differentiation separates sites with captive pharmacy operations from those dependent on reimbursement-driven dispensing economics.
- Hospitals:Integrated delivery networks in the United States mandate therapeutic interchange policies that automatically substitute extended-release oral agents at discharge, concentrating volume in formulary-controlled environments.
- Clinics:Outpatient facilities where oral step-down protocols compress intravenous therapy days.
- Pharmacies:Retail dispensing sites facing generic substitution pressure and prior authorization requirements.
- Homecare:Emerging channel for long-term oral antibiotic administration where adherence monitoring technologies create service revenue attachment.
Hospitals command volume leadership. Homecare offers the steepest expansion trajectory as remote patient monitoring infrastructure matures.
Formulation:
Application requirements dictate technology selection, with patient capability and age driving format preference in ways that reshape manufacturing investment.
- Tablet:Modified-release polymer matrices and osmotic pump systems dominate value capture through manufacturing economies and adult patient preference. Large United States hospital systems standardize on osmotic pump tablets for community-acquired pneumonia discharge.
- Liquid:Pediatric-focused formats where swallowing capability limits solid-dose adoption.
- Capsule:Mini-tablet-in-capsule technologies address multiparticulate release requirements.
- Suspension:Reconstitutable powders for acute otitis media where compliance failures drive treatment escalation.
Tablets anchor current revenue. Liquid formats are gaining share fastest in pediatric infection protocols.
Therapy Area:
Maturity gradients separate established prescribing patterns from segments where resistance surveillance creates premium positioning opportunities.
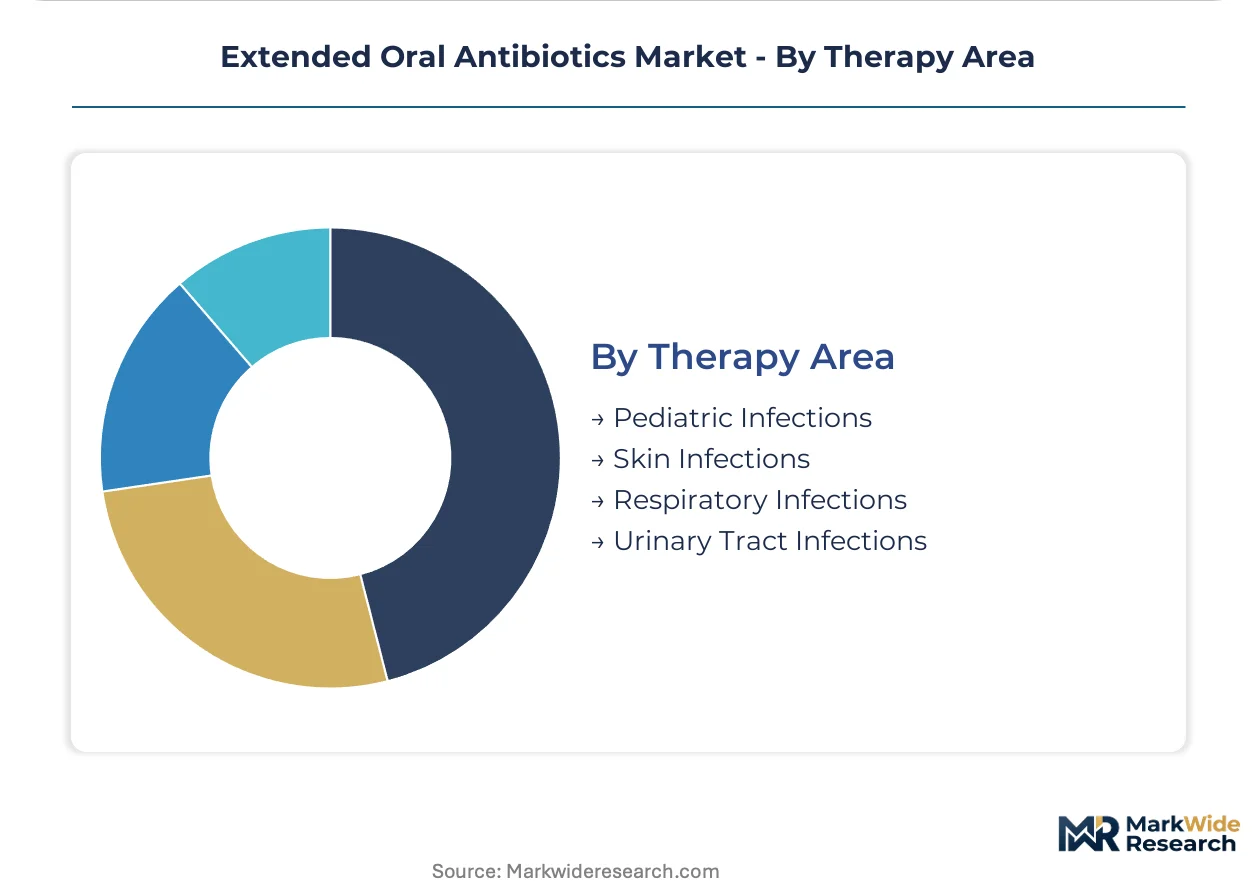
- Respiratory Infections:Most mature therapy area with established community-acquired pneumonia and acute bacterial sinusitis protocols. United States integrated delivery networks have compressed the market for immediate-release generics through standardized extended-release formulary placement.
- Urinary Tract Infections:Concentrated margin pools where EARS-Net resistance surveillance drives premium positioning for newer agents against resistant Gram-negative pathogens.
- Skin Infections:Outpatient cellulitis protocols favor extended-release beta-lactams with pharmacokinetic equivalence to parenteral therapy.
- Pediatric Infections:Acute otitis media and community-acquired pneumonia in age groups requiring liquid or multiparticulate formats.
Respiratory infections dominate current volume. Urinary tract infections present the most attractive margin expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Penicillin fermentation technology first achieved industrial scale in the United Kingdom during the 1940s, establishing the geographic template for extended-release oral antibiotic development that subsequently dispersed to North American and Asian manufacturing clusters.
United States
Hospital outpatient departments drive demand through IV-to-oral conversion mandates embedded in antimicrobial stewardship programs. FDA qualified infectious disease product incentives accelerate approval timelines for novel oral formulations targeting resistant pathogens. New Jersey and Massachusetts host concentrated pharmaceutical development clusters where contract research organizations specialize in physiologically-based pharmacokinetic modeling for modified-release design.
Germany
Antimicrobial stewardship legislation ties hospital reimbursement to specific timelines for intravenous-to-oral therapy transitions. EMA environmental risk assessments now mandate ecotoxicity profiling for all new antibiotic applications, filtering development portfolios. The Rhine-Main and Bavarian pharmaceutical corridors concentrate formulation science expertise and polymer matrix manufacturing infrastructure.
India
Generic manufacturing capacity expansion targets export markets in regulated jurisdictions through CDSCO fast-track pathways for qualified infectious disease products. BIS quality standards govern active pharmaceutical intermediate production for penicillin and cephalosporin derivatives. Gujarat and Maharashtra industrial zones concentrate backward-integrated API production and contract formulation services for extended-release tablet technologies.
Japan
Aging population demographics elevate outpatient infection management as a priority within universal health coverage frameworks. PMDA streamlined review pathways for anti-infective agents support domestic development of pediatric-appropriate liquid extended-release formats. The Kanto and Kansai metropolitan regions maintain specialized manufacturing infrastructure for osmotic pump and multiparticulate technologies.
Switzerland
Precision manufacturing traditions translate into specialized contract development services for complex modified-release formulations requiring hot-melt extrusion and fluid-bed coating capabilities. Swissmedic regulatory science leadership influences EMA guideline development for bioequivalence studies of extended-release generics. The Basel biopharmaceutical cluster anchors European development of polymer matrix systems for beta-lactam antibiotics.
Extended Oral Antibiotics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity tiers, with osmotic pump and multiparticulate technologies commanding price multiples over conventional hydrophilic matrix products. The market exhibits moderate concentration at the top tier, where integrated pharmaceutical companies control branded extended-release portfolios, while generic manufacturers fragment across cost-competitive immediate-release conversions. Three archetypes dominate: multinational innovators with captive development pipelines, regional generic houses with API backward integration, and specialized contract development organizations with formulation science expertise. Competitive dynamics center on regulatory pathway navigation and manufacturing scale deployment rather than direct price competition.
Among multinational innovators, Pfizer Inc. and GlaxoSmithKline occupy positions exemplifying the premium-tier archetype through sustained investment in extended-release development infrastructure and global distribution networks. Sun Pharmaceutical Industries represents the cost-leadership vector, leveraging Indian manufacturing scale to supply regulated markets with generic extended-release formulations. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive strategies within the oral antibiotics segment.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline |
| Abbott Laboratories |
| Cipla Limited |
| Novartis AG |
| Sun Pharmaceutical Industries |
| Bayer AG |
| Johnson & Johnson |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Formulation science expertise concentration in the Rhine-Main pharmaceutical corridor and Gujarat industrial zones creates labor-cost differentials that widen pricing-tier spreads between osmotic pump technologies and conventional hydrophilic matrices. Extended-release antibiotic pricing stratifies across three tiers: premium osmotic pump formulations commanding formulary placement in United States integrated delivery networks, standard polymer matrix products serving German antimicrobial stewardship mandates, and economy-tier immediate-release generics flooding Indian export markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the extended oral antibiotics landscape. Price differentiation hinges on bioequivalence certification complexity and manufacturing technology sophistication, with FDA-qualified infectious disease product status enabling premium positioning. Cost compression in the economy tier intensifies because Indian and Chinese API suppliers compete aggressively on penicillin and cephalosporin intermediates. Hospital procurement consortia exhibit lowest price sensitivity due to therapeutic interchange mandates, while retail pharmacies face highest substitution pressure from generic substitution laws.
Supply Chain Analysis
Freight cost volatility for temperature-controlled active pharmaceutical ingredient shipments from India and China to European formulation facilities elevates working capital requirements for just-in-time manufacturing. Raw material dependencies center on penicillin G potassium, cephalosporin C zinc salt, and modified-release polymer excipients. Single-source vulnerability concentrates in Chinese fermentation capacity for beta-lactam nuclei. Distribution runs through hospital procurement consortia in the United States, wholesaler networks in Germany, and direct institutional tenders in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The extended oral antibiotics market functions as a stable compounder anchored by irreversible antimicrobial stewardship mandates that perpetuate IV-to-oral conversion demand. Hospital outpatient expansion and generic manufacturing scale together sustain predictable value generation across economic cycles.
For Market Incumbents: Cement formulary lock-in through integrated IV-to-oral conversion protocol development with United States hospital systems facing CMS antimicrobial stewardship penalties. Secure backward integration into Indian API fermentation capacity to buffer penicillin intermediate price volatility from Chinese export restrictions. Pfizer Inc. and GlaxoSmithKline exemplify this defensive posture through captive manufacturing networks and stewardship program partnerships.
For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the most penetrable route for mid-scale generic houses seeking bypass of consolidated wholesaler networks. Target pediatric liquid extended-release formats where multiparticulate technology gaps persist and regulatory pathways through India's CDSCO fast-track mechanism enable accelerated market entry. Contract development organizations with physiologically-based pharmacokinetic modeling capability represent acquisition targets for technology access.
For Investors and Strategic Acquirers: Generic pharmaceutical conglomerates with Indian manufacturing footprints are the most active acquirer in this space, seeking formulation science capability to upgrade from immediate-release to modified-release portfolios. The five-to-ten-year viability window favors platforms with demonstrated bioequivalence study execution and EMA environmental risk assessment navigation. Watch for FDA qualified infectious disease product designation grants as inflection indicators for premium-tier repositioning potential.
| Strategic Initiative | Industry Significance |
|---|---|
| IV-to-Oral Conversion Protocol Development | United States hospital antimicrobial stewardship mandates create structural demand pull for extended-release formulations. |
| Modified-Release Manufacturing Scale-Up | Fluid-bed coating and hot-melt extrusion capacity expansion in Gujarat and Maharashtra serves regulated export markets. |
| Regulatory Fast-Track Pathway Navigation | India's CDSCO qualified infectious disease product designation enables accelerated approval for WHO priority pathogen targets. |
| Pediatric Formulation Technology Licensing | Mini-tablet-in-capsule and multiparticulate patents address acute otitis media compliance failures in outpatient settings. |
| Environmental Risk Assessment Capability | EMA's ecotoxicity profiling requirements filter development portfolios toward rapid-clearance antibiotic candidates. |
Research Methodology
Bottom-up hospital dispensing modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and pharmaceutical procurement managers informed demand-side assumptions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and national antimicrobial stewardship program documentation. Cross-referencing manufacturer capacity disclosures against customs trade data ensured supply-side calibration.
Input-output matrix framing connects active pharmaceutical ingredient fermentation volumes to finished formulation outputs across the projection horizon. Segmentation dimensions modeled include therapy area, dosage form technology, end-user site type, and regional regulatory cluster. CAGRs were derived from slope-intercept trajectory fitting against historical dispensing data and policy implementation timelines. Forecast inputs incorporated IV-to-oral conversion protocol adoption curves and environmental risk assessment filtering effects on development pipelines.
API export restriction triggers, bioequivalence guideline revision events, and phage therapy regulatory approval breakthroughs are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context and monitor EARS-Net resistance surveillance data for formulary shift indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market