
 Eye Infections Treatment Market | 2026-2036
Eye Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Infections Treatment Market Analysis
The capital-intensity divergence between large pharmaceutical conglomerates and focused ophthalmic specialists is rotating competitive investment toward biologics and sustained-release platforms. Pfizer Inc. leverages its global manufacturing scale to secure raw material access for antibiotic formulations. Santen Pharmaceutical Co., Ltd. anchors its position through deep specialization in ocular surface disease therapies. Regeneron Pharmaceuticals, Inc. differentiates via monoclonal antibody development for severe infectious indications.
Eye infections treatment encompasses pharmaceutical and biologic interventions targeting bacterial, fungal, and viral pathogens affecting ocular structures, typically formulated as sterile ophthalmic preparations with pH-balanced, isotonic compositions to preserve corneal epithelium integrity. These therapeutics serve to eradicate infectious agents, modulate inflammatory cascades, and prevent vision-threatening complications across acute and chronic presentations. Antibiotics occupy the largest therapeutic share within product type segmentation, reflecting established efficacy against bacterial conjunctivitis and keratitis pathogens. Topical delivery mode dominates volume flows due to direct ocular surface application and favorable patient compliance profiles. Hospital end-user channels capture premium pricing for injectable and complex regimen therapies, while homecare segments expand through patient-administered ophthalmic solutions.
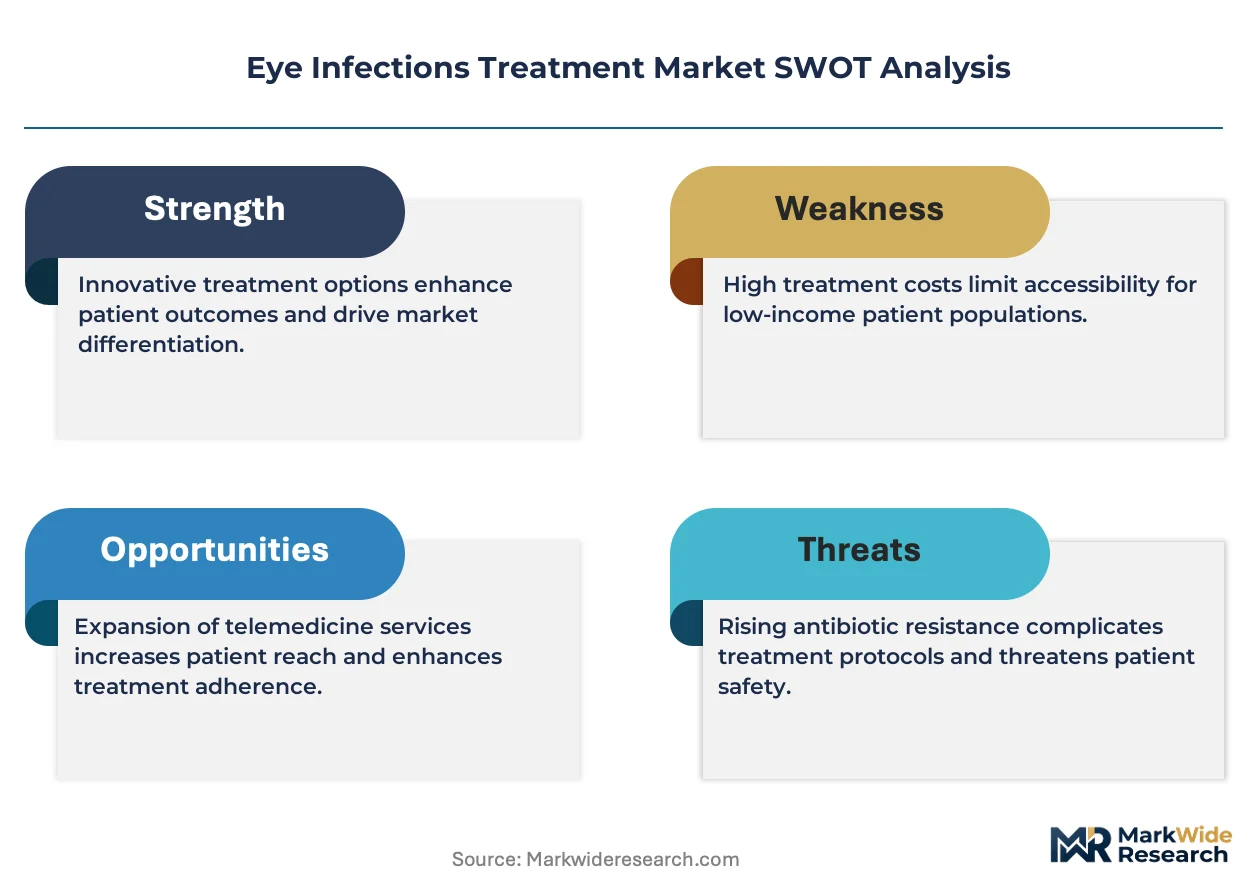
The FDA enforces Current Good Manufacturing Practice standards for sterile ophthalmic products, compelling manufacturers to validate aseptic processing and container-closure integrity. The EMA's ophthalmic working party guidelines on quality specifications for topical ocular formulations shape European market entry requirements. The EU MDR classification of active implantable and high-risk devices extends scrutiny to combination drug-device delivery systems. Stakeholders must monitor evolving regulatory convergence between pharmaceutical purity standards and medical device quality management systems to anticipate compliance cost trajectories.
Market Dynamics
FDA sterility mandates for ophthalmic manufacturing are compressing development timelines while forcing capital redeployment toward aseptic processing infrastructure. This regulatory pressure intersects with hospital procurement upgrades for infectious disease protocols.
Growth Catalysts
- Hospital procurement modernization:Healthcare systems in the United States are expanding infectious disease protocols to incorporate advanced ophthalmic therapeutics for severe keratitis cases.
- EMA quality guidelines:The ophthalmic working party specifications for topical ocular formulations are standardizing European market entry and reducing regulatory fragmentation.
- Biologics pipeline maturation:Monoclonal antibody development for severe infectious indications is expanding addressable patient populations beyond antibiotic-responsive cases.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing for fluoroquinolone formulations clusters among Asian contract manufacturers, creating single-source vulnerability.
- Container-closure integrity validation costs:FDA Current Good Manufacturing Practice requirements for sterile ophthalmic products demand specialized equipment for extractables and leachables testing.
- Topical corticosteroid substitution:Off-label use of generic anti-inflammatory drops for viral conjunctivitis diverts prescriptions from indicated antiviral therapies.
Strategic Opportunities
- Homecare administration expansion:Patient-administered sustained-release depot formulations address compliance gaps in chronic blepharitis management.
- Japan's PMDA regenerative medicine framework:Accelerated review pathways for cell-based corneal infection therapies reduce time-to-market for biologic innovators.
- Teleophthalmology integration:Remote diagnostic platforms in rural United States markets enable earlier infection detection and prescription initiation.
Industry Challenges
- Aseptic processing workforce scarcity:Sterile manufacturing technicians with ophthalmic formulation experience command premium compensation and extended recruitment cycles.
- Combination product classification complexity:EU MDR scrutiny of drug-device delivery systems extends regulatory timelines for novel sustained-release platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Infections Treatment Market |
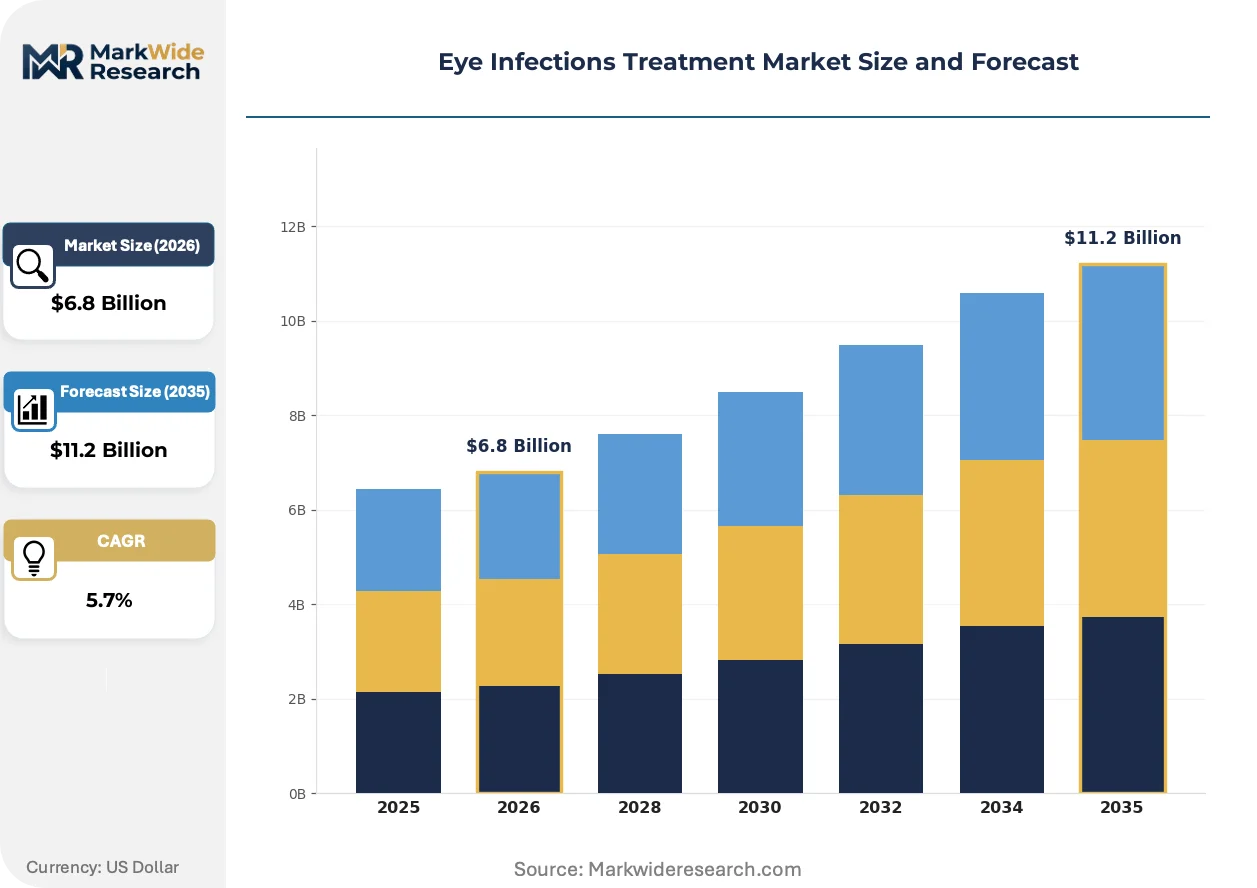
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antivirals, Corticosteroids Delivery Mode: Topical, Oral, Injectable, Ophthalmic Solutions End User: Clinics, Hospitals, Homecare, Pharmacies Indication: Conjunctivitis, Keratitis, Uveitis, Endophthalmitis |
| Companies Covered | Bausch + Lomb, Alcon Laboratories Inc., Novartis AG, Pfizer Inc., Johnson & Johnson Inc., Santen Pharmaceutical Co., Ltd., Regeneron Pharmaceuticals, Inc., Sun Pharmaceutical Industries Ltd., Allergan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Infections Treatment Market Emerging Trajectories
Sustained-release drug delivery platforms are compressing conventional dosing regimens while regulatory convergence between pharmaceutical and device standards rewrites compliance architectures. These forces reshape competitive investment priorities across the value chain.
Intracanalicular inserts and punctal plugs with embedded antibiotic reservoirs are displacing hourly drop instillation regimens for bacterial keratitis. Hospital outpatient departments in Germany and the United States are piloting these platforms for post-surgical prophylaxis. The technology is displacing conventional topical solutions in premium therapeutic tiers where compliance failure drives recurrence.
EU MDR classification rules for active implantable devices now capture combination drug-delivery systems previously regulated as pharmaceuticals alone. Manufacturers must establish quality management systems spanning both drug GMP and device ISO 13485 standards. European ophthalmic specialists are responding by segregating product pipelines into pharmaceutical-only and combination-device tracks to isolate regulatory risk.
Hospital formularies are consolidating vendor relationships around full-service infectious disease portfolios rather than single-product procurement. United States academic medical centers are negotiating multi-therapeutic agreements spanning antibiotics, antivirals, and antifungals. This concentration is most visible in tertiary eye care centers where pharmacy and therapeutics committees prioritize supply chain simplification over product-level differentiation.
Eye Infections Treatment Market Segmentation
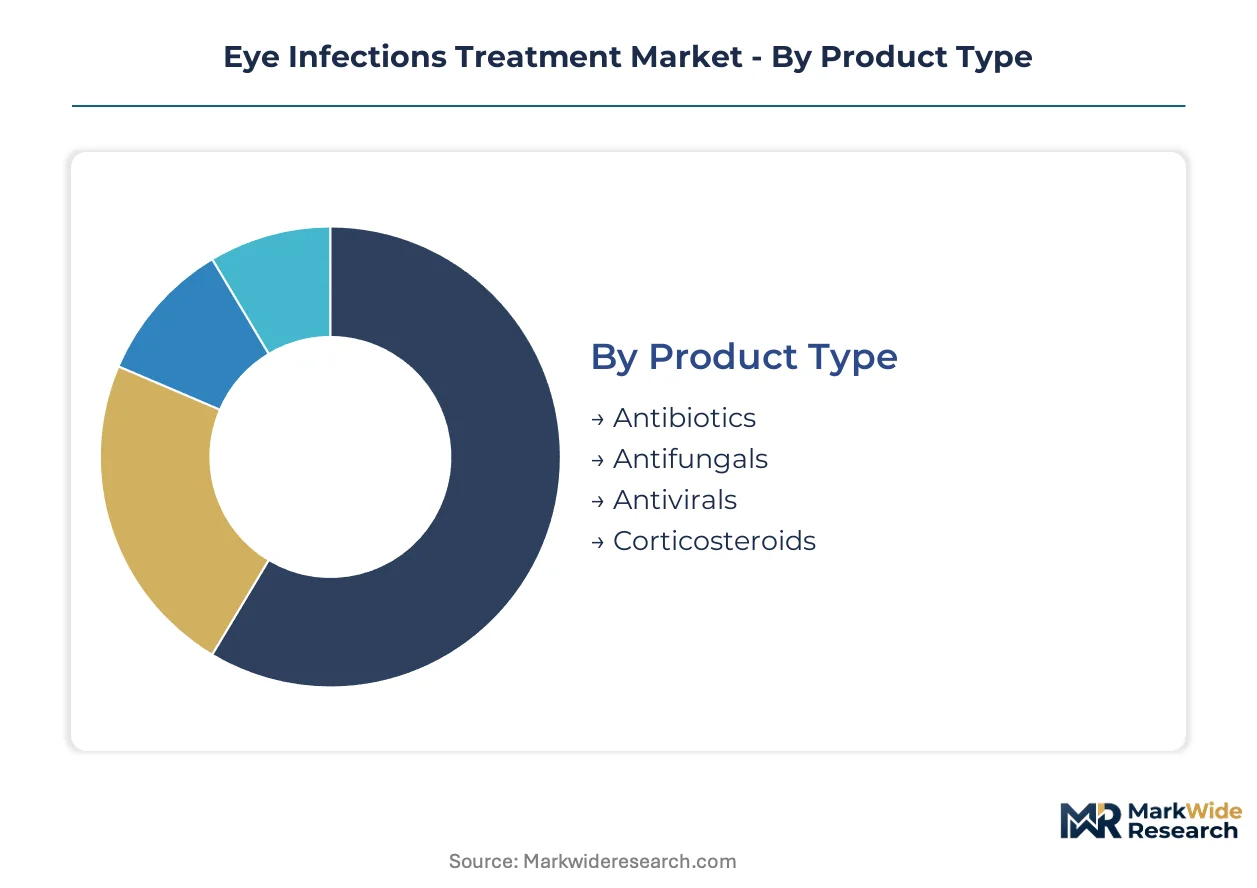
Segmentation in the eye infections treatment market reveals distinct substitution pressures across therapeutic classes, with generic alternatives and off-label prescribing reshaping competitive dynamics. Understanding where interchangeability concentrates guides portfolio prioritization and regulatory defense strategies for stakeholders.
Product Type:
Antibiotics face the most acute substitution pressure from fluoroquinolone generics, while biologics and novel antifungals maintain stronger therapeutic moats against interchangeability.
- Antibiotics:Fluoroquinolone and aminoglycoside formulations target bacterial conjunctivitis and keratitis pathogens with established efficacy profiles. Hospital procurement in the United States favors these agents for severe bacterial keratitis, though generic price erosion compresses margins in outpatient settings.
- Antifungals:Natamycin and amphotericin B preparations address filamentous fungal keratitis, a sight-threatening condition requiring prolonged therapy. Demand concentrates in tertiary eye care centers in Germany and the United States where diagnostic capacity supports appropriate initiation.
- Antivirals:Ganciclovir and trifluridine agents target herpetic keratitis and other viral presentations.
- Corticosteroids:Prednisolone and dexamethasone formulations modulate inflammatory cascades in infectious complications.
Antibiotics anchor the volume base while antifungals gain share at the steepest rate amid rising contact lens-related fungal keratitis incidence.
Delivery Mode:
Cost tier stratification separates premium implantable systems from commodity topical solutions, with reimbursement thresholds determining access expansion.
- Topical:Eye drops and ointments deliver direct ocular surface application with favorable patient compliance profiles for acute bacterial conjunctivitis. Homecare segments in the United States drive volume through patient-administered regimens, though hourly instillation requirements burden adherence in severe keratitis.
- Ophthalmic Solutions:Buffered, isotonic preparations preserve corneal epithelium integrity through pH-balanced formulations. Hospital outpatient departments in academic medical centers specify these for post-surgical prophylaxis where sterility assurance commands premium positioning.
- Injectable:Intravitreal and subconjunctival administration targets severe infectious presentations including endophthalmitis.
- Oral:Systemic agents supplement topical therapy in deep stromal infections or orbital involvement.
Topical formulations dominate prescription volume while ophthalmic solutions capture the highest value per dose in institutional procurement.
End User:
Customer type fragmentation creates divergent purchasing behaviors, with consolidated hospital formularies contrasting dispersed retail pharmacy decision-making.
- Hospitals:Academic medical centers and tertiary eye care facilities procure advanced therapeutics for severe infectious disease protocols. United States pharmacy and therapeutics committees increasingly negotiate multi-therapeutic agreements spanning antibiotics, antivirals, and antifungals to simplify supply chains.
- Homecare:Patient-administered therapies address chronic blepharitis and recurrent conjunctivitis outside institutional settings. Sustained-release depot formulations are expanding this segment by closing compliance gaps that drive recurrence.
- Clinics:Ophthalmology and optometry practices manage uncomplicated presentations with first-line topical agents.
- Pharmacies:Retail dispensing channels handle generic antibiotic fulfillment for acute bacterial conjunctivitis.
Hospitals anchor the revenue base while homecare expands most quickly through patient-administered sustained-release innovations.
Indication:
Maturity gradients separate well-managed common presentations from complex sight-threatening conditions requiring specialized therapeutic escalation.
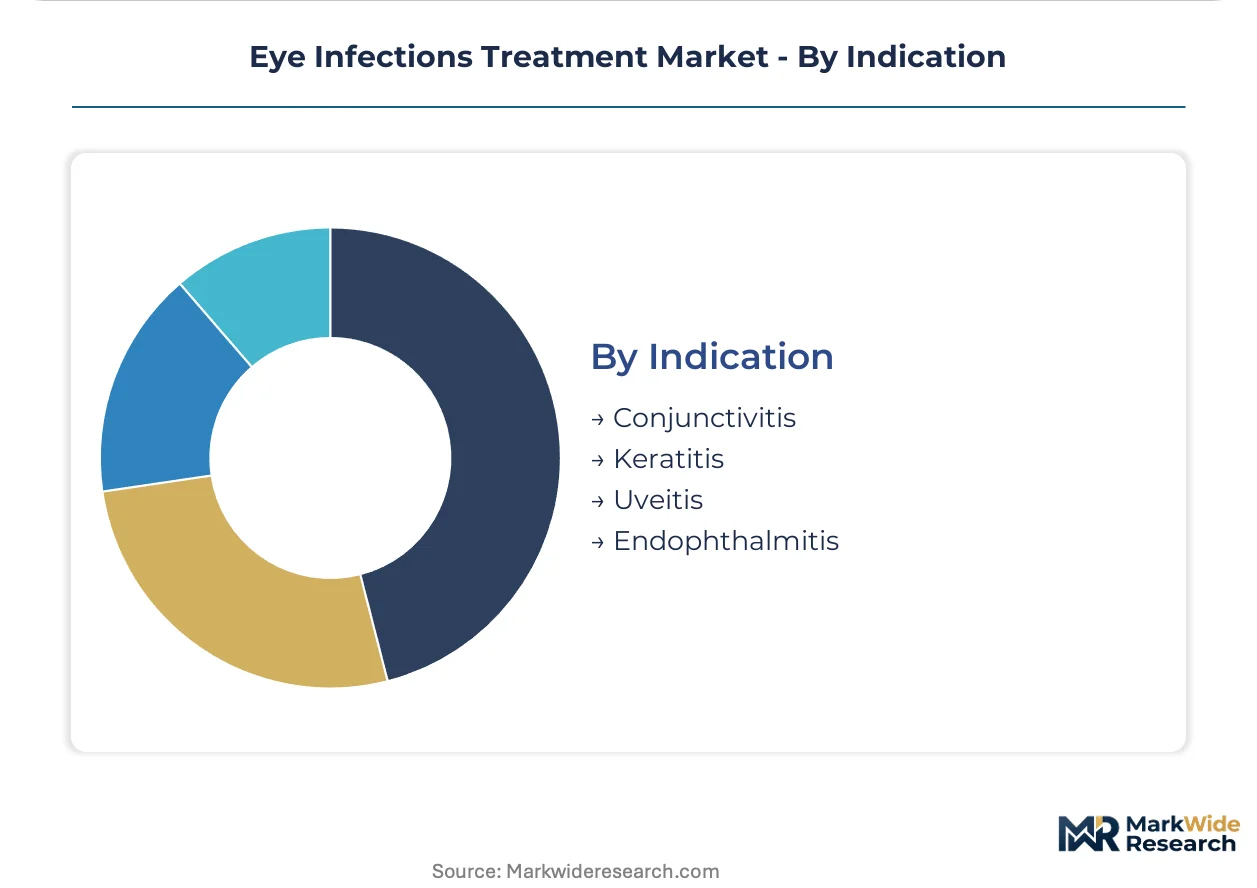
- Conjunctivitis:Bacterial, viral, and allergic presentations drive the highest prescription volumes with generally favorable prognoses. United States retail pharmacy channels dispense predominantly generic antibiotics for bacterial cases, though viral etiologies see off-label corticosteroid substitution that diverts antiviral prescribing.
- Keratitis:Infectious corneal inflammation spans bacterial, fungal, and protozoan etiologies with vision-threatening potential. Hospital-based corneal specialists in Germany and the United States manage severe cases with combination antimicrobial and anti-inflammatory protocols.
- Uveitis:Intraocular inflammation requires systemic or injectable therapy alongside infectious workup.
- Endophthalmitis:Intraocular infection constitutes an ophthalmic emergency demanding immediate surgical and medical intervention.
Conjunctivitis anchors the volume base while keratitis gains share at the steepest rate amid contact lens wear expansion and diagnostic refinement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium therapeutics with limited substitution, while Indian and Brazilian markets drive volume through accessible antibiotics. German and Japanese procurement balances innovation access with formulary discipline.
United States
Academic medical centers in Boston and Baltimore anchor demand for advanced ophthalmic biologics. FDA sterility mandates compress development timelines while forcing capital redeployment toward aseptic processing infrastructure. The Philadelphia-New York corridor concentrates pharmaceutical manufacturing for sterile ophthalmic preparations.
Germany
Tertiary eye care centers in Heidelberg and Tübingen manage severe fungal keratitis with combination antimicrobial protocols. EMA quality specifications for topical ocular formulations standardize market entry requirements across European member states. The Rhine-Main region hosts specialized contract manufacturers for ophthalmic solutions.
Japan
Corneal specialists in Tokyo and Osaka pioneer sustained-release depot formulations for chronic blepharitis. PMDA's regenerative medicine framework accelerates review pathways for cell-based infection therapies. The Kansai region concentrates ophthalmic device development alongside pharmaceutical formulation expertise.
India
Retail pharmacy channels in Mumbai and Delhi dispense generic fluoroquinolones for bacterial conjunctivitis at price points inaccessible to innovator products. CDSCO manufacturing standards for sterile ophthalmic products tighten compliance requirements for domestic producers. The Hyderabad-Bengaluru corridor clusters active pharmaceutical ingredient synthesis for antibiotic formulations.
Brazil
Public health systems in São Paulo and Rio de Janeiro prioritize cost-effective antibiotic access for epidemic conjunctivitis. ANVISA's alignment with FDA sterility standards elevates quality requirements for imported ophthalmic products. The Southeast region concentrates distribution infrastructure for pharmaceutical imports from Asian contract manufacturers.
Eye Infections Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Large pharmaceutical conglomerates leverage global manufacturing scale and raw material access, while focused ophthalmic specialists anchor positions through deep disease-state expertise. The market structures around three archetypes: diversified pharma majors, pure-play ocular specialists, and generic manufacturers with ophthalmic portfolios. Dominant competitive moves include biologics pipeline maturation and sustained-release platform development.
Among diversified pharmaceutical majors, Pfizer Inc. and Novartis AG occupy positions defined by manufacturing scale and therapeutic breadth. Santen Pharmaceutical Co., Ltd. exemplifies the pure-play specialist archetype with concentrated ocular surface disease focus. Sun Pharmaceutical Industries Ltd. represents the generic-anchored model with volume-driven ophthalmic portfolios. These three archetypes compete through divergent resource allocation: conglomerates deploy capital toward biologics infrastructure, specialists deepen formulation expertise, and generic players optimize cost positions in commoditized antibiotic segments.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Alcon Laboratories Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Regeneron Pharmaceuticals, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Allergan |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at aseptic processing facilities in the United States and Germany determines price floors for sterile ophthalmic preparations, with underutilized lines accepting contract manufacturing at compressed margins while fully loaded sites command premium positioning for complex biologic formulations.
Pricing Analysis
After-sales revenue from hospital formulary maintenance contracts and clinical education services drives lifetime value beyond unit sales. Three-tier pricing structure across premium biologic, standard branded, and economy generic levels segments the market by therapeutic complexity and reimbursement tier. Cost compression in fluoroquinolone generics intensifies because Indian API manufacturers expand output, while price insensitivity concentrates in United States academic medical centers where clinical outcomes override procurement cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate for high-turnover topical antibiotics, while strategic stockpiling of antifungal APIs buffers against agricultural demand competition for natamycin. Active pharmaceutical ingredient synthesis clusters in India and China, with sterile formulation finishing concentrated in the United States and Germany. Fluoroquinolone precursors, specialized glass vials, and preservative compounds constitute critical input dependencies. Single-source vulnerability in aminoglycoside fermentation capacity threatens supply continuity. Distribution runs through hospital GPO contracts and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of sterile manufacturing technicians with ophthalmic formulation expertise constrains output expansion and creates acquisition premiums for qualified facilities, positioning human capital as the decisive competitive moat.
For Market Incumbents: Consolidate manufacturing footprints around high-utilization aseptic processing hubs in the Philadelphia-New York corridor and Rhine-Main region to absorb fixed costs across broader product portfolios. Acquire specialized contract manufacturers in Japan's Kansai region to capture PMDA accelerated review pathways for cell-based therapies. Channel control through exclusive hospital formulary agreements defends against generic substitution in the conjunctivitis segment.
For New Entrants and Emerging Players: Lead with sustained-release depot formulations for chronic blepharitis management, where compliance gaps in hourly drop regimens create addressable white space. Target homecare administration expansion in rural United States markets enabled by teleophthalmology diagnostic platforms. Pursue licensing arrangements with Japanese device developers to shortcut combination product regulatory complexity under EU MDR.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play ophthalmic specialists with hospital formulary maintenance contracts and regenerative medicine pipelines under PMDA review. Long-term viability hinges on biologics infrastructure rather than commoditized antibiotic exposure. Acquisition targets should demonstrate captive aseptic processing capacity and active IND filings for severe infectious indications. The signal to watch is FDA warning letter frequency at sterile ophthalmic facilities, which predicts supply disruption and pricing volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Capacity Expansion | Hospital procurement upgrades for infectious disease protocols absorb expanded sterile output in the United States. |
| Biologics Pipeline Diversification | Monoclonal antibody development for severe keratitis extends addressable populations beyond antibiotic-responsive cases. |
| Regulatory Convergence Preparation | EU MDR quality management systems spanning drug GMP and device ISO 13485 standards reduce combination product timelines. |
| Teleophthalmology Platform Integration | Remote diagnostic deployment in rural United States markets enables earlier infection detection and prescription capture. |
| API Backward Integration | Captive fluoroquinolone precursor production insulates against Asian contract manufacturer concentration risk. |
Methodological Framework
Operator-level perspectives from sterile manufacturing technicians, hospital pharmacy and therapeutics committee members, ophthalmic formulary directors, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA warning letter databases, EMA ophthalmic working party guidelines, ClinicalTrials.gov entries, and hospital procurement contract disclosures. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across API price volatility scenarios and regulatory approval delay assumptions throughout the projection horizon. Segmentation dimensions modeled encompassed product type, delivery mode, end-user channel, and indication severity tier. CAGRs derived from therapeutic class growth differentials and regional reimbursement trajectory assessments. Forecast inputs incorporated contact lens wear prevalence trends and diagnostic capacity expansion timelines.
Underlying assumptions cover sterility standard enforcement continuity and hospital procurement consolidation pace, with deviation risk concentrated in FDA manufacturing inspection intensity and EMA MDR implementation variability. Revision becomes warranted when aseptic processing workforce scarcity crosses thresholds that constrain biologics launch schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Nystagmus Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Astigmatism Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Ocular Inserts Market