
 Brazil Ophthalmic Devices Market | 2026-2036
Brazil Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Ophthalmic Devices Market Outlook
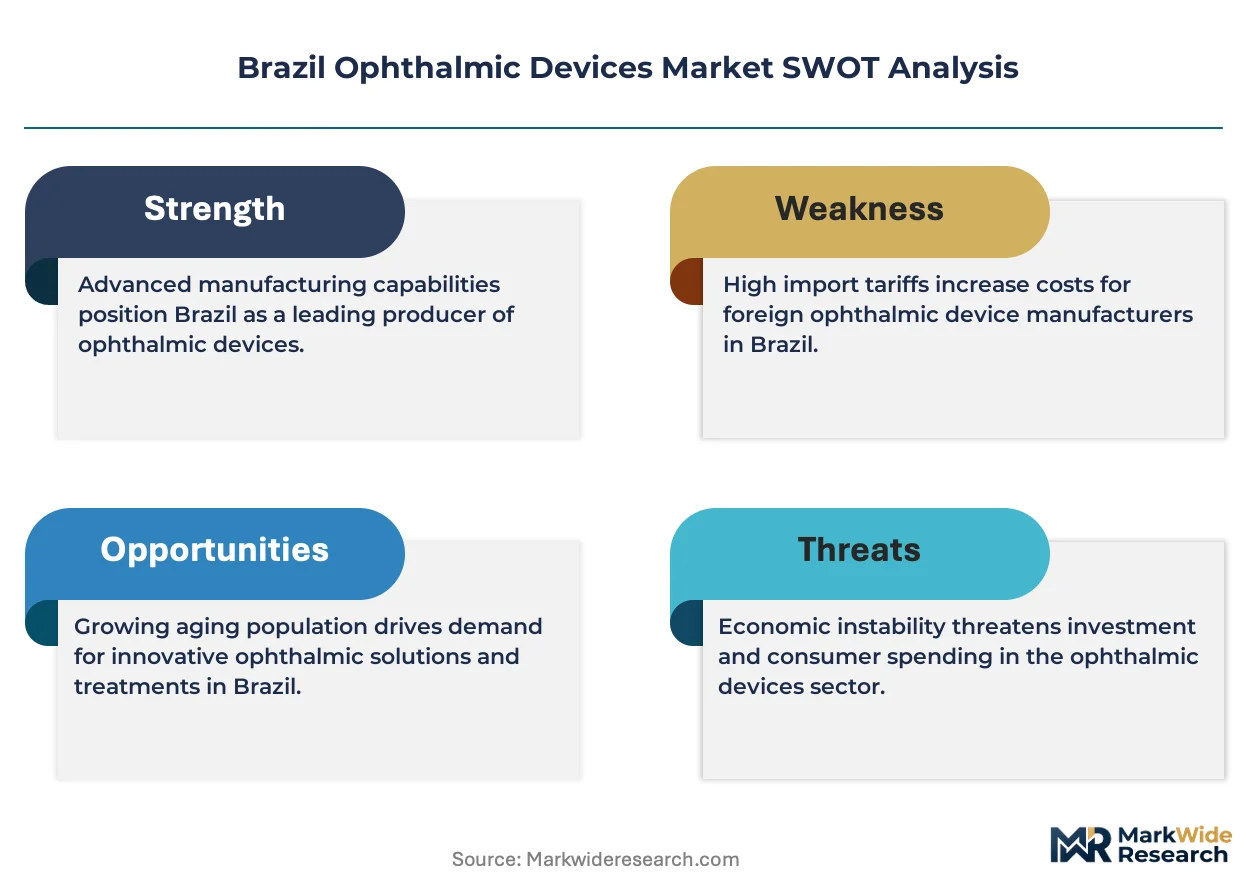
Buyer concentration among private hospital networks is pivoting toward fragmented procurement across independent clinics and ambulatory surgical centers. Alcon Inc anchors its position through captive supply of surgical consumables to large ophthalmology chains. Bausch + Lomb competes aggressively on contact lens portfolios distributed through retail optometry. Phelcom Technologies differentiates through locally manufactured fundus cameras designed for Brazil's public health diagnostic networks.
Ophthalmic devices comprise precision instruments for vision correction, disease diagnosis, and surgical intervention, typically incorporating optical-grade polymers, excimer laser systems operating at 193 nanometer wavelength, and micron-scale positioning mechanics to restore or preserve visual function. Intraocular lenses dominate value generation due to irreversible demand tied to age-related cataract prevalence. Diagnostic imaging segments led by optical coherence tomography are expanding fastest as glaucoma and retinal disease screening protocols deepen in outpatient settings. Laser technology maintains mature margins within refractive surgery suites where equipment replacement cycles extend beyond seven years.
ANVISA governs medical device registration and post-market surveillance, while the Brazilian Ministry of Health directs procurement through the SUS public system, creating dual-track demand dynamics across private and public channels. ISO 13485 certification and INMETRO conformity assessments shape supplier eligibility, filtering market access toward manufacturers with established quality management systems. Stakeholders must track how ANVISA's alignment with Mercosur harmonization protocols reshapes import documentation requirements for multinational suppliers.
Market Dynamics
ANVISA's compressed approval timelines for imported intraocular lenses are accelerating product registration velocity while simultaneously fragmenting procurement authority away from consolidated hospital networks toward independent ambulatory surgical centers across southeastern Brazil.
Growth Catalysts
- Aging Demographics:Irreversible demand for cataract intervention concentrates in São Paulo and Minas Gerais, where patient volumes exceed public health system surgical capacity and channel excess toward private providers.
- ANVISA Registration Reform:Streamlined pathways for Mercosur-harmonized medical device documentation are reducing import clearance friction for multinational intraocular lens manufacturers.
- Diagnostic Imaging Modernization:Optical coherence tomography systems are penetrating outpatient glaucoma screening protocols as retinal disease detection becomes standard in ophthalmology chain expansion plans.
Market Restraints
- Import Dependency:Excimer laser systems and premium intraocular lens raw materials concentrate supply among German and Swiss precision optics manufacturers, exposing buyers to currency volatility and shipping friction.
- Technical Limitation:Micron-scale positioning mechanics in femtosecond laser platforms require specialized biomedical engineering expertise that remains scarce in Brazilian technical training pipelines.
- Regulatory Friction:INMETRO conformity assessments for electro-medical equipment impose parallel certification requirements that extend commercialization timelines beyond ANVISA registration completion.
Strategic Opportunities
- Public Health Network Penetration:SUS procurement channels for fundus cameras and basic diagnostic equipment remain underpenetrated by premium manufacturers, creating volume opportunities through locally adapted product tiers.
- Technology Convergence:Integration of artificial intelligence image analysis with optical coherence tomography hardware is enabling automated glaucoma progression monitoring that reduces specialist interpretation burden.
- Retail Optometry Channel:Contact lens distribution through independent optometry practices bypasses hospital procurement committees and captures recurring revenue streams from myopia management protocols.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Servicing excimer laser platforms and femtosecond surgical systems requires specialized training that outpaces Brazilian technical education program output.
- ISO 13485 Certification Burden:Quality management system audits for multinational supplier status demand sustained documentation investment that strains mid-scale domestic manufacturers.
- Legacy Equipment Integration:New diagnostic imaging platforms must interface with fragmented hospital information systems across independent clinic networks, complicating deployment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Ophthalmic Devices Market |
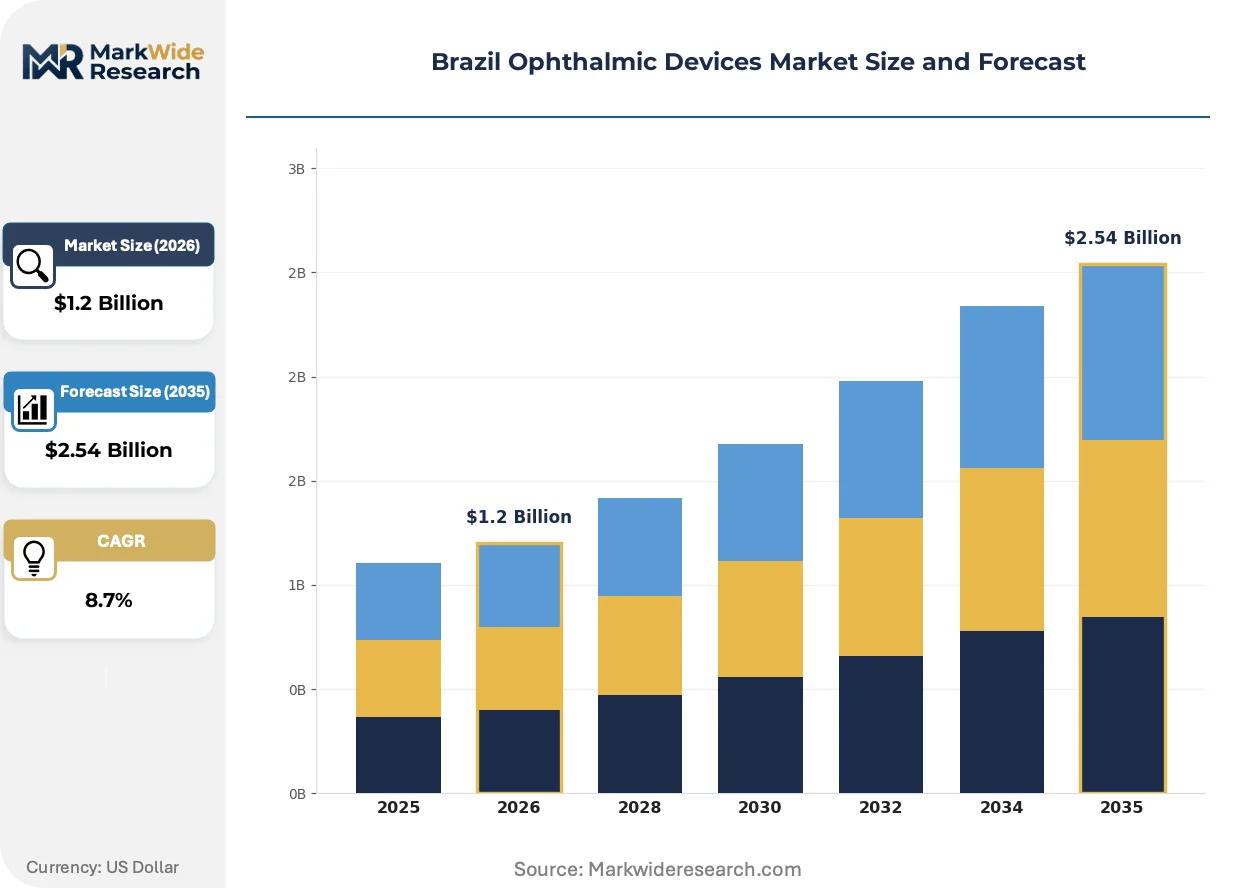
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Glaucoma Devices, Retinal Surgery Devices, Ophthalmic Drugs Technology: Laser Technology, Diagnostic Imaging, Optical Coherence Tomography, Wavefront Technology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesalers, Medical Distributors |
| Companies Covered | Bausch + Lomb, Nidek Co Ltd, Alcon Inc, Ziemer Ophthalmic Systems AG, Topcon Corporation, Johnson & Johnson Vision Care, EssilorLuxottica, Phelcom Technologies, Carl Zeiss Meditec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Ophthalmic Devices Market Strategic Shifts
Technological substitution in surgical visualization, regulatory alignment with international standards, and procurement decentralization are simultaneously compressing equipment replacement cycles and expanding addressable patient populations beyond traditional hospital settings.
Extended-depth-of-focus intraocular lenses are rewriting presbyopia-correcting cataract surgery economics by eliminating spectacle dependency for intermediate vision tasks. Private ophthalmology chains in São Paulo are adopting these platforms at replacement cycle compression rates that outpace conventional monofocal lens procurement. The technology is rewriting premium pricing structures by bundling refractive outcomes into mandatory cataract reimbursement categories.
ANVISA's progressive alignment with Mercosur harmonization protocols is eliminating redundant technical documentation for intraocular lens and diagnostic imaging imports. This regulatory convergence reduces registration preparation costs for European and North American manufacturers while accelerating competitive entry timelines. Multinational suppliers are responding by prioritizing Brazil as a lead launch market for next-generation optical coherence tomography platforms.
Independent clinic procurement committees are displacing centralized hospital network purchasing departments as the dominant equipment decision-making bodies. Ambulatory surgical centers in Minas Gerais and Rio de Janeiro are negotiating direct manufacturer relationships that bypass traditional distributor markups. This channel fragmentation is most visible in diagnostic imaging segments where capital equipment financing flexibility determines vendor selection.
Brazil Ophthalmic Devices Market Segmentation
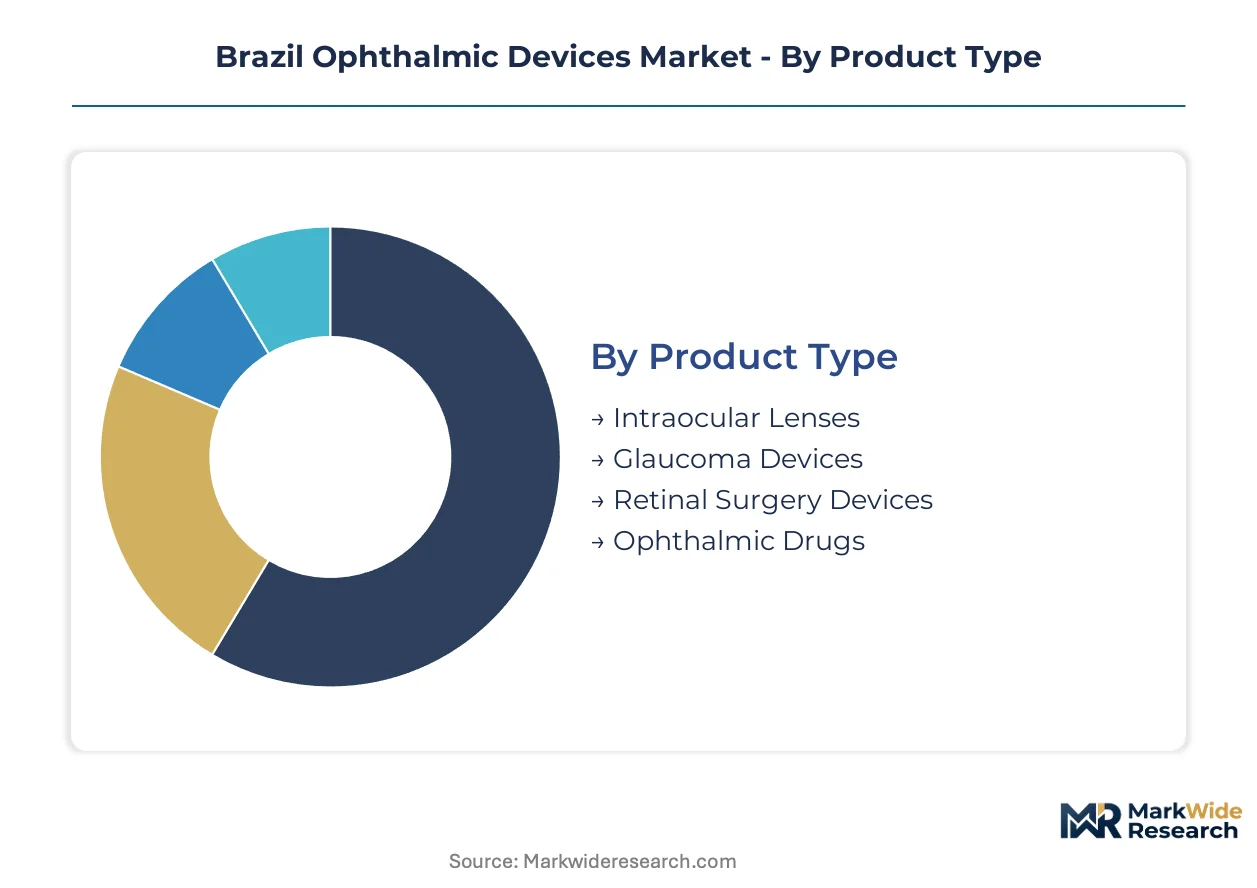
Ophthalmic device segmentation in Brazil reflects dual-track regulatory pressure where ANVISA registration timelines and INMETRO conformity requirements filter market access differently across product categories. Procurement decentralization toward independent clinics and ambulatory surgical centers is fragmenting traditional volume concentration patterns.
Product Type:
INMETRO conformity assessments and ANVISA registration pathways impose divergent documentation burdens across implantable versus non-implantable categories, with intraocular lenses facing the most stringent perpetual surveillance requirements.
- Intraocular Lenses:Precision-molded optical-grade polymers restore visual function through cataract replacement surgery. São Paulo private ophthalmology chains are compressing replacement cycles for extended-depth-of-focus platforms as presbyopia-correcting economics rewrite premium pricing structures.
- Glaucoma Devices:Implantable drainage systems and sustained-release drug delivery platforms manage intraocular pressure progression. Minas Gerais ambulatory surgical centers are expanding procedural volume for minimally invasive glaucoma surgery as specialist training pipelines deepen.
- Retinal Surgery Devices:Vitrectomy packs and membrane peeling instruments address macular hole and retinal detachment intervention.
- Ophthalmic Drugs:Topical formulations and intravitreal injections complement device-based therapy across chronic disease management protocols.
Leading the category by volume: Intraocular Lenses. Growing fastest: Glaucoma Devices.
Technology:
Capital intensity and service infrastructure requirements stratify adoption patterns, with diagnostic imaging platforms penetrating outpatient settings faster than surgical laser systems requiring dedicated facility investment.
- Laser Technology:Excimer systems operating at 193 nanometer wavelength and femtosecond platforms enable refractive and cataract surgical precision. Currency volatility against Swiss and German precision optics suppliers is extending equipment replacement cycles beyond seven years in southeastern hospital networks.
- Optical Coherence Tomography:Non-invasive cross-sectional retinal imaging systems automate glaucoma progression monitoring. Rio de Janeiro ophthalmology chains are prioritizing AI-integrated platforms that reduce specialist interpretation burden in high-volume screening protocols.
- Diagnostic Imaging:Fundus cameras and slit-lamp biomicroscopy systems support disease detection across public health networks.
- Wavefront Technology:Aberrometry-guided treatment planning customizes refractive surgical outcomes.
Dominating capital expenditure: Laser Technology. Expanding most quickly: Optical Coherence Tomography.
End User:
Procurement authority fragmentation is redistributing equipment decision-making from consolidated hospital purchasing committees toward independent clinic administrators with financing flexibility priorities.
- Hospitals:Integrated surgical suites and diagnostic departments within multi-specialty institutions. SUS public system capacity constraints in São Paulo are channeling excess cataract volumes toward private providers, moderating capital expansion urgency.
- Clinics:Dedicated ophthalmology practices with focused diagnostic and minor surgical capabilities. Independent networks in Minas Gerais are negotiating direct manufacturer relationships that bypass traditional distributor markups on imaging equipment.
- Ambulatory Surgical Centers:Same-day procedure facilities optimized for cataract and refractive intervention volume.
- Research Institutions:Academic medical centers driving clinical trial recruitment and technology validation protocols.
Capturing highest absolute spend: Hospitals. Gaining share fastest: Ambulatory Surgical Centers.
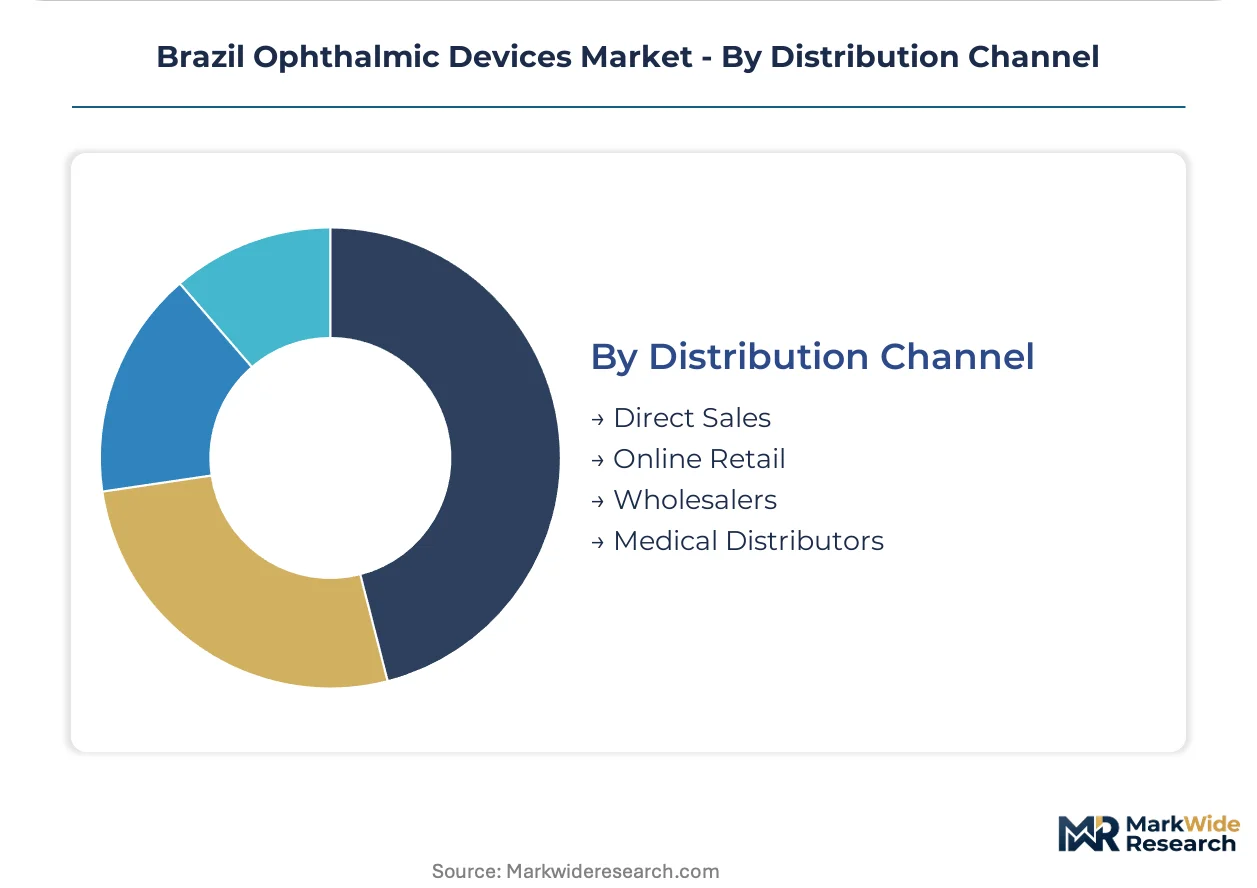
Distribution Channel:
Channel economics reflect equipment capital intensity versus consumable replenishment frequency, with direct relationships dominating high-value surgical platforms and intermediary networks handling routine supply logistics.
- Direct Sales:Manufacturer field teams negotiate capital equipment placement and consumable bundling agreements. Alcon and Bausch + Lomb deploy dedicated Brazil sales organizations to anchor large ophthalmology chain relationships.
- Medical Distributors:Specialized intermediaries manage import logistics and local inventory for multinational suppliers. ANVISA registration reform is accelerating distributor onboarding timelines for European intraocular lens manufacturers.
- Wholesalers:Broad-line medical supply aggregators serving fragmented independent practice segments.
- Online Retail:E-commerce platforms capturing contact lens and low-risk accessory replenishment demand.
Controlling premium equipment flow: Direct Sales. Expanding route-to-market breadth: Medical Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical-grade polymer feedstock for intraocular lens manufacturing concentrates in southeastern Brazil, where São Paulo's chemical processing corridor supplies precision-molded components to domestic and multinational device assemblers.
São Paulo
Private ophthalmology chains drive diagnostic imaging procurement as cataract surgery volumes exceed SUS public system capacity. ANVISA's streamlined registration pathways accelerate import clearance for European intraocular lens manufacturers. The metropolitan corridor hosts the densest concentration of ambulatory surgical centers negotiating direct manufacturer relationships.
Minas Gerais
Independent clinics expand minimally invasive glaucoma surgery capacity as specialist training pipelines deepen across Belo Horizonte medical centers. INMETRO conformity assessments for electro-medical equipment filter supplier eligibility toward ISO 13485-certified manufacturers. Diagnostic imaging equipment financing flexibility determines vendor selection in this fragmented procurement environment.
Rio de Janeiro
Ophthalmology chains prioritize AI-integrated optical coherence tomography platforms to reduce specialist interpretation burden in high-volume screening protocols. ANVISA's Mercosur harmonization alignment compresses documentation requirements for multinational suppliers. Capital equipment replacement cycles for excimer laser systems extend beyond seven years due to currency volatility against Swiss precision optics suppliers.
Rio Grande do Sul
Hospital networks modernize cataract surgery infrastructure as aging demographics concentrate irreversible demand for presbyopia-correcting interventions. The Brazilian Ministry of Health directs SUS procurement for basic diagnostic equipment through regional distribution hubs. Porto Alegre's medical device service ecosystem supports maintenance of femtosecond laser platforms requiring scarce biomedical engineering expertise.
Bahia
Public health diagnostic networks remain underpenetrated by premium manufacturers, creating volume opportunities through locally adapted product tiers. SUS procurement channels for fundus cameras prioritize cost efficiency over advanced feature integration. Salvador's ophthalmology service expansion lags southeastern corridors but attracts distributor investment for mid-tier imaging equipment.
Brazil Ophthalmic Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-integrated diagnostic platforms and locally manufactured alternatives. The market structure concentrates around multinational surgical consumable suppliers and specialized diagnostic equipment fabricators. Three archetypes dominate: integrated ophthalmology conglomerates with captive supply chains, precision optics specialists with excimer laser expertise, and domestic diagnostic manufacturers serving public health networks. Competitive moves center on direct sales force expansion into independent clinic channels and strategic partnerships with ambulatory surgical center networks.
Among Switzerland-based precision optics specialists, Ziemer Ophthalmic Systems AG occupies a position exemplifying femtosecond laser platform expertise. Carl Zeiss Meditec AG represents the integrated diagnostic-surgical archetype with established field service infrastructure. Phelcom Technologies anchors the domestic manufacturing tier, illustrating locally adapted production for Brazil's public health procurement channels. These three entities collectively represent the geographic and strategic diversity shaping vendor selection criteria across private and SUS-funded purchasing committees.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Nidek Co Ltd |
| Alcon Inc |
| Ziemer Ophthalmic Systems AG |
| Topcon Corporation |
| Johnson & Johnson Vision Care |
| EssilorLuxottica |
| Phelcom Technologies |
| Carl Zeiss Meditec AG |
| Others |
Value Chain & Pricing Dynamics
Optical-grade polymer feedstock costs for intraocular lens manufacturing flow from São Paulo's chemical processing corridor through three distinct pricing tiers downstream, with premium extended-depth-of-focus platforms commanding bundled service premiums while economy monofocal lenses compete on raw material efficiency alone.
Pricing Analysis
Extended warranty and field service bundling separates premium femtosecond laser platforms from unbundled diagnostic imaging equipment across Brazilian procurement committees. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and ANVISA registration completeness rather than functional performance alone. Cost compression in standard-tier intraocular lenses is intensifying because independent ambulatory surgical centers negotiate direct manufacturer relationships that bypass traditional distributor markups. Public health networks purchasing through SUS channels exhibit highest price sensitivity, while private ophthalmology chains in São Paulo demonstrate lowest sensitivity due to refractive outcome bundling into mandatory cataract reimbursement categories.
Supply Chain Analysis
Biomedical engineering talent scarcity in Swiss and German precision optics manufacturing regions constrains femtosecond laser platform output capacity for Brazilian buyers. Supply draws from Germany, Switzerland, and the United States for excimer laser systems, optical-grade polymers, and AI-integrated diagnostic imaging components respectively. Single-source vulnerability concentrates in femtosecond laser positioning mechanics requiring micron-scale precision that few suppliers globally can achieve. Distribution runs through direct manufacturer field teams for capital equipment above defined thresholds, with specialized medical distributors handling import logistics and local inventory for consumable replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive supply of surgical consumables and in-house production of diagnostic imaging components represent the decisive upstream and downstream levers players are pursuing to defend margin position.
For Market Incumbents: Deepen captive supply relationships with large ophthalmology chains through consumable bundling agreements that lock in replacement cycle compression for extended-depth-of-focus platforms. Expand ISO 13485-certified manufacturing footprint within Mercosur trade zones to compress ANVISA registration timelines and neutralize emerging domestic competitors like Phelcom Technologies in public health network procurement. For New Entrants and Emerging Players: Begin with SUS procurement channels for fundus cameras and basic diagnostic equipment, where premium manufacturers remain underpenetrated and cost efficiency requirements favor locally adapted product tiers. Target Bahia and northeastern states where ophthalmology service expansion lags southeastern corridors but attracts distributor investment for mid-tier imaging equipment with flexible financing structures. For Investors and Strategic Acquirers: ANVISA's progressive Mercosur harmonization alignment is the leading indicator that registration velocity will accelerate competitive entry timelines for European and North American manufacturers. Acquire domestic diagnostic equipment fabricators with established INMETRO conformity assessment pathways and existing relationships with Brazilian Ministry of Health procurement officers. Watch for femtosecond laser platform service contract renewal rates as the inflection signal for equipment replacement cycle compression in private clinic networks.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Optimization | Streamlined Mercosur-harmonized documentation accelerates market access for multinational intraocular lens manufacturers. |
| Hospital System Partnership | Direct relationships with independent ambulatory surgical centers bypass distributor markups and secure consumable replenishment streams. |
| Software Companion Development | AI-integrated optical coherence tomography platforms reduce specialist interpretation burden in high-volume glaucoma screening protocols. |
| Reimbursement Strategy | Bundling refractive outcomes into mandatory cataract reimbursement categories rewrites premium pricing structures for presbyopia-correcting lenses. |
| CE Marking Pathway | European regulatory alignment enables accelerated parallel registration through ANVISA's Mercosur harmonization protocols. |
Study Parameters
Independent corroboration across ophthalmology chain procurement officers, biomedical engineering service technicians, ANVISA regulatory affairs specialists, and SUS public health network administrators underwrites the qualitative findings presented. Primary interviews with hospital purchasing committees, independent clinic administrators, and GPO contracts managers combined with secondary validation from ANVISA registration databases, INMETRO conformity assessment records, and Brazilian Ministry of Health procurement disclosures. Bottom-up equipment installation tracking and top-down market size triangulation cross-validate segment-level estimates.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and mix shift effects. Segmentation dimensions modeled include product type, technology platform, end-user facility category, and distribution channel structure. CAGRs derive from equipment replacement cycle analysis, patient volume projections tied to aging demographic data, and penetration rate assumptions for AI-integrated diagnostic platforms. Forecast inputs incorporate ANVISA registration timeline compression scenarios and currency volatility assumptions against Swiss and German precision optics suppliers.
Underlying measurement precision varies by segment; intraocular lens and optical coherence tomography categories carry tighter precision than emerging glaucoma device and femtosecond laser platform estimates due to fragmented procurement data availability. Forecasts reflect documented assumptions regarding ANVISA regulatory alignment pace, SUS capacity constraint evolution, and biomedical engineering talent pipeline development. Material deviation in ANVISA Mercosur harmonization implementation timelines or Swiss franc exchange rate volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Detachment Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Synoptophore Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Ophthalmology Devices Market