
 Ophthalmic Drugs Market | 2026-2036
Ophthalmic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Drugs Market Intelligence
Biologic active pharmaceutical ingredients are recalibrating cost structures across ophthalmic formulation development. Regeneron Pharmaceuticals anchors its position through captive antibody production for retinal disease therapy. F. Hoffmann-La Roche sustains competitive pressure via deep clinical infrastructure in ocular oncology and neovascular indications. Bayer AG differentiates through geographic reach in European ophthalmology markets where biosimilar transition timelines remain fragmented.
Ophthalmic drugs comprise sterile dosage forms—solutions, suspensions, ointments, gels, and implantable depots—engineered for anterior and posterior segment delivery via topical, intravitreal, or periocular routes, with tonicity, pH, and particle size specifications governed by pharmacopeial standards for ocular tolerability. Their primary purpose is to achieve therapeutic concentrations at intraocular target tissues while minimizing systemic exposure and corneal or retinal toxicity. Anti-inflammatory and antiglaucoma categories carry mature volume bases but face margin compression from generic penetration, while intraocular delivery methods command premium positioning due to surgical administration requirements and sustained-release formulation complexity. Homecare and clinic end-user channels are expanding fastest as intravitreal injection protocols shift toward office-based and trained non-hospital settings.
FDA, EMA, and Japan's PMDA enforce divergent sterility, stability, and clinical endpoint standards that fragment development pathways for sustained-release implants and gene therapy candidates. REACH and the EU MDR impose additional material traceability and device-drug combination obligations on European manufacturers, while FDA's ophthalmic guidance on Q1/Q2 sameness shapes generic equivalence battles for complex formulations. Stakeholders must track how regulator divergence on preservative-free multidose container validation and real-world evidence requirements for anti-VEGF biosimilars will reshape competitive timelines and capital allocation across development pipelines.
Market Dynamics
Biologic active pharmaceutical ingredients are recalibrating cost structures across ophthalmic formulation development. Sustained-release implants and gene therapy platforms are redirecting investment from chronic eye drop regimens toward long-acting modalities that reduce treatment burden.
Growth Catalysts
- Anti-VEGF reimbursement frameworks:EMA and national health technology assessment bodies in Germany and France are expanding coverage for biologic prescribing in diabetic macular edema, accelerating clinic adoption of intravitreal protocols.
- Office-based administration:Trained non-hospital settings across the United States, China, and Japan are absorbing injection volume as retina clinics expand capacity outside traditional hospital infrastructure.
- Gene therapy platforms:Viral vector manufacturing scale-up is enabling one-time posterior segment interventions that displace chronic anti-VEGF dependence in inherited retinal disease populations.
Market Restraints
- Cold chain complexity:Biologics require uninterrupted temperature control from fill-finish through intravitreal administration, elevating logistics costs and limiting distribution to certified specialty pharmacies.
- EMA-FDA divergence on device-drug combinations:EU MDR imposes material traceability and notified body review timelines that lag FDA ophthalmic guidance, fragmenting development pathways for sustained-release implants.
- Preservative-free multidose validation:Container closure integrity testing for novel bottle systems adds 18-24 months to generic equivalence timelines, compressing margin recovery windows.
Strategic Opportunities
- Homecare injection training:Self-administration protocols for periocular depot formulations could unlock patient segments in Japan and the United States where clinic access creates treatment gaps.
- Real-world evidence mandates:FDA's evolving posture on anti-VEGF biosimilar approval creates openings for registry-based comparative effectiveness studies that accelerate market entry.
- Dual carbon goals in China:NMPA green chemistry incentives for aqueous manufacturing processes are reshaping API sourcing decisions for multinational ophthalmic portfolios.
Industry Challenges
- Vitreoretinal surgical training pipelines:The specialized skill set required for safe intravitreal injection limits clinic expansion velocity in secondary and tertiary cities.
- Q1/Q2 sameness litigation:Generic equivalence battles for complex suspensions and emulsions consume legal resources and delay portfolio optimization decisions.
- Legacy ERP integration:Serialization requirements under EU MDR and FDA DSCSA are forcing expensive upgrades to manufacturing execution systems at mid-scale sterile facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Drugs Market |
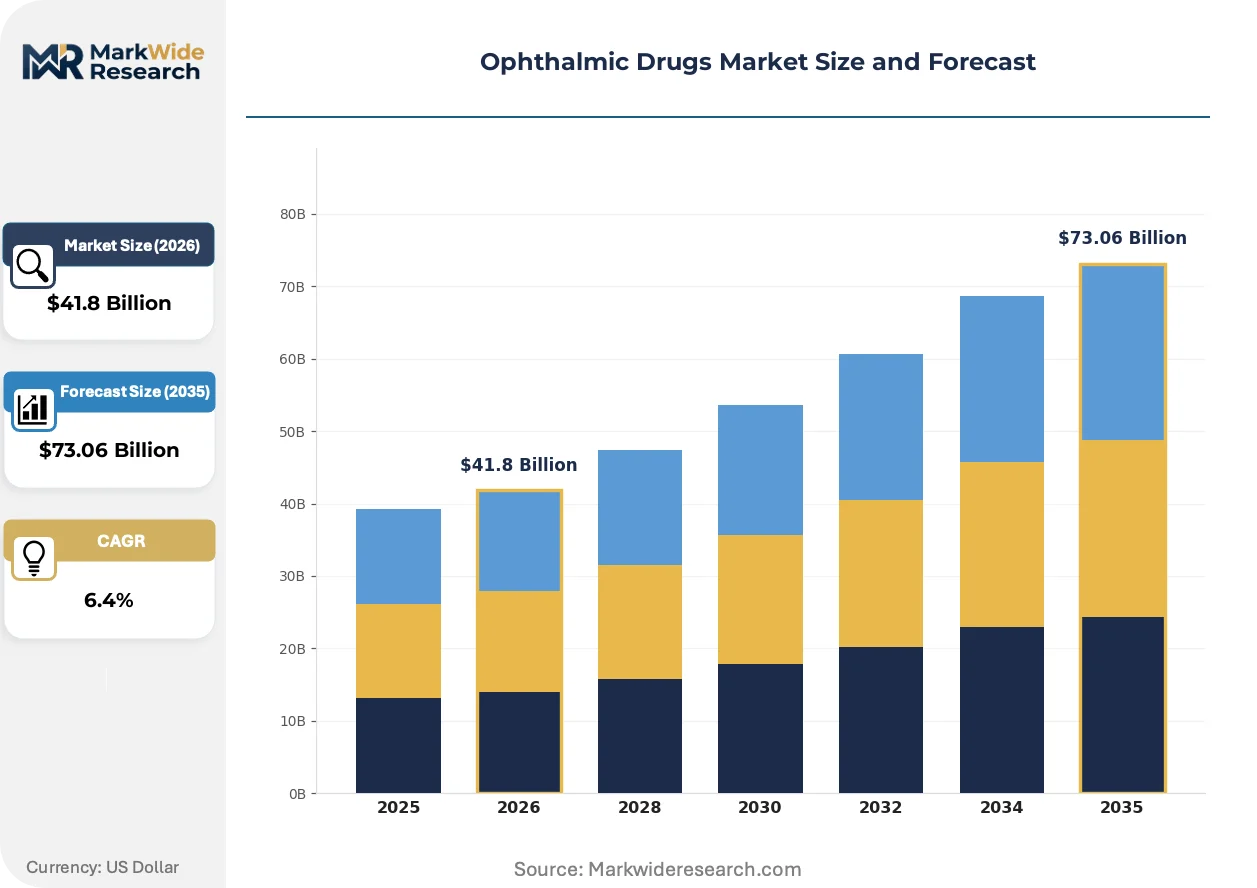
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $73.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiglaucoma, Anti-inflammatory, Antibiotic, Antiviral End User: Hospitals, Clinics, Pharmacies, Homecare Form: Drops, Ointments, Gels, Suspensions Delivery Method: Topical, Injectable, Implants, Intraocular |
| Companies Covered | Regeneron Pharmaceuticals, F. Hoffmann-La Roche, Bayer AG, Novartis AG, AbbVie, Alcon, Bausch Health Companies, Santen Pharmaceutical, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Drugs Market Strategic Shifts & Innovations
Sustained-release formulation engineering is compressing dosing frequency from monthly to quarterly or semi-annual intervals. This shift is redrawing competitive boundaries between chronic therapy incumbents and long-acting modality specialists.
Implantable depot technologies using biodegradable polymers and hydrogel matrices are decentralizing treatment administration from hospital-based surgical suites to office-based retina clinics. Community ophthalmology practices in the United States are adopting these platforms faster than academic medical centers, enabled by simplified injection protocols and reduced monitoring requirements. The structural consequence is compressing referral network dependence and enabling direct patient capture by standalone specialty practices.
REACH substance restrictions and the EU MDR's device-drug combination obligations are elevating material qualification burdens for European manufacturers. Suppliers must now document full polymer supply chain traceability for intraocular lenses and sustained-release implants, extending procurement cycles by 12-18 months. German and French notified bodies are applying divergent interpretations of biocompatibility testing scope, fragmenting CE marking timelines across national markets.
Homecare channels are displacing traditional hospital outpatient departments as the preferred site of service for chronic anti-VEGF therapy in Japan and the United States. Medicare reimbursement policy in the United States and Japan's fee schedule reforms are compressing site-of-service differentials, redirecting volume toward lower-acuity settings. Retina specialists are responding by consolidating into multi-site clinic networks that capture both injection revenue and ancillary diagnostic services.
Ophthalmic Drugs Market Segmentation
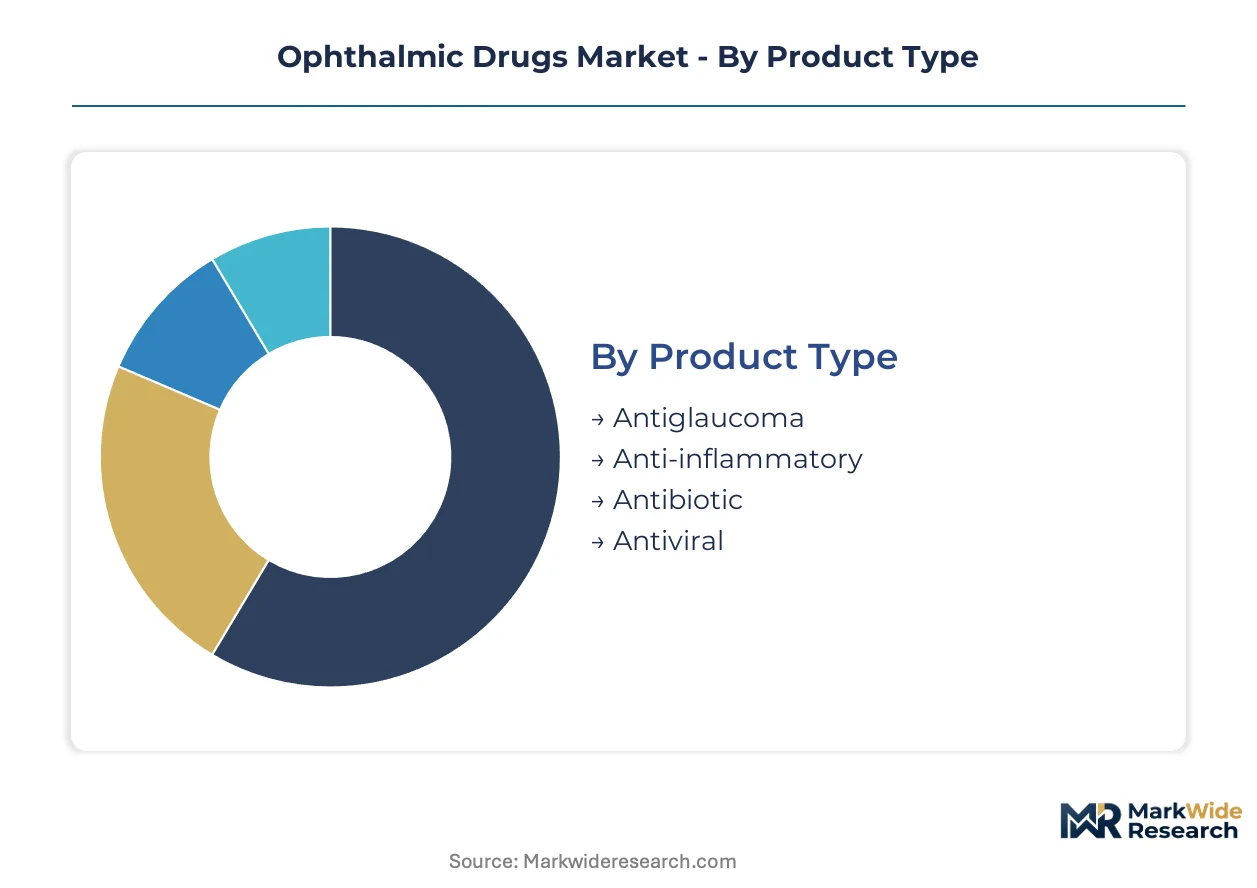
Ophthalmic drug segmentation reveals how formulation complexity and administration setting determine pricing power and competitive moats. Supply concentration varies sharply across delivery modalities, with sterile manufacturing capabilities limiting viable participants in implantable segments.
Product Type:
Antiglaucoma and anti-inflammatory formulations concentrate manufacturing among sterile specialists with validated aseptic lines, while antibiotic and antiviral categories fragment across generic producers with simpler validation requirements.
- Antiglaucoma:Prostaglandin analogs and beta-blockers dominate prescription volume, with preservative-free multidose systems commanding premium positioning in Germany and Japan where reimbursement rewards adherence optimization. Fixed-dose combinations are displacing monotherapy prescribing in United States retina clinics seeking to reduce drop burden.
- Anti-inflammatory:Corticosteroid suspensions and NSAID solutions serve post-surgical protocols, with difluprednate emulsions capturing share in cataract surgery recovery where rapid inflammation control reduces complication rates. Sustained-release dexamethasone implants are redirecting chronic uveitis management from drops to depot administration in French and United Kingdom hospital networks.
- Antibiotic:Fluoroquinolone solutions and fortified vancomycin formulations address acute bacterial keratitis, with compounding pharmacies filling gaps in resistant organism coverage.
- Antiviral:Ganciclovir gels and trifluridine drops manage herpetic keratitis, with oral antiviral co-prescribing reducing recurrence in immunocompromised patient segments.
Today's leader: Antiglaucoma. Tomorrow's challenger: Anti-inflammatory.
End User:
Cost tier stratification separates hospital-based surgical administration from clinic and homecare channels, with reimbursement differentials determining site-of-service migration patterns across national health systems.
- Hospitals:Academic medical centers and surgical hospitals concentrate complex intravitreal administration, gene therapy infusion, and emergency ophthalmic trauma cases. EMA device-drug combination requirements and EU MDR serialization obligations elevate procurement costs for European hospital pharmacies sourcing sustained-release implants.
- Clinics:Standalone retina and comprehensive ophthalmology practices absorb growing anti-VEGF injection volume as Medicare site-of-service reforms compress reimbursement gaps with hospital outpatient departments. Multi-site clinic networks in Texas, Florida, and California are consolidating to capture ancillary diagnostic revenue alongside therapeutic administration.
- Pharmacies:Retail and specialty pharmacy channels distribute chronic topical therapies, with cold chain-certified locations handling biologic prescriptions in urban markets.
- Homecare:Periocular depot training programs and telemedicine monitoring protocols are expanding self-administration feasibility in Japan and United States markets where clinic access creates geographic treatment gaps.
Volume concentrates in clinics. Margin expansion potential sits with homecare.
Form:
Application requirements dictate formulation selection, with anterior segment conditions favoring drops and ointments while posterior segment targets demand suspensions with enhanced corneal penetration or surgical placement.
- Drops:Aqueous and emulsion-based solutions dominate glaucoma and allergy management, with preservative-free unit-dose packaging gaining share in benzalkonium chloride-sensitive patient populations across European markets. Nanoparticle suspensions are improving bioavailability for poorly soluble corticosteroids in United States dry eye protocols.
- Ointments:Petrolatum-based vehicles provide prolonged contact time for overnight lubrication and antimicrobial coverage, with erythromycin and bacitracin ointments standard in neonatal prophylaxis protocols.
- Gels:Carbomer and cellulose-derived matrices extend precorneal residence for severe dry eye and post-photorefractive keratectomy recovery, with in-situ gelling systems responding to ocular surface pH.
- Suspensions:Micronized particle corticosteroids and cyclosporine emulsions address posterior segment inflammation and ocular surface disease, with particle size distribution governing regulatory equivalence determinations under FDA Q1/Q2 guidance.
Mature volume base: Drops. Technology differentiation: Suspensions.
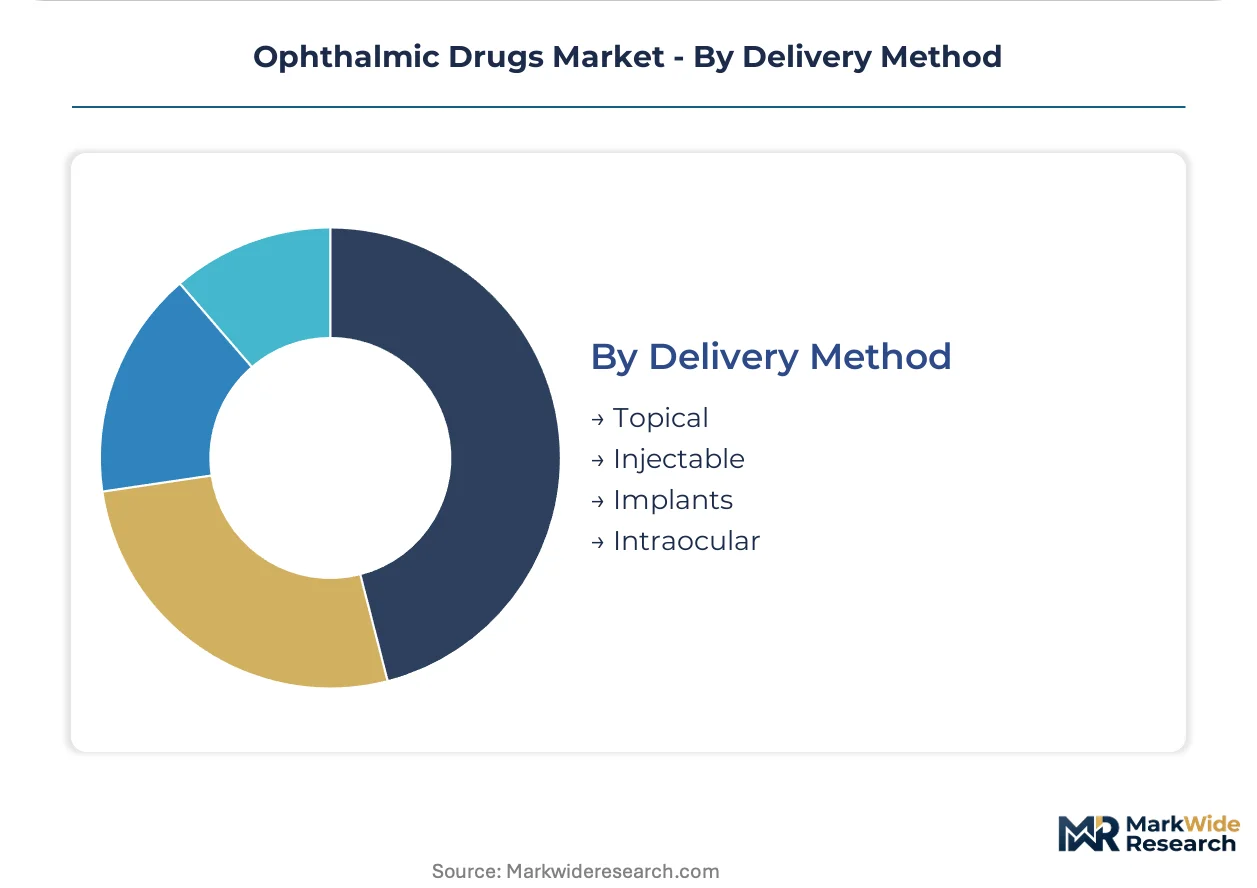
Delivery Method:
Customer type stratification separates chronic self-administered topical regimens from provider-administered interventions, with surgical delivery methods commanding premium pricing tied to training requirements and complication risk.
- Topical:Eye drops and ointments remain the default for anterior segment therapy, with patient adherence limitations driving sustained-release innovation. Preservative-free multidose bottle validation under FDA and EMA divergent standards extends generic development timelines.
- Injectable:Intravitreal anti-VEGF and corticosteroid injections require sterile compounding and immediate administration, with bevacizumab repackaging controversies shaping United States compounding pharmacy regulation. Office-based injection protocols are expanding clinic capacity outside hospital infrastructure.
- Implants:Biodegradable polymer and non-biodegradable reservoir systems deliver multi-year drug release for glaucoma and uveitis, with material traceability requirements under REACH and EU MDR extending European procurement cycles. Dexamethasone and fluocinolone acetonide implants are displacing chronic drop regimens in diabetic macular edema.
- Intraocular:Surgical placement during cataract extraction or standalone vitreoretinal procedures enables precise posterior segment targeting, with intracameral antibiotic injection now standard prophylaxis in European cataract surgery protocols.
Revenue concentration: Injectable. Steepest expansion trajectory: Implants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biopharma corridor anchors ophthalmic drug development, with venture deployment into gene therapy platforms and sustained-release engineering reshaping therapeutic paradigms across major markets.
United States
Medicare site-of-service reforms compress reimbursement differentials between hospital outpatient departments and standalone retina clinics, redirecting anti-VEGF injection volume toward office-based settings. FDA ophthalmic guidance on Q1/Q2 sameness shapes generic equivalence battles for complex suspensions. Multi-site clinic networks in Texas, Florida, and California consolidate to capture both therapeutic administration and ancillary diagnostic revenue.
Germany
Retina clinics in Bavaria and North Rhine-Westphalia expand biologic prescribing for diabetic macular edema under national reimbursement frameworks. EU MDR device-drug combination obligations and REACH material traceability requirements extend procurement cycles for sustained-release implants. German notified bodies apply divergent biocompatibility testing interpretations, fragmenting CE marking timelines.
China
Aging demographics in the Yangtze River Delta and Pearl River Delta drive volume for anti-VEGF therapy as reimbursement access broadens. NMPA green chemistry incentives for aqueous manufacturing processes reshape API sourcing decisions for multinational portfolios. Domestic biopharma clusters in Shanghai and Suzhou scale viral vector manufacturing for gene therapy candidates.
Japan
Fee schedule reforms compress site-of-service differentials, redirecting chronic anti-VEGF therapy from hospital outpatient departments toward homecare channels. PMDA sterility and stability standards for sustained-release implants diverge from FDA pathways, extending development timelines. Retina specialists in Tokyo and Osaka consolidate into multi-site networks capturing injection revenue.
France
ANSM national health technology assessment expands coverage for intravitreal protocols in diabetic macular edema, accelerating clinic adoption. EU MDR serialization requirements force upgrades to manufacturing execution systems at mid-scale sterile facilities. Paris and Lyon hospital networks redirect chronic uveitis management from drops to sustained-release dexamethasone implants.
Ophthalmic Drugs Market Key Industry Players
Capacity expansion dominates the current landscape as sterile manufacturing capabilities become the binding constraint on implantable segment participation. The market structure concentrates among integrated biopharma incumbents with captive antibody production and validated aseptic lines, while mid-scale specialists face ERP integration burdens under serialization mandates. Three archetypes define competitive positioning: large-cap biopharma with retinal disease franchises, diversified healthcare conglomerates with European ophthalmology reach, and sterile formulation specialists with device-drug combination expertise. Geographic expansion and technology licensing represent the dominant competitive moves, with players securing viral vector manufacturing scale and biodegradable polymer supply chains.
Among US-based biopharma anchors, Regeneron Pharmaceuticals and AbbVie exemplify the integrated archetype with captive production infrastructure for biologic active pharmaceutical ingredients. Bayer AG occupies a position representing European diversified reach, with geographic differentiation in markets where biosimilar transition timelines remain fragmented. These three entities illustrate how manufacturing depth and regulatory navigation capability separate viable participants from margin-compressed generic competitors in implantable and sustained-release segments.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche |
| Bayer AG |
| Novartis AG |
| AbbVie |
| Alcon |
| Bausch Health Companies |
| Santen Pharmaceutical |
| Pfizer |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient spot indices for monoclonal antibodies and viral vectors cascade through ophthalmic manufacturing tiers, compressing margins for sterile formulation specialists while amplifying pricing power for integrated biopharma with captive biologics production. Cost pass-through mechanics differentiate contract manufacturers exposed to biologic input volatility from vertically integrated incumbents buffering price erosion through internal antibody supply chains.
Pricing Analysis
Input-cost pass-through from biologic API procurement and cold chain logistics reshapes pricing stratification across ophthalmic segments. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy platforms and sustained-release implants from chronic drop regimens and generic antibiotics. Cost compression in anti-inflammatory suspensions intensifies because FDA Q1/Q2 sameness litigation extends generic equivalence timelines. Hospital outpatient departments demonstrate highest price sensitivity due to Medicare reimbursement compression, while retina clinics absorb premium pricing for office-based intravitreal protocols.
Supply Chain Analysis
Workforce availability constraints in sterile manufacturing hubs across Ireland, Switzerland, and Singapore limit expansion velocity for aseptic fill-finish capacity serving sustained-release implant production. Supply concentration draws from German polymer suppliers for biodegradable depot matrices, Indian API manufacturers for corticosteroid precursors, and US viral vector facilities for gene therapy candidates. Single-source vulnerability in specialized biologics cold chain logistics elevates risk exposure for European distributors navigating EU MDR serialization mandates. Distribution runs through certified specialty pharmacies for temperature-controlled biologics and multi-site clinic networks for office-administered injections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic drug manufacturing arbitrage favors capacity placement in Singapore and Ireland over continental Europe, where EU MDR compliance costs and REACH material traceability obligations inflate facility qualification timelines by 12-18 months relative to alternative jurisdictions.
For Market Incumbents: Cement sterile manufacturing dominance through backward integration into viral vector production and biodegradable polymer supply chains. Capacity addition in Singapore buffers against EU MDR timeline fragmentation for device-drug combination filings. Certification investment in preservative-free multidose container systems defends margin position against generic entrants exploiting FDA-EMA regulatory divergence. For New Entrants and Emerging Players: Community ophthalmology practices in secondary US cities represent the most penetrable buyer archetype for periocular depot formulations displacing chronic drop burden. White-space targets include homecare injection training protocols in Japan and telemedicine-enabled monitoring platforms for geographic treatment gaps. Go-to-market angle centers on simplified office-based administration protocols that reduce referral network dependence. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing capabilities become binding constraints on sustained-release and gene therapy platform participation. Long-term viability across the analysis window favors integrated biopharma with captive biologics production over mid-scale specialists facing ERP integration burdens under serialization mandates. Acquisition target archetype: sterile formulation specialists with validated aseptic lines and device-drug combination expertise. Signal to watch: divergence in FDA and EMA real-world evidence requirements for anti-VEGF biosimilar approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector capacity expansion in Boston-Cambridge corridor accelerates gene therapy platform commercialization timelines. |
| Regulatory Approval Pathway | Parallel FDA and EMA filings for sustained-release implants reduce market entry fragmentation across reimbursement clusters. |
| Backward Integration | Captive antibody production insulates Regeneron and AbbVie from biologic API spot price volatility. |
| Long-term Supply Agreement | Biodegradable polymer procurement contracts with German suppliers secure implant manufacturing continuity under REACH obligations. |
| Reimbursement Strategy | Medicare site-of-service reform navigation redirects anti-VEGF volume toward clinic networks capturing ancillary diagnostics. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored segment-level estimates.
Segment-weighting approaches distributed value across treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from epidemiological trend extrapolation, reimbursement policy trajectory analysis, and technology substitution curve modeling. Forecast inputs incorporated anti-VEGF injection volume migration patterns and gene therapy platform adoption elasticity.
Underlying measurement precision varies by segment; antiglaucoma and anti-inflammatory categories carry tighter precision than emerging gene therapy platforms. Forecasts reflect documented assumptions regarding reimbursement policy continuity, regulatory pathway convergence, and biologics manufacturing capacity expansion. Material deviation in FDA-EMA regulatory divergence timelines, biologic cold chain logistics reliability, or vitreoretinal surgical training pipeline throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Russia Diabetes Drugs Market