
 Global Ophthalmic Perimeters Market | 2026-2036
Global Ophthalmic Perimeters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmic Perimeters Market Foresight
German precision optics manufacturing is repositioning supply chains toward integrated diagnostic platforms. Carl Zeiss Meditec leverages its microscopy heritage to dominate high-end automated perimetry installations across European university hospitals. Haag-Streit Group anchors its position through Swiss-engineered kinetic perimeter systems that sustain premium pricing in specialized glaucoma practices. NIDEK competes aggressively on automated static perimeter volume in Asian markets, while Heidelberg Engineering differentiates through diagnostic imaging software that extends hardware utility.
Ophthalmic perimeters are instruments that map the visual field by presenting light stimuli at varying intensities and locations to quantify retinal sensitivity thresholds, typically operating within standardized luminance ranges and employing either static or kinetic stimulus presentation protocols. These devices serve primary clinical purposes in detecting and monitoring progressive vision loss, particularly for glaucoma where characteristic arcuate scotomas indicate optic nerve damage. Static perimeters currently occupy the largest installed base due to their reproducibility in longitudinal glaucoma management, while software solutions represent the fastest-expanding margin pool as clinics seek cloud-based analytics and remote monitoring capabilities. Kinetic perimeters retain specialized demand in neurological disorder assessment where peripheral field mapping remains diagnostically essential.
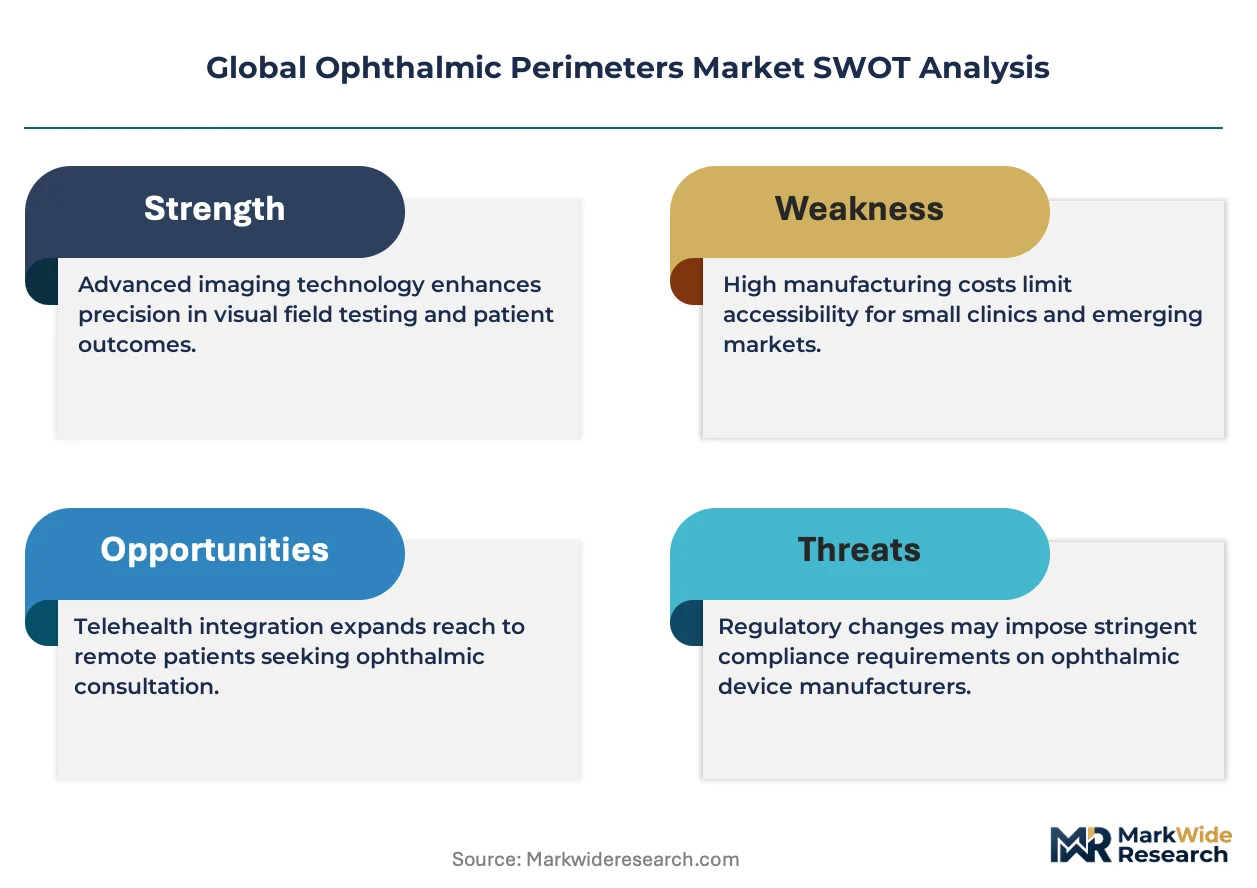
FDA clearance requirements for Class II ophthalmic diagnostic devices shape product development timelines and clinical validation burdens for manufacturers seeking US market access, while EU MDR conformity assessment under notified body supervision extends certification complexity for European commercialization. Japan's PMDA enforces stringent optical performance standards that filter non-compliant perimeter imports, creating regulatory moats for established domestic producers. Stakeholders must monitor evolving reimbursement codes for remote visual field testing as teleophthalmology protocols challenge traditional clinic-based perimetry deployment models.
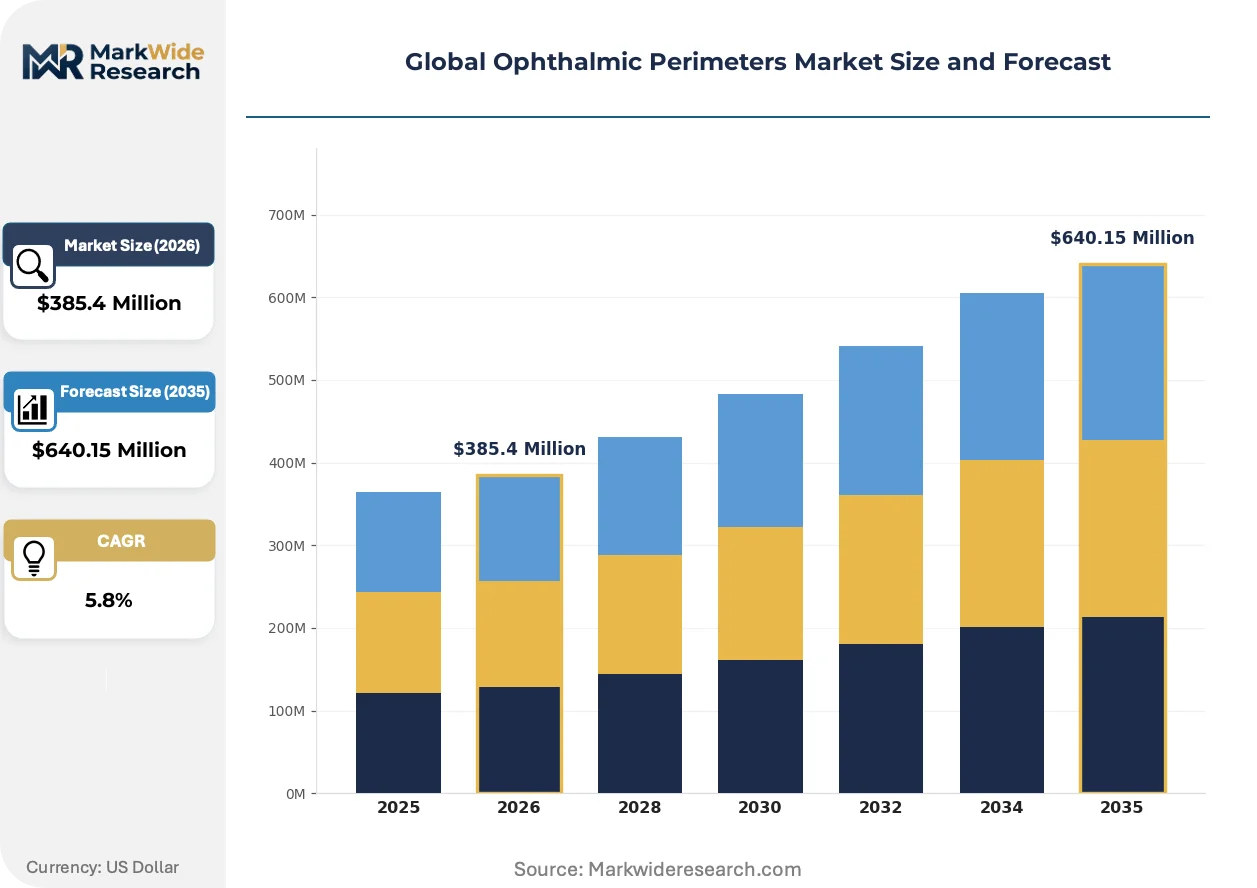
Market Dynamics
The convergence of optical coherence tomography with perimetry software is compressing hardware replacement cycles and consolidating diagnostic workflows into single-platform installations across ophthalmology clinics.
Growth Catalysts
- Japan's PMDA optical performance standards:Stringent technical barriers filter non-compliant imports, creating protected demand corridors for precision-engineered systems in domestic university hospitals.
- Static perimetry reproducibility:Longitudinal glaucoma management protocols favor automated static systems for their threshold sensitivity consistency in progressive disease tracking.
- Cloud-based analytics platforms:Software solutions extend hardware utility through remote monitoring capabilities, expanding margin pools beyond device sales.
Market Restraints
- EU MDR conformity assessment:Extended notified body supervision timelines delay European commercialization and inflate clinical validation burdens for Class II diagnostic devices.
- Precision optics supply concentration:German and Swiss manufacturing clusters control high-end optical component sourcing, creating geographic dependency risks for perimeter assembly.
- Kinetic perimetry substitution pressure:Neurological assessment applications face displacement from integrated OCT-angiography systems offering simultaneous structural and functional mapping.
Strategic Opportunities
- Teleophthalmology reimbursement evolution:Remote visual field testing codes under review by US Medicare and German statutory insurers challenge clinic-based deployment models.
- India's tier-two city ophthalmology expansion:Underpenetrated diagnostic infrastructure in secondary urban centers creates volume demand for mid-range automated perimeters.
- AI-assisted threshold algorithms:Machine learning integration with stimulus presentation protocols reduces examination duration and technician dependency.
Industry Challenges
- Perimetrist technician training pipelines:Specialized visual field interpretation skills face shortage as automated systems reduce hands-on examination exposure during credentialing.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for OCT-integrated platforms require complex clinical validation against legacy hardware benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmic Perimeters Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Perimeters, Kinetic Perimeters, Visual Field Analyzer, Software Solutions End User: Ophthalmology Clinics, Hospitals, Research Institutes, Rehabilitation Centers Technology: Automated Systems, Manual Systems, Hybrid Systems, Diagnostic Imaging Application: Glaucoma Management, Neurological Disorders, Retinal Diseases, Vision Screening |
| Companies Covered | NIDEK, Optopol Technology, Carl Zeiss Meditec, OCULUS Optikgeräte, Takagi Seiko, Haag-Streit Group, Heidelberg Engineering, Revenio Group, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmic Perimeters Market Shifts & Advancements
Diagnostic platform consolidation is erasing boundaries between structural imaging and functional testing, with software-defined workflows displacing standalone hardware categories.
Spectral-domain optical coherence tomography is absorbing perimetry data streams into unified diagnostic dashboards. European glaucoma referral networks are adopting these converged platforms to compress patient throughput times. The technology is absorbing standalone visual field analyzer market share by bundling sensitivity mapping with retinal nerve fiber layer thickness measurements.
EU MDR Article 10 technical documentation requirements are extending design dossier preparation timelines for ophthalmic diagnostic manufacturers. The regulation forces revalidation of legacy perimeter software against updated essential safety and performance benchmarks. German university hospital procurement offices are responding by consolidating vendor lists to reduce supplier qualification overhead.
Hospital group purchasing organizations are unbundling service contracts from hardware acquisitions in North American markets. Ophthalmology department administrators negotiate separate maintenance agreements and software subscription tiers. This purchasing behavior shift is most visible in US integrated delivery networks seeking operational expenditure flexibility over capital-heavy ownership models.
Global Ophthalmic Perimeters Market Segmentation
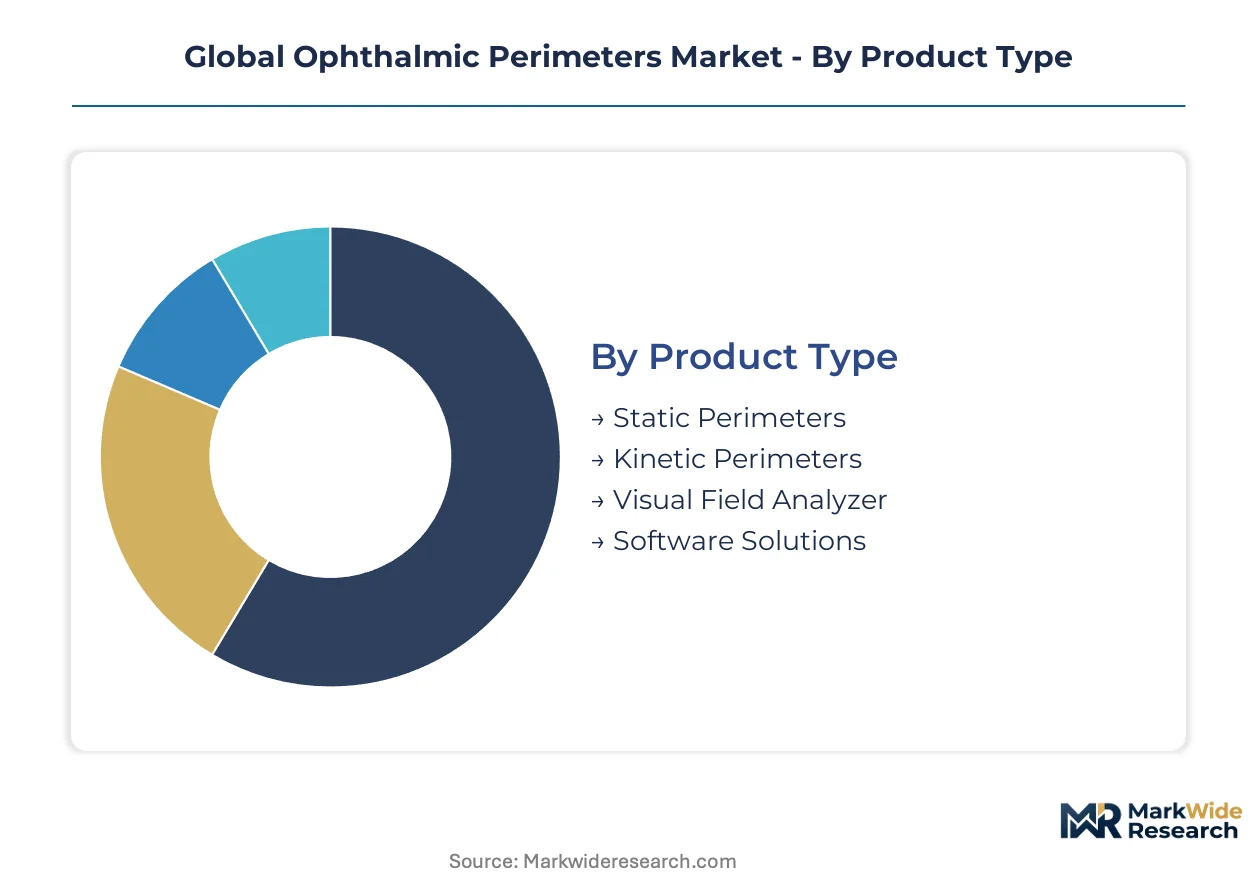
Perimeter segmentation reveals how diagnostic workflows split between standardized hospital procurement and customized clinic configurations. Product architecture choices cascade through technology adoption patterns and end-user service models.
Product Type:
Standardization dominates high-volume automated installations while customization persists in specialized kinetic configurations.
- Static Perimeters:Automated threshold algorithms present light stimuli at fixed locations with variable intensity to map retinal sensitivity gradients. Hospital procurement in Germany and Japan concentrates here due to reimbursement protocols favoring reproducible longitudinal glaucoma tracking.
- Kinetic Perimeters:Moving stimuli traverse the visual field perimeter to map isopters, preserving utility in neurological assessment where peripheral field boundaries matter. Swiss-engineered systems sustain premium positioning in specialized practices despite compression from integrated diagnostic platforms.
- Visual Field Analyzer:Dedicated hardware platforms combining stimulus presentation with capture optics.
- Software Solutions:Cloud-based analytics and remote monitoring capabilities extending hardware utility.
Most installed capacity flows through Static Perimeters. Expansion is steepest in Software Solutions.
End User:
Procurement scale separates institutional buyers from dispersed clinical operators across this category.
- Ophthalmology Clinics:Independent and group practices drive demand for consolidated diagnostic platforms integrating perimetry with OCT imaging. German university hospital networks increasingly influence purchasing standards that cascade to affiliated outpatient facilities.
- Hospitals:Centralized radiology and ophthalmology departments specify automated static systems for high-throughput screening protocols. Japanese statutory insurance frameworks accelerate replacement cycles in tertiary centers.
- Research Institutes:Academic medical centers requiring specialized kinetic configurations for experimental protocols.
- Rehabilitation Centers:Post-surgical and low-vision service providers with distinct field assessment requirements.
Hospital procurement commands the largest volume share. Ophthalmology Clinics are climbing the fastest as platform consolidation accelerates.
Technology:
Automation intensity determines labor substitution potential and throughput economics across deployment scenarios.
- Automated Systems:Microprocessor-controlled stimulus presentation with patient response capture eliminates perimetrist technician variability. FDA 510(k) clearance pathways shape development timelines for US market entry.
- Manual Systems:Operator-dependent kinetic examination retains niche utility in resource-constrained settings.
- Hybrid Systems:Configurable automation levels accommodating technician-supervised protocols.
- Diagnostic Imaging:OCT-integrated platforms absorbing functional testing into structural imaging workflows.
Automated Systems carry the dominant installed base. Diagnostic Imaging is gaining share fastest as convergence redefines category boundaries.
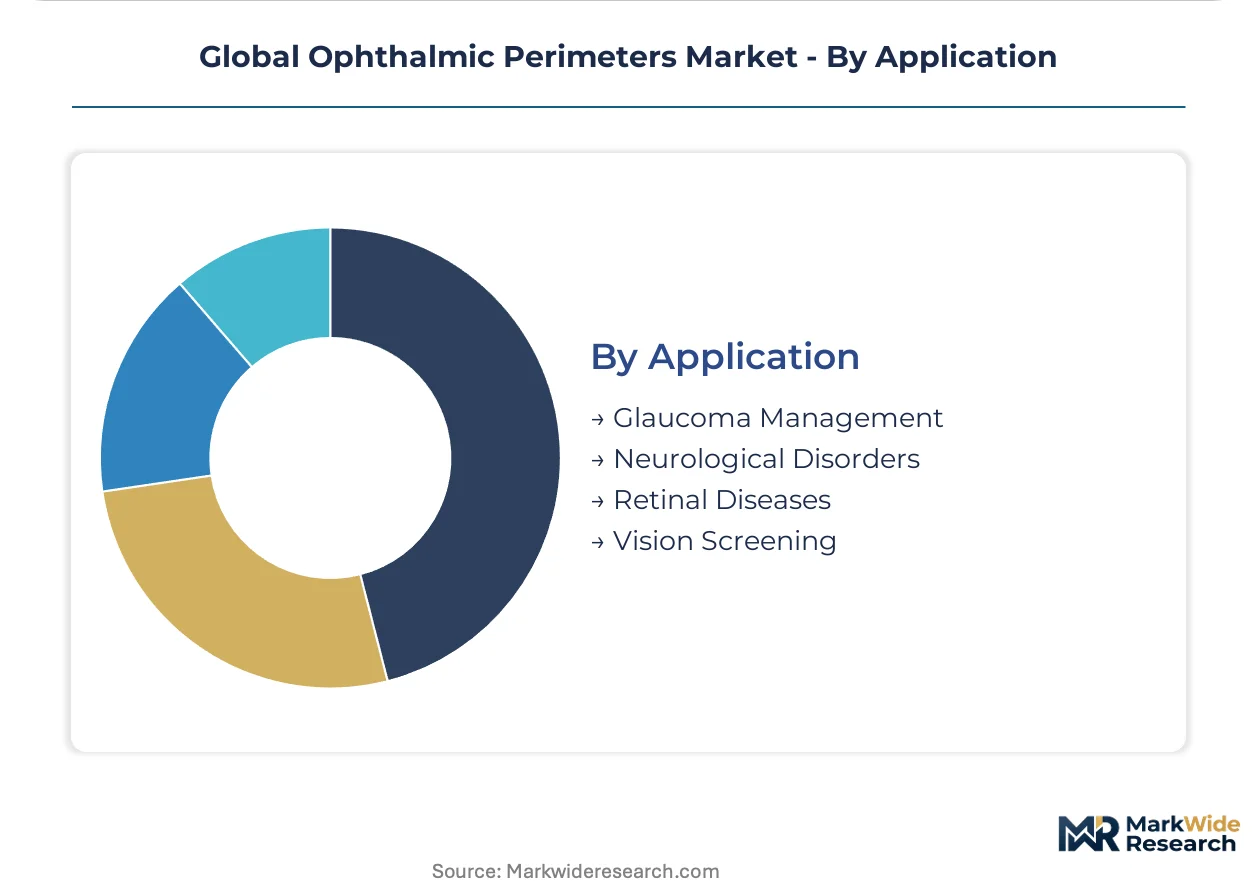
Application:
Disease prevalence and reimbursement specificity concentrate demand in chronic progressive conditions.
- Glaucoma Management:Longitudinal tracking of arcuate scotomas and nasal steps drives repeat examination protocols. Static perimetry's reproducibility makes it the reference standard for structural-functional correlation in European referral networks.
- Neurological Disorders:Hemianopia and quadrantanopia mapping from stroke, tumor, or demyelinating disease requires peripheral field assessment. Kinetic techniques retain specialized demand here despite OCT-angiography encroachment.
- Retinal Diseases:Macular dysfunction assessment with specialized central field protocols.
- Vision Screening:Population-level detection programs with simplified pass-fail criteria.
Glaucoma Management absorbs the majority of installed capacity. Neurological Disorders represent the most defensible niche against platform substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance cost differentials are redistributing ophthalmic perimeter manufacturing toward jurisdictions with streamlined optical device certification pathways. Production migration follows reimbursement density rather than labor arbitrage alone.
United States
Medicare's evolving teleophthalmology reimbursement codes are reshaping procurement patterns in integrated delivery networks. FDA 510(k) clearance pathways for Class II diagnostic devices maintain stringent clinical validation requirements that favor established domestic distributors. The Boston-Cambridge medical device corridor concentrates software development for AI-assisted perimetry analytics.
Germany
Statutory health insurance frameworks now prioritize early glaucoma detection protocols, accelerating automated static perimeter replacement cycles in university hospitals. EU MDR Article 10 technical documentation requirements extend design dossier preparation timelines for manufacturers. The Stuttgart precision optics cluster anchors high-end component sourcing for integrated diagnostic platforms.
Japan
PMDA optical performance standards create protected demand corridors for precision-engineered systems in domestic tertiary centers. National health insurance reimbursement favors reproducible longitudinal tracking protocols. The Tokyo-Osaka medical device corridor concentrates automated perimeter assembly for Asian market distribution.
India
Tier-two city ophthalmology expansion generates volume demand for mid-range automated perimeters as diagnostic infrastructure penetrates secondary urban centers. Central Drugs Standard Control Organization regulatory pathways for optical diagnostic devices remain less burdensome than US or EU equivalents. The Bangalore-Hyderabad med-tech manufacturing belt is attracting contract assembly for export-oriented perimeter production.
Switzerland
Swissmedic certification for high-precision optical instruments sustains premium positioning for kinetic perimeter systems in specialized glaucoma practices. Reimbursement autonomy within cantonal health systems permits faster adoption of integrated diagnostic platforms. The Basel-Zurich precision engineering corridor maintains captive supply chains for specialized perimetry components.
Global Ophthalmic Perimeters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined diagnostics and teleophthalmology integration. The vendor base clusters around three strategic archetypes: precision optics heritage manufacturers, volume-driven Asian electronics fabricators, and diagnostic imaging platform consolidators. Competitive positioning hardens through M&A activity targeting cloud-based analytics capabilities and strategic partnerships bridging hardware assembly with AI algorithm development.
Within the precision optics heritage tier, Carl Zeiss Meditec and Haag-Streit Group exemplify European-engineered positioning anchored in microscopy and Swiss kinetic system traditions respectively. NIDEK represents the volume-driven Asian archetype competing on automated static perimeter scale across domestic and export markets. Heidelberg Engineering occupies a platform consolidation position extending hardware utility through diagnostic imaging software rather than standalone perimeter sales.
| Leading Market Players |
|---|
| NIDEK |
| Optopol Technology |
| Carl Zeiss Meditec |
| OCULUS Optikgeräte |
| Takagi Seiko |
| Haag-Streit Group |
| Heidelberg Engineering |
| Revenio Group |
| Topcon Corporation |
| Others |
Supply & Pricing Matrix
EU MDR Article 10 technical documentation mandates now gate both qualified component supply and premium-tier pricing access for ophthalmic perimeter manufacturers seeking European commercialization. Compliance burden inflation separates vendors capable of absorbing extended notified body timelines from competitors forced toward price-competitive Asian markets.
Pricing Analysis
Distributor margins absorb 15-25 percent of manufacturer list price before hospital procurement committees negotiate final terms. Three-tier pricing structure across premium, standard, and economy levels reflects optical component grade, FDA 510(k) clearance status, and bundled software subscription duration. Cost compression in mid-range automated systems intensifies because NIDEK volume manufacturing erodes European heritage-brand positioning. German university hospitals exhibit lowest price sensitivity; Indian tier-two clinics demonstrate highest.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale procurement from integrated delivery networks seeking consolidated vendor relationships. Precision optics manufacturing concentrates in Germany, Switzerland, and Japan, drawing from specialized glass substrate foundries and electromagnetic actuator suppliers. Single-source vulnerability runs through Stuttgart-area lens grinding capacity for high-end kinetic perimeter assemblies. Distribution runs through authorized medical device distributors with PMDA or FDA establishment registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in software-defined diagnostics where cloud-based analytics transform capital equipment sales into recurring revenue streams. AI-assisted threshold algorithms reduce examination duration while extending hardware replacement cycles.
For Market Incumbents: Anticipate displacement from OCT-integrated platforms by accelerating diagnostic imaging partnerships before convergence erodes standalone perimeter demand. Defensive consolidation through captive supply of precision optical components protects against Stuttgart cluster supply disruptions. Channel control investments in hospital GPO contract management preserve pricing power against unbundled service contract trends.
For New Entrants and Emerging Players: The 40-60 percent price gap between premium Swiss-engineered systems and economy Asian imports creates white-space opportunity for mid-range automated perimeters with CE marking and basic cloud connectivity. India's tier-two ophthalmology expansion offers most penetrable geography with CDSCO regulatory pathways less burdensome than FDA equivalents. Go-to-market through regional distributor partnerships with existing hospital procurement relationships accelerates traction without direct sales infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for diagnostic imaging software specialists because platform consolidation is absorbing functional testing into structural imaging workflows across European glaucoma referral networks. Long-term viability favors vendors with AI algorithm development capabilities and teleophthalmology reimbursement strategy positioning. Monitor CMS telehealth code evolution as inflection signal for remote visual field testing adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| OCT-Perimetry Software Integration | Heidelberg Engineering's diagnostic imaging platforms demonstrate convergence compressing standalone hardware categories. |
| CE Marking Pathway Acceleration | EU MDR notified body relationships determine European commercialization timelines for automated static systems. |
| Hospital System Partnership | German university hospital networks cascade procurement standards to affiliated outpatient ophthalmology clinics. |
| AI-Assisted Algorithm Development | Machine learning integration with stimulus presentation protocols reduces examination duration and technician dependency. |
| Reimbursement Strategy | Medicare teleophthalmology code evolution shapes US integrated delivery network procurement patterns for remote monitoring. |
Research Methodology
Direct dialogue with ophthalmology department heads, biomedical equipment procurement managers, GPO contracts specialists, and perimetrist technicians grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) device listings, EU MDR notified body technical documentation, Japanese PMDA optical performance standards, and hospital procurement database extracts. Bottom-up installed base estimates triangulated against top-down reimbursement expenditure analysis.
Top-down macroeconomic drivers and bottom-up segment penetration rates converged across the projection horizon. Segmentation modeling spanned product architecture, automation intensity, end-user procurement scale, application disease state, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting against historical replacement cycle data and statutory insurance reimbursement velocity. AI algorithm development pipelines and teleophthalmology protocol adoption served as industry-specific forecast sensitivity inputs.
Caveats apply where PMDA regulatory tightening or EU MDR notified body capacity constraints could materially shift the outlook for premium-tier system commercialization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Tonometry Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Global Hemianopsia Market