
 India Ophthalmology Devices Market | 2026-2036
India Ophthalmology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Ophthalmology Devices Market Foresight
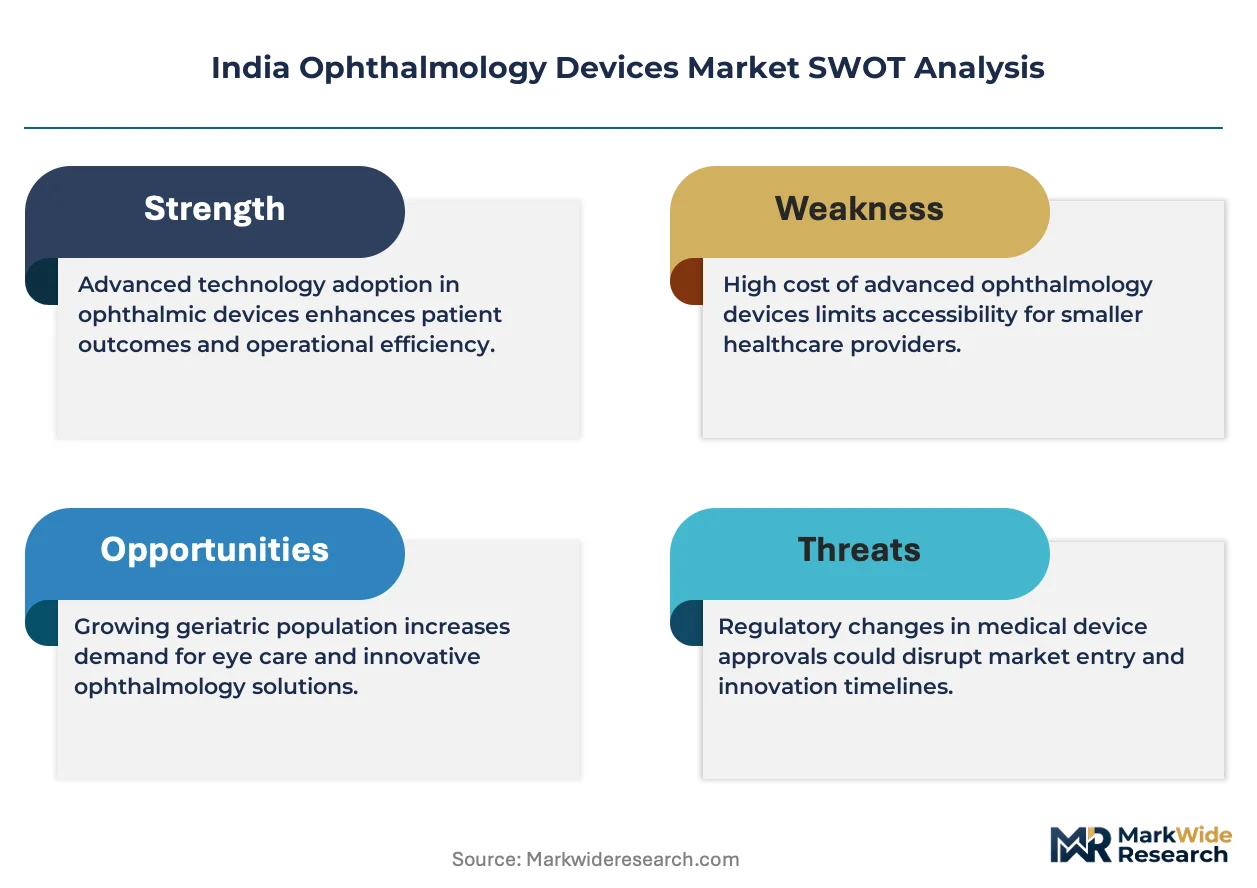
Hospital procurement consortia in western and southern India is reconfiguring how ophthalmology devices reach end users, with bulk purchasing agreements now bypassing traditional distributor tiers. Alcon Inc. leverages its cataract surgical portfolio to anchor relationships with multi-hospital networks across Gujarat and Telangana. EssilorLuxottica SA competes through diagnostic and lens technology integration, while Remidio specializes in portable retinal imaging systems suited for outreach clinics in rural Maharashtra.
Ophthalmology devices comprise precision instruments for diagnosis, surgical intervention, and vision correction, typically operating within wavelength-specific laser parameters and micron-level optical tolerances. These devices serve the clinical purpose of restoring, preserving, or enhancing visual function across diverse patient populations. Intraocular lenses dominate current procurement volumes due to India's high cataract surgical burden, while laser-assisted platforms represent the fastest-expanding technology segment as femtosecond systems displace manual techniques in premium surgical settings. Diagnostic equipment captures concentrated margin pools where optical coherence tomography and fundus imaging systems command replacement cycles tied to software upgrade pathways.
CDSCO governs device registration and quality standards under the Medical Device Rules, while BIS certification mandates electrical safety and performance benchmarks for imported ophthalmic equipment. The PLI scheme for medical devices creates domestic manufacturing incentives that reshape supplier economics for multinational entrants. State-level public health missions in Karnataka and Andhra Pradesh are expanding screening infrastructure, directly stimulating demand for portable diagnostic platforms. Stakeholders must monitor how CDSCO's risk-based classification revisions affect registration timelines for novel laser platforms and biometric diagnostic systems.
Market Dynamics
The central structural force reshaping India's ophthalmology devices landscape is the migration of surgical capacity from metropolitan centers to Tier-II and Tier-III cities, where hospital procurement consortia now aggregate demand and disintermediate traditional distribution tiers.
Growth Catalysts
- CDSCO's Risk-Based Registration Pathways:Streamlined approval frameworks under the Medical Device Rules compress time-to-market for both domestic manufacturers and importers of diagnostic laser platforms.
- State-Level Vision Screening Missions:Karnataka and Andhra Pradesh public health programs directly procure portable fundus imaging systems for rural outreach infrastructure.
- Femtosecond Laser Platforms:These systems enable bladeless cataract procedures that command premium pricing in Gujarat and Telangana's multi-hospital networks.
Market Restraints
- Optical Component Import Dependency:Precision lenses and laser sources concentrate in German and Japanese supply chains, exposing domestic assemblers to currency volatility and extended lead times.
- BIS Electrical Safety Certification:Mandatory testing protocols for imported diagnostic equipment create bottlenecks at designated laboratories in Mumbai and Chennai.
- Manual Phacoemulsification Persistence:Cost-sensitive government hospital tenders continue favoring conventional surgical techniques over femtosecond systems despite clinical advantages.
Strategic Opportunities
- PLI Scheme Manufacturing Incentives:Domestic production-linked subsidies for medical devices attract multinational entrants to establish captive assembly for intraocular lenses in Maharashtra.
- Tele-ophthalmology Integration:Cloud-connected diagnostic devices enable asynchronous consultation workflows between rural screening camps and urban specialists.
- Optical Coherence Tomography-AI Convergence:Automated retinal pathology detection algorithms embedded in diagnostic hardware reduce specialist interpretation burdens in Tamil Nadu's high-volume clinics.
Industry Challenges
- Biomedical Engineer Shortage:Servicing femtosecond laser platforms and spectral-domain OCT systems requires specialized training that India's technical institutes have not scaled to match equipment deployment rates.
- Legacy Equipment Interoperability:Software upgrade pathways for diagnostic devices often fail to integrate with hospital information systems running on decade-old architectures in Rajasthan and Madhya Pradesh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ophthalmology Devices Market |
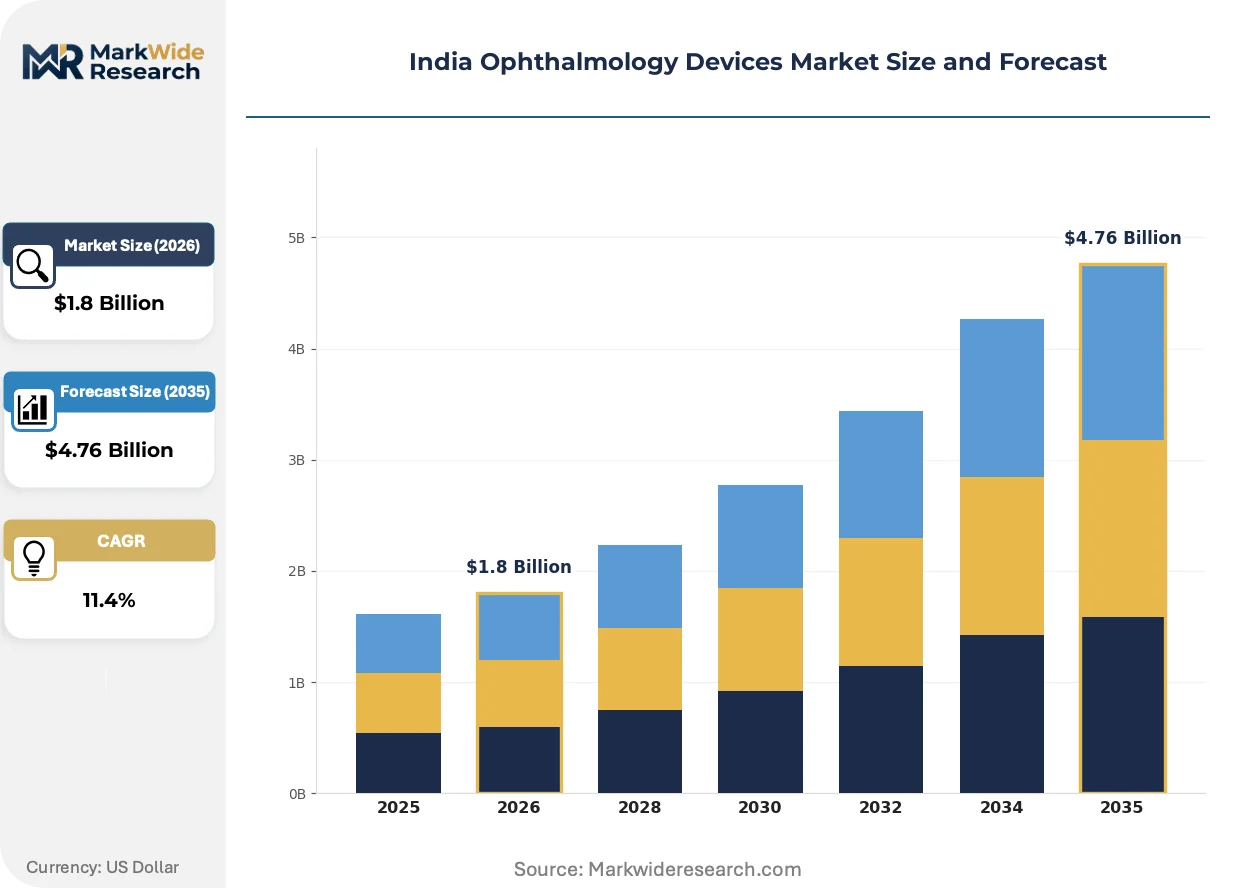
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Ophthalmic Lasers, Diagnostic Equipment, Surgical Microscopes End User: Hospitals, Clinics, Eye Care Centers, Research Institutions Technology: Minimally Invasive, Laser-assisted, Imaging Systems, Biometric Technologies Application: cataract Surgery, Retinal Surgery, Glaucoma Treatment, Refractive Surgery |
| Companies Covered | Bausch + Lomb Corp., Topcon Corporation, Alcon Inc., Nidek Co Ltd, Hoya Corporation, Johnson & Johnson Vision Care, EssilorLuxottica SA, Remidio, Carl Zeiss Meditec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ophthalmology Devices Market Shifts & Advancements
Active technology convergence and procurement model disruption are compressing replacement cycles while elevating software-dependent diagnostic platforms over standalone surgical hardware in buyer priority hierarchies.
Femtosecond laser-assisted cataract surgery is hybridizing manual capsulorhexis and lens fragmentation into automated workflows. Premium surgical centers in Hyderabad and Ahmedabad adopt these platforms at accelerating pace. The technology is hybridizing procedure standardization with outcomes-based contracting, compressing variance in surgical results across operator experience levels.
CDSCO's 2023 risk-based classification revisions for ophthalmic laser equipment impose clinical evidence requirements that previously applied only to implantable devices. Domestic manufacturers face elevated regulatory compliance costs. The diagnostic segment bears the heaviest documentation burden, with optical coherence tomography vendors extending registration timelines by eight to fourteen months.
Hospital procurement consortia in western India now bundle diagnostic and surgical device purchasing across multi-hospital networks. Traditional distributor tiers lose volume to direct manufacturer negotiations. Maharashtra's private eye care chains demonstrate the most aggressive consolidation, with single contracts covering equipment for fifteen to twenty facilities simultaneously.
India Ophthalmology Devices Market Segmentation
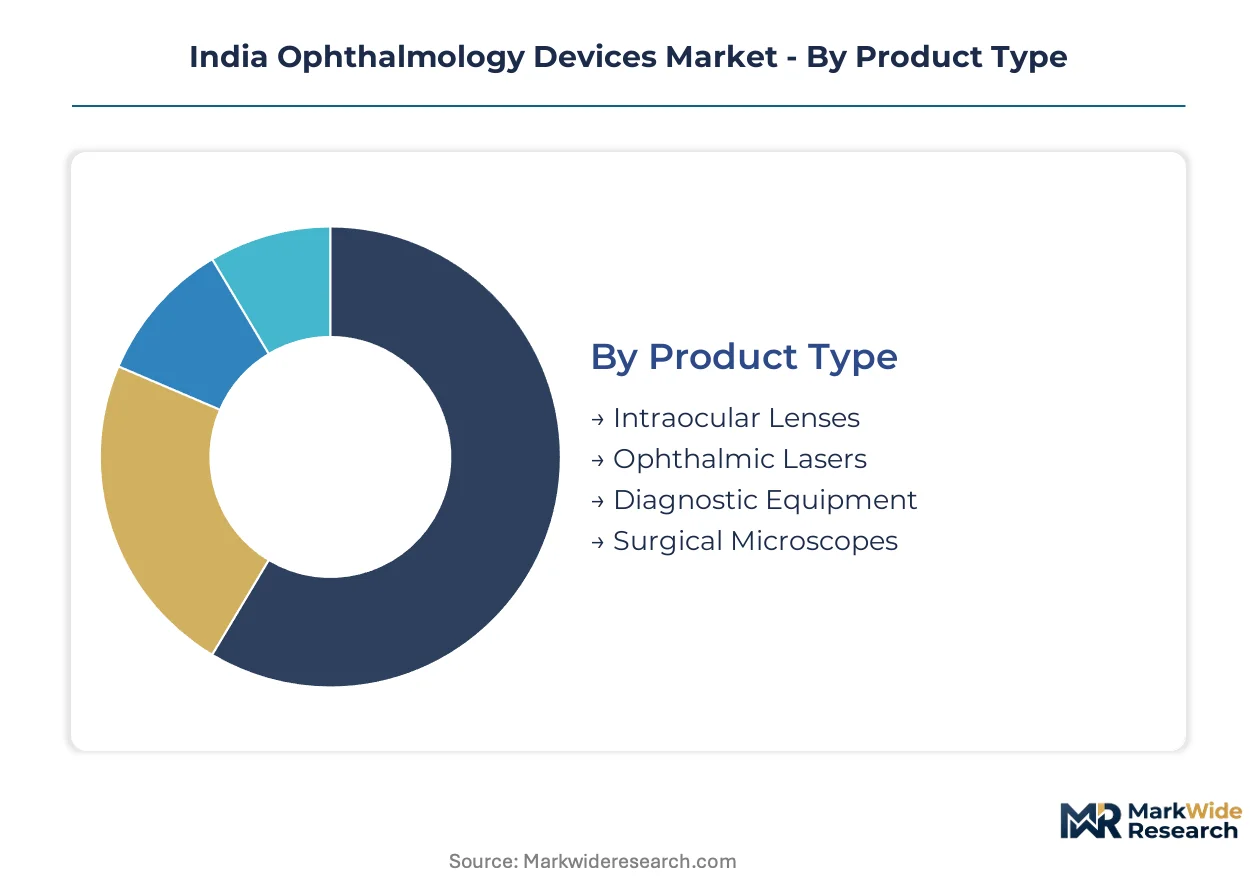
India's ophthalmology devices market fragments across four intersecting dimensions that determine procurement patterns, margin structures, and technology adoption curves. Each segmentation axis reveals distinct competitive dynamics between domestic manufacturers and multinational suppliers navigating CDSCO registration pathways and state-level public health tenders.
Product Type:
Cost tier stratification across surgical consumables, capital equipment, and diagnostic platforms creates divergent commercial models for suppliers serving Indian healthcare institutions.
- Intraocular Lenses:Polymer-based implantable devices with hydrophobic acrylic or hydrophilic materials, available in monofocal, multifocal, and toric configurations. Procurement concentrates in Maharashtra and Gujarat where private eye care chains execute bulk purchasing agreements for cataract surgical camps; government tenders persistently favor economy-tier pricing over premium optical performance.
- Ophthalmic Lasers:Solid-state and excimer systems operating at specific wavelength parameters for photocoagulation, capsulotomy, and refractive correction. Demand clusters in Telangana and Karnataka's tertiary centers where femtosecond platforms command premium positioning; CDSCO's risk-based classification elevates registration documentation burdens for novel laser modalities.
- Diagnostic Equipment:Optical coherence tomography, fundus cameras, and autorefractors with micron-level measurement precision.
- Surgical Microscopes:Operating microscopes with coaxial illumination and motorized zoom capabilities for anterior and posterior segment procedures.
Intraocular lenses command the established base. The steepest expansion runs through ophthalmic lasers.
End User:
Customer type determines purchasing authority, budget cycles, and technical support requirements across India's fragmented eye care delivery infrastructure.
- Hospitals:Multi-specialty and dedicated eye hospitals with centralized biomedical engineering departments and structured capital equipment replacement cycles. Procurement consortia in western and southern India aggregate demand across fifteen to twenty facilities simultaneously, disintermediating traditional distributor networks.
- Clinics:Single-physician and small-group practices with limited floor space and technician support. Equipment selection prioritizes compact footprint and minimal maintenance requirements; diagnostic device vendors compete on software upgrade pathways and remote troubleshooting capabilities.
- Eye Care Centers:Dedicated outpatient facilities with surgical capacity for day-care procedures.
- Research Institutions:Academic medical centers and clinical trial sites with specialized imaging and surgical training platforms.
Hospitals anchor volume concentration. Eye care centers are gaining share fastest as standalone surgical facilities proliferate in Tier-II cities.
Technology:
Maturity gradients across established manual techniques, emerging automated platforms, and convergent diagnostic-surgical systems shape replacement cycle timing and training investment requirements.
- Minimally Invasive:Micro-incisional techniques reducing tissue trauma and accelerating postoperative recovery. Phacoemulsification with sub-3mm incisions dominates government hospital procurement in Tamil Nadu and Andhra Pradesh despite femtosecond alternatives; cost sensitivity perpetuates manual technique reliance.
- Laser-assisted:Femtosecond and excimer platforms automating corneal and lenticular procedures. Premium surgical centers in Hyderabad and Ahmedabad adopt bladeless cataract workflows; BIS electrical safety certification creates bottlenecks at Mumbai and Chennai testing laboratories.
- Imaging Systems:Optical coherence tomography, fundus photography, and angiography with software-dependent diagnostic algorithms.
- Biometric Technologies:IOL power calculation systems integrating corneal topography, axial length measurement, and anterior chamber depth analysis.
Minimally invasive platforms retain the installed base. Laser-assisted modalities show the steepest adoption trajectory among premium providers.
Application:
Volume distribution across anterior and posterior segment procedures reflects India's disease burden demographics and surgical workforce specialization patterns.
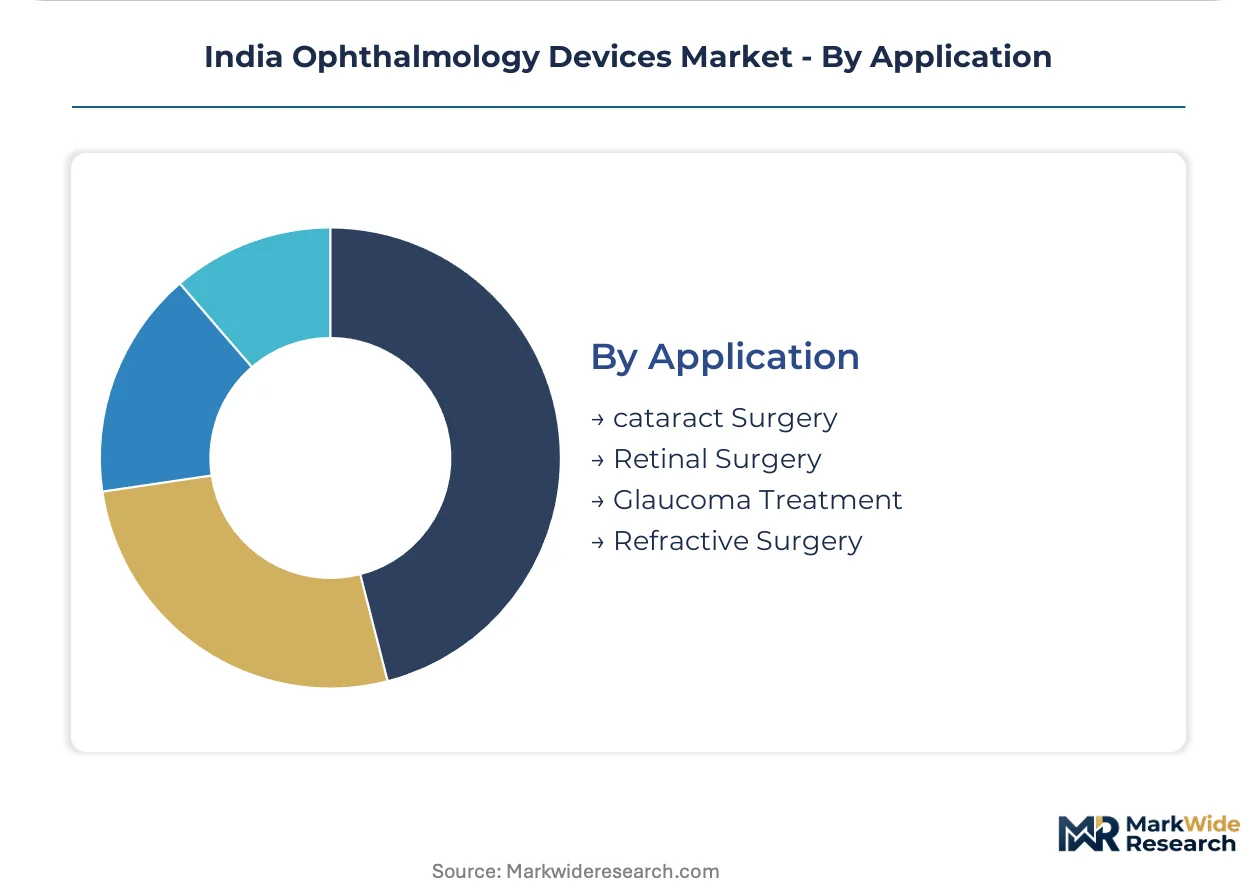
- Cataract Surgery:Lens extraction and intraocular lens implantation addressing age-related opacification. India's surgical volume concentrates in Maharashtra, Karnataka, and Tamil Nadu where government screening programs and private chains simultaneously expand capacity; manual phacoemulsification persists in cost-sensitive tenders despite femtosecond clinical advantages.
- Retinal Surgery:Vitrectomy, membrane peeling, and laser photocoagulation for diabetic retinopathy and macular disorders. Demand intensifies in urban centers with specialized vitreoretinal surgeons; portable fundus imaging systems enable rural screening camps in Karnataka and Andhra Pradesh public health missions.
- Glaucoma Treatment:Trabeculectomy, shunt implantation, and laser iridotomy for intraocular pressure management.
- Refractive Surgery:LASIK, PRK, and SMILE procedures for spectacle independence.
Cataract surgery dominates procedure volume. Retinal surgery demonstrates the most rapid expansion as diabetic retinopathy prevalence escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor's western alignment underwrites Maharashtra's centrality in ophthalmology device distribution, connecting Mumbai-Pune manufacturing clusters to northern and eastern markets through high-capacity rail freight.
Maharashtra
Mumbai and Pune anchor western India's ophthalmology device procurement networks, with private eye care chains executing bulk purchasing agreements across fifteen to twenty facilities simultaneously. CDSCO's streamlined registration pathways accelerate product approvals for imported diagnostic lasers entering through JNPT port. The Mumbai-Ahmedabad industrial corridor concentrates domestic assembly operations for intraocular lenses under PLI scheme incentives.
Karnataka
Bengaluru's tertiary centers drive demand for femtosecond laser platforms and spectral-domain OCT systems, while state-level vision screening missions procure portable fundus imaging for rural outreach. The Karnataka government directly contracts diagnostic equipment for public health infrastructure expansion. The Electronics City-Whitefield corridor hosts service centers for multinational ophthalmic equipment suppliers.
Tamil Nadu
Chennai's medical device manufacturing zone produces surgical microscopes and phacoemulsification systems for domestic consumption and export. Government hospital tenders in Madurai and Coimbatore sustain volume demand for economy-tier intraocular lenses. The Sriperumbudur-Oragadam industrial belt attracts component suppliers for laser source assemblies.
Telangana
Hyderabad's premium surgical centers adopt bladeless cataract workflows at accelerating pace, creating concentrated demand for femtosecond platforms. The Telangana government's medical device park near Shamshabad offers tax incentives for domestic ophthalmic equipment manufacturing. Genome Valley's clinical research infrastructure supports regulatory trials for novel diagnostic algorithms.
Gujarat
Ahmedabad and Surat hospital procurement consortia aggregate demand across multi-hospital networks, disintermediating traditional distributor tiers. BIS electrical safety certification creates bottlenecks at Ahmedabad testing laboratories for imported diagnostic equipment. The Sanand-Vithalapur industrial zone develops precision optical component capabilities to reduce import dependency.
India Ophthalmology Devices Market Competitive Landscape
On the supply side, the industry is consolidating around multinational instrument manufacturers with established CDSCO registration portfolios and domestic specialists exploiting PLI scheme manufacturing incentives. Three strategic archetypes dominate: integrated surgical platform suppliers bundling consumables and capital equipment, diagnostic technology specialists converging hardware with AI-enabled software, and domestic assemblers capturing government tender volumes through cost-optimized production. Competitive moves center on direct hospital procurement consortia negotiations bypassing distributor tiers, and backward integration into precision optical component manufacturing to mitigate currency volatility.
Among multinational suppliers, Alcon Inc., EssilorLuxottica SA, and Carl Zeiss Meditec AG exemplify the premium-tier archetype, anchoring relationships with multi-hospital networks through comprehensive surgical and diagnostic portfolios. Remidio occupies a distinct position within the domestic specialist tier, representing portable diagnostic innovation suited for rural outreach infrastructure. These named entities sit within broader competitive dynamics where registration timeline advantages and manufacturing subsidy access determine relative positioning across public and private procurement channels.
| Leading Market Players |
|---|
| Bausch + Lomb Corp. |
| Topcon Corporation |
| Alcon Inc. |
| Nidek Co Ltd |
| Hoya Corporation |
| Johnson & Johnson Vision Care |
| EssilorLuxottica SA |
| Remidio |
| Carl Zeiss Meditec AG |
| Others |
Supply & Pricing Matrix
The Dedicated Freight Corridor's western alignment compresses logistics costs between Mumbai-Pune manufacturing clusters and northern distribution nodes, concentrating pricing power among suppliers with direct rail access while forcing tiered cost absorption onto distributors serving Tier-II and Tier-III cities without corridor connectivity.
Pricing Analysis
Volume-discount tiering structures separate premium femtosecond laser platforms from standard phacoemulsification systems and economy-tier manual surgical sets across Maharashtra and Gujarat procurement consortia. Price differentiation hinges on CDSCO risk-classification tier and bundled after-sales service contracts, with government hospital tenders in Tamil Nadu and Karnataka exerting sustained downward pressure on intraocular lens pricing. Private eye care chains demonstrate lowest price sensitivity, absorbing premium positioning for bladeless cataract workflows, while rural outreach clinics in Andhra Pradesh operate at acute cost constraint.
Supply Chain Analysis
Tariff exposure between India and precision optics manufacturing centers in Germany and Japan dominates supply chain risk calculus for domestic assemblers of diagnostic equipment. German laser sources, Japanese optical coherence tomography sensors, and Chinese electronic subassemblies constitute critical input dependencies, with single-source vulnerability concentrated in femtosecond laser cavity components. Distribution runs through hospital procurement consortia in western and southern India that now bypass traditional distributor tiers for direct manufacturer negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consortia that aggregate demand across fifteen to twenty facilities simultaneously, fragmenting traditional distributor margins and forcing suppliers into direct volume negotiations with multi-hospital networks in Maharashtra and Gujarat.
For Market Incumbents: Build regulatory moats through accelerated CDSCO registration pathway mastery for novel laser platforms and AI-embedded diagnostic systems. Defensive consolidation requires backward integration into precision optical component manufacturing to mitigate currency volatility from German and Japanese supply chains, alongside captive service center deployment in Bengaluru and Hyderabad to preempt biomedical engineer shortage risks from emerging domestic competitors. For New Entrants and Emerging Players: Tier-III city clusters in Madhya Pradesh and Rajasthan present underpenetrated surgical capacity expansion zones where legacy hospital information systems create incumbent vulnerability. Portable diagnostic platforms with cloud-native architecture bypass interoperability constraints that handicap established vendors, while state-level vision screening missions in Karnataka and Andhra Pradesh offer direct public procurement channels unclaimed by multinational portfolios. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic-surgical convergence plays where software-dependent platforms command replacement cycle premiums over standalone hardware. Long-term viability across the analysis window rests on PLI scheme manufacturing subsidy capture and CDSCO registration timeline acceleration capabilities. The signal to watch is femtosecond laser platform adoption velocity in Gujarat and Telangana premium surgical centers as proxy for technology upgrade cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Compressed approval timelines under Medical Device Rules enable first-mover positioning in femtosecond laser categories. |
| Hospital System Partnership | Direct procurement consortia negotiations in Maharashtra and Gujarat disintermediate distributor tiers and lock multi-year equipment commitments. |
| Backward Integration | In-house production of precision optical components reduces import dependency on German and Japanese supply chains. |
| Software Companion Development | AI-embedded retinal pathology detection in OCT systems creates upgrade-dependent revenue streams and specialist workflow lock-in. |
| Reimbursement Strategy | Alignment with state-level vision screening missions in Karnataka and Andhra Pradesh secures direct public procurement volumes. |
Research Methodology
A standing panel of ophthalmic surgeons, hospital procurement committee members, biomedical engineering directors, and CDSCO regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from CDSCO medical device registration databases, state health mission tender documents, BIS certification records, and PLI scheme disbursement filings. Bottom-up equipment deployment tracking in Tier-II and Tier-III cities triangulated against top-down manufacturer shipment data to reconcile volume estimates.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user category, technology maturity tier, and application area. CAGRs derived from equipment replacement cycle analysis, surgical volume growth trajectories in cataract and retinal procedures, and technology adoption curve modeling for femtosecond platforms versus manual techniques. Forecast inputs incorporated CDSCO risk-classification revision impacts on registration timelines and PLI scheme manufacturing incentive uptake rates.
Practitioners should monitor CDSCO classification revisions, state-level screening mission budget allocations, and femtosecond laser adoption velocity for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Macular Edema Market
Ophthalmology
Retina Health Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Synoptophore Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Bullous Keratopathy Market