
 Operational Amplifier Market | 2026-2036
Operational Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Operational Amplifier Market Intelligence
Automotive tier-one suppliers is reorganizing the operational amplifier procurement landscape as electric powertrain and battery management systems displace traditional internal combustion architectures. Texas Instruments Inc. leverages its broad precision portfolio to anchor design wins across ADAS signal chains. Infineon Technologies specializes in automotive-qualified components with extended temperature ranges and AEC-Q100 certification. STMicroelectronics competes through integrated manufacturing scale at its French and Italian fabs.
An operational amplifier is a high-gain voltage amplification device with differential inputs and a single output, typically operating with supply voltages from 1.8 V to 36 V and input offset voltages as low as microvolts for precision variants; it functions as the fundamental building block for analog signal processing in sensor interfaces, audio paths, and control loops. CMOS technology dominates unit shipments due to low quiescent current demands in portable medical and consumer devices, while Bipolar architectures retain margin pools in high-speed instrumentation and test equipment where slew rate performance exceeds 100 V/µs. Precision op-amps command premium positioning in industrial automation and medical imaging, whereas general-purpose variants face commoditization pressure from Asian foundry competition.
RoHS and REACH frameworks in Europe restrict hazardous substances in semiconductor packaging materials, compelling suppliers to reformulate molding compounds and plating chemistries. The FDA in the United States enforces electromagnetic compatibility and isolation standards for op-amps deployed in patient-connected medical equipment, creating a compliance moat around qualified suppliers. Stakeholders must monitor how China's GB standards and dual carbon goals reshape local procurement mandates for analog components.
Market Dynamics
Automotive electrification is restructuring the operational amplifier value chain as battery management systems and electric powertrains displace internal combustion architectures, forcing tier-one suppliers to recalibrate sourcing specifications for precision analog components.
Growth Catalysts
- EU Green Deal:Carbon neutrality mandates accelerate demand for energy-efficient op-amps in industrial motor drives and renewable energy inverters across European manufacturing bases.
- Electric vehicle battery management:Cell monitoring and thermal runaway detection circuits require high-precision voltage sensing, expanding unit volumes for automotive-qualified operational amplifiers.
- China's dual carbon goals:Domestic fab expansion and local sourcing mandates under GB standards are concentrating procurement decisions within Chinese supply chains.
Market Restraints
- Silicon wafer cost volatility:Input price swings for 300mm wafers compress margins on general-purpose op-amp variants already facing Asian foundry oversupply.
- Packaging material restrictions:REACH and RoHS compliance costs for lead-free plating and halogen-free molding compounds add 8-12% to qualified component production expenses.
- Discrete alternative encroachment:Integrated analog front-ends in system-on-chip designs threaten standalone op-amp sockets in consumer audio and basic sensing applications.
Strategic Opportunities
- Medical imaging expansion:MRI gradient amplifiers and ultrasound front-ends in the United States create premium positioning for ultra-low-noise precision variants under FDA electromagnetic compatibility requirements.
- 5G base station deployment:Massive MIMO antenna calibration circuits in South Korea and Japan demand high-speed bipolar op-amps with slew rates exceeding 100 V/µs.
- Industrial automation retrofit:Edge computing nodes in German and Italian manufacturing clusters require rail-to-rail CMOS devices for sensor signal conditioning in legacy equipment upgrades.
Industry Challenges
- Analog design talent scarcity:Experienced IC layout engineers capable of optimizing offset voltage and noise floors command premium compensation, constraining product pipeline velocity.
- AEC-Q100 certification timelines:Extended qualification cycles for automotive temperature grades delay revenue recognition by 18-24 months for new precision amplifier introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operational Amplifier Market |
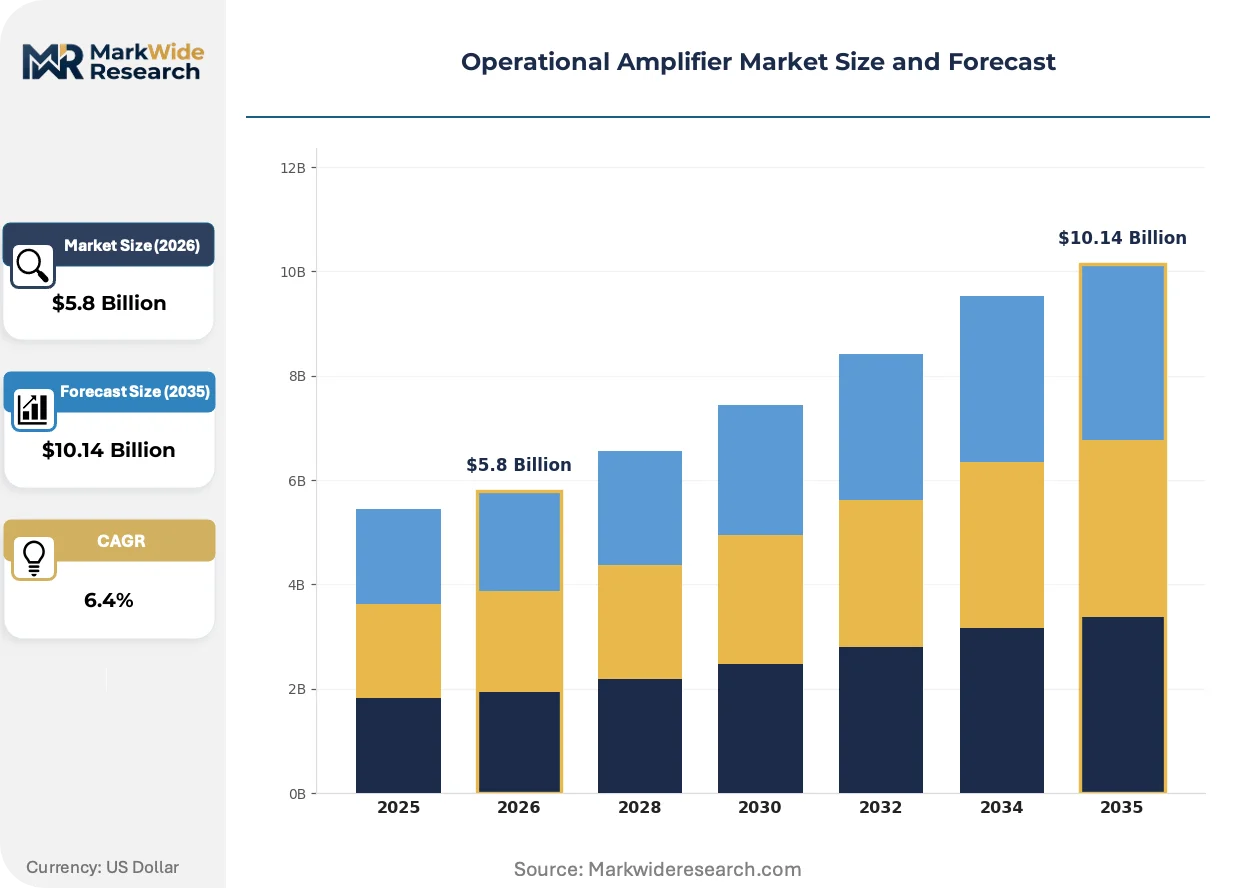
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General-Purpose, Precision, Low-Noise, Instrumentation Technology: CMOS, Bipolar, BiCMOS, JFET End User: Consumer Electronics, Automotive, Industrial, Medical Application: Signal Conditioning, Filtering, Data Acquisition, Control Systems |
| Companies Covered | ON Semiconductor, Renesas Electronics, Texas Instruments Inc., Microchip Technology, Infineon Technologies, Analog Devices Inc., NXP Semiconductors, Cirrus Logic, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operational Amplifier Market Strategic Shifts & Innovations
Three interconnected developments are compressing product lifecycles and reconfiguring competitive positioning in operational amplifiers: silicon integration advances, regulatory material mandates, and procurement centralization among automotive tier-ones.
Chopper-stabilized zero-drift architecture is decomposing the traditional trade-off between precision and power consumption in battery-powered instrumentation. Portable medical device manufacturers in the United States and Germany are adopting these devices at accelerating rates for glucose monitors and wearable ECG systems. This technology is decomposing the premium pricing power of legacy bipolar precision op-amps by delivering microvolt offset performance at nanoamp quiescent currents.
REACH substance restrictions are compelling reformulation of epoxy molding compounds and tin-based plating chemistries across European-bound semiconductor packaging. ECHA enforcement of candidate list updates forces suppliers to maintain dual material sets, fragmenting inventory management. Medical equipment suppliers face the strictest compliance burden, as RoHS exemptions for high-reliability applications narrow and CE marking audits intensify.
Consolidated sourcing agreements now dominate automotive analog procurement, with tier-one suppliers negotiating multi-year frame contracts directly with fab-owning IDMs. Distributor inventories are compressing as just-in-time delivery windows tighten to 4-6 weeks. This concentration is most visible in China, where domestic EV manufacturers are mandating local content ratios that exclude non-Chinese packaging and test subcontractors from qualified vendor lists.
Operational Amplifier Market Segmentation
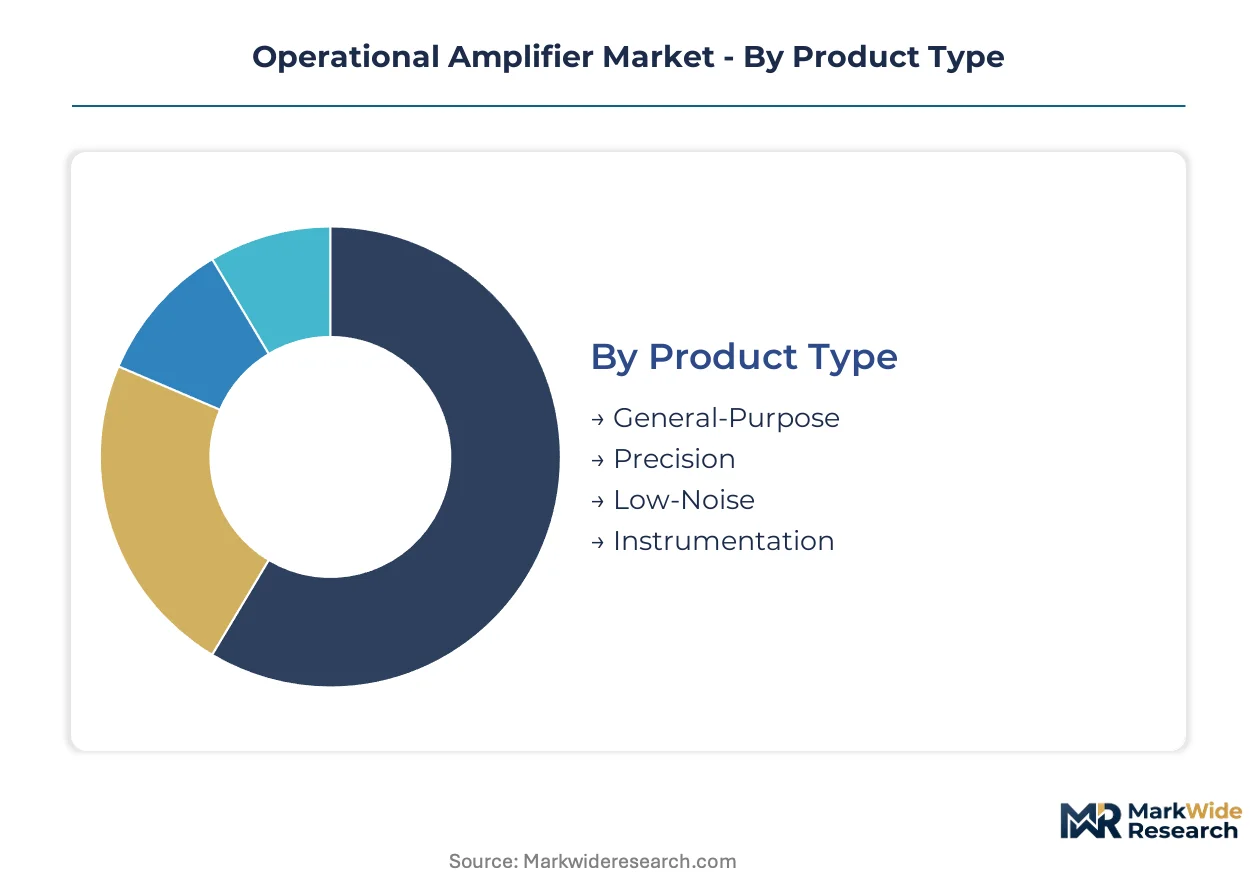
Margin capture in operational amplifiers diverges sharply across performance tiers and process technologies. Procurement specifications from automotive and medical end-users are fragmenting the addressable market into distinct qualification tracks with incompatible cost structures.
Product Type:
Precision variants command the deepest margin pools, while general-purpose devices face relentless foundry commoditization.
- General-Purpose:Basic voltage amplification with moderate offset specifications and standard temperature ranges. Consumer electronics manufacturers in China and contract equipment builders in Taiwan absorb volume shipments for audio buffering and simple sensor interfaces, though Asian foundry oversupply compresses realized pricing.
- Precision:Microvolt input offset voltage and drift characteristics below 0.01 µV/°C. Battery management systems in German automotive plants and MRI gradient amplifiers under FDA electromagnetic compatibility mandates concentrate demand, with AEC-Q100 and medical-grade certifications sustaining premium positioning.
- Low-Noise:Voltage noise density below 1 nV/√Hz for sensitive front-end applications. Professional audio interfaces and scientific instrumentation in Japan and South Korea represent primary demand clusters.
- Instrumentation:Integrated differential amplification with high common-mode rejection for bridge sensors and strain gauges. Industrial automation retrofits across Italian manufacturing clusters and weigh-scale manufacturers in Germany anchor procurement volumes.
Precision holds installed capacity. Low-Noise is rotating up the share rankings.
Technology:
Process selection determines power-performance trade-offs and foundry access, with CMOS dominating unit economics and Bipolar retaining speed premiums.
- CMOS:Sub-micron processes enabling nanoamp quiescent currents and rail-to-rail input/output swing. Portable medical device manufacturers in the United States and Germany—producing glucose monitors and wearable ECG systems—drive volume adoption for battery-powered instrumentation.
- Bipolar:Vertical NPN structures delivering slew rates exceeding 100 V/µs and superior transconductance linearity. Test equipment manufacturers and 5G base station designers in South Korea and Japan absorb output for high-speed signal paths where settling time dominates specifications.
- BiCMOS:Merged CMOS-Bipolar processes combining digital control with analog precision. Mixed-signal industrial controllers and programmable logic interfaces concentrate demand.
- JFET:Junction-field-effect input stages offering ultra-low input bias current for high-impedance sensor interfaces. pH meters and photodiode amplifiers in laboratory equipment represent niche applications.
CMOS maintains the broadest installed base. BiCMOS is climbing fastest in industrial automation sockets.
End User:
Automotive qualification requirements are restructuring procurement concentration, while medical certification creates defensible margin enclaves.
- Consumer Electronics:High-volume, cost-optimized sockets in smartphones, tablets, and wireless audio accessories. Chinese OEMs and contract manufacturers drive procurement with compressed lead times and minimal qualification overhead.
- Automotive:AEC-Q100 temperature grades from -40°C to 125°C and enhanced electromagnetic immunity for electric powertrain electronics. Tier-one suppliers in Germany, Japan, and China negotiate multi-year frame contracts directly with fab-owning IDMs for battery management and ADAS signal chains.
- Industrial:Extended temperature ranges and high reliability for motor drives, process control, and factory automation. German and Italian manufacturing clusters retrofitting edge computing nodes generate sustained replacement demand.
- Medical:FDA electromagnetic compatibility and isolation standards for patient-connected equipment. MRI and ultrasound OEMs in the United States pay premiums for ultra-low-noise precision variants with documented traceability.
Automotive is accumulating the fastest share expansion. Medical retains the most pricing power per qualified socket.
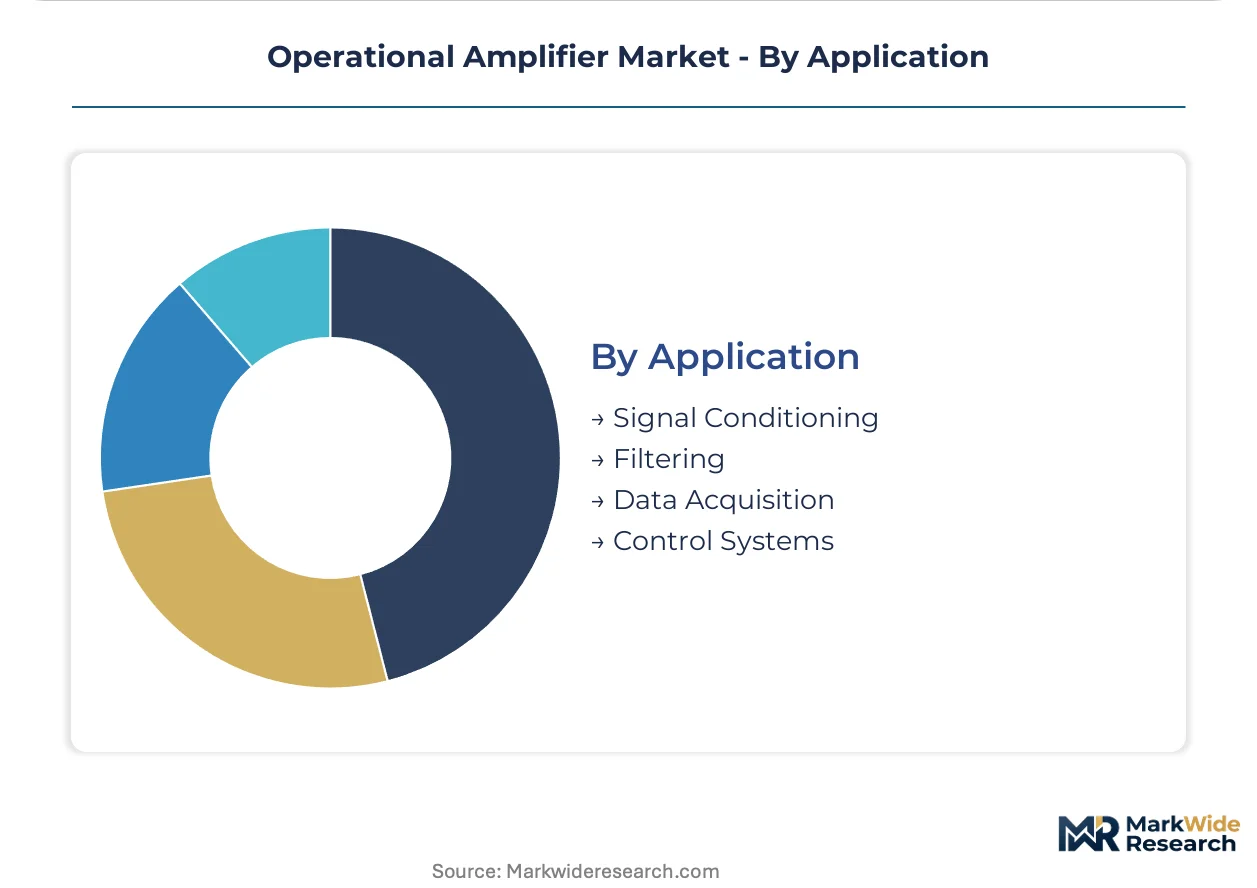
Application:
Functional use cases map directly to performance tier selection, with signal conditioning absorbing the highest aggregate unit volumes.
- Signal Conditioning:Sensor bridge excitation, amplification, and level translation for analog-to-digital converter interfaces. Industrial IoT deployments and automotive sensor fusion architectures concentrate demand across multiple end-use verticals.
- Filtering:Active filter topologies for anti-aliasing, noise reduction, and frequency response shaping. Audio equipment and data acquisition front-ends in professional and consumer segments absorb specialized low-distortion variants.
- Data Acquisition:Precision buffering and multiplexing for analog measurement systems. Automated test equipment and scientific instrumentation require matched offset specifications across channel arrays.
- Control Systems:Error amplification and compensation networks for feedback loops in power supplies and motor controllers. Servo drives and renewable energy inverters under EU Green Deal efficiency mandates drive precision requirements.
Signal Conditioning dominates cumulative shipments. Data Acquisition is advancing fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for precision analog components clusters in East Asia and Western Europe, with packaging and test operations dispersing to Southeast Asia and Mexico to satisfy regional content requirements.
China
Domestic EV manufacturers are mandating local content ratios for battery management systems, excluding foreign packaging subcontractors from qualified vendor lists. MIIT enforces GB standards and dual carbon goals that reshape procurement mandates for analog components. Yangtze River Delta fabs in Shanghai and Wuxi are expanding 300mm capacity for automotive-qualified operational amplifiers.
Germany
Industrial automation retrofits across manufacturing clusters generate sustained replacement demand for rail-to-rail CMOS devices. EU Green Deal carbon neutrality mandates accelerate procurement of energy-efficient op-amps for motor drives and renewable energy inverters. Bavarian automotive suppliers negotiate multi-year frame contracts directly with IDMs for electric powertrain signal chains.
United States
MRI gradient amplifiers and ultrasound front-ends create premium positioning for ultra-low-noise precision variants. FDA electromagnetic compatibility and isolation standards enforce compliance moats around qualified suppliers for patient-connected equipment. Greater Boston and Austin medical device clusters concentrate design wins for chopper-stabilized zero-drift architectures.
Japan
5G base station deployment drives demand for high-speed bipolar op-amps with slew rates exceeding 100 V/µs for massive MIMO antenna calibration. METI industrial policy supports domestic analog semiconductor production for strategic autonomy. Nagoya and Osaka manufacturing belts anchor test equipment and scientific instrumentation procurement.
South Korea
Memory semiconductor manufacturers are diversifying into analog front-ends for display driver ICs and camera modules. MFDS medical device regulations align with international standards for portable diagnostic equipment. Seoul Capital Area fabs are qualifying zero-drift precision amplifiers for wearable health monitors.
Operational Amplifier Market Key Industry Players
Concentration sits with diversified analog IDMs owning captive fabrication and automotive qualification expertise. The vendor base stratifies across three tiers: broad-line suppliers with full precision portfolios, automotive-specialized fabricators with AEC-Q100 certification, and regional foundry services targeting consumer commoditization. Strategic moves center on multi-year frame contracts with tier-one automotive suppliers and backward integration into 300mm wafer supply.
Within the broad-line tier, Texas Instruments Inc. and Analog Devices Inc. exemplify scale-driven diversification across industrial, medical, and automotive verticals. Infineon Technologies occupies a position anchoring automotive-qualified specialization with extended temperature range expertise. These three represent the dominant archetypes: portfolio breadth, automotive certification depth, and integrated manufacturing scale.
| Leading Market Players |
|---|
| ON Semiconductor |
| Renesas Electronics |
| Texas Instruments Inc. |
| Microchip Technology |
| Infineon Technologies |
| Analog Devices Inc. |
| NXP Semiconductors |
| Cirrus Logic |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Four-to-six-week just-in-time delivery windows for automotive-qualified components concentrate pricing power with fab-owning IDMs negotiating multi-year frame contracts directly with Bavarian tier-one suppliers, while distributor inventories compress and spot-market access for precision variants tightens under AEC-Q100 certification timelines.
Pricing Analysis
REACH and RoHS compliance dictates the pricing tier structure across European-bound operational amplifiers, separating medical-grade precision variants with documented traceability from general-purpose CMOS devices facing Asian foundry commoditization. Price differentiation rests on AEC-Q100 certification level and volume scale, with automotive temperature grades commanding premiums against consumer electronics sockets. Cost compression in general-purpose tiers is intensifying because 300mm wafer input volatility squeezes margins already eroded by Chinese domestic fab expansion. Consumer electronics manufacturers in China exhibit highest price sensitivity, while MRI OEMs in the United States show least sensitivity due to FDA electromagnetic compatibility mandates.
Supply Chain Analysis
Inventory compression to 4-6 week delivery windows for automotive sockets concentrates supply in Taiwan, South Korea, and China, where Yangtze River Delta fabs expand 300mm capacity for battery management systems. Raw material dependencies center on 300mm silicon wafers, lead-free plating chemistries, and halogen-free epoxy molding compounds. Single-source vulnerability around qualified packaging subcontractors in China exposes foreign suppliers to MIIT local content mandates. Distribution runs through consolidated tier-one procurement desks with direct IDM contracting, bypassing traditional distributor channels for precision automotive variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Experienced IC layout engineers capable of optimizing offset voltage and noise floors command premium compensation, constraining product pipeline velocity and creating acquisition premiums for teams with proven chopper-stabilized architectures.
For Market Incumbents: Secure captive 300mm wafer supply through backward integration or long-term offtake agreements with Yangtze River Delta and Taiwanese foundries to defend against Chinese domestic fab expansion. Deepen AEC-Q100 certification pipelines to 18-24 month qualification cycles, locking tier-one automotive sockets before emerging BiCMOS specialists achieve temperature grade parity. Channel control through direct frame contracts with German and Japanese tier-ones reduces distributor dependency. For New Entrants and Emerging Players: After-sales technical support gaps in industrial automation retrofits across Italian manufacturing clusters offer service-layer differentiation against broad-line incumbents. Target precision low-noise variants for professional audio interfaces in Japan and South Korea, where slew rate specifications exceed 100 V/µs and bipolar expertise concentrates. Go-to-market angle: zero-drift chopper-stabilized architectures for portable medical device manufacturers in Greater Boston and Austin seeking FDA-compliant glucose monitors and wearable ECG systems. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automotive electrification concentrates procurement among tier-ones with multi-year qualification requirements, raising barriers for new entrants and sustaining premium multiples for qualified precision portfolios. Acquisition target archetype: mid-cap analog specialists with AEC-Q100 automotive certification and existing frame contracts with German or Chinese tier-ones. Signal to watch: MIIT enforcement of GB standards local content ratios accelerating domestic Chinese packaging qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 300mm Wafer Supply | Captive silicon supply from Yangtze River Delta fabs insulates margins against input volatility under MIIT expansion mandates. |
| AEC-Q100 Certification Pipeline Expansion | Extended temperature grade qualification locks automotive sockets before BiCMOS competitors achieve thermal runaway detection circuit parity. |
| Chopper-Stabilized Zero-Drift Architecture R&D | Microvolt offset performance at nanoamp quiescent currents decomposes legacy bipolar precision pricing power in portable medical devices. |
| Direct Frame Contracts with Tier-One Suppliers | Bypassing distributor channels concentrates pricing power with Bavarian and Chinese automotive procurement desks. |
| REACH-Compliant Material Reformulation | Lead-free plating and halogen-free molding compounds sustain European market access under ECHA candidate list enforcement. |
Research Approach
A standing panel of analog IC design directors, tier-one automotive procurement managers, medical device regulatory affairs leads, and semiconductor distribution channel heads provided ongoing calibration against secondary validation from SEC 10-K filings, MIIT capacity expansion disclosures, FDA electromagnetic compatibility guidance documents, and ECHA REACH candidate list updates. Bottom-up unit shipment modeling across precision, low-noise, general-purpose, and instrumentation product types triangulated with top-down value estimates from foundry utilization rates and frame contract disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions covering technology node, end-user vertical, and application function. CAGRs derived from fitted growth curves incorporating automotive electrification penetration rates, 5G base station deployment schedules, and industrial automation retrofit cycles. Forecast inputs included 300mm wafer supply elasticity, AEC-Q100 certification queue lengths, and Chinese domestic fab capacity commissioning timelines.
Underlying assumptions cover sustained automotive electrification investment, REACH substance restriction enforcement continuity, and Chinese local content mandate implementation, with deviation risk concentrated in silicon wafer cost volatility and analog design talent scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Power Inductors Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Industrial Relays Market
Electronic Components
Safety Relay Market
Electronic Components
Display Port Adapters Market
Electronic Components
Audio Amplifier Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Trackpad Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Electronic Wipe Market
Electronic Components
Touchless Tubes Market