
 Wearable Technology Component Market | 2026-2036
Wearable Technology Component Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Technology Component Market Analytics
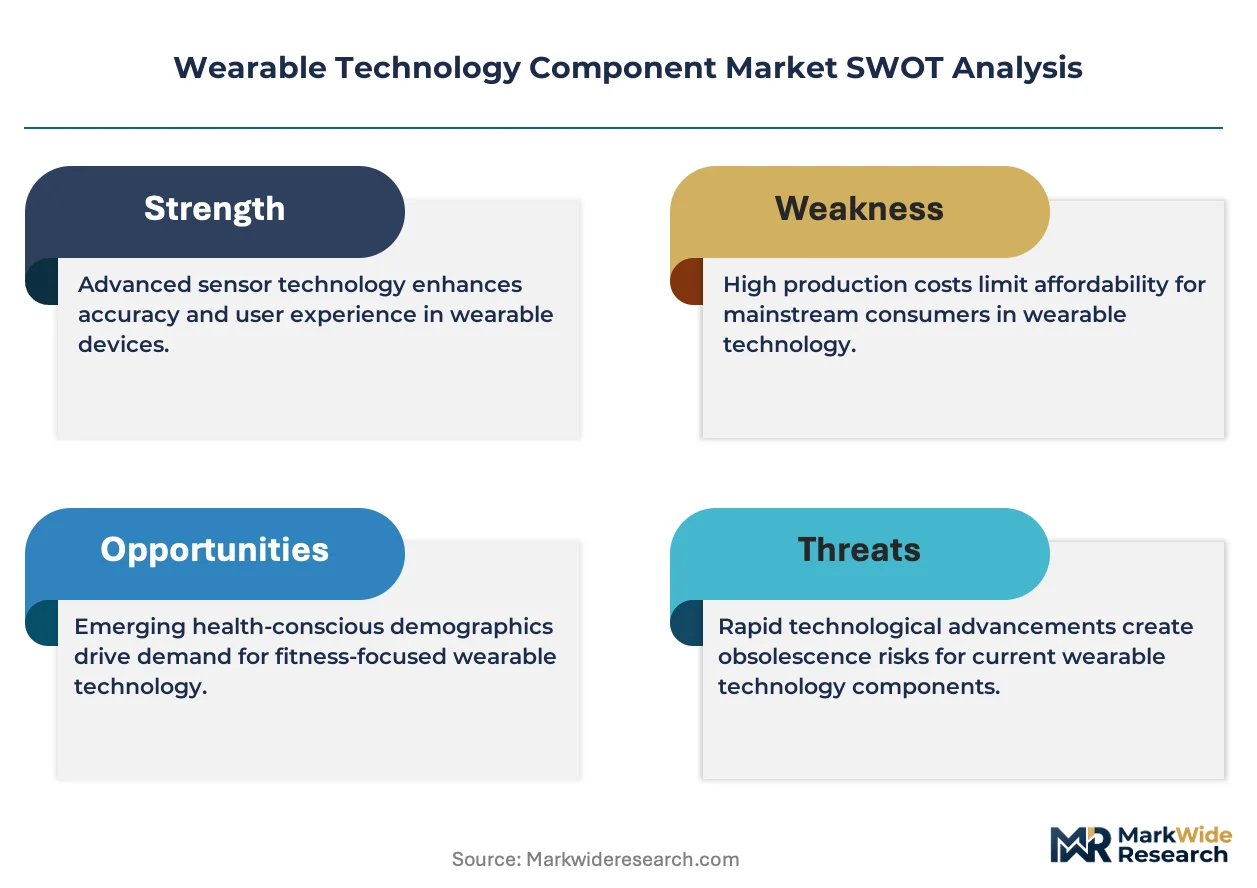
Taiwanese semiconductor foundry capacity is shifting toward ultra-low-power process nodes purpose-built for wrist-worn and body-worn devices. Qualcomm Technologies leverages its Snapdragon Wear platform to anchor premium smartwatch silicon supply. STMicroelectronics sustains leadership in MEMS motion sensors for fitness trackers. Texas Instruments competes through analog power management ICs that extend battery life in compact form factors.
Wearable technology components comprise miniature electronic subsystems—typically incorporating sensors, wireless transceivers, power management circuits, and flexible substrates within sub-gram assemblies—engineered to operate at sub-milliwatt power budgets while maintaining continuous physiological or environmental data acquisition. These components serve consumer, clinical, and industrial applications where unobtrusive body-worn instrumentation enables real-time monitoring and two-way connectivity. Smartwatches dominate current value capture due to display and processor complexity, while wearable medical devices represent the fastest-expanding margin pool as clinical validation requirements deepen. Bluetooth technology leads connectivity attach rates, though NFC is carving a dedicated position in payment-authentication and access-control use cases.
The FDA governs wearable medical devices through 510(k) and De Novo pathways that demand clinical evidence for arrhythmia detection and blood glucose monitoring claims. The FCC regulates radio frequency emissions from Wi-Fi and Bluetooth modules integrated into body-worn hardware. The EU Medical Device Regulation and CE marking framework impose biocompatibility, cybersecurity, and post-market surveillance obligations that reshape component selection and supplier qualification timelines. Stakeholders must monitor evolving regulatory divergence between FDA software-as-medical-device guidance and EU MDR implementing acts to avoid fragmented certification costs.
Market Dynamics
Continuous monitoring patches for remote patient management are forcing component suppliers to redesign power budgets and biocompatibility profiles around FDA 510(k) and EU MDR clinical validation timelines. Healthcare providers now demand sub-milliwatt sensor modules with wireless transceivers that maintain uninterrupted physiological data streams across multi-day wear cycles.
Growth Catalysts
- EU Medical Device Regulation:Tightening biocompatibility and cybersecurity mandates for body-worn electronics are accelerating supplier qualification programs and creating captive demand for certified component vendors.
- Remote patient monitoring:Healthcare systems in aging economies are deploying continuous glucose and cardiac patches that require ultra-low-power analog front-ends and flexible substrate assemblies.
- Shenzhen manufacturing cluster:Concentrated sensor module foundry capacity enables rapid prototyping and volume scaling for brands across North America and Asia.
Market Restraints
- Lithium-polymer cell volatility:Battery chemistry constraints limit energy density in sub-gram form factors, compressing operational lifespan between recharges for multi-sensor arrays.
- MEMS foundry concentration:Motion sensor fabrication relies on a narrow base of specialized semiconductor facilities, creating supply vulnerability for fitness tracker OEMs.
- Biocompatibility certification friction:ISO 10993 testing timelines for skin-contact adhesives and encapsulants extend product development cycles by 12-18 months.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting component assembly investments to serve domestic wearable demand and export markets.
- NFC payment authentication:Contactless transaction modules are penetrating access-control and transit applications beyond traditional smartwatch form factors.
- AI at the edge:On-device neural processing for arrhythmia classification is converging with ultra-low-power process nodes to enable clinical-grade diagnostics without cloud dependency.
Industry Challenges
- Multiphysics simulation expertise:Shortage of engineers capable of modeling thermal, mechanical, and electromagnetic interactions in compact body-worn assemblies delays design validation.
- Software-as-medical-device alignment:Divergent FDA guidance and EU MDR implementing acts on algorithm-based diagnostic claims fragment certification strategies for multi-market vendors.
- Legacy hospital IT integration:Wearable data streams require interoperability with entrenched electronic health record systems, complicating deployment workflows for clinical-grade devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Technology Component Market |
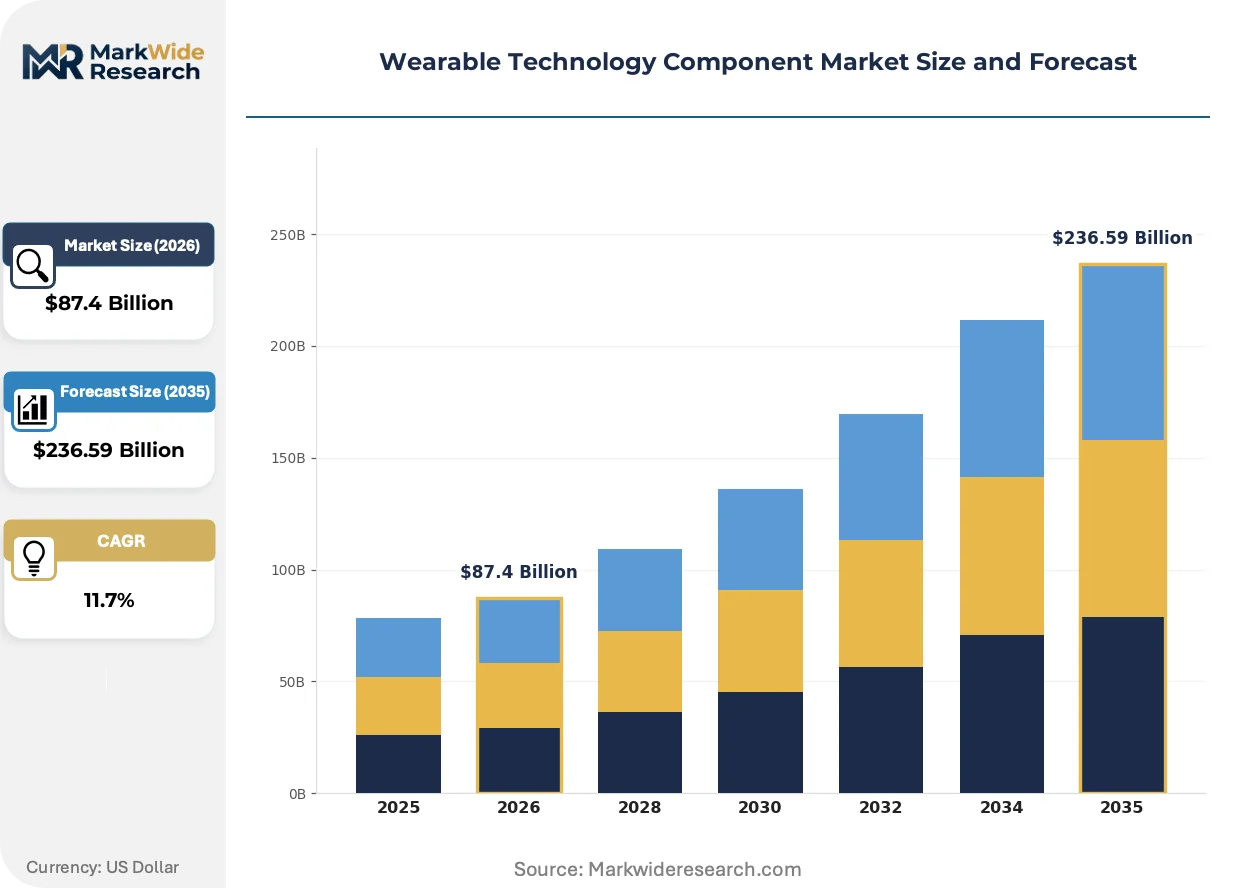
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $236.59 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Wearable Medical Devices Technology: Bluetooth, NFC, Wi-Fi, RFID Application: Health Monitoring, Fitness Tracking, Communication, Entertainment End User: Fitness Enthusiasts, Healthcare Providers, Tech Savvy Consumers, Corporations |
| Companies Covered | Qualcomm Technologies, STMicroelectronics, Texas Instruments, Broadcom, Analog Devices, Infineon Technologies, NXP Semiconductors, Sony, Huami, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Technology Component Market Evolving Landscape
Edge AI inference engines are automating physiological signal processing directly on wrist-worn and patch-based hardware, eliminating cloud latency for time-critical diagnostic alerts. This architectural shift is redrawing power budget allocations and semiconductor supplier relationships across the component stack.
Photoplethysmography with multi-wavelength LED arrays is automating blood oxygen and hydration monitoring in fitness trackers. Consumer OEMs are adopting these modules at accelerated refresh cycles. The technology is compressing the feature gap between clinical monitors and lifestyle wearables, forcing component suppliers to bridge precision and cost targets simultaneously.
EU MDR post-market surveillance obligations are mandating cybersecurity documentation and biocompatibility traceability for all body-worn electronics claiming clinical utility. Component vendors must now maintain technical files spanning raw material sourcing through end-of-life disposal. Wearable medical device segments face the steepest compliance cost escalation as notified body capacity constrains certification throughput.
Direct-to-consumer clinical wearable brands are bypassing traditional distributor networks and engaging sensor foundries through dedicated supply agreements. This channel disintermediation concentrates procurement leverage with vertically integrated hardware startups. North American telehealth platforms exhibit the most aggressive supplier consolidation, locking multi-year capacity at Taiwanese analog IC foundries.
Wearable Technology Component Market Segmentation
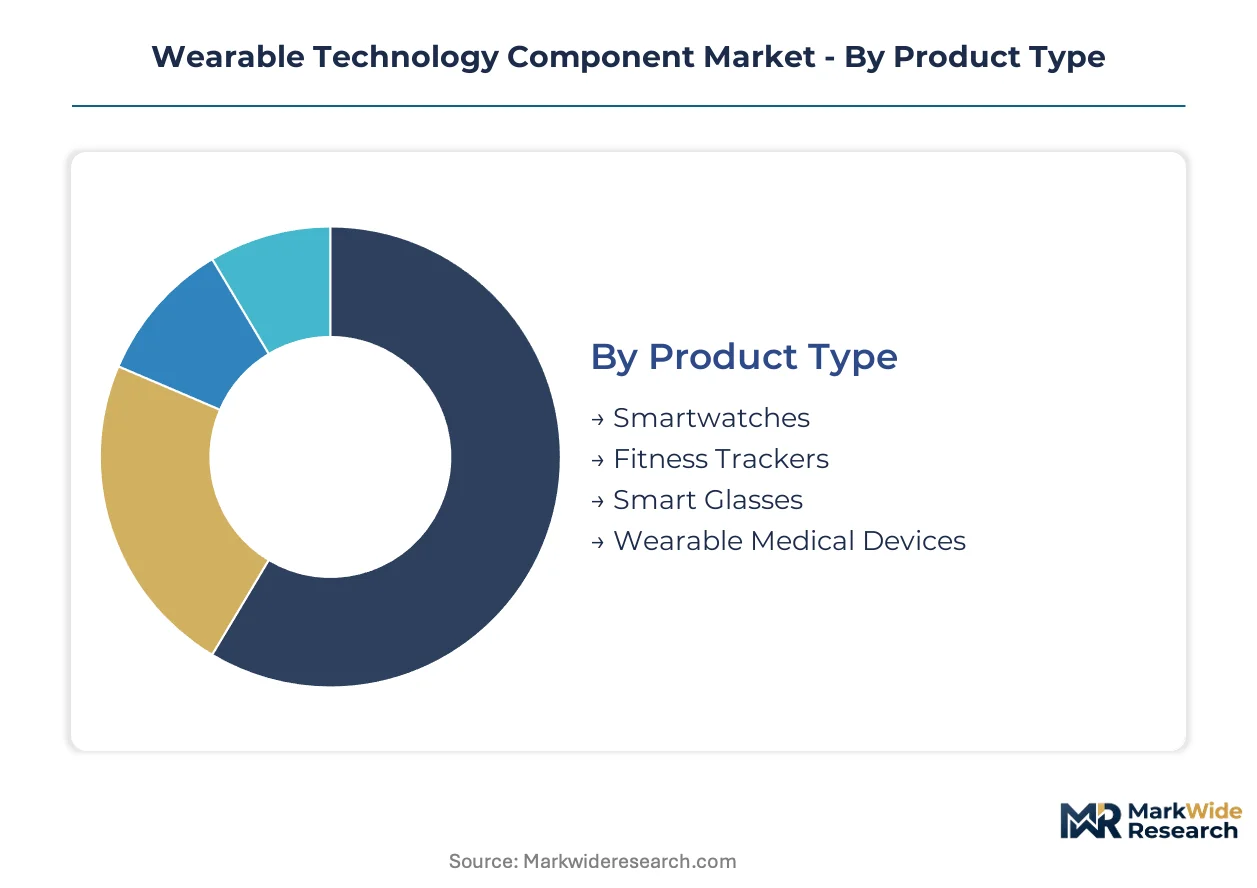
Component suppliers in the Wearable Technology Component Market must align power budgets, wireless protocols, and biocompatibility profiles against sharply divergent end-use requirements. Segmentation reveals where margin pools concentrate and which certification pathways govern supplier qualification timelines.
Product Type:
Smartwatches command premium component pricing through display complexity and processor integration, while wearable medical devices concentrate the steepest margin expansion as clinical validation requirements deepen.
- Smartwatches:These assemblies integrate AMOLED display drivers, application processors, and multi-sensor hubs within sub-5-gram enclosures. Demand clusters with North American consumer electronics brands refreshing hardware annually. Qualcomm's Snapdragon Wear platform anchors silicon supply for premium tiers.
- Wearable Medical Devices:Continuous monitoring patches for cardiac rhythm and glucose surveillance require ISO 10993-certified adhesives and FDA 510(k) cleared analog front-ends. Healthcare providers in Germany and Japan are expanding remote patient management deployments, forcing sub-milliwatt power architectures.
- Fitness Trackers:STMicroelectronics MEMS motion sensors dominate step-counting and sleep-stage algorithms in wrist-worn form factors.
- Smart Glasses:Waveguide optics and micro-LED projection modules remain supply-constrained, limiting volume scaling outside enterprise pilot programs.
Today's leader: Smartwatches. Tomorrow's challenger: Wearable Medical Devices.
Technology:
Connectivity protocol selection determines antenna design, certification jurisdiction, and power budget allocation across the component stack.
- Bluetooth:Low-energy 5.3 stacks achieve near-universal attach rates in wrist-worn hardware, with Nordic Semiconductor and Texas Instruments competing on link-layer power consumption. Fitness tracker OEMs in Shenzhen's manufacturing cluster source pre-certified modules to compress development cycles.
- NFC:Contactless payment authentication and access-control use cases are penetrating transit and enterprise badge applications beyond traditional smartwatch boundaries. NXP Semiconductors and STMicroelectronics supply secure element integration for EMV compliance.
- Wi-Fi:Higher throughput demands for standalone music streaming and voice assistant offload drain battery budgets, limiting deployment to premium smartwatch tiers.
- RFID:Passive backscatter tags enable inventory and patient identification without onboard power, serving industrial and hospital asset-tracking verticals.
Bluetooth anchors current volume. NFC is climbing the fastest as payment infrastructure matures.
Application:
Health monitoring applications command the strictest regulatory scrutiny, while entertainment use cases prioritize display bandwidth and audio codec efficiency.
- Health Monitoring:Photoplethysmography with multi-wavelength LED arrays automates blood oxygen and atrial fibrillation detection. EU MDR post-market surveillance obligations now mandate cybersecurity documentation for all body-worn electronics claiming clinical utility.
- Fitness Tracking:Accelerometer and gyroscope fusion algorithms for VO2 max estimation require MEMS foundry capacity concentrated in Taiwan and South Korea.
- Communication:LTE-M and NB-IoT modems for standalone voice calling compress battery life, constraining adoption to high-end smartwatch segments.
- Entertainment:Spatial audio DSPs and haptic feedback drivers serve gaming and immersive media applications with minimal regulatory friction.
Health Monitoring captures the deepest margin pool. Fitness Tracking scales the broadest volume base.
End User:
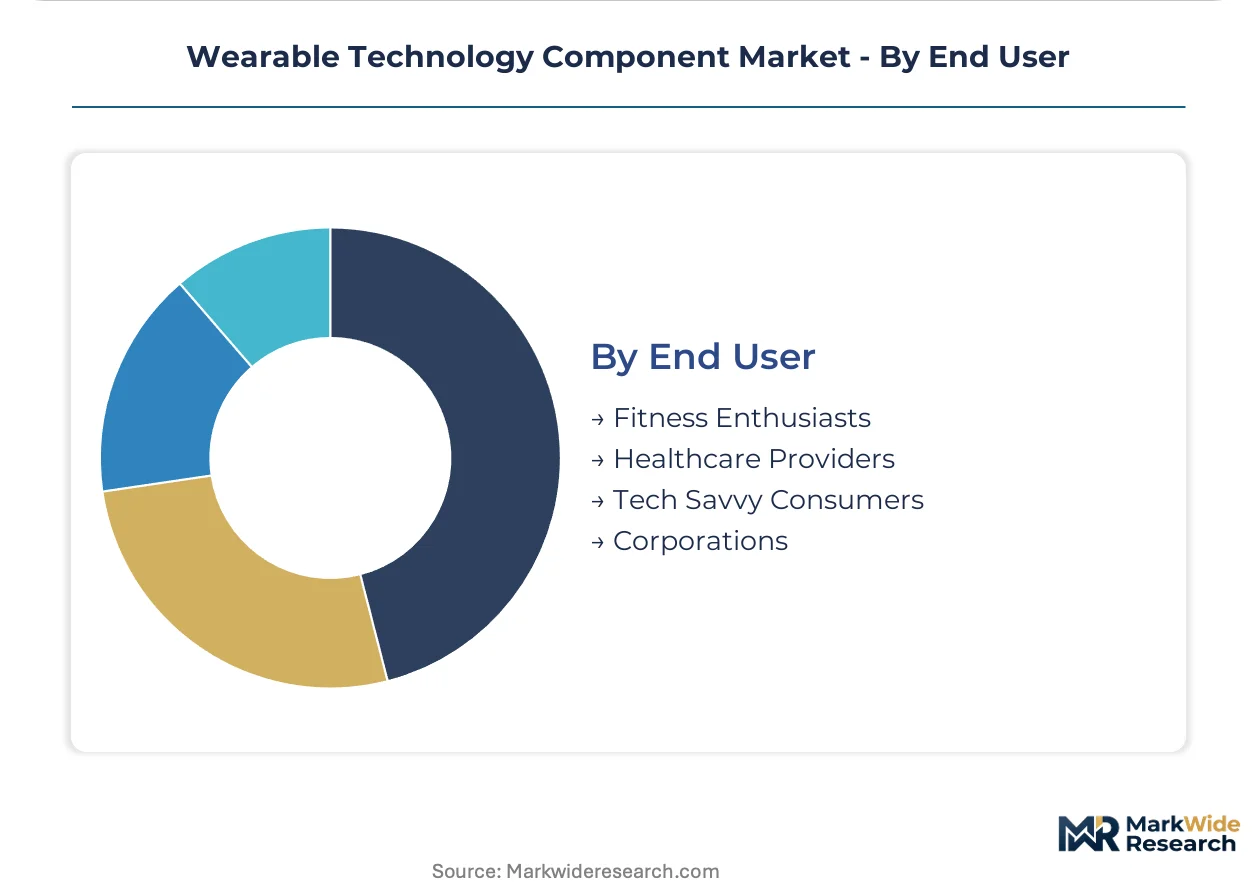
Healthcare providers impose the longest supplier qualification timelines, while fitness enthusiasts drive the fastest hardware refresh cycles.
- Healthcare Providers:Hospital systems in the United States and Germany demand interoperability with Epic and Cerner electronic health record platforms, complicating wearable data integration workflows. FDA software-as-medical-device guidance and EU MDR implementing acts fragment certification strategies for multi-market vendors.
- Fitness Enthusiasts:Strava and Garmin Connect ecosystem loyalty drives sensor accuracy expectations for GPS and heart rate variability tracking.
- Tech Savvy Consumers:Early adopters prioritize notification mirroring and voice assistant responsiveness over clinical-grade precision.
- Corporations:Wellness program subsidies and lone-worker safety mandates are emerging procurement channels for fleet-deployed wearables.
Healthcare Providers anchor premium pricing. Fitness Enthusiasts drive volume velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component suppliers are arbitraging regulatory compliance costs by shifting assembly toward jurisdictions with streamlined certification pathways, while maintaining design and validation proximity to end markets. Production gravitates toward manufacturing clusters that balance FDA and EU MDR access with favorable duty structures.
United States
Hospital systems in California and Texas are expanding remote patient monitoring programs that demand FDA 510(k) cleared analog front-ends. The FDA's software-as-medical-device guidance creates certification clarity for algorithm-based diagnostic claims. Boston's medical device corridor anchors clinical validation partnerships between wearable startups and academic medical centers.
Germany
Healthcare providers in Bavaria and North Rhine-Westphalia are deploying continuous cardiac patches for post-acute care management. The EU MDR's biocompatibility mandates are extending supplier qualification timelines for skin-contact adhesives. Stuttgart's automotive electronics ecosystem is repurposing MEMS fabrication expertise for medical-grade motion sensors.
China
Shenzhen's component manufacturing cluster serves smartwatch brands across Asia and North America with pre-certified Bluetooth and NFC modules. The NMPA's medical device classification rules are tightening for glucose monitoring wearables claiming clinical utility. Shanghai's Yangtze River Delta concentration hosts analog IC foundries producing ultra-low-power power management circuits.
India
Domestic wearable brands in Karnataka and Maharashtra are sourcing sensor modules for fitness trackers targeting price-sensitive consumers. The PLI scheme for electronics manufacturing is attracting component assembly investments to serve export markets. Delhi-NCR's emerging hardware startup ecosystem is prototyping health monitoring devices for telehealth platforms.
Japan
Aging demographics in Tokyo and Osaka are driving demand for continuous monitoring patches for home-based elderly care. The PMDA's regulatory framework for software-enabled medical devices is converging with international standards to streamline multi-market approvals. Kyushu's semiconductor facilities are dedicating capacity to ultra-low-power process nodes for wrist-worn health monitors.
Wearable Technology Component Market Competitive Landscape
Established semiconductor foundries occupy the standard tier; emerging fabless entrants pursue differentiated sensor integration and edge AI acceleration. Market structure concentrates around analog IC specialists, MEMS fabricators, and wireless connectivity module suppliers. Three archetypes dominate: integrated platform providers bundling processors and connectivity, discrete component specialists optimizing single-function performance, and vertically integrated OEMs captive-producing critical subsystems. Competitive moves center on process node transitions toward sub-10nm ultra-low-power geometries and strategic partnerships with medical device brands seeking pre-certified component supply.
Within the integrated platform tier, Qualcomm Technologies and Broadcom exemplify the connectivity-processor convergence archetype. Among discrete component specialists, STMicroelectronics and Texas Instruments occupy positions anchored by MEMS and analog power management expertise respectively. Infineon Technologies and NXP Semiconductors represent the secure connectivity and sensor fusion segment. Sony and Huami sit within the vertically integrated OEM category, with the latter reflecting Chinese hardware ecosystem consolidation.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| STMicroelectronics |
| Texas Instruments |
| Broadcom |
| Analog Devices |
| Infineon Technologies |
| NXP Semiconductors |
| Sony |
| Huami |
| Others |
Value Network & Pricing Analysis
North American telehealth platforms and German hospital systems anchor procurement leverage for clinical-grade wearable components, forcing suppliers toward contract-based long-term offtake structures that embed FDA 510(k) and EU MDR certification costs into unit economics. Direct-to-consumer clinical wearable brands are bypassing distributor networks entirely, compressing channel margins and concentrating price negotiation power with vertically integrated hardware startups.
Pricing Analysis
Distributor margins for Bluetooth and NFC modules compress as Shenzhen-based sensor foundries sell direct to smartwatch OEMs. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, ISO 10993 biocompatibility grade, and volume scale commitments. Pricing pressure stems from lithium-polymer cell volatility and MEMS foundry concentration. Fitness tracker OEMs in Asia exhibit highest price sensitivity; healthcare providers in Germany and Japan accept premium pricing for clinical validation depth.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Taipei, and Shanghai orchestrate hub-and-spoke patterns for sensor modules serving North American and European brands. Taiwan and South Korea anchor MEMS motion sensor fabrication; China dominates flexible substrate assembly and analog IC packaging. Raw material dependencies include lithium-polymer cells, silicon wafers, and medical-grade adhesives. Single-source vulnerability in specialized semiconductor facilities threatens fitness tracker OEMs. Distribution runs through dedicated supply agreements with direct-to-consumer clinical brands consolidating procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wearable technology components hinges on edge AI silicon premiumization and clinical certification depth, with sub-milliwatt process node transitions enabling cost-down trajectories alongside FDA 510(k) cleared premium tiers.
For Market Incumbents: Hedge against MEMS foundry concentration by securing multi-year capacity commitments at Taiwanese analog IC facilities. Deepen backward integration into ultra-low-power process nodes to defend against Qualcomm's Snapdragon Wear platform dominance. Prioritize EU MDR notified body relationships to compress certification throughput timelines. For New Entrants and Emerging Players: Hospital systems in India and Southeast Asia represent underserved buyer archetypes seeking continuous monitoring patches at price points below German and Japanese procurement thresholds. Target domestic telehealth platforms in Karnataka and Maharashtra through white-label sensor module partnerships. Pursue PLI scheme assembly incentives to serve export markets from Indian manufacturing bases. For Investors and Strategic Acquirers: Medical device conglomerates are the most active acquirer in this space, consolidating analog front-end specialists to capture remote patient monitoring growth. Long-term viability centers on clinical validation depth and edge AI inference capability. Target acquisition archetypes include ISO 10993-certified adhesive suppliers and FDA-cleared algorithm developers. Watch FDA software-as-medical-device guidance divergence from EU MDR implementing acts as inflection indicator for fragmented certification cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Development | On-device neural processing for arrhythmia classification eliminates cloud latency for clinical alerts. |
| EU MDR Certification Investment | Notified body capacity constraints create first-mover advantage for biocompatibility documentation depth. |
| Backward Integration into MEMS | Captive motion sensor fabrication reduces supply vulnerability for fitness tracker volume commitments. |
| Hospital System Partnership | Epic and Cerner EHR interoperability unlocks procurement workflows for clinical-grade wearable deployment. |
| Direct-to-Consumer Channel Launch | Bypassing distributor networks concentrates margin capture with vertically integrated hardware startups. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with semiconductor foundry executives, wearable OEM procurement leads, FDA regulatory consultants, and hospital biomedical engineers with secondary validation against SEC 10-K filings, FDA 510(k) clearance databases, EU MDR notified body registers, and customs trade data. Bottom-up sensor module shipment analysis and top-down healthcare expenditure allocation triangulated market sizing across the analysis window.
Segment-weighting applied product type, connectivity protocol, application vertical, and end-user archetype dimensions across the projection horizon. CAGRs derived from fitted growth curves calibrated against foundry capacity expansion announcements and clinical validation pipeline density. Forecast inputs incorporated MEMS fabrication yield trends and lithium-polymer energy density improvement trajectories.
Underlying measurement precision varies by segment; smartwatch component volumes carry tighter precision than emerging wearable medical device categories given disclosure granularity. Forecasts reflect documented assumptions around regulatory timeline convergence and foundry capacity allocation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Fixed Capacitor Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Dual Relay Board Market
Electronic Components
Chip Shield Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Flex-Rigid PCB Market