
 Trackpad Market | 2026-2036
Trackpad Market Size, Share, and Industry Trends Forecast 2026-2036
Trackpad Market Analytics
REACH compliance is shifting the cost-of-entry calculus for European-bound trackpad suppliers. Cherry GmbH leverages in-house switch manufacturing to control material traceability across its supply chain. Advantech Co., Ltd. anchors its industrial trackpad portfolio with extended-temperature specifications for embedded computing deployments. Elo Touch Solutions, Inc. specializes in projected capacitive modules for kiosk and point-of-sale terminals, competing on touch latency metrics rather than unit cost.
A trackpad is a capacitive or resistive planar input device that translates finger position and gesture data into cursor control signals, typically specified by surface dimensions, contact-point resolution, and force-sensing range. Its primary commercial purpose is to provide pointer manipulation in space-constrained computing environments where external mice prove impractical. Capacitive technology dominates volume shipments due to lower power draw and multi-touch gesture support, while force-touch architectures capture premium margin pools in professional workstation segments. Consumer electronics end-use channels exhibit the steepest volume growth, though gaming device applications command higher per-unit pricing through low-latency controller integration.
FCC electromagnetic emissions standards govern wireless trackpad certification for US market access, while EU RoHS and REACH frameworks restrict hazardous substance content in flexible printed circuit substrates. China's GB standards for information technology equipment mandate specific electrostatic discharge immunity levels for touch input devices sold domestically. Stakeholders must monitor evolving repairability mandates across Brussels and Beijing, as right-to-repair provisions threaten integrated form-factor designs that preclude component-level replacement.
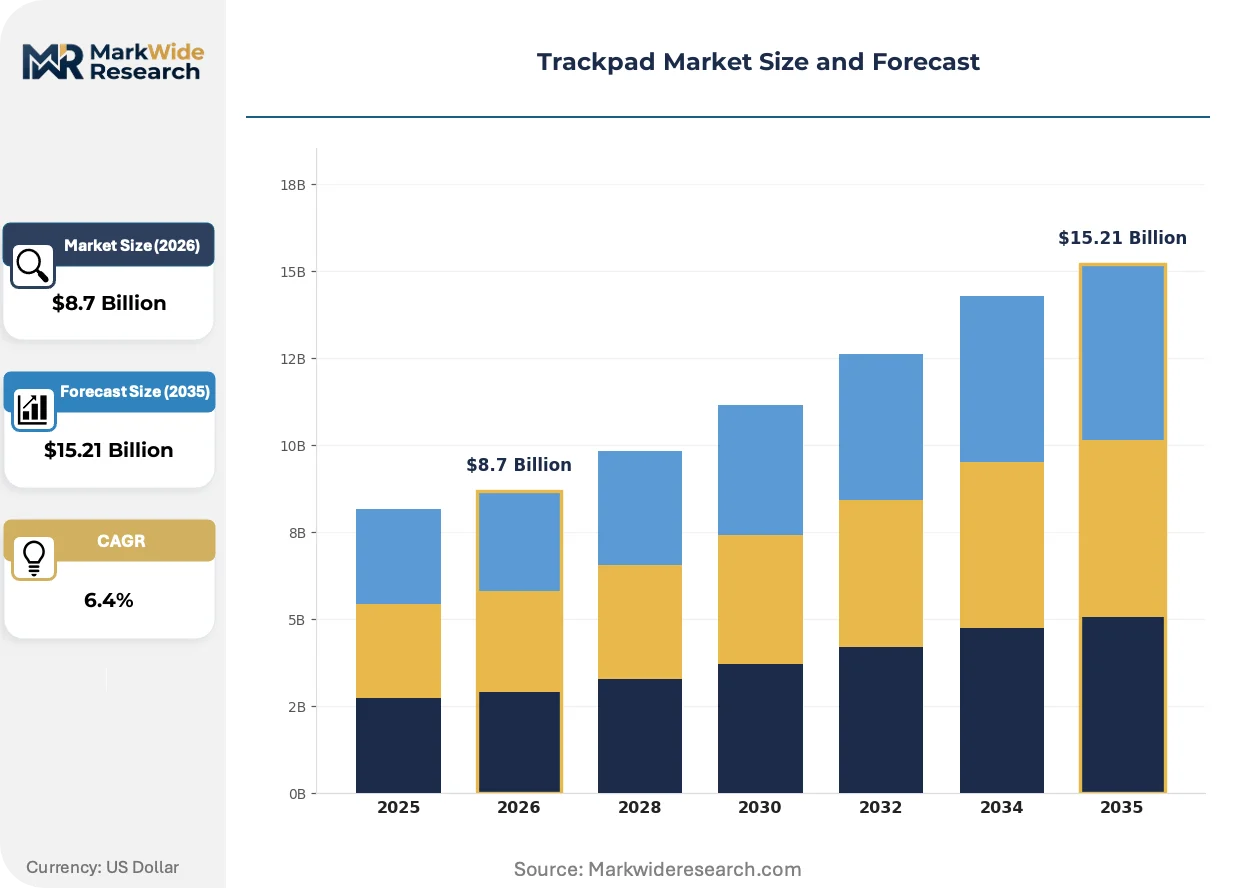
Market Dynamics
Enterprise laptop refresh cycles are compressing replacement timelines while the EU's Ecodesign for Sustainable Products Regulation forces modular trackpad architectures that complicate integrated designs. This tension between procurement velocity and repairability mandates is restructuring supplier relationships.
Growth Catalysts
- Corporate fleet modernization:Enterprise procurement channels are standardizing precision touch modules across laptop deployments, expanding volume commitments from Fortune 500 technology refresh programs.
- REACH material compliance:European-bound suppliers are redesigning flexible printed circuit substrates to eliminate restricted substances, creating certified-component premiums in cross-border trade.
- Yangtze River Delta manufacturing scale:OEM integration of force-sensing architectures at China's electronics cluster is driving cost compression for multi-touch modules.
Market Restraints
- Indium tin oxide price volatility:Transparent conductor input costs fluctuate with display panel demand cycles, squeezing margins on projected capacitive trackpad production.
- Single-source controller IC concentration:Touch digitizer semiconductor supply concentrates among Taiwanese foundry customers, exposing buyers to allocation risk during foundry loading peaks.
- Integrated battery bonding:Ultrabook form-factor adhesives prevent component-level trackpad replacement, conflicting with emerging right-to-repair mandates in Brussels and Beijing.
Strategic Opportunities
- Industrial embedded computing:Extended-temperature trackpad specifications for outdoor kiosks and fleet management terminals remain underpenetrated relative to consumer volumes.
- Gaming peripheral integration:Low-latency haptic feedback modules command pricing premiums through controller ecosystem partnerships with esports hardware vendors.
- EU repairability scoring:Ecodesign modularity requirements create first-mover advantage for suppliers offering tool-free replacement subassemblies with published disassembly instructions.
Industry Challenges
- Force-sensing calibration expertise:Capacitive strain-gauge integration requires specialized firmware talent scarce outside Apple and Synaptics legacy engineering pools.
- Multi-regulatory certification timelines:Simultaneous FCC Part 15, CE marking, and China GB standard testing extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trackpad Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchpads, Force Touch, Surface Acoustic Wave, Multi-Touch Technology: Capacitive, Resistive, Optical, Infrared End User: Consumer Electronics, Laptops, Gaming Devices, Smart Home Form Factor: Integrated, External, Miniature, Wireless |
| Companies Covered | iKey, Inc., AAEO Technology Inc., Advantech Co., Ltd., PrehKeyTec GmbH, EAO AG, Winmate Inc., Elo Touch Solutions, Inc., Cherry GmbH, Genovation, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trackpad Market Evolving Landscape
Trackpad technology is bifurcating between commodity capacitive modules and premium force-touch architectures, with regulatory pressure on repairability forcing design compromises that favor mechanical modularity over seamless integration.
Force-sensing resistor arrays with strain-gauge interpolation are absorbing gesture complexity previously handled by software algorithms alone. Gaming workstation OEMs are adopting these architectures fastest, compressing the latency gap between touch input and system response that once justified external mouse peripherals. The technology is absorbing premium-margin positioning from traditional capacitive dominance.
The EU Ecodesign for Sustainable Products Regulation is mandating modular component separation with published repair instructions by 2026. Manufacturers must redesign bonded assemblies into screw-retained submodules, increasing bill-of-materials count but preserving market access. Professional laptop segments face the steepest compliance cost given their thin-form-factor constraints.
Enterprise buyers are consolidating vendor relationships through managed procurement platforms that bundle trackpad modules with keyboard and display assemblies. Direct OEM sales teams are losing access to discrete component decisions as channel purchasing shifts to systems integrators with frame-contract authority. This concentration is most visible in North American Fortune 500 technology refresh programs.
Trackpad Market Segmentation
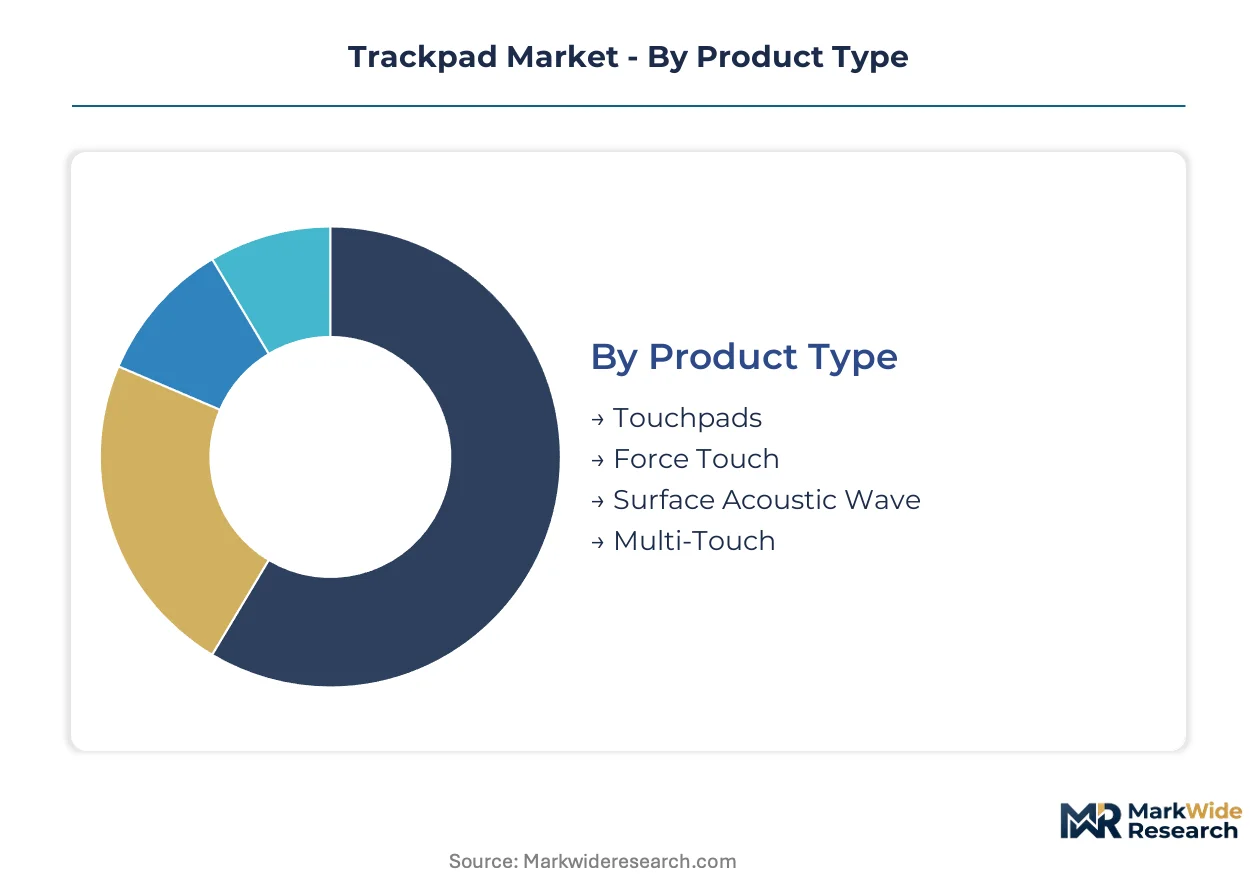
Trackpad procurement decisions hinge on interface responsiveness, power budgets, and repairability mandates that vary sharply across device categories. Segmentation reveals where force-sensing architectures command premium positioning versus commoditized capacitive volumes.
Product Type:
Enterprise buyers prioritize gesture latency and haptic fidelity over unit cost when specifying precision input modules for fleet deployments.
- Touchpads:Standard capacitive planar sensors with multi-finger gesture recognition dominate laptop OEM specifications. Corporate refresh programs in the United States and Germany are consolidating procurement around this architecture for its balance of power efficiency and software compatibility.
- Force Touch:Strain-gauge arrays measuring applied pressure enable pressure-sensitive input and eliminate mechanical click mechanisms. Apple's MacBook line established this specification; professional workstation OEMs in Japan and South Korea now mandate force-sensing for premium product tiers.
- Surface Acoustic Wave:Piezoelectric transducers detect touch via ultrasonic wave absorption, offering durability in high-traffic kiosk environments. Transit authorities in Singapore deploy SAW modules for ticket vending terminals.
- Multi-Touch:Expanded contact-point tracking supports complex gesture vocabularies for creative software workflows. Adobe Creative Cloud certification programs are driving adoption among content production houses in California and London.
Touchpads lead on scale; Force Touch leads on momentum.
Technology:
Controller IC availability and indium tin oxide supply contracts determine which sensing modality OEMs can source at volume.
- Capacitive:Electrostatic field disruption detection enables sub-millimeter resolution with minimal power draw. The Yangtze River Delta manufacturing cluster produces capacitive modules at cost structures that undercut alternative technologies by substantial margins.
- Resistive:Pressure-activated conductive layers function with gloved or stylus input, suiting industrial and medical environments. German automotive suppliers specify resistive trackpads for factory floor Human Machine Interface panels where ESD immunity is critical.
- Optical:Image sensors track finger position through transparent surfaces, enabling unconventional form factors. Gaming peripheral vendors in Taiwan integrate optical tracking for ultra-low-latency esports controllers.
- Infrared:LED arrays and photodetectors create touch-sensitive grids without conductive coatings. Outdoor digital signage deployments in Dubai and Riyadh favor IR for temperature tolerance and sunlight readability.
Capacitive commands volume leadership; optical architectures are climbing fastest in gaming specialization.
End User:
Device category dictates surface area requirements, environmental sealing, and integration depth with host system firmware.
- Consumer Electronics:Smartphones and tablets incorporate compact trackpad modules for accessory keyboard docks. Chinese OEMs integrate these at sub-$5 bill-of-materials targets for emerging market price tiers.
- Laptops:Precision touchpad certification from Microsoft and Apple defines the specification baseline for Windows and macOS ecosystems. Fortune 500 technology refresh programs in North America and Western Europe are consolidating vendor relationships around certified module suppliers.
- Gaming Devices:Low-latency haptic feedback and programmable gesture macros command 3-4x pricing premiums over standard laptop modules. Razer and Logitech G series specifications are forcing controller IC vendors to prioritize polling rate optimization.
- Smart Home:Wall-mounted control panels and appliance interfaces require gesture recognition in high-humidity kitchen and bathroom environments. BSH Hausgeräte and Whirlpool are qualifying capacitive modules with conformal coating for appliance integration.
Laptops anchor volume commitments; gaming devices generate the steepest margin expansion.
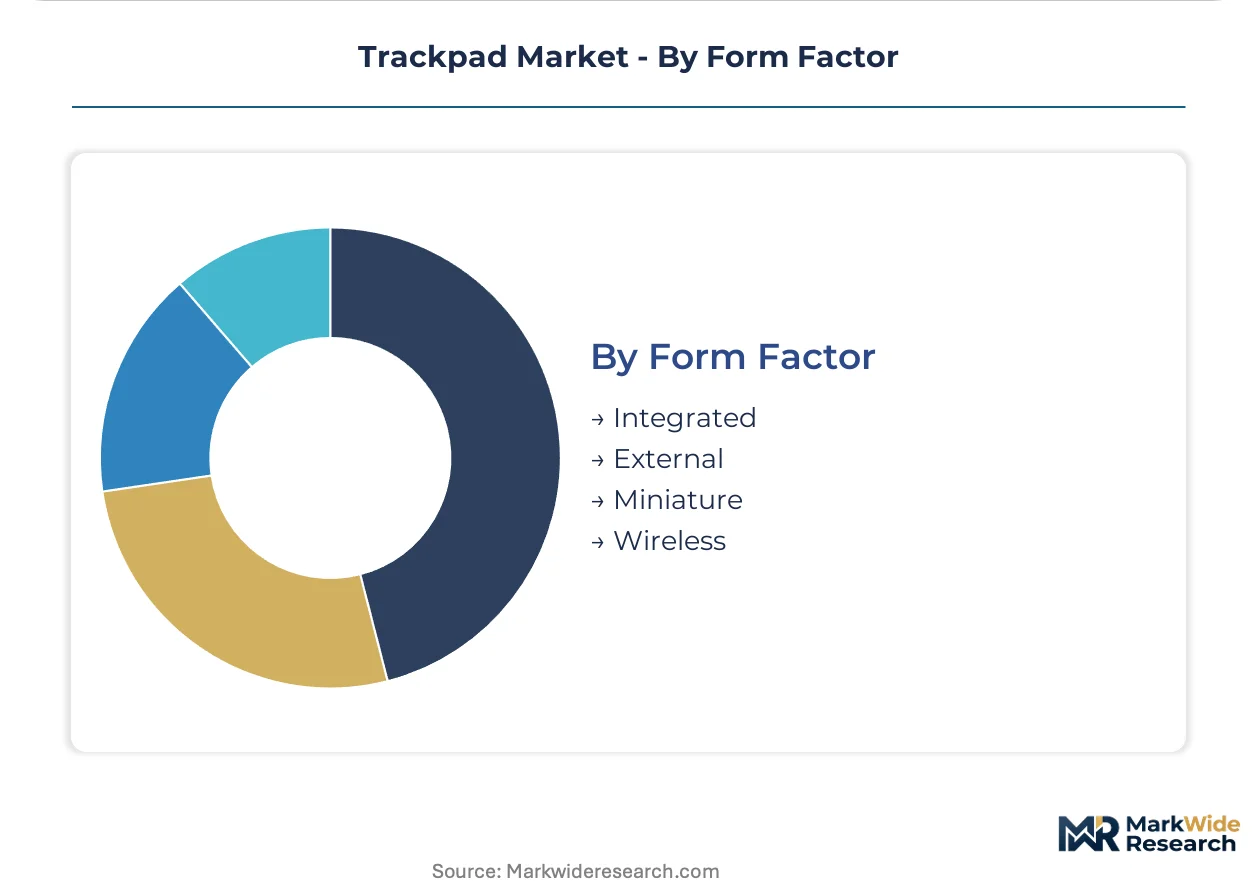
Form Factor:
Physical integration method determines repairability compliance under EU Ecodesign mandates and influences end-user replacement economics.
- Integrated:Bonded subassemblies within laptop palm rests require complete top-case replacement upon failure. Brussels repairability scoring is pressuring redesign toward screw-retained modules with published disassembly instructions.
- External:USB or Bluetooth-connected peripherals serve desktop replacement and accessibility use cases. Microsoft's Adaptive Accessories program is expanding addressable market for external trackpad formats.
- Miniature:Sub-50mm surface dimensions enable wearable and handheld device applications. VR controller manufacturers in San Francisco and Shenzhen are sourcing miniature modules for thumb-operated input.
- Wireless:Battery-powered units with proprietary 2.4GHz or BLE protocols eliminate cable clutter for presentation and living room scenarios. Logitech's MX Master ecosystem has established wireless trackpad expectations for creative professionals.
Integrated configurations dominate shipment volumes; external formats are gaining share fastest among accessibility and hybrid work segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized firmware engineers cluster in Taiwan's Hsinchu Science Park and California's Silicon Valley, anchoring the force-sensing calibration expertise that differentiates premium trackpad architectures from commodity capacitive volumes.
United States
Fortune 500 technology refresh programs in North America are consolidating vendor relationships around precision touchpad certification requirements. FCC Part 15 electromagnetic emissions standards govern wireless trackpad certification for domestic market access. Microsoft's Redmond engineering campus anchors precision touch specification development for Windows ecosystem compatibility.
Germany
Enterprise procurement channels across German industrial conglomerates are standardizing modular trackpad architectures compliant with emerging repairability mandates. REACH and RoHS frameworks restrict hazardous substance content in flexible printed circuit substrates bound for European markets. Cherry GmbH's Auerbach manufacturing base leverages in-house switch production to control material traceability across supply chains.
China
OEM integration of force-sensing architectures is driving cost compression for multi-touch modules serving global laptop brands. GB standards for information technology equipment mandate specific electrostatic discharge immunity levels for touch input devices sold domestically. The Yangtze River Delta electronics manufacturing cluster produces capacitive modules at cost structures that undercut alternative technologies by substantial margins.
Japan
Professional workstation OEMs in Tokyo and Osaka now mandate force-sensing specifications for premium product tiers targeting creative software workflows. METI industrial standards influence component reliability benchmarks for enterprise laptop deployments. Kanto region engineering teams specialize in strain-gauge interpolation firmware that absorbs gesture complexity previously handled by software algorithms alone.
South Korea
Display panel manufacturers in Seoul and Suwon are vertically integrating touch module production to secure indium tin oxide supply contracts against price volatility. MFDS-equivalent semiconductor quality protocols extend to touch controller IC validation for domestic OEM qualification. Samsung and LG supply chain proximity enables rapid prototyping cycles for gaming peripheral vendors demanding low-latency haptic feedback specifications.
Trackpad Market Competitive Landscape
The competitive structure tilts toward vertically integrated component specialists with captive switch manufacturing and firmware development capabilities. Tier-one suppliers concentrate among Taiwanese foundry customers and German precision electromechanical fabricators. Two strategic archetypes dominate: modular subassembly vendors compliant with EU Ecodesign repairability mandates, and integrated solution providers bundling trackpad modules with keyboard and display assemblies. Capacity expansion and strategic partnerships represent the dominant competitive moves as enterprise procurement platforms consolidate vendor relationships.
Among German-based fabricators, Cherry GmbH and PrehKeyTec GmbH exemplify the modular-architecture archetype with in-house material traceability systems. Advantech Co., Ltd. occupies a position within the industrial-embedded computing tier, anchoring extended-temperature specifications for outdoor kiosk and fleet management terminal deployments. Elo Touch Solutions, Inc. represents the projected-capacitive specialization vector, competing on touch latency metrics for point-of-sale terminal applications rather than unit cost positioning.
| Leading Market Players |
|---|
| iKey, Inc. |
| AAEO Technology Inc. |
| Advantech Co., Ltd. |
| PrehKeyTec GmbH |
| EAO AG |
| Winmate Inc. |
| Elo Touch Solutions, Inc. |
| Cherry GmbH |
| Genovation, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Germany's precision electromechanical belt anchor pricing discipline through captive switch manufacturing, while Taiwanese foundry-dependent controller IC vendors absorb allocation risk that compresses margin buffers across projected capacitive module tiers.
Pricing Analysis
Bundled procurement through enterprise systems integrators commands modest premiums over discrete component sourcing, though Fortune 500 frame contracts increasingly strip out after-sales service bundles to hit cost targets. Pricing stratifies across premium force-sensing architectures, standard precision touch modules, and economy capacitive volumes, with force-touch tiers absorbing margin expansion from gaming peripheral vendors while economy tiers face cost compression from Yangtze River Delta manufacturing scale. Pricing pressure stems from indium tin oxide input volatility tied to display panel demand cycles. Gaming device OEMs exhibit lowest price sensitivity due to latency-performance tradeoffs, while Chinese smartphone accessory dock manufacturers operate at highest sensitivity with sub-$5 bill-of-materials targets.
Supply Chain Analysis
Reverse-logistics flows for modular trackpad subassemblies are accelerating as EU Ecodesign mandates require tool-free replacement protocols and published disassembly instructions, creating refurbishment revenue streams for certified component suppliers. Manufacturing gravity centers on China, Taiwan, and Germany, with the Yangtze River Delta producing capacitive modules at cost structures that undercut alternatives, Hsinchu Science Park anchoring controller IC design, and German fabricators controlling material traceability for REACH-bound shipments. Supply chains draw from indium tin oxide coatings, flexible printed circuit substrates, and strain-gauge sensor arrays. Single-source vulnerability concentrates among Taiwanese foundry customers for touch digitizer semiconductors. Distribution runs through direct OEM sales teams losing ground to systems integrators with frame-contract authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trackpad market reads as a late-cycle quality story, with enterprise procurement channels consolidating around precision touch certification requirements that favor incumbent specialists over commodity assemblers.
For Market Incumbents:Acquire force-sensing calibration firmware engineering pools to secure talent scarce outside Apple and Synaptics legacy teams. Backward integration into indium tin oxide supply contracts mitigates transparent conductor price volatility that squeezes projected capacitive margins. Capacity addition in Germany's Auerbach manufacturing cluster preserves REACH-compliant market access against regulatory fragmentation.
For New Entrants and Emerging Players:Direct-to-industrial channels bypassing systems integrator gatekeepers offer white-space access for extended-temperature trackpad specifications in outdoor kiosk and fleet management terminal deployments. Gaming peripheral integration presents the most penetrable premium tier, with low-latency haptic feedback modules commanding 3-4x pricing premiums through esports hardware vendor partnerships. Qualify modules through Adobe Creative Cloud certification programs to access content production house procurement channels in California and London.
For Investors and Strategic Acquirers:Valuations sit cheapest among modular subassembly vendors with published repair instructions and tool-free replacement protocols compliant with EU Ecodesign mandates. The 5-10 year viability window favors suppliers with in-house material traceability systems and captive switch manufacturing capabilities. Monitor right-to-repair legislative progress in Brussels and Beijing as inflection indicator for integrated versus modular form-factor demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Force-Sensing Firmware Acquisition | Secures scarce calibration talent from Apple and Synaptics legacy engineering pools. |
| EU Repairability Certification | Preserves market access under Ecodesign modular separation mandates. |
| Gaming Peripheral Partnership | Captures 3-4x pricing premiums through Razer and Logitech G ecosystem integration. |
| Indium Tin Oxide Supply Contract | Hedges transparent conductor price volatility from display panel demand cycles. |
| Industrial Temperature Qualification | Opens outdoor kiosk and fleet terminal segments underpenetrated versus consumer volumes. |
Research Methodology
Bottom-up laptop OEM and gaming peripheral modeling reconciled against top-down controller IC and touch module production tracking forms the analytical core. Primary interviews with procurement directors at Fortune 500 technology refresh programs, touch controller firmware engineers, systems integrator category managers, and REACH compliance officers combined with secondary validation from FCC Part 15 certification databases, EU Ecodesign regulatory filings, SEC 10-K component supplier disclosures, and Yangtze River Delta customs export records. Triangulation across stakeholder inputs and trade data ensures segmentation integrity.
Input-output matrices map capacitive and force-sensing module production volumes against enterprise fleet deployment schedules and gaming hardware release cycles across the projection horizon. Segmentation dimensions include product type, sensing technology, end-use device category, and form factor integration depth. CAGRs derive from weighted average of OEM procurement pipeline visibility and foundry capacity allocation trends. Force-sensing adoption curves and repairability mandate compliance timelines constitute key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for optical sensing architectures in gaming controllers would alter the outlook. Forecasts reflect assumptions around indium tin oxide supply contract stability and Taiwanese foundry loading normalization. Practitioners should monitor EU repairability scoring implementation and right-to-repair legislative progress in Beijing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Wearable Technology Component Market
Electronic Components
China Data Converter Market
Electronic Components
Power Inductors Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Impulse Relays Market
Electronic Components
United States MLCC Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Global Capacitor Market
Electronic Components
2D Electronics Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Data Acquisition Card Market
Electronic Components
US Supercapacitor Market
Electronic Components
USB Charger Market