
 Global Microfluidic Components Market | 2026-2036
Global Microfluidic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microfluidic Components Market Foresight
OEM-direct procurement channels for microfluidic subassemblies is rewriting how diagnostic instrument builders source precision components. Parker Hannifin Corporation leverages its motion and control portfolio to dominate high-pressure microvalve supply for analytical instrumentation. SMC Corporation anchors Asia-Pacific manufacturing scale through its pneumatic expertise adapted for miniature fluidic circuits. The Lee Company specializes in chemically inert miniature solenoid valves that sustain premium positioning in life science applications.
Microfluidic components are precision-engineered fluidic elements—typically fabricated in polymers, glass, or silicon with channel dimensions from tens to hundreds of micrometers—designed to manipulate minute liquid volumes for controlled reactions, separations, or detections. Photolithography, soft lithography, and precision micromilling are primary fabrication routes, with surface treatment protocols determining wettability and biocompatibility performance. Micropumps and microvalves command the largest product type share due to their irreplaceable role in dosing accuracy and flow regulation across diagnostic platforms. Pressure-driven technology leads installed base volumes, though electrokinetic methods are gaining fastest in DNA analysis workflows where precise ionic transport eliminates mechanical wear. DNA analysis and drug delivery applications concentrate the highest margin pools as pharmaceutical developers and diagnostic laboratories prioritize regulatory-compliant, single-use fluidic paths.
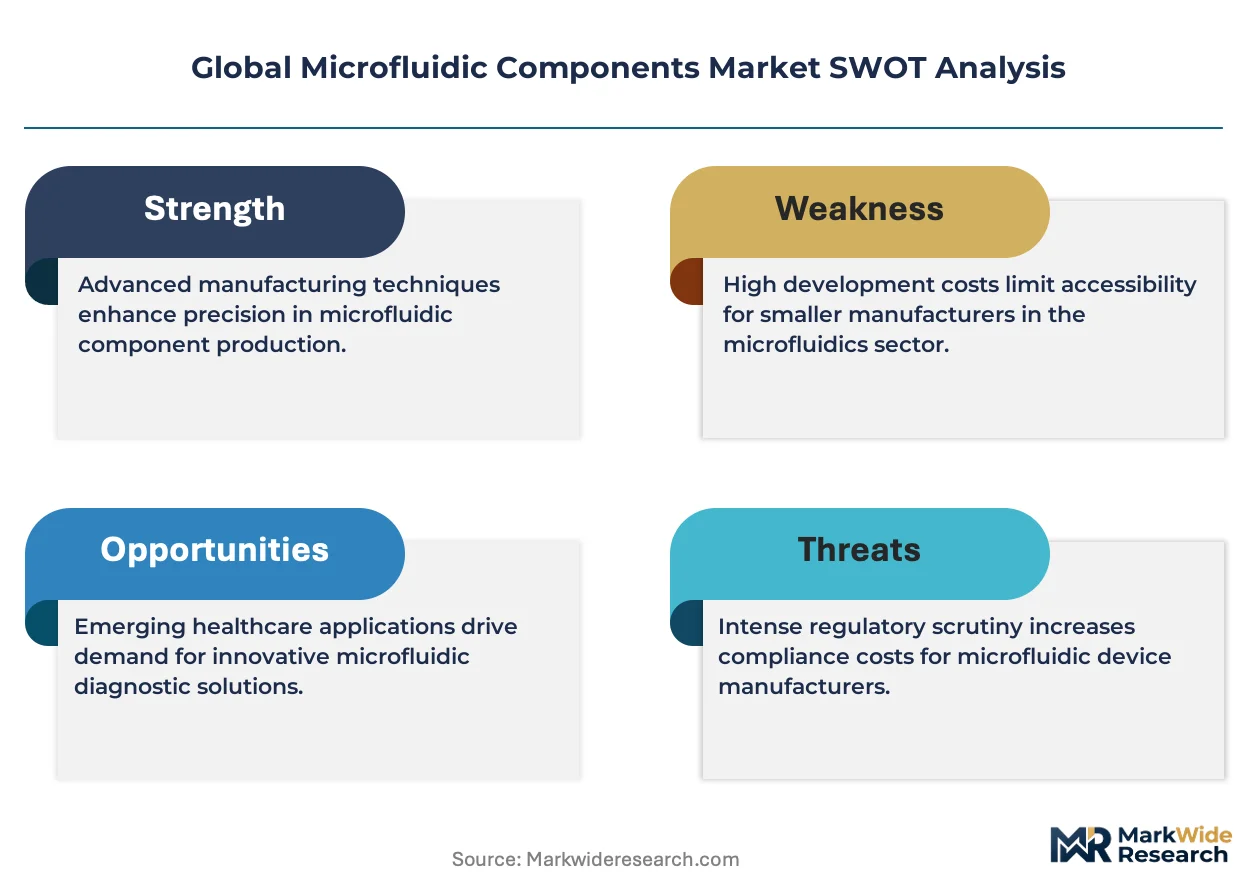
FDA's 21 CFR Part 820 quality system requirements and the EU MDR's reinforced biocompatibility standards shape product development timelines and validation costs for manufacturers targeting clinical diagnostics. ISO 13485 certification has become a baseline market access condition, with notified body scrutiny intensifying for devices incorporating patient-contacting polymeric microchannels. China's NMPA alignment with international harmonization pathways is accelerating local registration complexity for Western suppliers. Stakeholders must monitor evolving polymer qualification standards and regional divergence in single-use device sustainability mandates to preserve commercial positioning across fragmented regulatory landscapes.
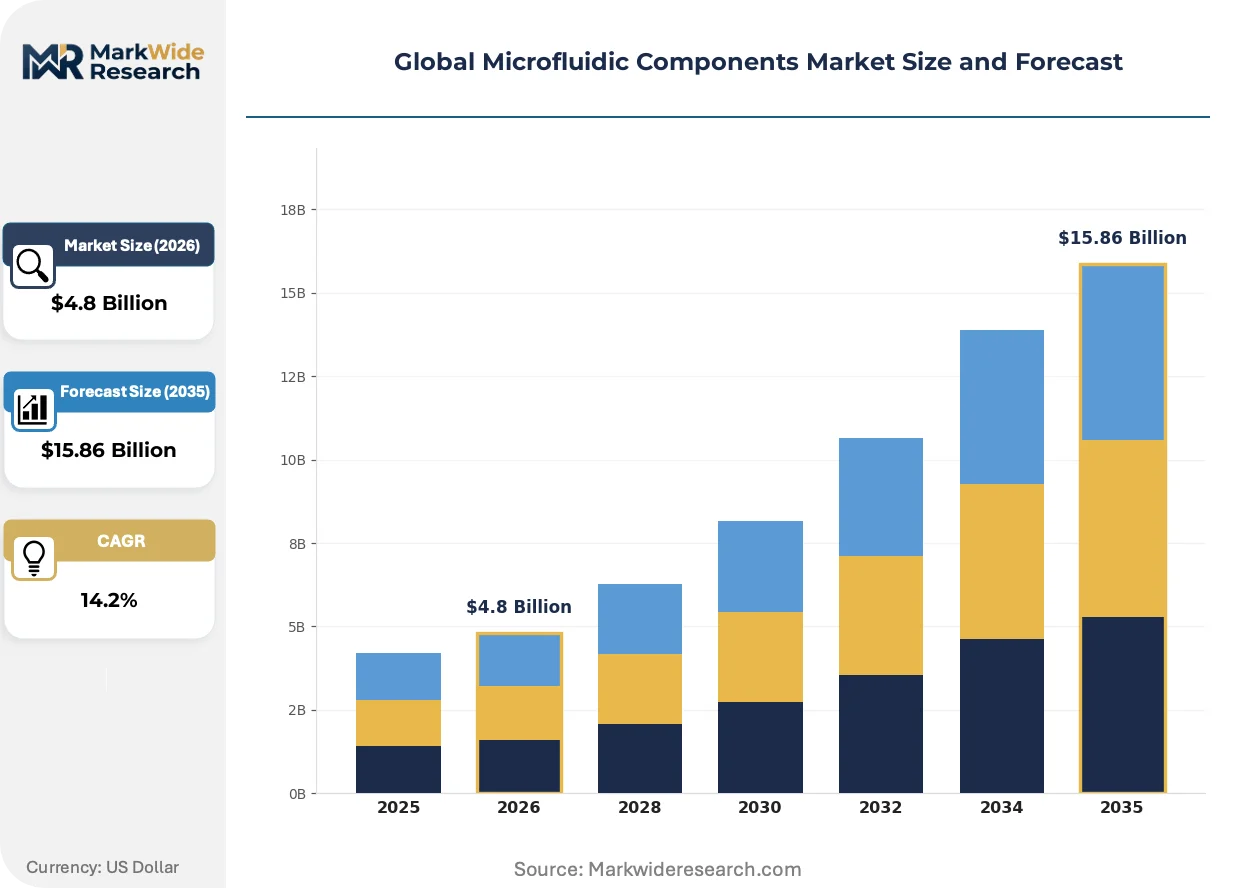
Market Dynamics
Point-of-care diagnostic laboratories are consolidating purchasing power around precision flow control systems, compressing supplier margins while elevating technical qualification barriers for component vendors seeking instrument builder partnerships.
Growth Catalysts
- EU MDR biocompatibility mandates:Patient-contacting polymeric microchannels now require extensive material qualification, creating replacement demand for legacy devices that fail enhanced testing protocols.
- Stuttgart-Freiburg manufacturing corridor concentration:Germany's precision engineering cluster anchors European supply for high-tolerance microvalve production, drawing adjacent R&D investment from diagnostic OEMs.
- Electrokinetic transport methods:DNA analysis workflows are adopting ionic-driven flow control to eliminate mechanical wear in high-throughput sequencing instruments.
Market Restraints
- Specialized polymer feedstock volatility:Perfluorinated materials for chemically inert channels face supply concentration among Japanese and German chemical suppliers.
- FDA 21 CFR Part 820 validation costs:Quality system documentation requirements extend product development timelines by 18-24 months for clinical diagnostic applications.
- Glass microfabrication scale limits:Photolithography throughput constraints cap volume economics for disposable microfluidic cartridges in mass-market diagnostics.
Strategic Opportunities
- India's CDSCO harmonization pathway:Regulatory alignment with international standards is opening registration channels for Western suppliers of single-use diagnostic consumables.
- Soft lithography-3D printing convergence:Rapid prototyping capabilities are collapsing design iteration cycles for custom microchannel geometries in research applications.
- Direct OEM-subassembly procurement:Instrument builders are bypassing distribution layers to source integrated fluidic modules, reshaping channel economics for precision component vendors.
Industry Challenges
- ISO 13485 auditor capacity constraints:Notified body backlogs are delaying certification timelines for patient-contacting microfluidic devices.
- Cross-disciplinary engineering talent scarcity:Microfluidic design requires simultaneous fluency in fluid mechanics, surface chemistry, and biocompatibility protocols.
- Legacy instrument integration complexity:New microvalve architectures must maintain electrical and mechanical compatibility with installed base diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microfluidic Components Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microchannels, Micropumps, Microvalves, Micromixers, Microreactors Technology: Capillary, Electrokinetic, Pressure-driven, Acoustic, Magnetic Application: Drug Delivery, Environmental Monitoring, Food Safety, Chemical Synthesis, DNA Analysis End User: Biotechnology Firms, Research Institutes, Diagnostic Laboratories, Pharmaceutical Developers |
| Companies Covered | Parker Hannifin Corporation, SMC Corporation, The Lee Company, Fluigent, IDEX Corporation, Dolomite Microfluidics, Elveflow, Staiger, Camozzi Automation Spa Societä Unipersonale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microfluidic Components Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product lifecycles while fragmenting competitive advantage across specialized fabrication competencies.
Organ-on-chip platforms utilizing living cell cultures in microengineered environments are rendering obsolete static well-plate assays for preclinical drug toxicity screening. Pharmaceutical developers in Basel and Boston are adopting these systems at pilot scale. The shift is rendering obsolete conventional animal model dependencies for early-stage compound evaluation.
China's NMPA alignment with international harmonization pathways is accelerating local registration complexity for Western suppliers. Domestic manufacturers gain accelerated approval timelines while foreign entrants face extended documentation requirements. Single-use diagnostic consumables face the steepest compliance burden as biocompatibility testing protocols converge with EU MDR standards.
Diagnostic instrument builders are unbundling after-sales service contracts from hardware procurement, forcing component suppliers to assume remote monitoring and predictive maintenance obligations. Fluidic subsystem vendors in California and Massachusetts are restructuring pricing to capture recurring revenue streams. This reconfiguration is most visible in high-throughput sequencing installations where uptime guarantees determine competitive selection.
Global Microfluidic Components Market Segmentation
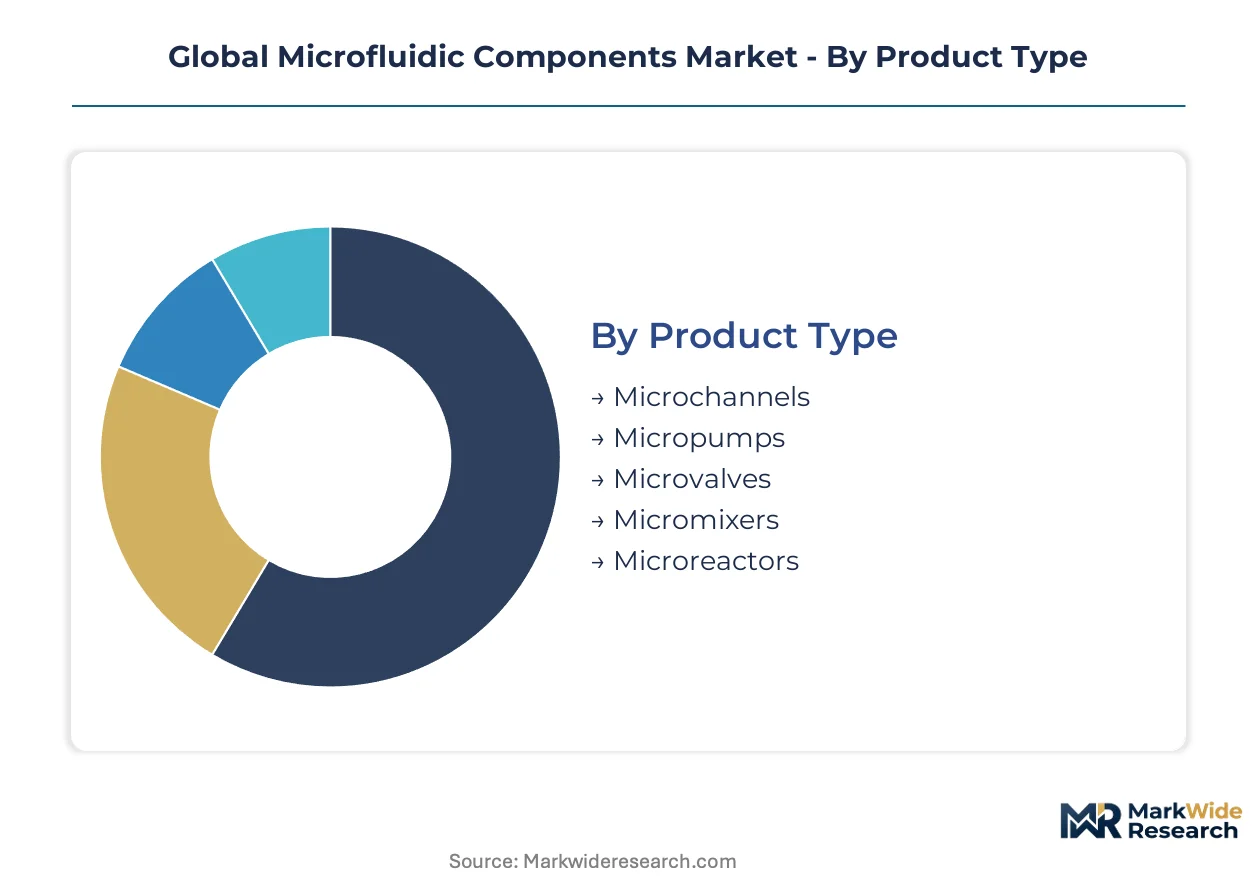
Microfluidic component suppliers face divergent service intensity demands across product architectures. Technical complexity and regulatory exposure vary sharply by segment, reshaping how vendors structure lifecycle support contracts and predictive maintenance offerings.
Product Type:
After-sales service intensity escalates dramatically for components handling patient-contacting fluids, where calibration drift and biocompatibility degradation trigger replacement protocols.
- Microchannels:Polymer-based microchannels with surface-modified wettability profiles dominate disposable diagnostic cartridges. Diagnostic laboratories in Germany's Stuttgart-Freiburg corridor prioritize single-use channels to eliminate cross-contamination risks in high-throughput screening workflows.
- Micropumps:Piezoelectric and pneumatic micropumps deliver nanoliter-precision dosing for drug delivery systems. Pharmaceutical developers in Basel and Boston concentrate procurement around pumps with embedded flow sensors that enable real-time performance telemetry.
- Microvalves:Solenoid-actuated microvalves regulate reagent routing in analytical instrumentation. FDA 21 CFR Part 820 compliance requirements extend validation timelines for clinical diagnostic applications.
- Micromixers:Passive chaotic advection designs achieve rapid homogenization without moving parts. Research institutes favor these for protein crystallization studies requiring minimal sample disturbance.
- Microreactors:Silicon-glass hybrid reactors enable precise thermal control for exothermic chemical synthesis. Chemical manufacturers in Japan leverage these for hazardous reaction containment.
Micropumps hold the largest share; momentum sits with microchannels.
Technology:
Cost tier stratification separates premium electrokinetic systems from commoditized pressure-driven alternatives, with acoustic and magnetic methods occupying intermediate positions.
- Pressure-driven:Pneumatic or hydraulic pressure gradients drive fluid movement through microchannel networks. This mature technology anchors installed base volumes across environmental monitoring stations in the US and EU.
- Electrokinetic:Electric field-induced ionic transport eliminates mechanical wear in DNA analysis workflows. Research institutes in Cambridge and San Diego adopt these for long-read sequencing applications where pump degradation compromises read accuracy.
- Capillary:Surface tension and wettability gradients enable passive fluid propulsion without external power. Point-of-care diagnostic developers favor capillary systems for battery-independent operation in resource-limited settings.
- Acoustic:Surface acoustic waves manipulate droplets and cells through piezoelectric substrate excitation. Biotechnology firms integrate these for contact-free cell sorting in organ-on-chip platforms.
- Magnetic:Ferrofluid or bead-based transport enables programmable fluid routing using external field patterns. Pharmaceutical developers employ magnetic methods for targeted drug encapsulation processes.
Pressure-driven technology commands the greatest installed base; electrokinetic methods are climbing the fastest.
Application:
Application-level margin pools concentrate where regulatory compliance costs create barriers to entry, particularly in patient-contacting therapeutic delivery systems.
- DNA Analysis:Microfluidic integration enables sample preparation, amplification, and detection within sealed cartridges. Diagnostic laboratories prioritize FDA-cleared and EU MDR-compliant systems for clinical genomics workflows.
- Drug Delivery:Implantable and wearable microfluidic pumps enable programmable therapeutic administration. Pharmaceutical developers in Switzerland and Massachusetts concentrate investment around closed-loop systems with glucose-responsive insulin dosing.
- Chemical Synthesis:Continuous-flow microreactors improve heat and mass transfer for fine chemical production. German chemical manufacturers adopt these for hazardous nitration reactions requiring precise temperature control.
- Environmental Monitoring:Portable microfluidic sensors detect heavy metals and pathogens in water samples. China's MEE standards drive demand for field-deployable units with automated calibration routines.
- Food Safety:Pathogen detection cartridges integrate sample lysis and nucleic acid amplification. EU EFSA guidelines shape validation requirements for commercial testing laboratories.
Drug Delivery holds the largest share; DNA Analysis is gaining share fastest.
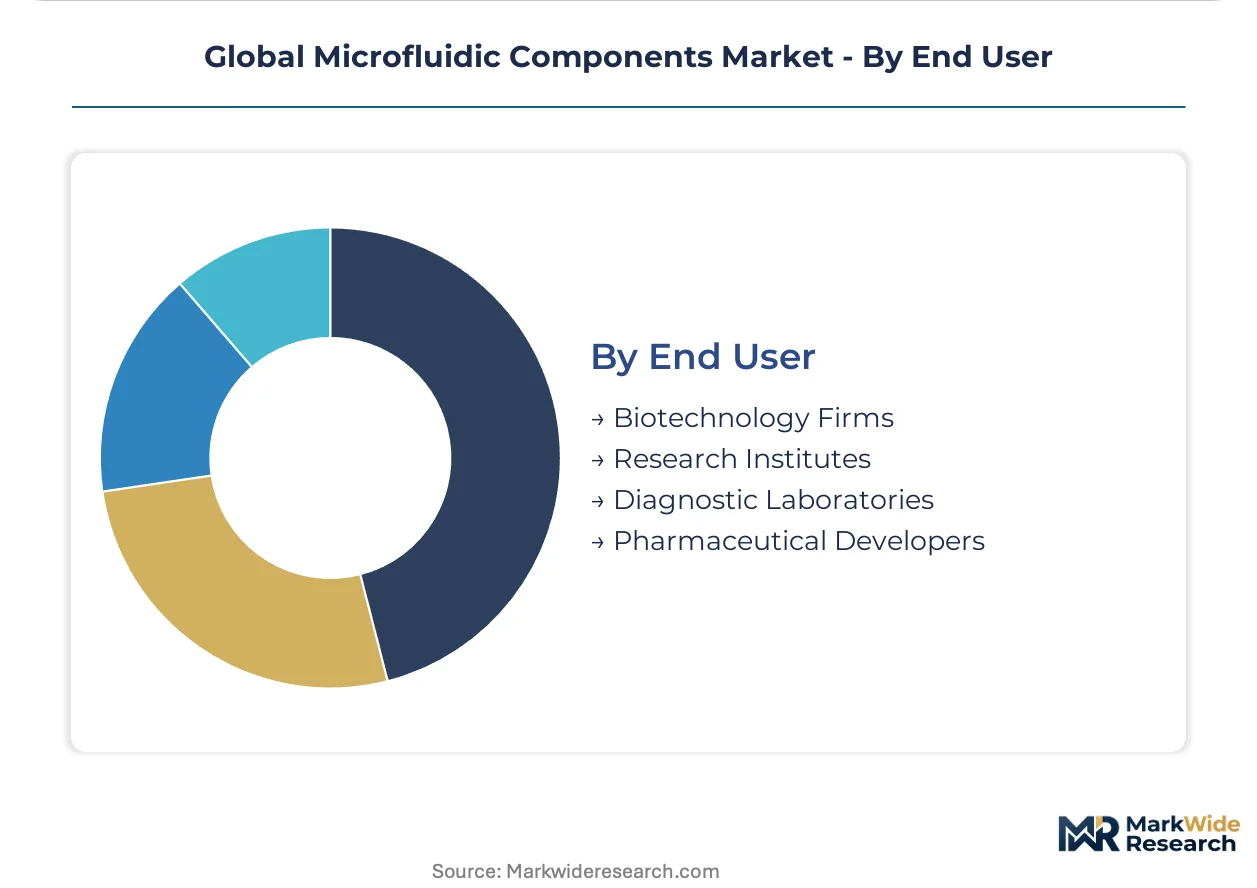
End User:
Customer type determines procurement sophistication, with biotechnology firms and pharmaceutical developers demanding integrated subsystem sourcing while research institutes prioritize configurability.
- Pharmaceutical Developers:Integrated drug discovery platforms require microfluidic modules with validated fluidic paths and comprehensive documentation packages. EU MDR and FDA dual-track submissions dominate procurement criteria for clinical-stage programs.
- Diagnostic Laboratories:High-throughput operations prioritize uptime guarantees and remote monitoring capabilities. Instrument builders unbundle service contracts, forcing component suppliers to assume predictive maintenance obligations.
- Biotechnology Firms:Cell therapy and gene editing workflows demand sterile, single-use fluidic assemblies. CDSCO harmonization in India is opening registration channels for Western consumable suppliers.
- Research Institutes:Academic laboratories favor modular, reconfigurable platforms supporting rapid protocol iteration. Soft lithography prototyping capabilities enable custom microchannel geometries without fabrication outsourcing.
Pharmaceutical Developers hold the largest share; momentum sits with Diagnostic Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for precision-manufactured microvalves while Chinese suppliers compete on volume for standard fluidic subassemblies. This asymmetry concentrates high-margin procurement decisions in Stuttgart and Freiburg while driving cost engineering toward Shanghai and Shenzhen.
United States
Diagnostic instrument builders in Greater Boston and San Diego drive demand for FDA-validated single-use fluidic cartridges. FDA's 21 CFR Part 820 quality system requirements extend product development timelines for clinical applications. California's Bay Area anchors venture-backed organ-on-chip startups transitioning from research to commercial scale.
Germany
Precision engineering clusters around Stuttgart and Freiburg supply high-tolerance microvalves for analytical instrumentation. EU MDR biocompatibility mandates for patient-contacting polymeric microchannels create replacement demand for legacy devices. Baden-Württemberg's manufacturing corridor draws adjacent R&D investment from Swiss and domestic diagnostic OEMs.
China
Domestic diagnostic consumable manufacturers scale production of disposable microfluidic cartridges for infectious disease testing. NMPA alignment with international harmonization pathways accelerates local registration complexity for Western suppliers. Yangtze River Delta contract manufacturers absorb volume production of standard polymer microchannels.
Japan
Specialized chemical suppliers concentrate perfluorinated feedstock production for chemically inert microfluidic channels. METI-supported precision manufacturing programs sustain domestic microfabrication capabilities. Tokyo-Osaka industrial corridor houses integrated suppliers serving semiconductor and life science equipment builders.
Switzerland
Pharmaceutical developers in Basel pilot closed-loop drug delivery systems with glucose-responsive insulin dosing. Swissmedic's medical device regulations align with EU MDR standards, streamlining dual-track submissions. Lake Geneva region anchors precision fluidic engineering talent pools serving adjacent pharmaceutical R&D.
Global Microfluidic Components Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying validated subassemblies to instrument builders. The vendor base organizes around three archetypes: diversified motion-and-control conglomerates with fluidic divisions, pneumatic specialists adapting miniature circuits for life science, and focused miniature valve engineers sustaining premium positioning through material expertise. Consolidation pressures favor acquisition of soft lithography capabilities by established precision manufacturers, while strategic partnerships between polymer suppliers and device fabricators shorten qualification timelines for new biocompatible materials.
Among diversified industrial technology groups, Parker Hannifin Corporation anchors the high-pressure microvalve segment for analytical instrumentation. SMC Corporation exemplifies Asia-Pacific manufacturing scale through pneumatic expertise adapted for miniature fluidic circuits. The Lee Company occupies a specialist position in chemically inert miniature solenoid valves for life science applications. These three represent distinct competitive vectors: portfolio breadth, regional production scale, and material-specific premium positioning.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| SMC Corporation |
| The Lee Company |
| Fluigent |
| IDEX Corporation |
| Dolomite Microfluidics |
| Elveflow |
| Staiger |
| Camozzi Automation Spa Societä Unipersonale |
| Others |
Supply & Pricing Matrix
Single-source dependency on Japanese and German perfluorinated polymer suppliers determines both pricing tier spreads and supply chain shape for chemically inert microfluidic channels. This concentration forces buyers into long-term offtake contracts or premium spot purchases while compressing margins for standard polymer alternatives.
Pricing Analysis
Configured-to-order pricing for patient-contacting microchannels with EU MDR biocompatibility certification commands 40-60% premiums over standard catalog items. The dominant structure is tiered pricing across ISO 13485-certified premium, CE-marked standard, and uncertified economy levels. Price differentiation hinges on certification grade and customization depth for specific diagnostic instrument integrations. Pricing pressure intensifies as diagnostic laboratories consolidate purchasing power around precision flow control systems. Research institutes exhibit highest price sensitivity due to grant-funded procurement cycles, while pharmaceutical developers prioritize compliance over cost.
Supply Chain Analysis
Export-control regimes restricting advanced photolithography equipment to Chinese fabs limit domestic microfabrication scale-up for high-tolerance glass-silicon hybrid devices. Geographic supply concentration centers on Germany for precision microvalves, Japan for perfluorinated feedstocks, and China for volume polymer microchannel production. Raw material dependencies include cyclic olefin copolymers, perfluoroalkoxy alkanes, and piezoelectric ceramics. Single-source vulnerability in specialized polymer feedstocks creates procurement risk for Western manufacturers. Distribution runs through OEM-direct channels for integrated fluidic subassemblies, bypassing traditional distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against organ-on-chip platforms displacing conventional microfluidic assays in preclinical toxicology. Incumbents must navigate this technology shift while preserving installed base relationships.
For Market Incumbents: Insulate core revenue by acquiring soft lithography capabilities to serve research prototyping demand and expanding ISO 13485-certified capacity in Germany's Stuttgart-Freiburg corridor. Backward integration into polymer compounding reduces exposure to Japanese feedstock volatility. Prioritize long-term service contracts with diagnostic laboratories to lock out emerging competitors.
For New Entrants and Emerging Players: Pursue India's CDSCO-harmonized registration pathway for single-use diagnostic consumables, where Western incumbents face documentation delays. Target research institutes with modular, reconfigurable platforms supporting rapid protocol iteration. Lead with soft lithography-3D printing convergence for custom microchannel geometries without fabrication outsourcing.
For Investors and Strategic Acquirers: EU MDR's full enforcement reshapes the acquisition landscape by elevating certified device manufacturers above uncertified competitors. Five-to-ten-year viability favors specialists with validated fluidic paths and comprehensive documentation packages. Target acquisition archetypes include soft lithography-capable prototyping firms and polymer suppliers with biocompatibility qualification pipelines. Watch NMPA registration timelines for Western suppliers as inflection indicator for Chinese market access.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates EU MDR compliance timelines for patient-contacting polymeric microchannels. |
| Soft Lithography Capability Acquisition | Collapses design iteration cycles for custom microchannel geometries in research applications. |
| OEM-Direct Channel Development | Captures integrated fluidic module procurement bypassing distribution margin layers. |
| Perfluorinated Feedstock Partnership | Secures chemically inert material supply from Japanese chemical suppliers against volatility. |
| Remote Monitoring Platform Launch | Enables predictive maintenance revenue streams as instrument builders unbundle service contracts. |
Research Methodology
A standing panel of diagnostic instrument procurement directors, biomedical engineers at pharmaceutical developers, GPO contracts managers, and regulatory affairs specialists at notified bodies provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and ISO 13485 certification registries. Bottom-up component demand modeling and top-down diagnostic instrument production estimates underwent triangulation for convergence.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, technology method, application workflow, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating electrokinetic transport adoption rates in DNA analysis and EU MDR replacement demand timelines for legacy devices.
Sensitivities concentrate around NMPA harmonization pace, ISO 13485 auditor capacity constraints, and perfluorinated polymer supply disruptions. Forecasts reflect documented assumptions on regulatory enforcement timelines and technology substitution rates. Material shifts in organ-on-chip platform adoption or EU MDR biocompatibility testing protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Touchless Tubes Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Power Resistor Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Resonators Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Flexible Heater Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Capacitor Kits Market
Electronic Components
USB Wall Charger Market