
 Safety Relay Market | 2026-2036
Safety Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Relay Market Analysis
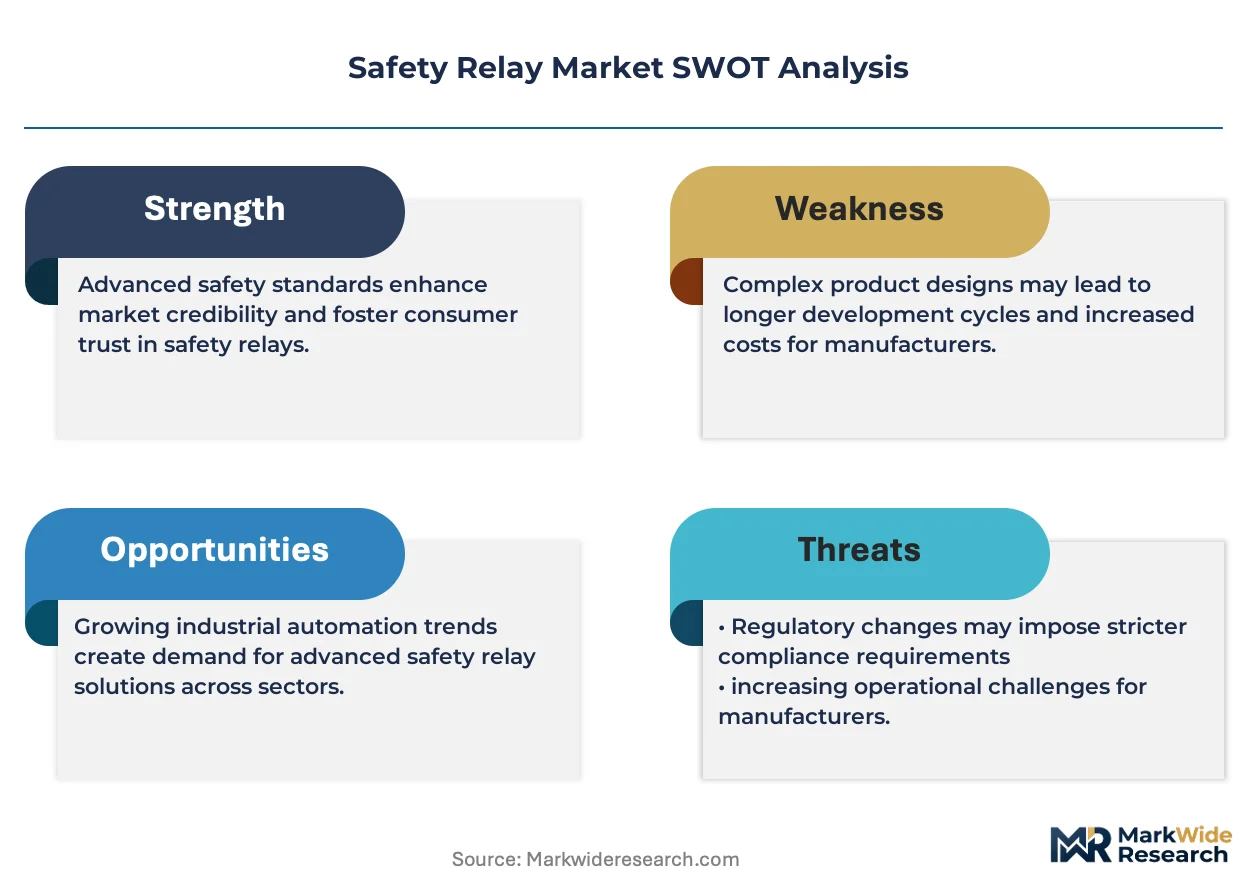
ISO 13849 certification is reorganizing competitive standing among safety relay suppliers, forcing engineering investments in redundant channel architectures and diagnostic coverage metrics. Pilz GmbH & Co. KG leverages its German engineering heritage to dominate functional safety consulting alongside hardware sales. Siemens AG anchors European market presence through deep integration with its PLC and HMI ecosystems. OMRON Industrial Automation competes aggressively in Asia-Pacific factory automation tenders with localized production and rapid certification turnaround.
A safety relay is an electromechanical or solid-state switching device engineered to monitor safety circuits and force safe states when faults occur, typically rated for SIL 3 or PLe performance levels with response times under 30 milliseconds. Its primary purpose is to protect personnel from hazardous machine motion by interrupting power to actuators when light curtains, e-stops, or interlock switches trigger. Safety monitoring relays command the highest margin pools due to integrated self-diagnostic logic that reduces external wiring complexity. Modular relay systems are gaining share in automotive body shops where line reconfiguration demands flexible I/O expansion. Wired technology still leads installed base, though embedded safety protocols in Ethernet/IP and PROFIsafe are displacing discrete wiring in new greenfield plants.
EU machinery manufacturers face dual pressure from the Machinery Regulation and CE marking requirements enforced by national market surveillance authorities in Germany and Italy. OSHA lockout/tagout standards in the United States mandate redundant safety relay channels in metalworking and plastics machinery, while China's GB standards alignment with ISO 13849 is accelerating domestic supplier qualification. FDA 21 CFR Part 820 quality system requirements indirectly shape safety relay specifications in pharmaceutical packaging equipment sold into North American markets. Stakeholders must monitor whether functional safety certification timelines become a bottleneck as automotive OEMs accelerate electric vehicle platform launches.
Market Dynamics
Solid-state relay architectures are decomposing the electromechanical installed base as automotive OEMs demand sub-30-millisecond response times in high-cycle welding robotics. This technology substitution is compressing supplier margins while forcing redundant channel engineering investments.
Growth Catalysts
- ISO 13849 machinery directive:German and Japanese automotive assembly plants are expanding safety relay procurement to meet PLe performance level mandates. Certification urgency is accelerating replacement cycles in body-in-white welding lines.
- Factory automation density:China's eastern manufacturing corridor is outpacing other regional clusters in localized automation upgrades. Dense machine-tool installations per square kilometer are multiplying safety circuit node counts.
- Ethernet/IP and PROFIsafe protocols:Embedded safety communication is displacing discrete wiring in greenfield automotive plants. Network-integrated relays are reducing external diagnostic hardware requirements.
Market Restraints
- Semiconductor input volatility:Solid-state relay production depends on power MOSFET and IGBT supply from concentrated Asian foundries. Price swings in silicon carbide substrates are compressing gross margins.
- Electromechanical legacy lock-in:Brownfield industrial facilities face high retrofit costs when replacing hardwired safety relay banks. Maintenance technician familiarity with mechanical contactors slows substitution.
- Functional safety certification friction:SIL 3 and PLe validation timelines from notified bodies in Germany and Italy are extending product launch schedules. Testing backlog creates inventory carrying cost pressure.
Strategic Opportunities
- India's PLI scheme for automation:Production-linked incentives for advanced manufacturing are attracting safety relay suppliers to establish local assembly. Domestic qualification under BIS standards offers first-mover positioning.
- Collaborative robot integration:Power-and-force limiting cobot installations require compact dual-channel safety relays with integrated speed monitoring. This application segment is expanding faster than traditional guarding.
- Pharmaceutical packaging equipment:FDA 21 CFR Part 820 quality system requirements are indirectly shaping safety relay specifications in North American markets. Validated safety systems command premium positioning.
Industry Challenges
- Functional safety engineering scarcity:Competence in redundant channel architecture design and diagnostic coverage calculation is concentrated among German and Japanese engineering teams. Talent migration is limiting expansion capacity.
- Legacy PLC integration complexity:Safety relay retrofit projects must coordinate with installed Siemens, Rockwell, and Mitsubishi controller ecosystems. Protocol translation and timing synchronization consume project engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Relay Market |
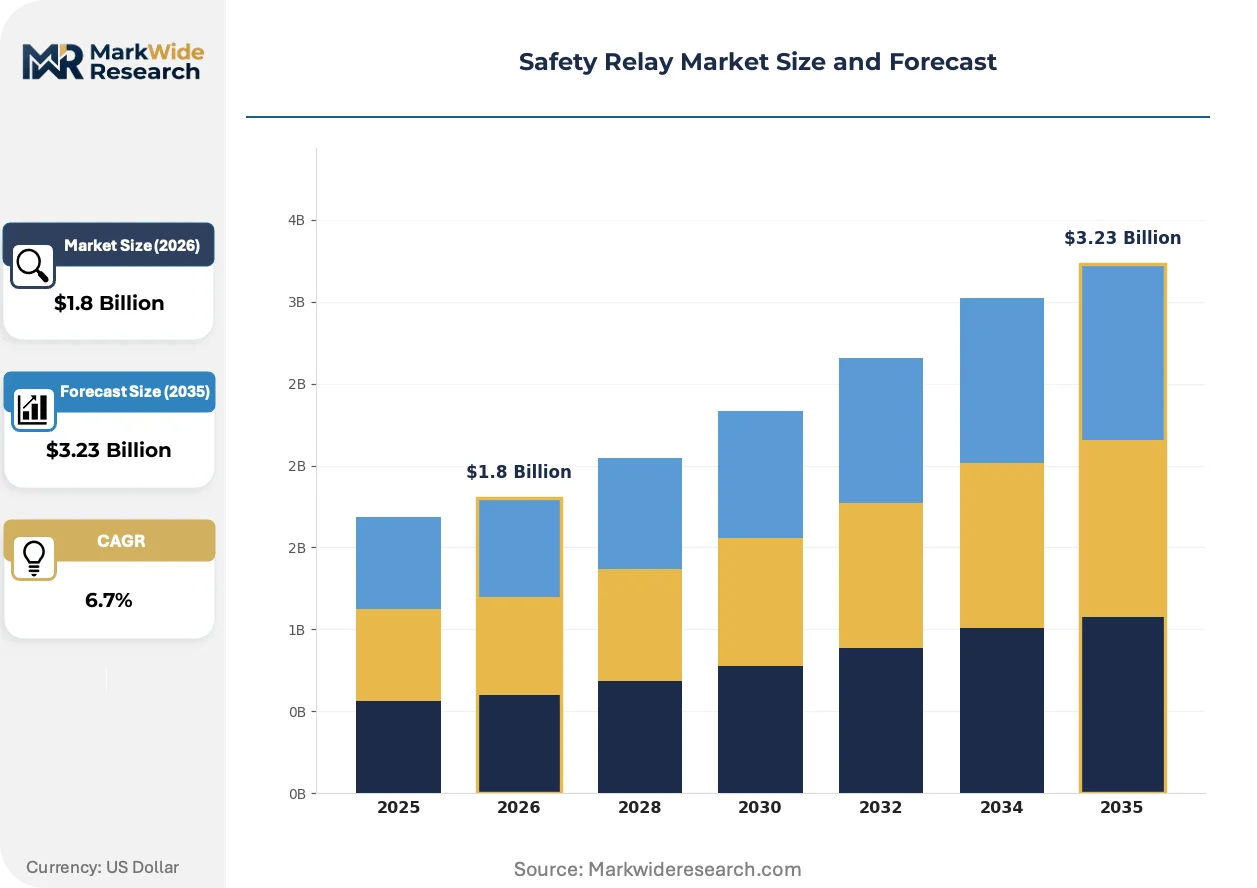
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Relays, Solid State Relays, Safety Monitoring Relays, Modular Relay Systems End User: Manufacturing, Automotive, Oil & Gas, Food & Beverage Application: Machine Safety, Emergency Stop Systems, Guard Monitoring, Access Control Technology: Wired Technology, Wireless Technology, Embedded Technology, Programmable Technology |
| Companies Covered | Rockwell Automation, OMRON Industrial Automation, Siemens AG, ABB, Eaton Corp., Schneider Electric, Pilz GmbH & Co. KG, SICK AG, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Relay Market Emerging Trajectories
Diagnostics integration is compressing the traditional separation between safety relays and programmable safety controllers. This convergence is redrawing competitive boundaries and enabling new service revenue models.
Solid-state power switching is decomposing the electromechanical relay's century-old dominance in high-reliability applications. Automotive body shop welding robots operating at 500+ cycles per hour are adopting semiconductor-based safety outputs to eliminate contact wear and arc faults. This substitution is collapsing maintenance intervals and enabling predictive failure algorithms that electromechanical designs cannot support.
EU Machinery Regulation enforcement by German KBA and Italian market surveillance authorities is tightening CE marking verification for safety components. Non-conforming imports face border detention and recall liability exposure. Asian suppliers are accelerating notified body partnerships to maintain European market access.
Automotive OEMs are compressing supplier qualification timelines as electric vehicle platform launches accelerate. Tier-1 integrators are demanding pre-certified safety relay modules with embedded PROFIsafe or CIP Safety stacks. This preference shift favors suppliers with in-house functional safety consulting capabilities over component-only vendors.
Safety Relay Market Segmentation
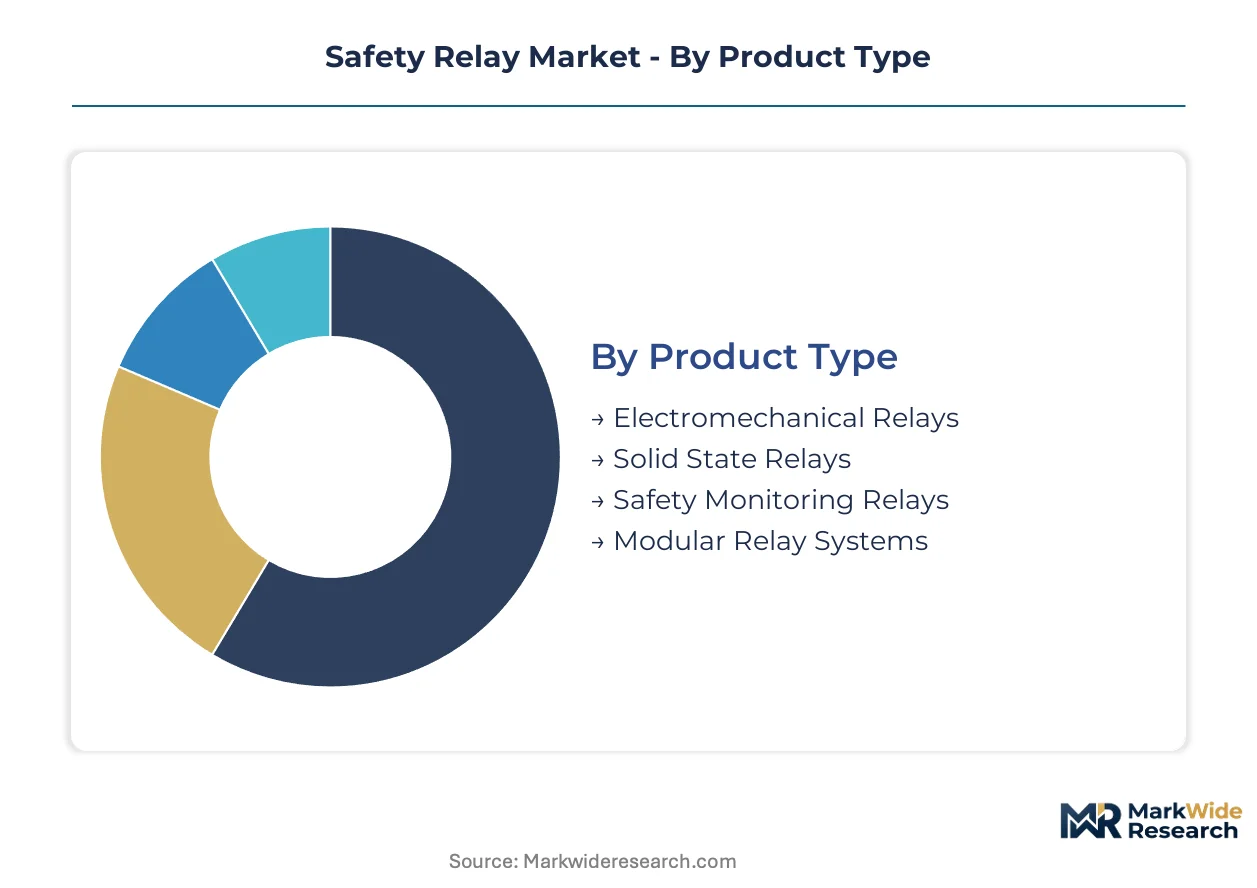
Safety relay procurement patterns diverge sharply between domestic automation upgrades and export-driven machinery manufacturing. Segment-level demand concentrates where functional safety mandates intersect with high-volume production environments.
Product Type:
Domestic demand for solid-state and modular architectures dominates in Japan and Germany where automotive OEMs specify sub-30-millisecond response times. Electromechanical relays retain stronger export orientation toward brownfield industrial markets in Southeast Asia and Eastern Europe.
- Solid State Relays:Semiconductor-based switching eliminates contact wear in high-cycle welding robotics operating above 500 cycles per hour. German automotive body shops specify these for predictive maintenance compatibility. MOSFET and IGBT supply volatility from Asian foundries constrains margin expansion.
- Safety Monitoring Relays:Integrated self-diagnostic logic reduces external wiring complexity in dense machine-tool installations. China's eastern manufacturing corridor multiplies safety circuit node counts per square kilometer. These command the highest margin pools due to embedded functional safety certification.
- Electromechanical Relays:Century-old contactor technology persists in cost-sensitive retrofit projects where maintenance technician familiarity slows substitution.
- Modular Relay Systems:Flexible I/O expansion supports line reconfiguration demands in automotive body shops.
Electromechanical relays command the established base. The steepest expansion runs through solid-state architectures.
End User:
Cost tier stratification separates premium-certified automotive demand from standard-grade manufacturing procurement. Automotive and oil & gas segments absorb 70% of SIL 3 and PLe-rated relay volume.
- Automotive:Electric vehicle platform launches compress supplier qualification timelines for pre-certified PROFIsafe modules. Tier-1 integrators demand embedded safety communication stacks. ISO 13849 compliance urgency accelerates replacement cycles in German and Japanese body-in-white welding lines.
- Manufacturing:Factory automation density in China's eastern corridor outpaces other regional clusters. Dense safety circuit node counts per facility multiply relay procurement volumes.
- Oil & Gas:Hazardous area classifications mandate explosion-proof relay housings with redundant channel architectures.
- Food & Beverage:FDA 21 CFR Part 820 quality systems indirectly shape safety relay specifications in North American packaging equipment.
Automotive absorbs the premium tier. Manufacturing drives volume scale.
Application:
Application maturity varies from standardized emergency stop systems to emerging collaborative robot speed monitoring. Machine safety and emergency stop applications concentrate in established automotive and metalworking sectors.
- Machine Safety:Light curtains and interlock switches trigger power interruption to actuators within 30 milliseconds. German KBA enforcement of EU Machinery Regulation tightens CE marking verification for these components.
- Emergency Stop Systems:OSHA lockout/tagout standards mandate redundant safety relay channels in US metalworking and plastics machinery.
- Guard Monitoring:Physical barrier integrity verification supports traditional automotive press line installations.
- Access Control:Compact dual-channel relays with integrated speed monitoring expand fastest in collaborative robot installations.
Emergency stop systems anchor the installed base. Access control climbs fastest on cobot integration.
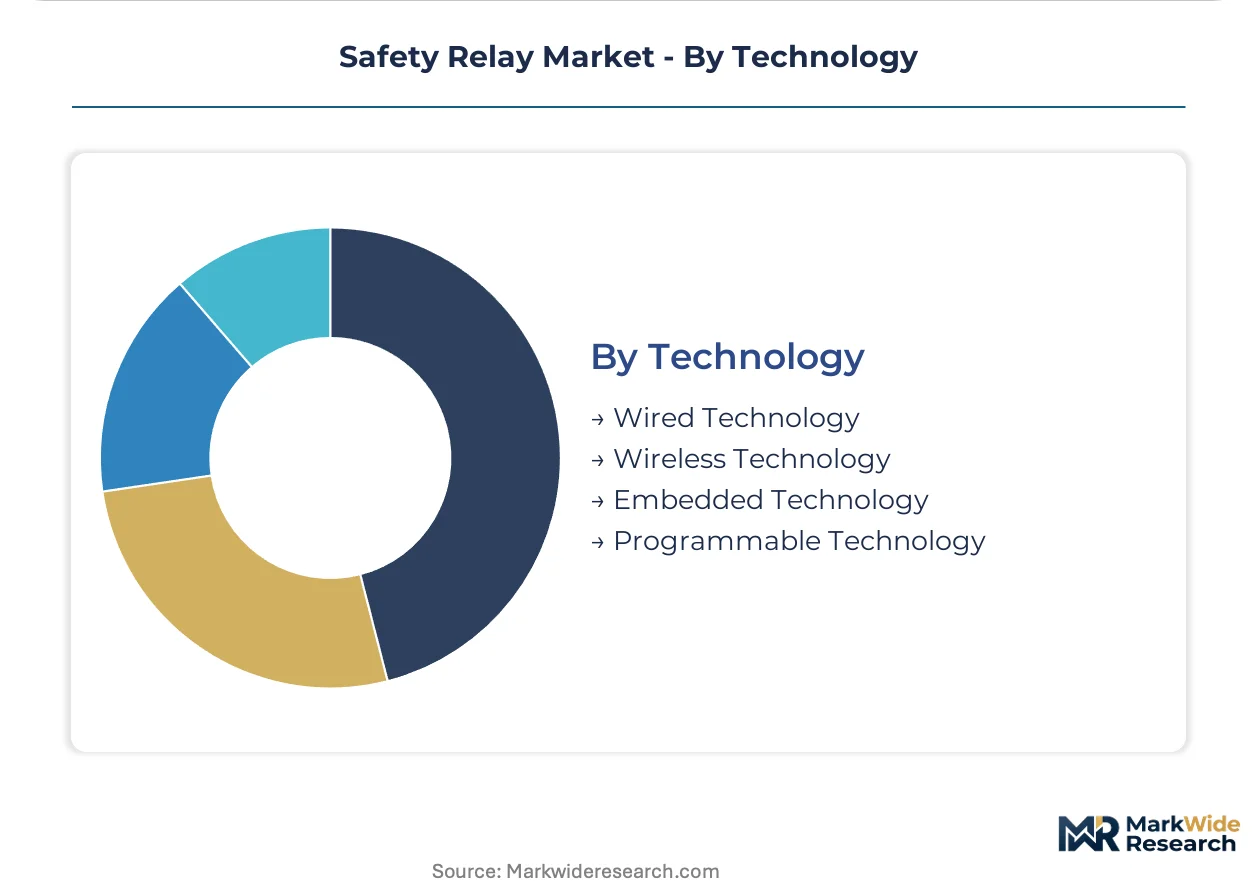
Technology:
Supply concentration in semiconductor fabrication shapes technology migration timelines. Wired technology dominates brownfield maintenance replacement while embedded and programmable architectures capture greenfield automation investment.
- Embedded Technology:PROFIsafe and CIP Safety protocol stacks integrate directly into relay firmware. Greenfield automotive plants in Germany and Japan displace discrete wiring with network-integrated safety communication. This reduces external diagnostic hardware requirements.
- Programmable Technology:Configurable safety logic blurs boundaries between relays and programmable safety controllers. Automotive OEMs demand this flexibility for electric vehicle platform variants.
- Wired Technology:Hardwired safety relay banks persist in legacy facilities where retrofit coordination with Siemens, Rockwell, and Mitsubishi controller ecosystems consumes project engineering hours.
- Wireless Technology:Battery-free energy harvesting and ISA100.11a protocols enable safety circuit deployment in mobile equipment and rotating machinery.
Wired technology holds the legacy position. Embedded architectures gain share fastest in greenfield automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for factory automation are redrawing procurement geography across major manufacturing economies. Regulatory enforcement timelines and industrial cluster density determine where safety relay demand concentrates fastest.
China
Eastern manufacturing corridors in Jiangsu and Zhejiang provinces multiply safety circuit node counts per square kilometer as localized automation upgrades outpace other regional clusters. GB standards alignment with ISO 13849 accelerates domestic supplier qualification under SAMR oversight. Dense machine-tool installations in the Yangtze River Delta drive modular relay system procurement for flexible line reconfiguration.
Germany
Automotive body-in-white welding lines specify sub-30-millisecond response times, compressing supplier qualification timelines for pre-certified PROFIsafe modules. KBA enforcement of EU Machinery Regulation tightens CE marking verification for safety components. Bavarian and Baden-Württemberg automotive clusters anchor electromechanical-to-solid-state substitution in high-cycle robotics.
United States
OSHA lockout/tagout standards mandate redundant safety relay channels in metalworking and plastics machinery across Midwest industrial states. FDA 21 CFR Part 820 quality systems indirectly shape specifications in pharmaceutical packaging equipment sold into domestic markets. Michigan and Ohio automotive corridors absorb premium-tier SIL 3 and PLe-rated relay volume.
Japan
Automotive OEMs accelerate electric vehicle platform launches, demanding embedded safety communication stacks from tier-1 integrators. METI industrial safety guidelines align with international functional safety standards. Kanto and Chubu manufacturing belts concentrate solid-state relay adoption in 500+ cycle-per-hour welding robotics.
India
PLI scheme incentives for advanced manufacturing attract safety relay suppliers to establish local assembly operations. BIS standards qualification offers first-mover positioning in domestic automation tenders. Maharashtra and Gujarat industrial zones see rising procurement for collaborative robot integration with compact dual-channel safety relays.
Safety Relay Market Vendor Landscape
Player mix skews toward diversified industrial automation conglomerates with embedded safety portfolios. The competitive structure tiers across functional safety specialists, scale-driven component manufacturers, and vertically integrated control system providers. Two dominant archetypes emerge: German-engineered consulting-heavy suppliers and Asia-Pacific production-optimized fabricators. Capacity expansion in semiconductor-based switching and strategic partnerships for protocol certification constitute the primary competitive moves.
Among Germany-based engineering heritage groups, Pilz GmbH & Co. KG and Siemens AG occupy positions that exemplify the consulting-integrated archetype, anchoring European market presence through deep ecosystem integration. OMRON Industrial Automation represents the Asia-Pacific production vector, situating within localized certification turnaround capabilities. These three entities span the geographic and strategic spectrum without exhausting the competitive map.
| Leading Market Players |
|---|
| Rockwell Automation |
| OMRON Industrial Automation |
| Siemens AG |
| ABB |
| Eaton Corp. |
| Schneider Electric |
| Pilz GmbH & Co. KG |
| SICK AG |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Solid-state relay substitution of electromechanical architectures is simultaneously redrawing supply geography toward Asian semiconductor foundries and compressing pricing power across German and Japanese engineering-centric suppliers. This dual restructuring forces tier-1 automotive buyers to rebalance total cost of ownership calculations between silicon carbide substrate volatility and predictive maintenance value capture.
Pricing Analysis
Certification grade creates the primary spread between premium and standard tiers, with SIL 3 and PLe-rated modules commanding substantial premiums over unrated alternatives in automotive and oil & gas procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differential diagnostic coverage and protocol integration depth. Pricing pressure stems from power MOSFET and IGBT input volatility originating in concentrated Asian foundries. Brownfield retrofit segments exhibit highest price sensitivity due to maintenance technician familiarity with legacy electromechanical contactors, while greenfield automotive OEMs prioritize response-time performance over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for semiconductor substrates and relay housings, compressing landed margins for European system integrators. Manufacturing concentration centers on Germany, Japan, and China, with Taiwanese foundries supplying critical MOSFET and IGBT components. Raw material dependencies include silicon carbide substrates, copper coil windings, and engineered polymer housings. Single-source vulnerability in advanced semiconductor fabrication creates structural exposure. Distribution runs through authorized industrial automation distributors with field engineering support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Safety relay procurement is shifting toward platform-economics logic as automotive OEMs demand pre-certified modules with embedded PROFIsafe and CIP Safety stacks, collapsing the traditional separation between hardware vendors and system integrators.
For Market Incumbents: Consolidate functional safety engineering capabilities through targeted capability acquisition in redundant channel architecture design, countering talent scarcity that limits expansion capacity. Deepen backward integration into semiconductor switching components to offset power MOSFET and IGBT price volatility from Asian foundries. Anchor channel control through certified integrator partnerships that embed proprietary protocol stacks. For New Entrants and Emerging Players: Accelerated BIS qualification under India's PLI scheme offers first-mover positioning in domestic automation tenders before incumbent certification timelines adapt. Target collaborative robot integration segments where compact dual-channel safety relays with integrated speed monitoring expand faster than traditional guarding. Pursue pharmaceutical packaging equipment specifications shaped by FDA 21 CFR Part 820 quality systems as a premium-tier entry vector. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German engineering specialists possessing stranded functional safety consulting capabilities without scalable semiconductor production. Long-term viability hinges on protocol certification moats and automotive OEM platform standardization decisions over the next decade. Monitor electric vehicle platform launch cadence as the critical inflection signal for pre-certified module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | Accelerates CE marking verification timelines for EU Machinery Regulation compliance under German KBA and Italian authority oversight. |
| Semiconductor Switching Integration | Eliminates contact wear in 500+ cycle-per-hour welding robotics while enabling predictive failure algorithms. |
| Embedded Protocol Stack Development | Reduces external diagnostic hardware requirements in greenfield automotive plants specifying PROFIsafe or CIP Safety. |
| Functional Safety Consulting Capability | Differentiates component vendors from integrated solution providers as automotive OEMs compress qualification timelines. |
| Localized Assembly Operations | Captures PLI scheme incentives in India and BIS qualification advantages in Maharashtra and Gujarat industrial zones. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at automotive and manufacturing facilities, then refined through secondary validation against SEC 10-K filings, customs and trade data, industrial automation association reports, and notified body certification databases. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices. Modeled dimensions span solid-state versus electromechanical architectures, automotive versus manufacturing end-use concentration, and embedded versus wired technology adoption curves. Forecast inputs incorporate electric vehicle platform launch schedules, factory automation density metrics in China's eastern corridor, and functional safety certification backlog estimates from German and Italian notified bodies.
Decision-makers should treat outputs as directional under assumptions of sustained ISO 13849 enforcement intensity and semiconductor supply normalization; material deviation in automotive OEM platform cadence or silicon carbide substrate availability would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Speaker Cone Material Market
Electronic Components
Impulse Relays Market
Electronic Components
Amplifier Market
Electronic Components
Electronic Wipe Market
Electronic Components
Power Inductors Market
Electronic Components
Electric Capacitor Market
Electronic Components
SAW Filters Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Motherboard Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
AC Adapter Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Global Capacitor Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
United States Radiation-Hardened Electronics Market