
 Wireless Charging Stand Market | 2026-2036
Wireless Charging Stand Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Charging Stand Market Analytics
Retail shelf space allocation is reconfiguring as big-box electronics chains and direct-to-consumer platforms compete for exclusive placement of premium charging accessories. Belkin International leverages its longstanding Apple Store partnerships to sustain premium positioning in North American channels. Anker Innovations competes aggressively on Amazon's marketplace, where its review volume anchors mid-tier consumer trust. Samsung Electronics extends its Galaxy ecosystem strategy by bundling stands with flagship smartphone launches, controlling upgrade-cycle timing.
A wireless charging stand is a fixed-position inductive power transfer device comprising a transmitter coil, ferrite shielding, and control circuitry that converts AC mains input to resonant magnetic field output, typically operating at 110-205 kHz under Qi protocol specifications. Its commercial purpose centers on eliminating cable wear and enabling hands-free device viewing during power delivery. Multi-device chargers now capture disproportionate margin pools as households accumulate Qi-enabled earbuds, watches, and phones requiring simultaneous replenishment. Fast chargers built on the Qi2 magnetic alignment standard represent the fastest-expanding technology segment, displacing legacy 5W inductive units in premium tiers. Desktop chargers remain the volume backbone across enterprise procurement contracts where IT standardization favors uniform form factors.
The Wireless Power Consortium's Qi certification program and the EU's Radio Equipment Directive impose electromagnetic compatibility and safety thresholds that filter uncertified competitors from European and North American market access. China's MIIT radio transmission regulations and compulsory GB standards for electromagnetic radiation exposure add compliance layers for domestic manufacturers exporting through Shenzhen and Dongguan production clusters. Stakeholders must monitor whether Qi2's magnetic alignment protocol becomes a de facto mandate through smartphone OEM bundling decisions rather than regulatory fiat alone.
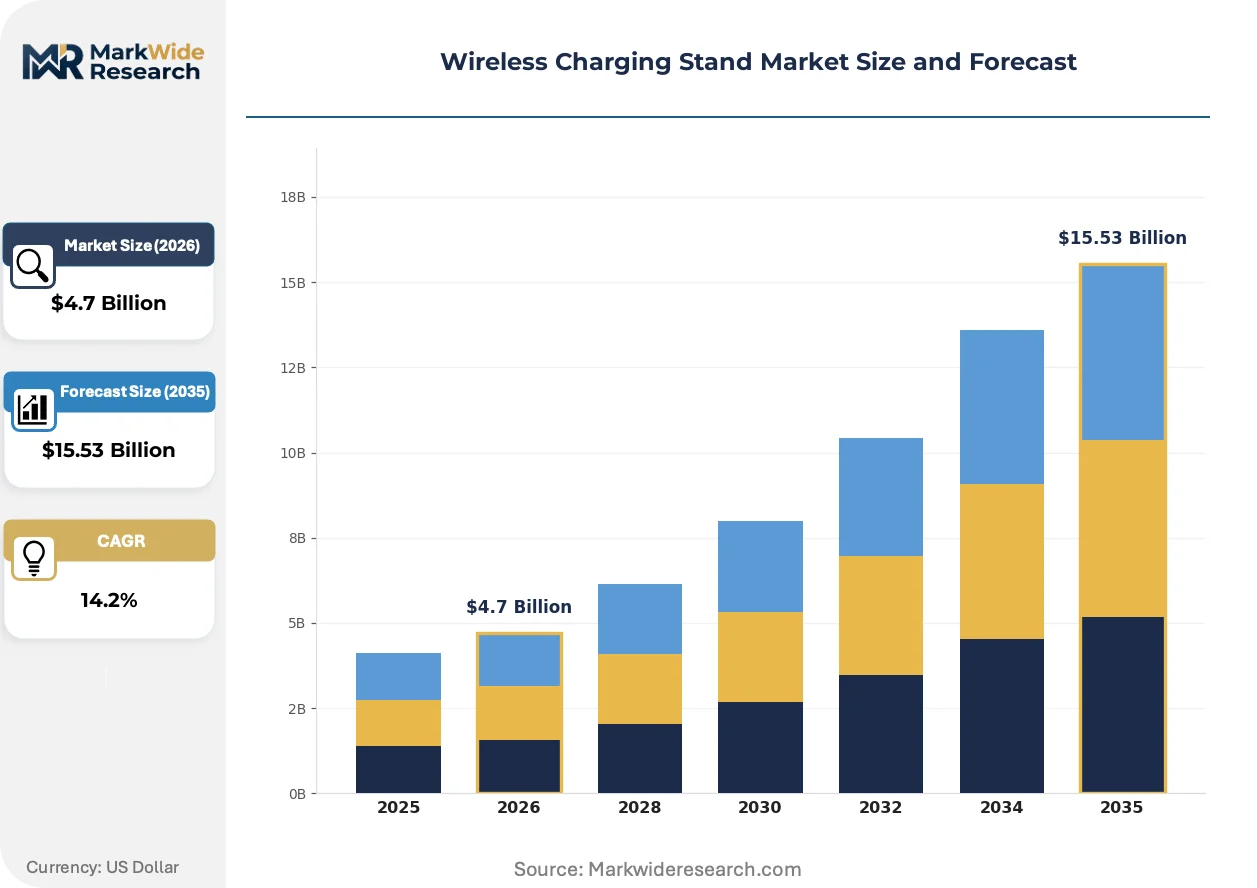
Market Dynamics
Qi2 magnetic alignment protocol standardization from the Wireless Power Consortium is compressing product lifecycles and forcing component requalification across Shenzhen and Dongguan manufacturing clusters.
Growth Catalysts
- Qi2 Certification Mandate:The Wireless Power Consortium's interoperability testing requirements are filtering uncertified suppliers from European and North American channel access, consolidating procurement toward validated vendors.
- Enterprise Workspace Refresh:IT standardization contracts across financial services and professional services sectors are specifying uniform desktop charging infrastructure with magnetic alignment features.
- Multi-Device Household Accumulation:Simultaneous replenishment demand for earbuds, watches, and phones is expanding addressable unit economics beyond single-device replacement cycles.
Market Restraints
- Ferrite Core Supply Concentration:Shielding material production clusters in China's Hunan and Jiangxi provinces create input cost volatility and single-source vulnerability for transmitter coil assemblies.
- EU Radio Equipment Directive Compliance Burden:Electromagnetic compatibility testing timelines and notified body queue lengths extend product launch windows by 4-8 months for non-EU manufacturers.
- Legacy 5W Inductive Substitution:Low-cost unbranded pad chargers continue capturing price-sensitive consumer segments, compressing stand-format adoption in entry tiers.
Strategic Opportunities
- India BIS Certification Pathway:The Bureau of Indian Standards' phased radio equipment mandate creates first-mover positioning for Qi2-compliant vendors ahead of domestic manufacturing scale-up.
- Automotive Console Integration:Center-stack and tray-embedded charging surfaces in passenger vehicles represent untapped specification channels requiring thermal management and vibration-hardened designs.
- Healthcare IT Procurement:HIPAA-aligned clean-power requirements in US hospital systems favor certified stands with isolation transformers and leakage current monitoring.
Industry Challenges
- RF Engineer Talent Scarcity:Resonant magnetic field design expertise concentrates in Dongguan and Taipei, constraining R&D expansion for second-tier vendors.
- Qi2 Retrofit Complexity:Existing inventory and channel stock require write-downs or controller board swaps, creating working capital strain during transition windows.
- Patent Licensing Fragmentation:Wireless Power Consortium pool licenses coexist with independent patent holders in magnetic alignment and foreign object detection, complicating freedom-to-operate analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Charging Stand Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Chargers, Portable Stands, Multi-Device Chargers, Fast Chargers Technology: Inductive Charging, Resonant Charging, Magnetic Resonance, AirFuel End User: Consumers, Enterprises, Educational Institutions, Healthcare Facilities Material: Plastic, Metal, Glass, Wood |
| Companies Covered | Apple, Samsung Electronics, Belkin International, Anker Innovations, Mophie, RAVPower, Xiaomi, Baseus, Nillkin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Charging Stand Market Evolving Landscape
Magnetic alignment architectures and thermal management advances are redefining performance benchmarks while regulatory harmonization efforts compress cross-border product variation.
Qi2's 15W magnetic alignment standard with 360-degree rotational freedom is rendering obsolete fixed-position stands requiring precise placement guesswork. Enterprise procurement teams and hospitality outfitters are specifying these units for guest room and hot-desk deployments. The technology is compressing return rates and support ticket volume previously driven by misalignment complaints.
EU Radio Equipment Directive electromagnetic compatibility thresholds are hardening test documentation requirements for transmitter coil assemblies. Manufacturers must now submit third-party SAR exposure assessments and foreign object detection validation protocols before CE marking authorization. Premium-tier vendors with in-house anechoic chamber capacity are internalizing compliance timelines while smaller competitors face notified body bottlenecks.
Direct-to-consumer platform purchasing is displacing big-box electronics retail for mid-tier accessory selection. Amazon's review aggregation and same-day fulfillment infrastructure has concentrated consumer trust formation online rather than through physical shelf comparison. This shift is most pronounced in North American and Western European urban markets where Prime penetration exceeds 60 percent of households with Qi-enabled device ownership.
Wireless Charging Stand Market Segmentation
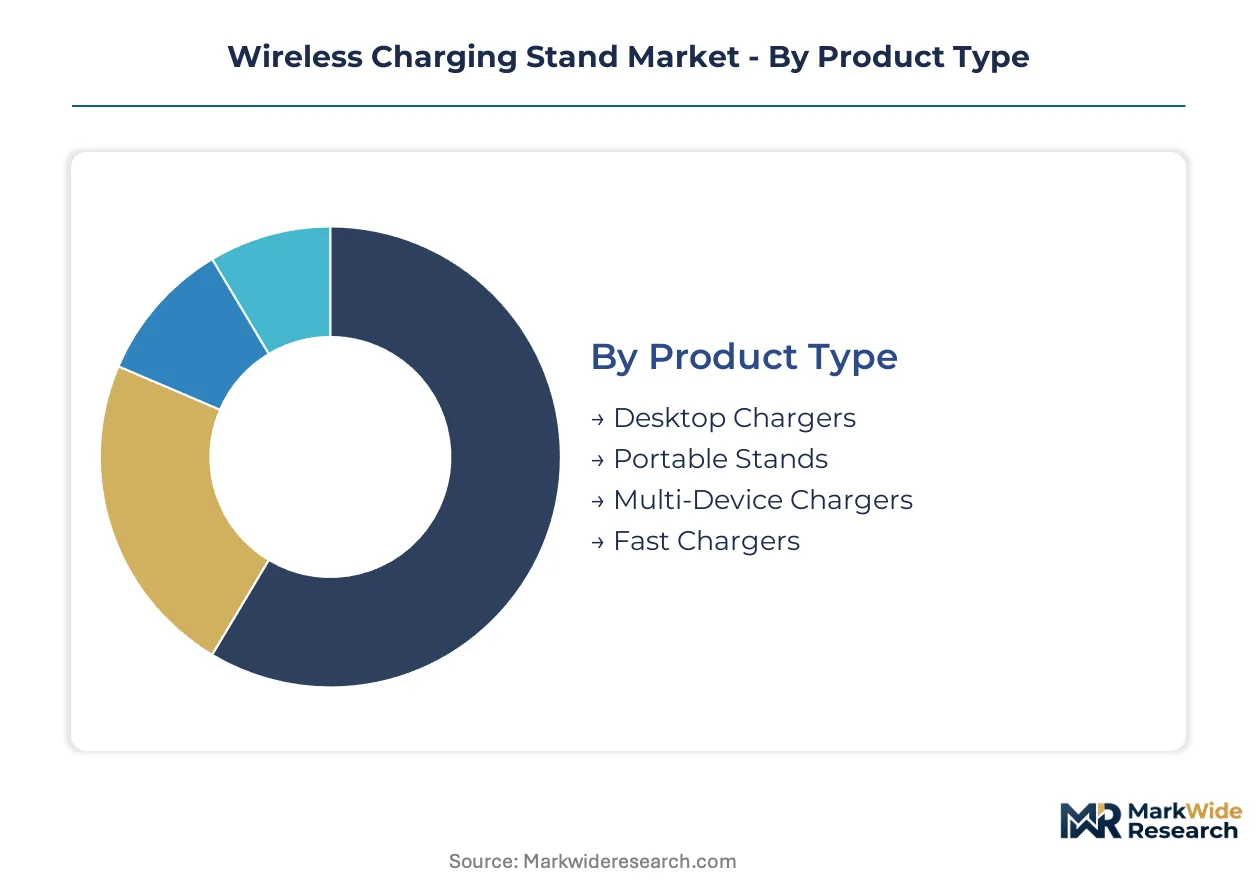
Wireless charging stand segmentation reveals how Qi2 standardization is fragmenting procurement specifications across enterprise IT, consumer retail, and specialized verticals. Each dimension captures distinct margin pools and compliance burdens that reshape vendor positioning.
Product Type:
Cost tier differentiation separates volume plays from premium-margin capture in charging hardware deployment cycles.
- Desktop Chargers:Fixed-position units with ferrite shielding and 110-205 kHz resonant coils dominate enterprise procurement contracts where IT standardization favors uniform form factors across workstation fleets. Financial services firms in Frankfurt and Singapore specify these for hot-desk environments, though legacy 5W inductive units face Qi2 retrofit pressure.
- Multi-Device Chargers:Simultaneous replenishment architectures for earbuds, watches, and phones capture disproportionate margin pools as household device accumulation accelerates. Hospitality outfitters in Dubai and Miami Beach specify these for guest room deployments where magnetic alignment reduces support ticket volume.
- Portable Stands:Collapsible or travel-format units with reduced coil mass target mobile professionals.
- Fast Chargers:Qi2-compliant 15W magnetic alignment units with rotational freedom.
Desktop Chargers hold installed capacity. Multi-Device Chargers is rotating up the share rankings.
Technology:
Application suitability determines protocol selection as interoperability mandates harden across regulatory jurisdictions.
- Inductive Charging:Near-field magnetic coupling between aligned transmitter and receiver coils operating at 110-205 kHz under Qi protocol specifications. Consumer electronics OEMs in Shenzhen and Seoul embed this in smartphone accessories where cost minimization overrides efficiency optimization.
- Magnetic Resonance:Tightly coupled resonant systems with extended positioning tolerance for multi-device arrays. Automotive tier-1 suppliers in Stuttgart and Nagoya evaluate this for center-stack integration where vibration hardening and thermal management requirements apply.
- Resonant Charging:Loosely coupled architectures with greater spatial freedom but lower efficiency.
- AirFuel:Uncoupled magnetic resonance specification competing for industrial and infrastructure deployment.
Inductive Charging commands current volume. Magnetic Resonance is gaining specification traction fastest.
End User:
Customer type segmentation exposes divergent procurement authority structures and compliance thresholds.
- Enterprises:IT standardization contracts across professional services and financial sectors specify uniform desktop infrastructure with magnetic alignment features. HIPAA-aligned clean-power requirements in US hospital systems favor certified stands with isolation transformers.
- Healthcare Facilities:Clinical environments with leakage current monitoring and electromagnetic compatibility validation. Procurement teams prioritize Qi certification and third-party SAR exposure assessments.
- Consumers:Individual purchasers through Amazon marketplace and direct-to-consumer platforms.
- Educational Institutions:Campus-wide deployment with bulk procurement and extended warranty requirements.
Enterprises hold contract value concentration. Healthcare Facilities is climbing the specification priority ladder.
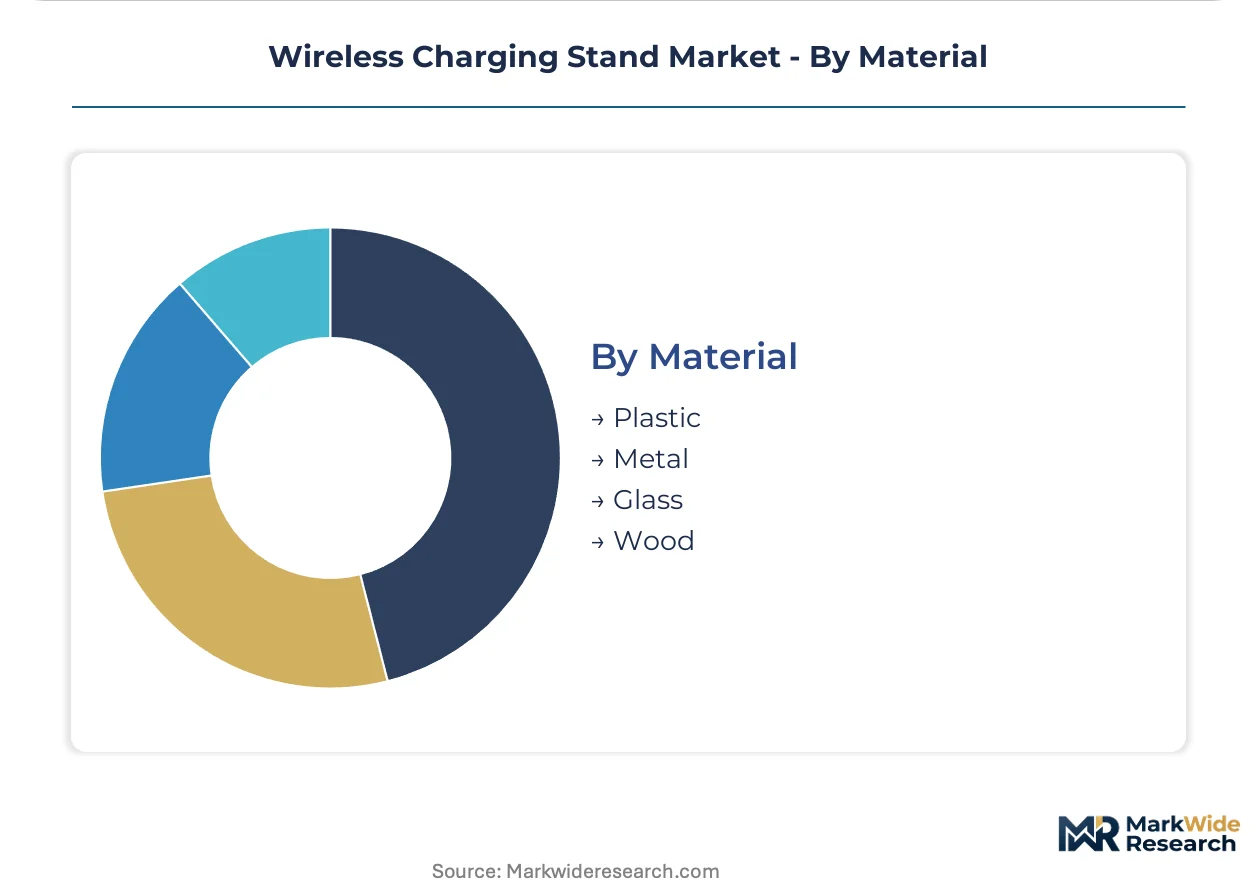
Material:
Supply concentration in raw material processing clusters shapes cost tier accessibility and design flexibility.
- Metal:Aluminum and zinc alloy enclosures with thermal dissipation properties for high-wattage Qi2 units. Premium-tier vendors source from Dongguan die-casting clusters where surface finishing capabilities support Apple Store aesthetic requirements.
- Plastic:ABS and polycarbonate housings with ferrite core integration for cost-optimized entry tiers. Injection molding capacity in Shenzhen and Ningbo enables rapid SKU rotation for Amazon marketplace sellers.
- Glass:Tempered surface panels for aesthetic differentiation in hospitality and residential segments.
- Wood:Bamboo and walnut veneers targeting sustainable positioning in Nordic and Japanese markets.
Plastic holds unit volume dominance. Metal is ascending the premium tier rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Bureau of Indian Standards phased radio equipment mandate is accelerating first-mover positioning for Qi2-compliant vendors ahead of domestic manufacturing scale-up. Germany's notified body queue lengths under EU Radio Equipment Directive compliance are extending product launch windows for Asian exporters. China's MIIT radio transmission regulations and compulsory GB standards continue filtering uncertified competitors from European and North American market access.
United States
HIPAA-aligned clean-power requirements in US hospital systems favor certified stands with isolation transformers and leakage current monitoring. The FCC maintains electromagnetic compatibility thresholds for transmitter coil assemblies entering consumer electronics channels. Silicon Valley procurement teams and New York financial services firms specify uniform desktop infrastructure with magnetic alignment features for hot-desk environments.
China
Xiaomi and Baseus dominate domestic manufacturing and pricing tiers as demand clusters concentrate in tier-one cities. MIIT radio transmission regulations and compulsory GB standards for electromagnetic radiation exposure add compliance layers for Shenzhen and Dongguan production clusters. Dongguan die-casting facilities supply aluminum enclosures with thermal dissipation properties for high-wattage Qi2 units.
Germany
Automotive tier-1 suppliers in Stuttgart evaluate magnetic resonance systems for center-stack integration where vibration hardening applies. ECHA and REACH compliance requirements shape material selection for ferrite shielding and enclosure finishes. Frankfurt financial services firms specify Qi2-compliant desktop chargers for workstation fleet standardization contracts.
Japan
METI efficiency standards and JIS certification protocols govern resonant coil assembly quality thresholds for consumer electronics accessories. Nagoya automotive suppliers assess multi-device charging surfaces for passenger vehicle console integration. Tokyo-based electronics retailers allocate premium shelf space to magnetic alignment units with 360-degree rotational freedom.
India
The Bureau of Indian Standards phased radio equipment mandate creates first-mover positioning for Qi2-compliant vendors ahead of domestic manufacturing scale-up. BIS certification pathways filter uncertified suppliers from channel access as procurement shifts toward validated vendors. Bengaluru IT parks and Mumbai financial districts specify uniform desktop charging infrastructure for enterprise workspace refresh cycles.
Wireless Charging Stand Market Competitive Landscape
On the supply side, the industry is consolidating around validated vendors with Qi2 certification and notified body relationships. Component requalification pressures across Shenzhen and Dongguan manufacturing clusters are compressing product lifecycles and elevating capital requirements. Three strategic archetypes dominate: ecosystem-integrated smartphone OEMs, premium-tier accessory specialists with Apple Store partnerships, and Amazon-native volume players competing on review aggregation. Dominant competitive moves include strategic partnerships with electronics retail chains and portfolio diversification into multi-device charging architectures.
Among Cupertino-based ecosystem integrators, Apple exemplifies the proprietary magnetic alignment strategy through vertical control over device-charger interoperability. Samsung Electronics anchors the Android-aligned tier, bundling charging hardware with flagship smartphone launches to control upgrade-cycle timing. Belkin International occupies a position within the premium accessory archetype, leveraging longstanding retail partnerships to sustain positioning in North American channels.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Belkin International |
| Anker Innovations |
| Mophie |
| RAVPower |
| Xiaomi |
| Baseus |
| Nillkin |
| Others |
Value Network & Pricing Analysis
Dongguan die-casting clusters command premium-tier enclosure pricing through thermal dissipation capabilities that Apple Store aesthetic requirements demand. Shenzhen injection molding capacity enables rapid SKU rotation for Amazon marketplace sellers, compressing mid-tier margins through volume competition. This geographic bifurcation creates pricing power concentration at the quality extremes while standard-format hardware faces cost compression.
Pricing Analysis
Qi2 certification grade creates the primary spread between premium and entry tiers. Three-tier pricing structure across premium, standard, and economy levels reflects brand premium, after-sales service bundling, and electromagnetic compatibility validation depth. Cost compression in entry tiers is intensifying because legacy 5W inductive units face displacement pressure from magnetic alignment protocols. Enterprise procurement teams show least price sensitivity due to IT standardization mandates, while individual Amazon purchasers exhibit highest elasticity.
Supply Chain Analysis
Export-control scrutiny on resonant magnetic field design expertise limits technology transfer from Dongguan and Taipei R&D centers. Ferrite shielding production draws from Hunan and Jiangxi province mining clusters, while transmitter coil assemblies rely on Taiwan semiconductor packaging capabilities. Single-source vulnerability in ferrite core supply creates input cost volatility. Distribution runs through direct-to-consumer platforms and electronics retail chains in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless charging stand market is recovering through enterprise workspace refresh cycles as IT standardization contracts accelerate replacement demand. Qi2 protocol adoption represents the cyclical driver justifying positioning ahead of magnetic alignment hardware deployment.
For Market Incumbents: Build certification moats through Wireless Power Consortium notified body relationships that filter uncertified competitors from European channel access. Defend against emerging Amazon-native volume players by anchoring mid-tier consumer trust through review aggregation dominance. Prioritize backward integration into ferrite core supply to mitigate Hunan and Jiangxi province concentration risk.
For New Entrants and Emerging Players: India's BIS certification pathway offers underpenetrated white-space ahead of domestic manufacturing scale-up. Target automotive console integration specifications where vibration-hardened designs and thermal management requirements create technical barriers. Pursue healthcare IT procurement channels with HIPAA-aligned clean-power positioning as the go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Qi2-compliant vendors with magnetic alignment IP and automotive tier-1 supplier relationships. Long-term viability hinges on patent licensing freedom-to-operate in foreign object detection and resonant coil architectures. Monitor smartphone OEM bundling decisions as the inflection indicator for protocol mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Investment | Wireless Power Consortium validation filters uncertified suppliers from European and North American channel access. |
| Automotive Tier-1 Partnership | Center-stack integration specifications in Stuttgart and Nagoya create untapped specification channels requiring hardened designs. |
| Healthcare IT Procurement Alignment | HIPAA-compliant clean-power requirements in US hospital systems favor certified stands with isolation transformers. |
| India BIS Certification Pathway | Bureau of Indian Standards phased mandate creates first-mover positioning ahead of domestic manufacturing scale-up. |
| Multi-Device Architecture Development | Simultaneous replenishment demand for earbuds, watches, and phones expands addressable unit economics beyond single-device cycles. |
Research Methodology
Cross-validation between primary interviews with wireless power engineers and secondary validation through FCC electromagnetic compatibility filings anchors the qualitative findings. Procurement officers at financial services firms, IT standardization leads at professional services companies, and channel managers at electronics retail chains provided operational perspective. SEC 10-K disclosures, Wireless Power Consortium certification databases, and EU Radio Equipment Directive notified body records supplied quantitative benchmarks. Bottom-up transmitter coil shipment analysis and top-down enterprise IT spending triangulation calibrated market sizing.
Calibration against historical Qi protocol adoption curves and smartphone accessory attachment rates structured the analytical framework across the projection horizon. Product type, technology protocol, end-user vertical, and material composition segmentation dimensions modeled demand fragmentation. CAGRs derived from installed base replacement cycles and magnetic alignment upgrade elasticity. Enterprise workspace refresh contract timing and automotive OEM specification pipelines served as industry-specific forecast inputs.
Practitioners should monitor Wireless Power Consortium bundling decisions and EU notified body queue lengths for early signals of protocol acceleration or compliance delay. Forecasts reflect assumptions around Qi2 magnetic alignment adoption curves and ferrite core supply stability. Material shifts in smartphone OEM interoperability mandates or export-control expansion on resonant magnetic field technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Capacitor Kits Market
Electronic Components
Breadboards Market
Electronic Components
Structural Electronics Market
Electronic Components
Discrete Capacitors Market
Electronic Components
Resonators Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Touchless Tubes Market
Electronic Components
North America USB Retimer Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Display Port Adapters Market