
 Industrial Relays Market | 2026-2036
Industrial Relays Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Relays Market Outlook
China is reconfiguring regional supply dynamics through expanded domestic production of electromechanical and solid-state relay components. TE Connectivity leverages its vertical manufacturing footprint across Asian assembly hubs to sustain cost competitiveness in high-volume contracts. Omron Corporation anchors its position through precision engineering capabilities in factory automation relay applications. Siemens competes on system integration strength, bundling relay products with broader industrial control portfolios.
Industrial relays are electrically operated switches engineered to open or close circuits under specified load conditions, typically rated between milliamps and hundreds of amperes depending on application requirements, with coil voltages spanning 5V DC to 480V AC and mechanical life expectancies exceeding ten million operations in premium grades. Their primary purpose is to enable low-power control signals to manage high-power industrial loads while providing electrical isolation between circuits. Solid-state relays command expanding share in heating and motor control applications where silent operation and absence of mechanical wear justify premium positioning. Electromechanical variants retain dominance in cost-sensitive power distribution installations where proven durability under surge conditions matters most. Hybrid architectures are gaining traction in aerospace and precision manufacturing segments demanding both fast switching and high inrush tolerance.
IEC 61810 family standards govern relay construction and testing protocols across European and Asia-Pacific export markets, while NEMA ICS 2 requirements shape product acceptance in North American industrial installations. China's GB standards, administered by SAMR, establish mandatory certification thresholds for relays deployed in domestic energy infrastructure and railway signaling systems. UL 508 recognition remains essential for access to US factory automation and HVAC equipment supply chains. Stakeholders must monitor evolving efficiency mandates from regulators in Germany, Japan, and the United States that are embedding relay performance into broader equipment energy ratings.
Market Dynamics
Factory automation intensity in automotive and electronics assembly is compressing relay replacement cycles while IEC 61810 and NEMA certification requirements are elevating qualification barriers for new entrants.
Growth Catalysts
- Automotive EV manufacturing lines:Battery pack assembly and motor control stations require high-reliability relays rated for continuous duty cycles. Tier-1 suppliers in Germany and Japan are expanding relay procurement volumes.
- IEC 61810-1 harmonization:Unified testing protocols across European and Asia-Pacific export markets reduce duplicate certification costs. Manufacturers serving multiple jurisdictions achieve faster product launches.
- Solid-state thermal management:Silicon-controlled rectifier and triac-based relays eliminate mechanical wear in heating applications. Food processing and plastics molding sectors are standardizing on silent-switching architectures.
Market Restraints
- Copper and silver contact material volatility:Electromechanical relay production depends on precious metal plating for arc suppression. Price swings in commodity markets compress margin predictability for mid-tier producers.
- NEMA ICS 2 compliance friction:North American industrial installations require third-party validation of interrupting capacity and temperature rise. Certification timelines extend 8-14 weeks for new product families.
- Solid-state relay cost premium:Semiconductor-based switching carries 3-5x unit cost versus electromechanical equivalents. Cost-sensitive power distribution installations retain preference for mechanical architectures.
Strategic Opportunities
- India industrial corridor expansion:Dedicated freight corridors and smart grid infrastructure under CEA mandates create demand for railway signaling and substation relays. Domestic manufacturing incentives reduce import dependency.
- Hybrid relay architectures:Convergence of electromechanical durability with solid-state switching speed addresses aerospace and precision manufacturing requirements. Dual-mode designs command premium positioning in mission-critical applications.
- Direct OEM contracting:Large automation integrators are bypassing distribution layers for high-volume relay supply. Siemens and Rockwell Automation are consolidating supplier panels to capture volume pricing.
Industry Challenges
- Embedded firmware security validation:Intelligent relays with diagnostic and communication capabilities require cybersecurity certification under IEC 62443. Development teams lack sufficient industrial control security expertise.
- Legacy system integration complexity:Retrofit projects in mature manufacturing facilities must interface with 20-30 year-old control architectures. Protocol translation and physical mounting adaptations consume engineering resources.
- RoHS substance restriction compliance:Lead-free solder and cadmium-free contact materials alter thermal and electrical performance characteristics. Reformulation testing extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Relays Market |
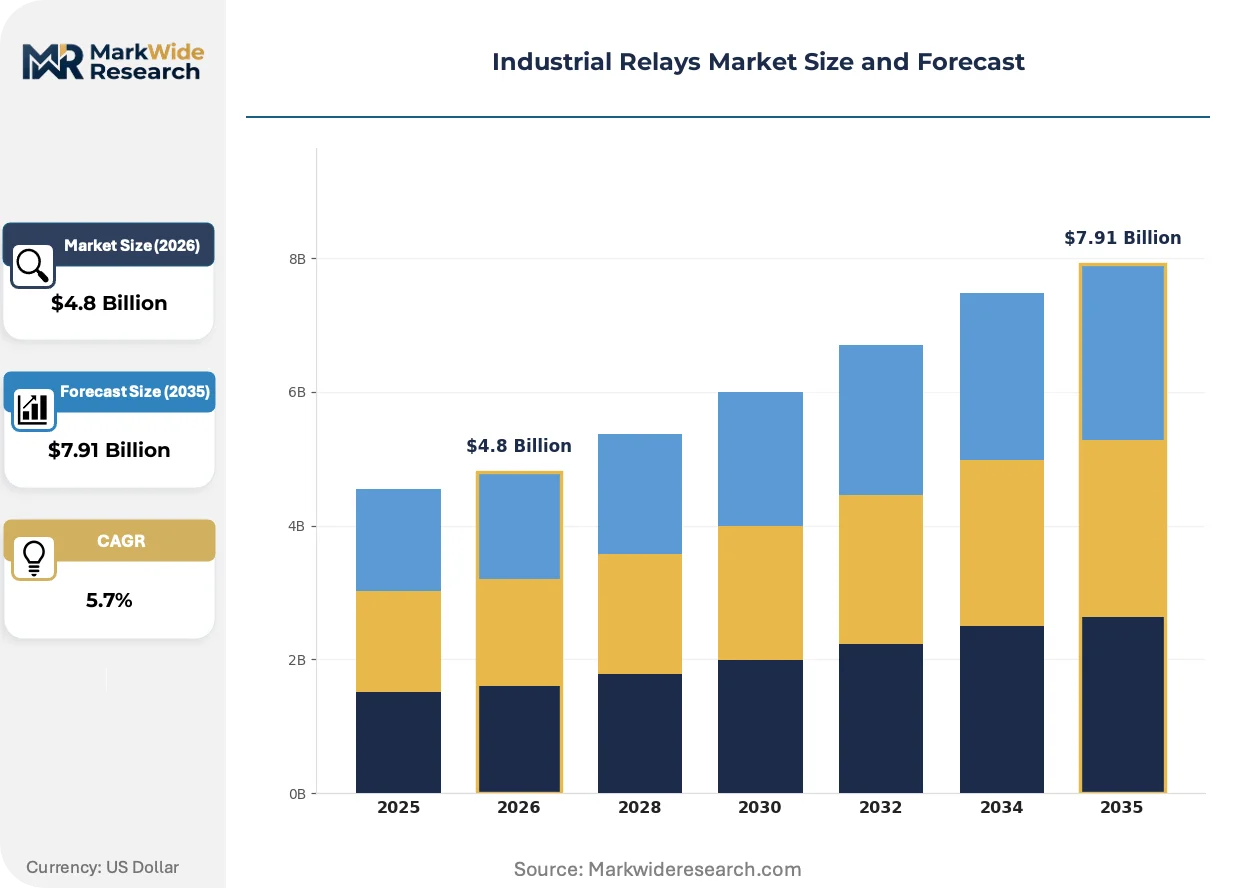
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid-State, Hybrid, Time-Delay Application: Aerospace, Manufacturing, Power Distribution, Automation End User: Energy, Transportation, Telecommunications, HVAC Contact Configuration: SPST, DPST, SPDT, DPDT |
| Companies Covered | TE Connectivity, Omron Corporation, Panasonic Holdings Corporation, Siemens, Schneider Electric, ABB, Fujitsu, Crydom, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Relays Market Strategic Shifts
Digitalization of relay functionality is merging switching hardware with predictive diagnostics, while material science advances and procurement model evolution are compressing traditional product lifecycles.
Silicon carbide power semiconductors are collapsing the performance gap between solid-state and electromechanical relays in high-current applications. Wind turbine inverter manufacturers and electric vehicle charging infrastructure builders are adopting SiC-based switching at accelerating rates. This material transition is collapsing the historical trade-off between switching speed and surge tolerance that protected electromechanical incumbency.
REACH substance restriction amendments are phasing out hexavalent chromium in relay contact plating across European industrial equipment supply chains. Manufacturers serving German automotive and French rail sectors must validate alternative corrosion-resistant coatings by 2026. Relay producers with captive plating facilities in Eastern Europe are accelerating qualification of trivalent chromium and zinc-nickel alternatives.
Consolidated supplier programs among automation integrators are compressing the viable vendor base for standard relay families. Rockwell Automation and Schneider Electric are reducing approved supplier lists from 12-15 to 4-6 qualified sources per product category. This concentration is most visible in US factory automation and German automotive assembly, where procurement teams prioritize single-source accountability over price competition.
Industrial Relays Market Segmentation
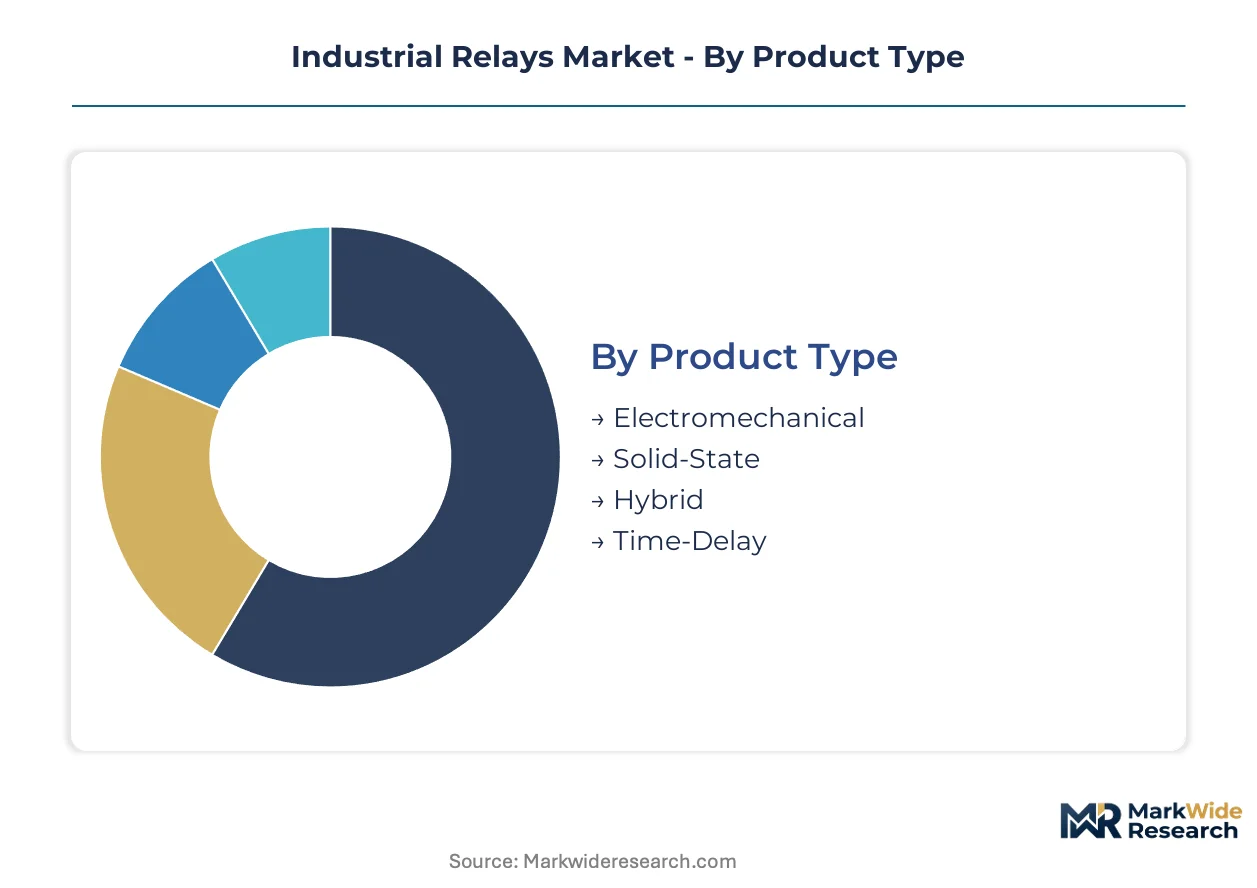
Industrial relay procurement patterns diverge sharply across product architectures and end-use environments. Understanding these segment boundaries reveals where specification premiums command pricing power versus where commoditization pressures dominate.
Product Type:
Cost tier separation defines competitive positioning across relay architectures, with semiconductor-based variants commanding substantial premiums over electromechanical alternatives.
- Electromechanical:Mechanical switching elements with silver or copper alloy contacts deliver proven surge tolerance and arc extinction. Automotive assembly lines in Germany and power distribution contractors across the US Midwest specify these for durability under inrush conditions.
- Solid-State:Silicon-controlled rectifier and triac-based architectures eliminate mechanical wear and enable silent operation. Food processing facilities in France and plastics molding operations in Japan are standardizing on these for precision thermal control.
- Hybrid:Combines electromechanical contact pairs with solid-state switching elements for mission-critical aerospace applications.
- Time-Delay:Incorporates pneumatic or electronic timing mechanisms for motor starting sequences in HVAC compressor installations.
Electromechanical holds installed capacity. Solid-State is rotating up the share rankings.
Application:
Application context determines certification burden and replacement cycle intensity, with aerospace and automation imposing the most stringent qualification requirements.
- Manufacturing:Factory automation cells require relays rated for continuous duty cycles and rapid switching frequencies. Tier-1 automotive suppliers in Japan and electronics contract manufacturers in China are compressing replacement intervals through 24/7 production schedules.
- Power Distribution:Utility-scale substations and industrial feeder circuits demand high interrupting capacity and temperature stability. Grid modernization programs under FERC guidelines in the United States and CEA mandates in India are refreshing aging relay populations.
- Aerospace:Flight control and avionics systems require DO-160 environmental qualification and hermetic sealing.
- Automation:Programmable logic controller integration and fieldbus communication capabilities define specification requirements.
Power Distribution maintains the largest installed base. Manufacturing is climbing the fastest in procurement volume.
End User:
Customer type concentration shapes distribution channel structure, with energy utilities and transportation authorities favoring direct OEM contracting over distributor intermediaries.
- Energy:Generation, transmission, and distribution utilities specify relays for protective relaying and load switching. State Grid Corporation in China and Dominion Energy in the United States are consolidating supplier panels for substation equipment.
- Transportation:Railway signaling and electric vehicle charging infrastructure demand high-reliability switching. Dedicated freight corridor projects in India and high-speed rail expansions in Spain are accelerating procurement timelines.
- Telecommunications:Central office power distribution and base station backup systems require compact form factors.
- HVAC:Commercial building automation and residential heat pump installations drive volume demand for standard relay families.
Energy dominates procurement value. Transportation is gaining share fastest among end-user categories.
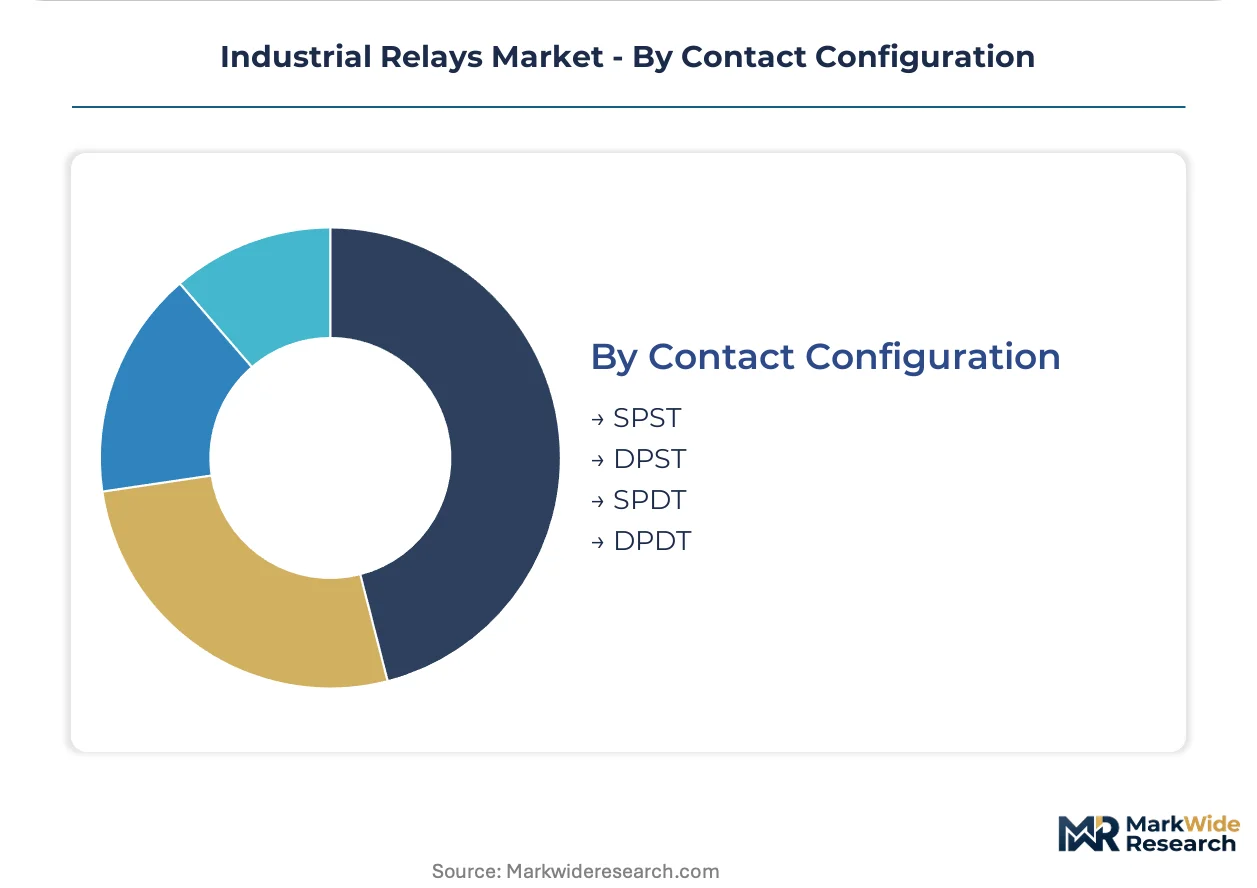
Contact Configuration:
Volume scale and margin structure vary systematically with pole count and throw complexity, with simpler configurations facing the deepest commoditization.
- SPST:Single-pole single-throw designs offer the most economical switching solution for basic on/off control. Residential HVAC and small appliance manufacturers in Mexico and Vietnam specify these for cost-sensitive production.
- DPDT:Double-pole double-throw configurations enable complex circuit routing and motor reversing applications. Machine tool builders in Italy and packaging equipment manufacturers in Germany absorb higher unit costs for wiring simplification.
- DPST:Double-pole single-throw variants serve simultaneous isolation of line and neutral conductors in safety-critical installations.
- SPDT:Single-pole double-throw relays provide changeover functionality for transfer switching and alarm circuits.
SPST commands production volume scale. DPDT is ascending in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for railway signaling and energy infrastructure anchor China's dominant position in industrial relay procurement. Manufacturing automation intensity varies sharply across national industrial bases.
China
Battery pack assembly lines and motor control stations in EV manufacturing are expanding relay volumes. SAMR mandates GB standard certification for relays deployed in State Grid substations and CRRC signaling systems. Shenzhen and Suzhou industrial clusters host expanding domestic production of electromechanical and solid-state relay components for export markets.
Germany
Tier-1 automotive suppliers are compressing relay replacement cycles through 24/7 production schedules. REACH substance restrictions are phasing out hexavalent chromium in contact plating by 2026. Bavaria's automotive assembly corridors and Baden-Württemberg's machine tool builders specify high-reliability relays for factory automation integration.
United States
Grid modernization programs under FERC guidelines are refreshing aging relay populations in utility substations. NEMA ICS 2 requirements shape product acceptance through third-party validation of interrupting capacity. Texas and California energy utilities are consolidating supplier panels for protective relaying equipment.
Japan
Electronics contract manufacturers and plastics molding operations are standardizing on silent-switching solid-state architectures. METI efficiency mandates embed relay performance into broader equipment energy ratings. Nagoya's automotive component cluster and Osaka's industrial electronics base drive precision relay specification.
India
Dedicated freight corridors and smart grid infrastructure under CEA mandates are accelerating procurement for railway signaling and substation relays. Domestic manufacturing incentives under PLI schemes reduce import dependency. Maharashtra and Gujarat industrial corridors host emerging relay assembly operations for transportation and energy applications.
Industrial Relays Market Competitive Environment
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified electrical component conglomerates. The vendor base stratifies across three tiers: integrated automation system suppliers, dedicated relay manufacturers with captive plating facilities, and regional fabricators serving cost-sensitive installations. Two dominant competitive moves are reshaping positioning: direct OEM contracting that bypasses distribution layers, and backward integration into contact material plating to secure supply chain control over silver and copper alloys.
Among diversified electrical conglomerates, Siemens AG and Schneider Electric SE exemplify the system integration archetype, bundling relay products with broader industrial control portfolios to capture single-source accountability contracts. TE Connectivity Ltd. occupies a position within the scale-driven manufacturing tier, leveraging Asian assembly hub footprints to sustain cost competitiveness in high-volume automotive and electronics sector procurement.
| Leading Market Players |
|---|
| TE Connectivity |
| Omron Corporation |
| Panasonic Holdings Corporation |
| Siemens |
| Schneider Electric |
| ABB |
| Fujitsu |
| Crydom |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
Shenzhen and Suzhou industrial clusters anchor global electromechanical and solid-state relay production, concentrating capacity among vertically integrated manufacturers whose captive plating facilities translate into pricing leverage over mid-tier competitors dependent on volatile silver and copper alloy spot markets.
Pricing Analysis
Price spreads between Asian assembly hubs and European qualification centers reach substantial multiples for IEC 61810-certified versus uncertified product families. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification burden and volume commitment. Cost compression in economy-grade electromechanical tiers is intensifying because Mexican and Vietnamese fabricators are absorbing margin erosion to secure automotive HVAC contracts. Residential appliance manufacturers exhibit highest price sensitivity, while aerospace integrators absorbing DO-160 qualification costs show least elasticity.
Supply Chain Analysis
Silver and copper alloy contact materials, silicon carbide power semiconductors, and hermetic sealing ceramics feed relay manufacturing across China, Japan, and Germany. Raw material sourcing draws from Chilean copper concentrate, Australian silver refining, and Taiwanese SiC wafer fabrication. Single-source vulnerability concentrates in high-purity silver plating chemistry governed by REACH substance restrictions. Distribution runs through authorized distributor networks for standard families, with direct OEM contracting displacing intermediaries in high-volume automotive and energy utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation intensity in automotive EV lines and electronics contract manufacturing signals early-cycle expansion, with solid-state relay penetration in thermal management applications representing a durable adoption tailwind.
For Market Incumbents: Pre-empt margin erosion in electromechanical tiers by accelerating backward integration into contact material plating and securing long-term silver alloy offtake agreements. Consolidate supplier panel positions through IEC 61810-1 harmonization investments that raise qualification barriers for emerging Asian competitors.
For New Entrants and Emerging Players: India's dedicated freight corridors and smart grid infrastructure under CEA mandates present underpenetrated demand for railway signaling and substation relays. Target domestic manufacturing incentives under PLI schemes to bypass established import channels, partnering with Maharashtra and Gujarat industrial corridor developers for local assembly qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier panel reduction at Rockwell Automation and Schneider Electric is compressing the viable vendor base from twelve-to-fifteen to four-to-six qualified sources per category. Target mid-cap relay specialists with captive plating facilities in Eastern Europe. Monitor SiC power semiconductor adoption rates in wind turbine inverters as inflection signal for solid-state relay displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Plating | Secures supply chain control over silver and copper alloys against commodity volatility. |
| IEC 61810-1 Harmonization Investment | Accelerates multi-jurisdiction product launches while raising barriers for uncertified competitors. |
| Direct OEM Contracting Expansion | Bypasses distributor layers to capture volume pricing at Siemens and Rockwell Automation panels. |
| Hybrid Relay Architecture Development | Addresses aerospace and precision manufacturing demand for dual-mode switching performance. |
| India PLI Scheme Localization | Positions for CEA-mandated railway signaling and smart grid procurement under domestic manufacturing incentives. |
Study Parameters
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in observable certification and procurement patterns. Plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners provided operational perspective. Secondary sources include IEC 61810 family standards documentation, SAMR GB certification registries, NEMA ICS 2 testing protocols, SEC filings from listed electrical component conglomerates, and customs trade data for relay component flows. Bottom-up demand modeling triangulates against top-down market sizing from automation equipment production forecasts.
Calibration against historical replacement cycle compression in automotive assembly and electronics manufacturing validates growth assumptions across the projection horizon. Segmentation dimensions span product architecture, application environment, end-user concentration, and contact configuration complexity. CAGRs derive from installed base refresh rates, penetration modeling for solid-state alternatives, and regional industrial automation intensity indices. Forecast inputs incorporate silicon carbide power semiconductor adoption curves and REACH substance restriction compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic producers or accelerated SiC cost reduction would shift outcomes. Cross-checking against FERC grid modernization expenditure disclosures and CEA smart grid implementation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Passive Attenuator Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Switch Diode Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Breadboards Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Electronic Wipe Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Safety Relay Market