
 High Density Interconnect (HDI) PCB Market | 2026-2036
High Density Interconnect (HDI) PCB Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Interconnect (HDI) PCB Market Intelligence
The distinction between high-end HDI and substrate-like PCBs (SLPs) is collapsing as manufacturers push for finer line and space specifications. Unimicron Technology Corp. leverages its scale in Taiwan to serve high-volume smartphone clients. In the United States, TTM Technologies, Inc. specializes in complex boards for aerospace and defense applications. Japan's Ibiden Co., Ltd. differentiates through its leadership in advanced packaging substrates and build-up materials.
High Density Interconnect (HDI) Printed Circuit Boards are a class of PCBs featuring higher wiring density per unit area than conventional boards. They utilize microvias, with diameters often under 150 microns, to enable component miniaturization in high-performance electronics. Within end-user segments, consumer electronics represents the largest volume, while the automotive sector shows rapid adoption. Rigid-flex HDI boards command higher margins due to manufacturing complexity compared to standard rigid HDI.
Regulatory frameworks like the EU's RoHS and REACH directives dictate material use, restricting lead and other hazardous substances in PCB manufacturing. Conformance with IPC standards, such as IPC-2226 for HDI design, ensures reliability for products sold across the United States, Europe, and Asia. Future investment decisions for fabricators hinge on balancing the capital cost of laser drilling for smaller microvias against performance demands from next-generation hardware.
Market Dynamics
The central force shaping the market is the technological convergence between high-end HDI and substrate-like PCBs (SLPs). This is driven by relentless demands from consumer electronics and automotive sectors for greater circuit density and component miniaturization, pushing fabricators toward finer specifications.
Growth Catalysts
- Advanced Microvias:The adoption of microvias with diameters under 150 microns enables higher interconnect density, a critical requirement for component miniaturization in high-performance smartphones and wearable devices.
- Automotive Sector Demand:Surging requirements from the automotive industry for advanced driver-assistance systems (ADAS) and in-cabin infotainment systems are compelling the use of complex, high-reliability HDI boards.
- Asian Supply Chain Maturity:A deeply integrated and mature electronics supply chain, particularly concentrated in Taiwan and China, provides the scale and efficiency necessary for high-volume HDI manufacturing.
Market Restraints
- High Capital Expenditure:The significant investment required for advanced laser drilling and imaging equipment to produce finer lines and smaller microvias creates a high barrier to entry and expansion for smaller fabricators.
- Supply Chain Concentration:An over-reliance on manufacturing capacity located in Taiwan and China exposes the global supply chain to geopolitical tensions, trade policy shifts, and potential logistical disruptions.
- Regulatory Compliance Costs:Adherence to environmental regulations like the EU's RoHS and REACH directives, which restrict hazardous materials, necessitates investment in alternative materials and processes, increasing production costs.
Strategic Opportunities
- Medical Device Miniaturization:The growing field of connected medical devices, including patient monitoring wearables and implantable electronics, presents a significant opportunity for high-margin, high-reliability rigid-flex HDI boards.
- Aerospace and Defense Modernization:Demand for complex rigid-flex HDI boards is increasing for avionics, military communications, and satellite systems, where space, weight, and reliability are critical performance parameters. *Advanced Packaging Integration: The convergence of HDI with advanced packaging substrates offers an opportunity for fabricators to move up the value chain, providing integrated solutions that combine board fabrication and semiconductor packaging.
Industry Challenges
- Capital Allocation Dilemma:Fabricators face the challenge of balancing massive capital outlays for next-generation laser drilling equipment against the volatile demand cycles of the consumer electronics industry.
- IPC Standard Adherence:Maintaining consistent quality and reliability in conformance with IPC standards, such as IPC-2226 for HDI design, across a geographically dispersed and multi-tiered supply chain is a persistent operational hurdle.
- Engineering Talent Scarcity:A shortage of skilled design and process engineers with expertise in ultra-fine pitch and advanced build-up technologies hinders the ability of firms to execute on next-generation product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Interconnect (HDI) PCB Market |
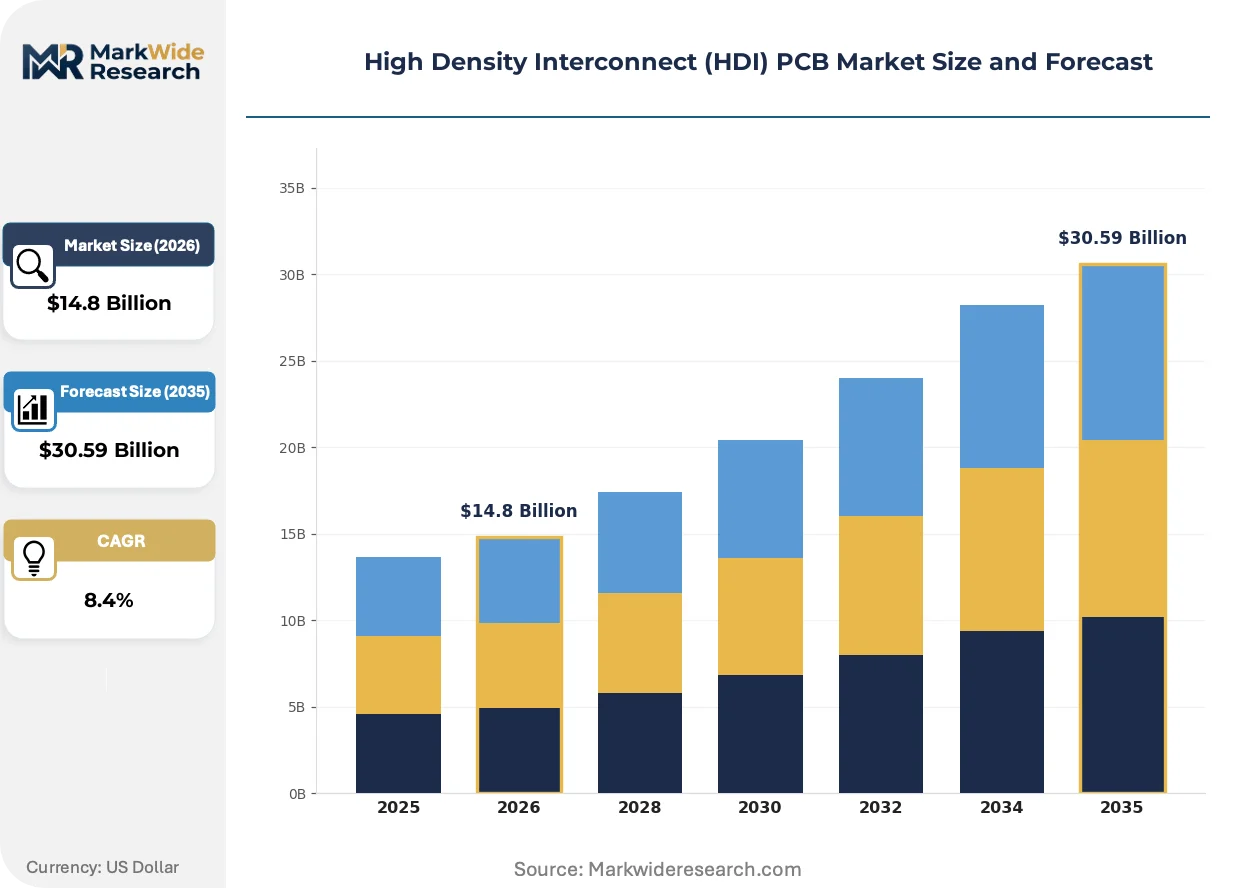
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Flexible, Rigid-Flex, Multilayer End User: Consumer Electronics, Automotive, Telecommunications, Medical Devices Technology: Laser Technology, Imaging Technology, HF Systems, Microvias Application: High-Frequency Circuits, Portable Devices, Aerospace Electronics, IoT Devices |
| Companies Covered | Ibiden Co., Ltd., Compeq Manufacturing Co., Ltd., TTM Technologies, Inc., Tripod Technology Corporation, Meiko Electronics Co., Ltd., Unimicron Technology Corp., Zhen Ding Technology Holding Limited, NCAB Group AB, AT & S Austria Technologie & Systemtechnik Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Interconnect (HDI) PCB Market Strategic Shifts & Innovations
Technological progression is defined by the industry's push towards finer line and space specifications, effectively blurring the distinction between traditional HDI and more advanced substrate-like PCBs. This evolution is a direct response to the form factor and performance demands of next-generation hardware.
Advanced microvia formation using laser drilling is a key enabling technology. These features, often with diameters below 150 microns, permit a higher density of electrical connections on the board surface. The consumer electronics segment, particularly for flagship smartphones, is the fastest adopter of this capability. This technology is miniaturizing the board's overall size, which allows for larger batteries or additional components within a fixed device footprint.
Material use and manufacturing processes are heavily influenced by global environmental regulations. The EU's Restriction of Hazardous Substances (RoHS) directive, for example, strictly limits the use of lead and other specified materials in electronics sold within Europe. This forces fabricators worldwide to qualify and transition to lead-free and halogen-free material sets. The consumer and automotive electronics segments are most impacted, requiring extensive testing to ensure long-term reliability with these new materials.
A notable shift in buyer behavior is the move toward deeper co-design partnerships between OEMs and HDI fabricators. Traditional transactional purchasing is being replaced by collaborative models, especially for complex products in the aerospace and defense sectors. In this model, OEM engineers work directly with fabricator teams during the initial design phase to optimize layout, material selection, and manufacturability. This collaborative approach is most visible in North American and European defense programs.
High Density Interconnect (HDI) PCB Market Segmentation
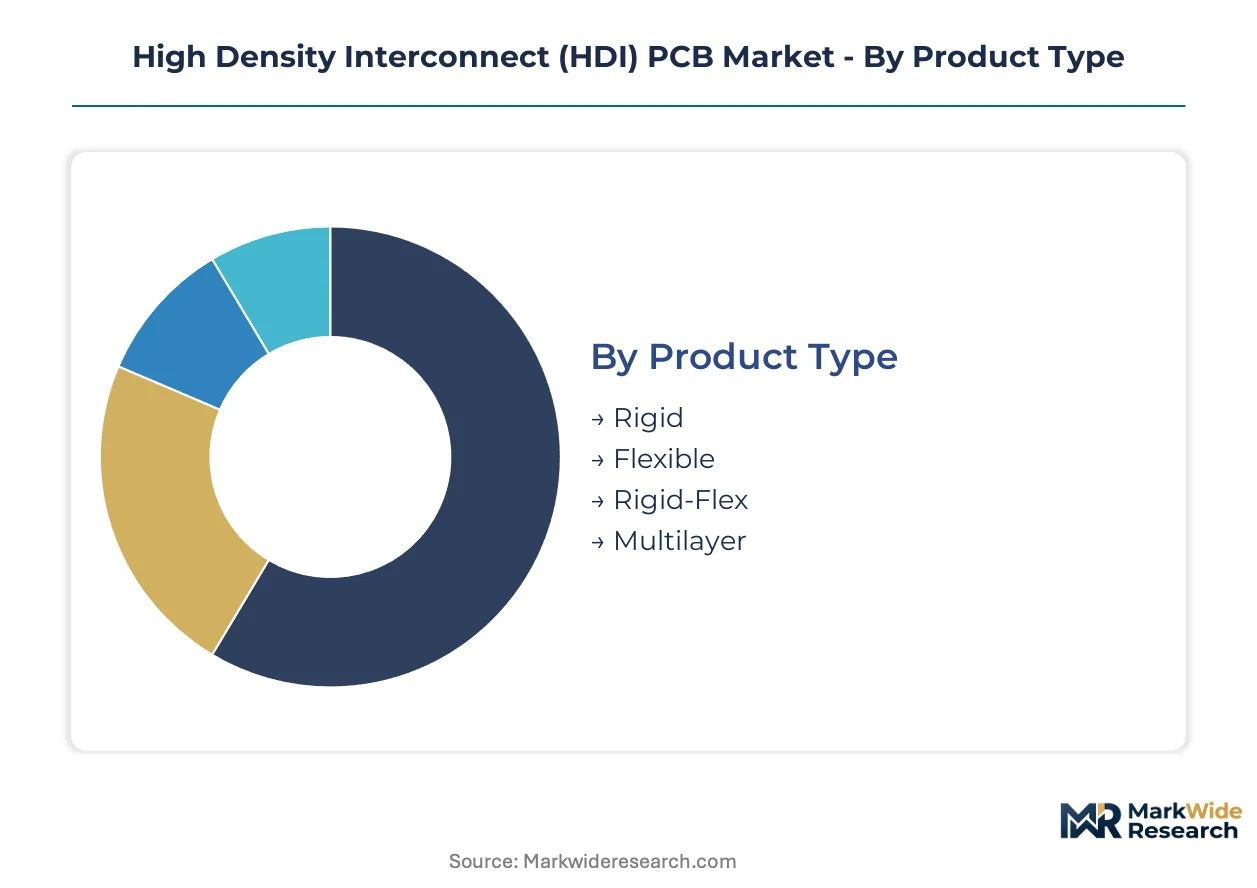
The High Density Interconnect (HDI) PCB market is analyzed across key dimensions, reflecting the diverse technical requirements and end-user demands for advanced circuit boards. Each segment represents distinct performance characteristics and market dynamics, influencing fabrication processes and material selection. Understanding these delineations is crucial for identifying areas of growth and competitive differentiation.
Product Type:
Substitution pressure is most pronounced for standard rigid PCBs, as manufacturers continually seek more compact and flexible solutions for next-generation devices.
- Rigid-Flex:These boards integrate rigid and flexible sections, enabling three-dimensional circuit designs and dynamic bending capabilities. Demand concentrates in medical devices and aerospace applications, where space constraints and high reliability are paramount.
- Flexible:Flexible PCBs are constructed on pliable substrates, allowing for dynamic bending and conforming to irregular shapes. Consumer electronics, especially wearable technology, drive demand for these lightweight and space-saving interconnect solutions.
- Rigid:Rigid PCBs utilize inflexible substrates, providing a stable platform for components in a wide array of electronic devices.
- Multilayer:Multilayer PCBs feature multiple conductive layers separated by insulating materials, enabling high circuit density for complex digital systems.
Rigid PCBs anchor the foundational volume base, while Rigid-Flex boards gain share at the steepest rate, driven by miniaturization trends.
End User:
The varied performance demands across end-user sectors dictate the specific HDI PCB configurations required, with automotive and medical devices exhibiting the most stringent reliability needs.
- Consumer Electronics:This segment includes smartphones, tablets, and wearable devices, requiring ultra-compact and cost-effective HDI solutions. Asia-Pacific manufacturing hubs drive high-volume production for these devices, emphasizing miniaturization and advanced microvias.
- Automotive:Automotive applications encompass ADAS, infotainment systems, and engine control units, demanding high-reliability and extended temperature range HDI boards. European and North American automotive OEMs require robust HDI designs to meet stringent safety and functional standards.
- Telecommunications:Telecommunications infrastructure, including 5G base stations and network equipment, relies on HDI PCBs for high-speed signal integrity.
- Medical Devices:Medical devices, such as diagnostic equipment and implantables, require highly reliable and biocompatible HDI boards for critical functions.
High-volume demand from consumer electronics contrasts with the specialized, high-reliability requirements of medical devices, each shaping distinct supply chain approaches.
Technology:
Capital intensity varies significantly across HDI PCB technologies, with advanced laser drilling systems representing a substantial investment for fabricators.
- Laser Technology:Laser drilling and ablation are critical for creating microvias with diameters often below 150 microns, enabling higher circuit density. Investment in advanced CO2 and UV lasers is concentrated in leading Asian manufacturing facilities to meet next-generation specifications.
- Microvias:Microvias are small-diameter plated holes connecting layers in an HDI PCB, significantly increasing routing density and reducing board size. Their widespread adoption in smartphones and automotive ADAS systems drives continuous innovation in formation and reliability.
- Imaging Technology:Advanced imaging systems are essential for precise pattern definition and alignment during the HDI PCB fabrication process.
- HF Systems:High-frequency (HF) systems refer to specialized materials and design techniques used for high-speed signal transmission in HDI boards.
The evolution of laser technology directly underpins the capabilities enabled by advanced microvias, pushing the boundaries of miniaturization.
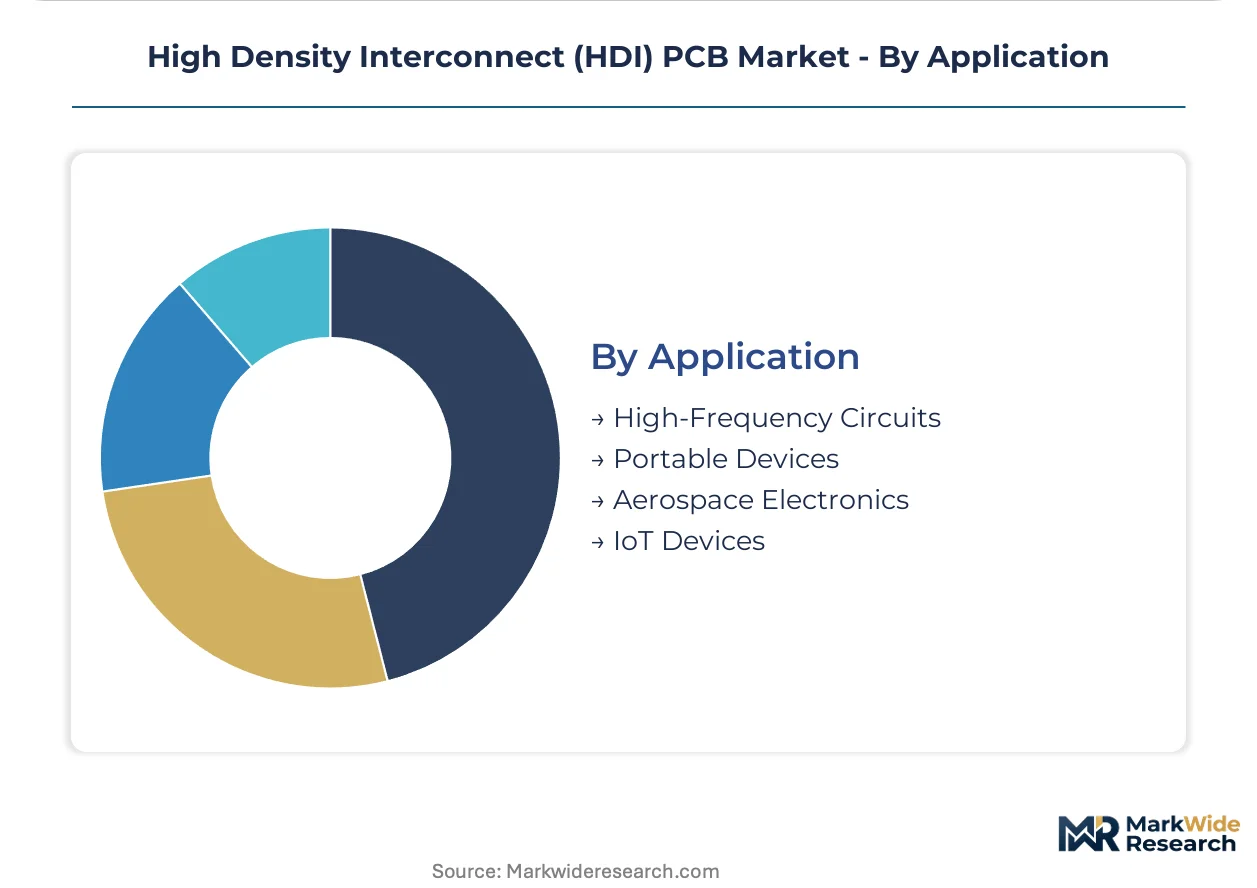
Application:
Performance criticality defines the application segments, with aerospace electronics demanding extreme reliability and IoT devices prioritizing cost-effectiveness and compact form factors.
- Portable Devices:This segment includes consumer electronics like smartphones, wearables, and digital cameras, which require compact and lightweight HDI solutions. The demand for thinner, smaller form factors in devices sold across global markets drives rapid innovation in HDI design.
- Aerospace Electronics:Aerospace applications involve avionics, control systems, and communication modules, necessitating HDI boards with exceptional reliability and environmental robustness. North American and European defense programs require HDI solutions that withstand extreme temperatures and vibrations.
- High-Frequency Circuits:High-frequency circuits, critical for 5G and radar systems, utilize HDI to maintain signal integrity and minimize latency.
- IoT Devices:IoT devices, ranging from smart home sensors to industrial monitors, leverage HDI for compact size and efficient power management.
While portable devices drive significant volume demand, aerospace electronics represents a high-value, specialized niche requiring stringent HDI performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan and China drive significant HDI PCB exports, supplying critical components to global electronics assembly operations. This established trade corridor underscores Asia's central role in advanced circuit board production. Diverse regional demands shape specific product requirements, from high-volume consumer devices to specialized aerospace systems.
Taiwan
Taiwan remains a central hub for high-volume HDI PCB production, particularly for smartphone and advanced packaging applications. Taiwan's Industrial Technology Research Institute (ITRI) actively supports R&D initiatives in advanced manufacturing processes. The Hsinchu Science Park concentrates a critical mass of semiconductor and PCB innovation, fostering technological leadership.
China
The People's Republic of China exhibits immense demand for HDI boards, driven by its vast consumer electronics and automotive sectors. China's dual carbon goals influence green manufacturing processes and material selection for PCB fabricators. Shenzhen's extensive electronics ecosystem drives high-volume HDI fabrication and supports rapid product cycles.
United States
United States demand for HDI PCBs stems from its robust aerospace and defense industries, alongside high-reliability medical devices. The US FAA ensures stringent quality and reliability for avionics-grade PCBs used in critical systems. Silicon Valley and other defense industry clusters demand advanced HDI solutions for complex electronic systems.
Germany
Germany's automotive sector, particularly for advanced driver-assistance systems (ADAS) and industrial automation, requires sophisticated HDI boards. Germany's KBA (Federal Motor Transport Authority) oversees automotive component quality and safety standards. Southern Germany's automotive manufacturing hubs drive demand for complex and robust HDI designs.
Japan
Japan's market for HDI PCBs is characterized by strong demand for advanced packaging substrates and high-end consumer electronics. Japan's METI (Ministry of Economy, Trade and Industry) promotes the development of advanced manufacturing technologies. The Kansai region's electronics firms lead in specialized HDI materials and high-density interconnect solutions.
High Density Interconnect (HDI) PCB Market Key Industry Players
Listed leaders compete with private specialists across scale and technological complexity within the HDI PCB market. The industry exhibits consolidation among top-tier manufacturers serving high-volume segments. Simultaneously, a fragmented landscape exists for specialized applications requiring unique technical capabilities. Key strategic archetypes include global volume producers, regional high-mix/low-volume providers, and niche players focusing on extreme reliability. Firms engage in significant capacity expansion and strategic partnerships to secure supply chains and advance technology.
Specialists in advanced HDI fabrication include Taiwan-based Unimicron Technology Corp., which exemplifies the archetype of a high-volume manufacturer for consumer electronics clients. United States-headquartered TTM Technologies, Inc. occupies a position among providers of complex boards, particularly for high-reliability aerospace and defense applications. Japan's Ibiden Co., Ltd. represents a leader in advanced packaging substrates, differentiating through its expertise in material science and advanced build-up technologies. These firms collectively demonstrate the diverse strategic approaches required to succeed across various segments of the HDI PCB market.
| Leading Market Players |
|---|
| Ibiden Co., Ltd. |
| Compeq Manufacturing Co., Ltd. |
| TTM Technologies, Inc. |
| Tripod Technology Corporation |
| Meiko Electronics Co., Ltd. |
| Unimicron Technology Corp. |
| Zhen Ding Technology Holding Limited |
| NCAB Group AB |
| AT & S Austria Technologie & Systemtechnik Aktiengesellschaft |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts, particularly for high-volume consumer electronics and specialized aerospace applications, lock in both supply access and price visibility for HDI PCB fabricators and their OEM clients.
Pricing Analysis
Next-generation HDI boards, featuring sub-100 micron microvias, command a premium over current-generation products due to higher capital expenditure and material costs. Pricing for HDI PCBs is predominantly contract-based, reflecting long-term supply agreements between fabricators and large original equipment manufacturers. Price differentiation stems from customization levels, adherence to stringent IPC-2226 standards, and the volume scale of orders. Pricing pressure in the consumer electronics segment stems from volatile demand cycles, while medical devices exhibit lower price sensitivity due to critical reliability requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume consumer electronics HDI boards, while strategic stockpiling is common for critical aerospace and defense components. Geographic supply concentration for HDI PCBs centers heavily in Taiwan and China, which possess mature electronics manufacturing ecosystems. The industry draws from key raw material dependencies including specialized copper foils, advanced resins, and laser drilling equipment. Geopolitical tensions and trade policy shifts represent a structural risk to this concentrated supply chain. Distribution runs through direct sales to OEMs and via electronic manufacturing services (EMS) providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a buyer-power shift story, driven by the consolidation of large consumer electronics OEMs demanding high-volume, cost-effective HDI solutions.
For Market Incumbents: Shield existing market share by aggressively investing in advanced laser drilling and imaging technologies to meet next-generation specifications. The threat of substrate-like PCBs displacing high-end HDI necessitates continuous R&D in advanced packaging substrates. Incumbents should leverage their scale to secure long-term material supply agreements and deepen vertical integration into critical material production.
For New Entrants and Emerging Players: Anchor in high-margin, specialized niches like medical devices and aerospace electronics, where reliability and performance outweigh cost considerations. The most penetrable segment for new entrants involves complex rigid-flex HDI boards for industrial IoT applications. A strong go-to-market angle involves offering deep co-design partnerships with OEMs, providing tailored solutions from the initial concept phase.
For Investors and Strategic Acquirers: Capital is best deployed toward firms with proven expertise in advanced packaging integration and proprietary build-up material science. The long-term viability of the HDI PCB market, spanning the next 5-10 years, remains strong due to continued miniaturization trends across electronics. A key signal to watch as an inflection indicator is the widespread adoption rate of microvias with diameters below 50 microns in high-volume applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Microvia R&D | Investing in sub-50 micron microvia technology enables higher circuit densities for next-generation smartphones. |
| Rigid-Flex Capacity Expansion | Increasing capacity for rigid-flex HDI boards addresses the growing demand from medical devices and wearable electronics. |
| Strategic Partnerships | Collaborating with automotive OEMs ensures early design-in and long-term supply for ADAS and infotainment systems. |
| Green Material Sourcing | Prioritizing lead-free and halogen-free materials ensures compliance with EU RoHS and REACH directives. |
| Advanced Packaging Integration | Moving up the value chain by combining PCB fabrication with semiconductor packaging creates integrated solutions. |
Research Approach
Desk research of IPC standards, company annual reports, and regulatory filings preceded structured interviews with PCB fabricators, material suppliers, automotive OEM engineers, and medical device procurement specialists. This approach combined primary insights with secondary validation to ensure a robust data foundation. Bottom-up and top-down triangulation methods were applied to reconcile market size estimates and growth projections.
Variance decomposition analysis informed the forecast framework across the projection horizon. The analysis modeled market segments by product type, end user, technology, application, and regional manufacturing capacity. Compound annual growth rates were derived from historical data trends and projected technological adoption curves, factoring in industry-specific inputs like ADAS penetration rates and smartphone miniaturization trends.
Material uncertainties — including geopolitical shifts, raw material supply disruptions, and rapid technological obsolescence — sit outside the modeled envelope, reflecting inherent market volatility. Forecasts reflect assumptions documented through extensive primary and secondary research. Practitioners should keep alternative scenarios live as trade policy changes and component availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coin Battery Holder Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Impulse Relays Market
Electronic Components
Audio Transistors Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Distribution Components Market
Electronic Components
Encoder Market
Electronic Components
Global Capacitor Market
Electronic Components
Electronic Speed Controllers Market