
 Audio Amplifier Market | 2026-2036
Audio Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Amplifier Market Analysis
CE marking under the EU Radio Equipment Directive is reorganizing which amplifier manufacturers can access European distribution channels. Texas Instruments leverages its integrated analog portfolio to sustain design-in relationships across automotive audio subsystems. Infineon Technologies anchors its position through silicon carbide and gallium nitride expertise in high-efficiency Class-D architectures. Yamaha Corporation differentiates through vertical control over professional audio end markets, from transducer to finished system.
An audio amplifier is an electronic device that increases the amplitude of electrical audio signals to drive loudspeakers or headphones, typically operating across frequency ranges from 20 Hz to 20 kHz with total harmonic distortion below 1% at rated output. Its primary purpose is to deliver sufficient current and voltage gain to reproduce source material at target sound pressure levels while preserving signal fidelity. Class-D technology leads in unit volume due to thermal efficiency advantages in portable and automotive applications, while tube amplifiers occupy premium segments in musical instruments and high-fidelity home audio where harmonic character constitutes product value. Bluetooth-enabled wireless amplifiers represent the fastest-growing technology segment as consumers abandon wired interconnects in home audio systems.
FCC Part 15 emissions limits govern wireless amplifier certification in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in printed circuit board assemblies and solder joints. These regulatory layers elevate compliance costs for smaller manufacturers but create margin pools for firms with established certification infrastructure and materials science capabilities. Stakeholders must monitor convergence between automotive functional safety standards and consumer audio reliability expectations as amplifier modules migrate into safety-critical vehicle domains.
Market Dynamics
Class-D amplifier architectures are compressing thermal management costs while MIIT electromagnetic compatibility mandates in China force redesign cycles across automotive supply chains.
Growth Catalysts
- Automotive cabin entertainment integration:OEMs embed multi-channel amplifier arrays as vehicle interiors transform into immersive audio environments, with KBA certification protocols in Germany validating system reliability.
- REACH and RoHS substance restrictions:European hazardous substance frameworks compel manufacturers to reformulate solder joints and PCB assemblies, creating margin pools for certified suppliers.
- Gallium nitride switching technology:Wide-bandgap semiconductors enable higher efficiency in Class-D topologies, reducing heat sink mass in portable and automotive deployments.
Market Restraints
- Silicon carbide substrate cost volatility:Raw material concentration in limited foundry capacity elevates input costs for high-efficiency amplifier designs.
- FCC Part 15 certification friction:Wireless amplifier variants face extended electromagnetic emissions testing timelines, delaying product launches in the United States.
- Tube amplifier substitution persistence:Vacuum-tube architectures retain preference in musical instrument and premium hi-fi segments where harmonic distortion characteristics constitute product value.
Strategic Opportunities
- Bluetooth-enabled wireless home audio:Consumer abandonment of wired interconnects creates expansion space for integrated amplifier-speaker systems in residential environments.
- EU Green Deal circularity mandates:Repairability and recyclability requirements favor modular amplifier designs with standardized component interfaces.
- Functional safety convergence:Amplifier modules migrating into safety-critical vehicle domains must meet automotive reliability standards, opening premium positioning for qualified suppliers.
Industry Challenges
- Analog-digital mixed-signal design expertise scarcity:Class-D architecture optimization requires specialized talent pools concentrated in Baden-Württemberg electronics clusters and select Asian design centers.
- CE marking documentation burden:EU Radio Equipment Directive compliance costs disproportionately impact smaller manufacturers lacking established certification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Amplifier Market |
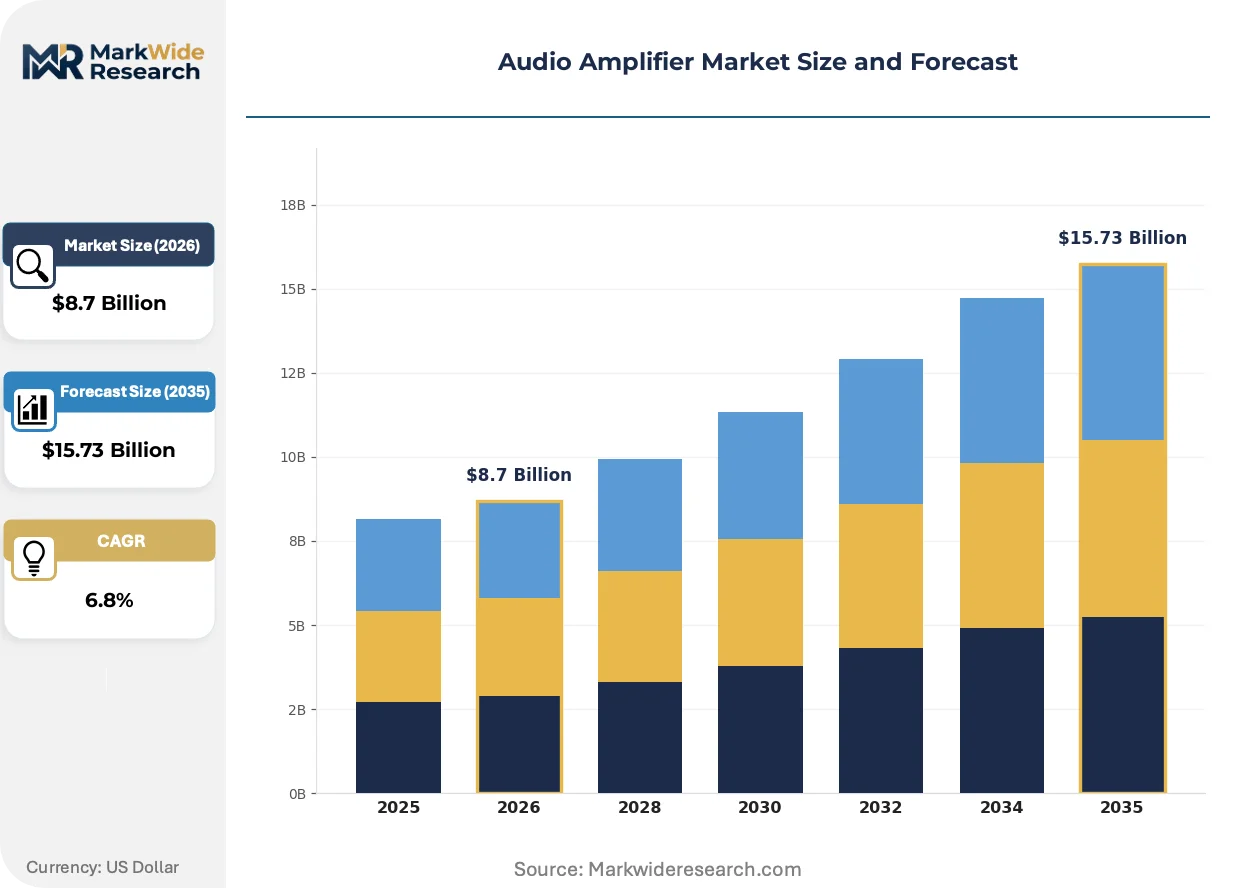
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Tube, Hybrid, Class-D, Operational Technology: Analog, Digital, Bluetooth, Wireless, Multi-Channel Application: Consumer Electronics, Professional Audio, Public Address, Automotive OEMs, Musical Instruments End User: Home Audio Systems, Recording Studios, Event Organizers, Vehicle Manufacturers, Broadcast Stations |
| Companies Covered | STMicroelectronics, ON Semiconductor, Analog Devices, Yamaha Corporation, Qualcomm, Texas Instruments, Cirrus Logic, Sony, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Amplifier Market Emerging Trajectories
Gallium nitride power stages and wireless connectivity protocols are compressing form factors while regulatory frameworks in major economies force materials and design recertification cycles.
GaN-based output stages are miniaturizing switching power supplies in Class-D amplifiers, enabling automotive OEMs to reduce amplifier module volume by half while maintaining thermal performance. Portable audio manufacturers in East Asian supply chains adopt these topologies aggressively. The technology is compressing enclosure sizes and expanding placement flexibility within vehicle cabins and compact consumer devices.
China's MIIT GB electromagnetic compatibility standards are tightening radiated emissions limits for automotive electronics, forcing amplifier manufacturers to redesign filtering networks and shielding architectures. Component suppliers serving East Asian OEMs face recertification costs. The regulatory pressure concentrates sourcing decisions toward manufacturers with pre-validated electromagnetic compliance testing capabilities.
Residential audio buyers increasingly reject wired interconnects in favor of Bluetooth streaming amplifiers, compressing traditional hi-fi distribution channels. Specialty retailers lose volume to direct-to-consumer wireless system brands. This behavioral shift is most pronounced in North American and European home audio markets where smartphone-centric music consumption dominates.
Audio Amplifier Market Segmentation
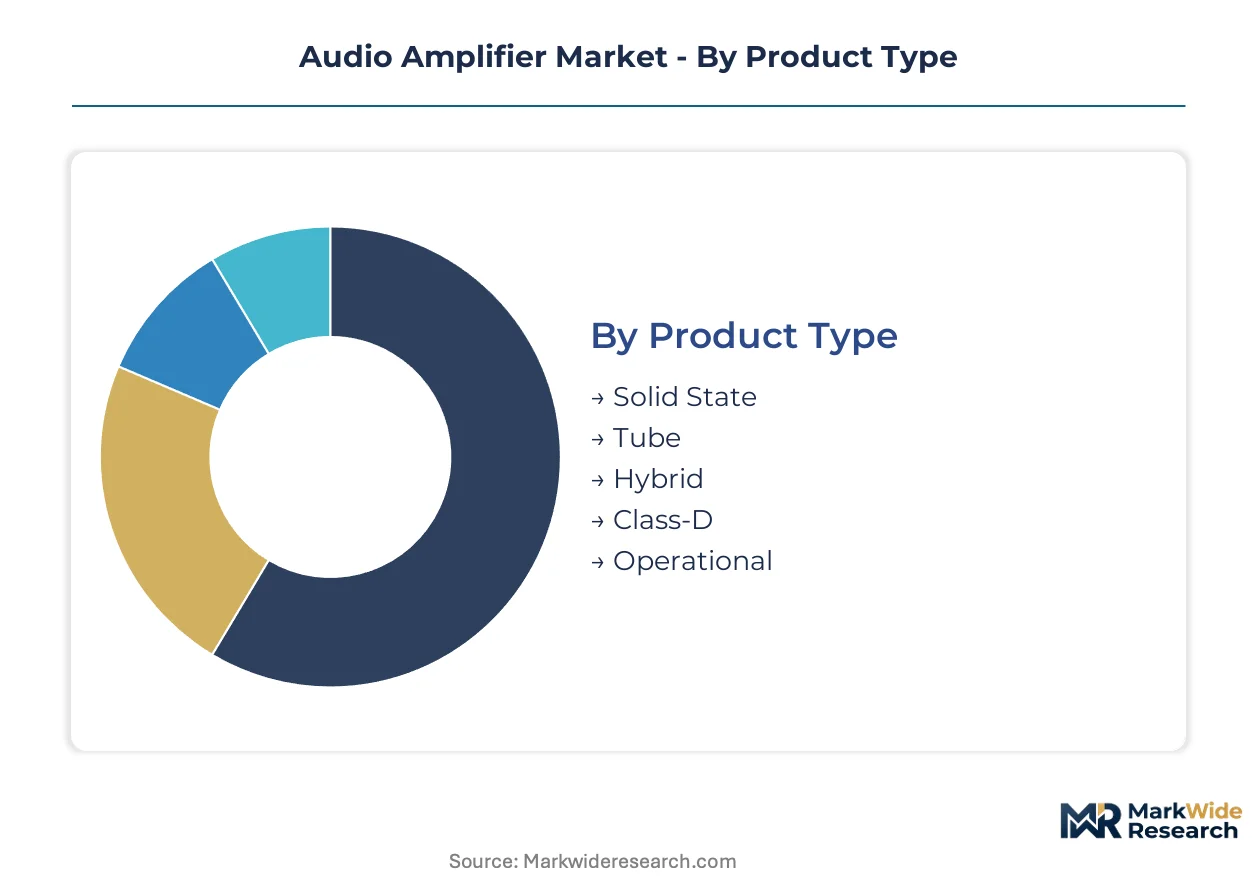
Audio amplifier segmentation reveals distinct procurement channels and design requirements across power technologies, connectivity protocols, and end-use environments. Each dimension carries implications for thermal management, electromagnetic compliance, and channel strategy.
Product Type:
Distribution channels bifurcate between mass-market electronics retailers and specialized pro-audio dealers based on amplification topology.
- Solid State:Transistor-based designs dominate consumer electronics and professional installations where reliability and cost efficiency matter. Demand concentrates in German automotive clusters under KBA certification protocols, where OEMs prioritize thermal stability in multi-channel cabin arrays.
- Tube:Vacuum-tube architectures preserve harmonic distortion characteristics valued in musical instruments and premium home audio. Japan's METI energy efficiency standards create friction for import distribution, limiting channel penetration despite sustained enthusiast demand.
- Hybrid:Combines tube preamplification with solid-state output stages for tonal flexibility in mid-tier recording equipment. China MIIT electromagnetic compatibility testing adds certification overhead for East Asian supply chains.
- Class-D:Switching amplifiers with pulse-width modulation achieve thermal efficiency critical for portable and automotive deployments. Gallium nitride power stages from Baden-Württemberg suppliers enable volume reduction without sacrificing output.
- Operational:Integrated circuit amplifiers serve low-power signal conditioning in broadcast and measurement equipment. REACH substance restrictions in Europe constrain solder joint formulations for PCB-mounted variants.
By volume, Class-D leads. By growth pace, tube designs are climbing fastest among premium audio enthusiasts.
Technology:
Cost tiers separate legacy analog implementations from digitally-controlled architectures with networked connectivity.
- Analog:Continuous signal path architectures persist in professional studios and broadcast chains where latency and conversion artifacts are unacceptable. German recording facilities in Berlin and Hamburg sustain demand for discrete component designs.
- Digital:DSP-based amplification enables programmable crossover networks and room correction algorithms. FCC Part 15 emissions testing in the United States extends certification timelines for products with embedded processors.
- Bluetooth:Integrated wireless streaming modules eliminate interconnect cables in residential installations. Consumer abandonment of wired hi-fi systems is reshaping North American and European distribution toward direct-to-consumer brands.
- Wireless:Proprietary RF protocols support multi-room synchronization and outdoor event coverage. China's MIIT radio frequency allocation rules constrain transmit power for products serving East Asian markets.
- Multi-Channel:Surround and immersive audio configurations drive amplifier count in automotive and home theater applications. Vehicle manufacturers in Stuttgart and Munich specify 12-16 channel arrays for cabin entertainment.
Analog retains margin leadership in professional tiers. Bluetooth-enabled variants are gaining share fastest in residential channels.
Application:
Customer type determines specification intensity, with automotive and professional segments demanding functional safety validation absent in consumer categories.
- Consumer Electronics:Portable speakers, soundbars, and desktop systems prioritize miniaturization and battery efficiency. GaN switching technology from Infineon enables thermal performance in compact enclosures.
- Professional Audio:Touring sound systems and installed venue equipment require touring-grade durability and serviceability. EU Green Deal repairability mandates favor modular designs with standardized component interfaces.
- Public Address:Voice evacuation and emergency notification systems in transportation hubs and stadiums demand 24/7 reliability certification. Germany's KBA vehicle protocols and building codes in Frankfurt and Munich influence specification standards.
- Automotive OEMs:Multi-channel amplifier arrays integrate with head units and active noise cancellation systems. MIIT electromagnetic compatibility standards in China force shielding redesigns for suppliers serving Geely and BYD.
- Musical Instruments:Guitar and bass amplifiers emphasize harmonic character and dynamic response over measured fidelity. Tube substitution persists despite solid-state alternatives from Yamaha and Roland.
Automotive OEMs command highest unit values. Consumer electronics shows steepest expansion trajectory in absolute volume.
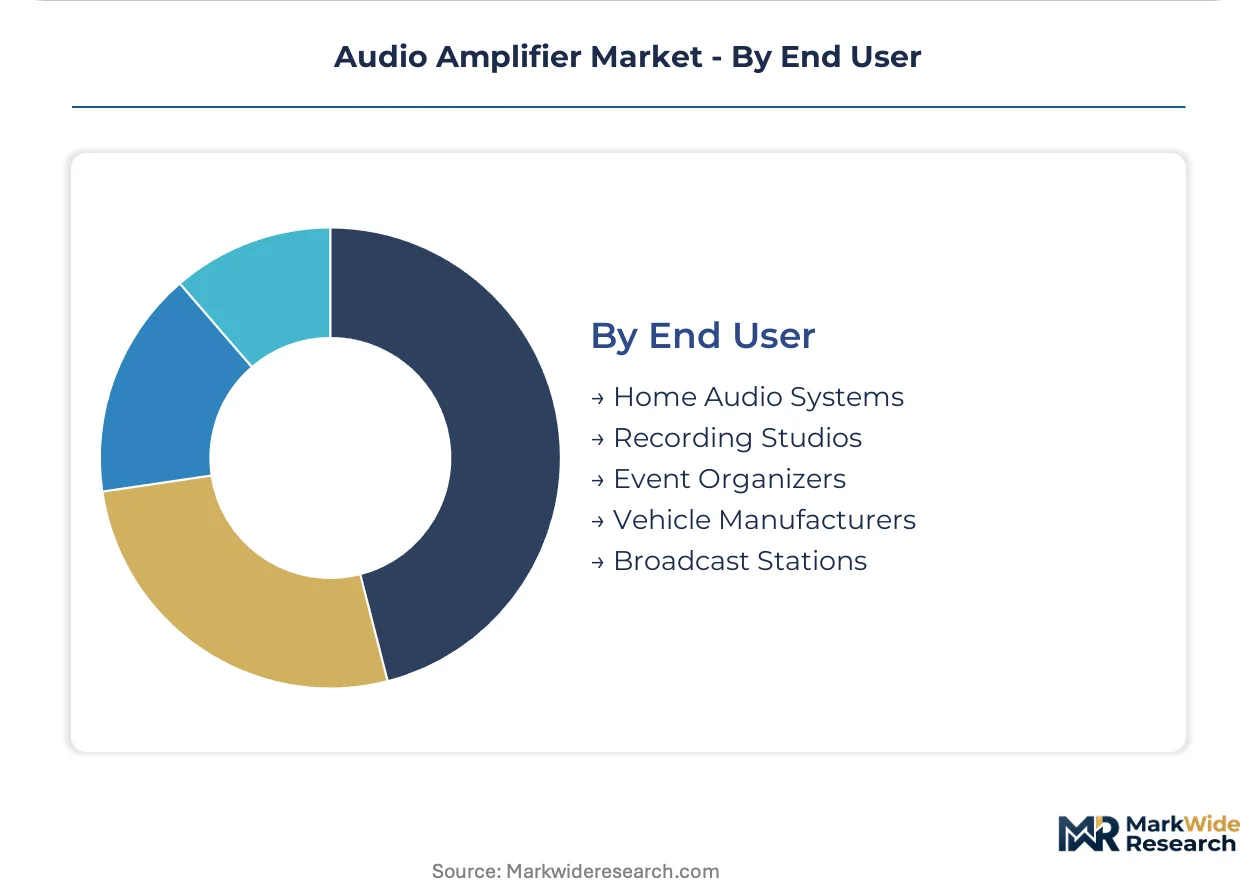
End User:
Volume scale separates residential purchasers from institutional procurement with extended qualification cycles.
- Home Audio Systems:Enthusiast and casual listeners drive wireless amplifier adoption in North American and European markets. Bluetooth streaming displaces wired interconnects in Tokyo and Seoul apartment installations.
- Recording Studios:Commercial facilities in Nashville, London, and Los Angeles specify transparent amplification for critical monitoring. Analog-digital hybrid workflows sustain demand for low-noise discrete designs.
- Event Organizers:Rental companies and production houses prioritize amplifier weight reduction for transport efficiency. Class-D topologies with active power factor correction dominate festival and touring deployments.
- Vehicle Manufacturers:BMW, Mercedes-Benz, and Volkswagen integrate amplifier modules with safety-critical domain controllers. Functional safety convergence with ISO 26262 standards elevates supplier qualification barriers.
- Broadcast Stations:Radio and television transmission facilities require redundant amplification chains with remote monitoring capability. India's TRAI broadcast regulations influence equipment specifications for Prasar Bharati infrastructure.
Vehicle manufacturers lead in revenue per unit. Home audio systems are expanding most quickly as wireless protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and professional audio buyers concentrate procurement in manufacturing clusters with established certification infrastructure. Germany's KBA protocols, China's MIIT standards, and FCC emissions frameworks in the United States reshape sourcing decisions. Component suppliers must validate electromagnetic compliance across multiple jurisdictions simultaneously.
United States
Vehicle manufacturers in Detroit and Austin integrate multi-channel amplifier arrays with active noise cancellation systems. FCC Part 15 emissions testing extends certification timelines for wireless-enabled variants. Nashville recording studios sustain demand for transparent analog amplification in critical monitoring chains.
Germany
BMW and Mercedes-Benz specify 12-16 channel cabin entertainment systems requiring KBA reliability validation. REACH substance restrictions compel solder joint reformulation in PCB assemblies. Baden-Württemberg electronics clusters concentrate Class-D design expertise for automotive thermal management.
China
Geely and BYD force shielding redesigns through MIIT GB electromagnetic compatibility mandates. GB standards tighten radiated emissions limits for automotive electronics. Yangtze River Delta contract manufacturers absorb recertification costs for East Asian supply chain integration.
Japan
Tokyo and Seoul apartment installations accelerate Bluetooth streaming displacement of wired interconnects. METI energy efficiency standards create friction for tube amplifier import distribution. Osaka musical instrument manufacturers preserve vacuum-tube architectures for harmonic character.
South Korea
Seoul Capital Area consumer electronics brands prioritize GaN switching technology for portable enclosure miniaturization. MFDS broadcast regulations influence equipment specifications for terrestrial transmission infrastructure. Busan-Ulsan manufacturing corridors export Class-D modules to global automotive Tier 1s.
Audio Amplifier Market Vendor Landscape
Player mix skews toward diversified semiconductor conglomerates with analog-digital mixed-signal portfolios. Consolidation pressures concentrate design-in relationships around firms with pre-validated electromagnetic compliance capabilities. Two strategic archetypes dominate: integrated component suppliers leveraging silicon carbide and gallium nitride expertise, and vertically controlled audio specialists commanding transducer-to-system value chains. Competitive moves center on strategic partnerships for automotive qualification and geographic expansion into China MIIT-certified supply channels.
Among diversified semiconductor suppliers, Texas Instruments and Infineon Technologies exemplify the integrated portfolio archetype with sustained automotive design-in relationships. Yamaha Corporation occupies a distinct position as a vertically controlled specialist spanning professional audio end markets from component to finished system. STMicroelectronics and ON Semiconductor represent European and North American anchors respectively in high-efficiency Class-D architectures. Qualcomm and Cirrus Logic sit within the connectivity-focused tier where wireless protocol integration determines competitive positioning.
| Leading Market Players |
|---|
| STMicroelectronics |
| ON Semiconductor |
| Analog Devices |
| Yamaha Corporation |
| Qualcomm |
| Texas Instruments |
| Cirrus Logic |
| Sony |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
Ninety-day gallium nitride substrate lead times concentrate pricing power with Baden-Württemberg foundries serving automotive OEMs, while Yangtze River Delta contract manufacturers absorb inventory carrying costs to maintain volume relationships with East Asian consumer electronics brands.
Pricing Analysis
Cost-plus contracts with silicon carbide wafer indexation dominate Class-D amplifier procurement between automotive Tier 1s and semiconductor suppliers. Price differentiation separates KBA-certified automotive modules from consumer-grade variants lacking functional safety validation. Cost compression in Bluetooth-enabled residential amplifiers intensifies as direct-to-consumer brands bypass traditional distribution markups. Vehicle manufacturers exhibit lowest price sensitivity due to reliability qualification barriers, while portable audio OEMs face acute margin pressure from commoditized Class-D controller ICs.
Supply Chain Analysis
Shanghai port congestion elevates inbound logistics costs for gallium nitride substrates sourced from European chemical suppliers serving East Asian packaging facilities. Manufacturing concentrates in China, Germany, and South Korea, with Yangtze River Delta fabs handling consumer electronics volume and Baden-Württemberg clusters anchoring automotive thermal management expertise. Raw material dependencies span silicon carbide wafers, rare earth magnets for output transformers, and RoHS-compliant solder formulations. Single-source vulnerability concentrates in wide-bandgap semiconductor foundry capacity. Distribution runs through authorized component distributors for automotive qualification and direct OEM relationships for high-volume consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward automotive OEMs consolidating amplifier procurement across 12-16 channel cabin entertainment platforms, fragmenting supplier margins despite technical qualification barriers.
For Market Incumbents: Compound design-in relationships through captive gallium nitride process development partnerships with Baden-Württemberg foundries. Deepen backward integration into electromagnetic compliance testing infrastructure to preempt MIIT recertification cycles threatening East Asian revenue streams. Defend against modular wireless amplifier entrants by embedding firmware-lock functionality that complicates aftermarket substitution. For New Entrants and Emerging Players: Lead with GaN-based thermal efficiency narratives targeting Seoul Capital Area portable audio brands seeking enclosure miniaturization. The most penetrable white-space sits in repairable modular amplifiers compliant with EU Green Deal circularity mandates, where incumbents lack standardized component interface roadmaps. Establish direct-to-consumer channels in North American and European residential markets where Bluetooth streaming has already displaced specialty retailer influence. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor conglomerates seeking to divest analog audio IC portfolios with sub-scale automotive traction. Long-term viability favors suppliers with pre-validated KBA and MIIT electromagnetic compliance capabilities that accelerate OEM qualification timelines. The critical inflection signal is consolidation among Yangtze River Delta contract manufacturers absorbing recertification costs that smaller competitors cannot sustain.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Technology Partnership | Baden-Württemberg foundries secure automotive design-in relationships through thermal efficiency roadmaps. |
| MIIT Pre-Certification Infrastructure | East Asian contract manufacturers absorb GB standard compliance costs before competitor qualification cycles. |
| Modular Repairability Platform | EU Green Deal alignment opens institutional procurement channels closed to sealed-unit competitors. |
| Direct-to-Consumer Wireless Launch | Bypass of traditional hi-fi distribution captures margin compression from Bluetooth adoption. |
| Functional Safety Convergence Investment | ISO 26262 qualification barriers protect premium positioning as amplifiers migrate into safety-critical vehicle domains. |
Methodological Framework
The analysis maps Class-D controller ICs, tube amplification subsystems, GaN power stages, and wireless streaming modules, each validated through procurement directors at automotive Tier 1s, OEM platform engineers, professional audio rental company technical managers, and semiconductor field application engineers. Primary interview findings triangulate against customs records for gallium nitride substrate trade flows, MIIT GB standard publication databases, KBA vehicle certification registries, and SEC filings from diversified semiconductor suppliers. Bottom-up bill-of-materials costing for amplifier modules reconciles with top-down revenue aggregation across disclosed automotive electronics segments.
Consistency checks validate volume and value outputs against IHS Markit vehicle production databases, hyperscaler Bluetooth chipset shipment disclosures, and EIA rare earth magnet trade statistics across the projection horizon. Segmentation dimensions modeled include amplification topology, connectivity protocol, end-use environment, and regional regulatory cluster. CAGRs derive from unit shipment trajectories weighted by average selling price erosion curves for mature Class-D architectures and premium capture rates for GaN-enabled automotive deployments.
Forecasts assume regulatory continuity in FCC Part 15 emissions frameworks, REACH substance restrictions, and MIIT electromagnetic compatibility regimes; material policy shifts would require re-modeling. Specific risks include silicon carbide substrate supply disruptions, abrupt automotive functional safety standard elevation, and wireless protocol obsolescence cycles compressing residential product lifespans. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
RAID Controller Card Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Passive Attenuator Market
Electronic Components
Resonators Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Audio DSP Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Speaker Cone Material Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Motherboard Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Stretchable Conductors in Electronics Market