
 Metal Composite Power Inductor Market | 2026-2036
Metal Composite Power Inductor Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Composite Power Inductor Market Foresight
AEC-Q200 qualification is unwinding the competitive landscape toward automotive-grade reliability tiers. TDK Corporation leverages its ferrite and metal composite material science heritage to anchor premium EV powertrain contracts. Bourns Inc. competes through vertical integration into powder core formulation and automated winding. Murata Manufacturing Co., Ltd. differentiates via multilayer co-firing expertise that extends into compact, high-isat inductor designs.
Metal composite power inductors combine alloy powder cores with copper windings to deliver high saturation current, low DC resistance, and stable inductance under thermal stress for switched-mode power supplies. Manufacturers press iron-silicon-aluminum or iron-nickel-molybdenum powders into toroidal or block geometries, then coat particles with insulating layers to suppress eddy current losses at frequencies above one megahertz. Surface mount formats dominate volume shipments into consumer electronics and telecommunications base stations, while through hole configurations retain structural importance in industrial equipment subject to mechanical vibration. DC-DC converter applications command the fastest expansion as datacenter and automotive voltage regulation architectures shift toward higher current density and multiphase topologies.
Automotive OEMs now require AEC-Q200 Rev E compliance alongside IECQ certification for passive components in safety-critical circuits. China's GB standards for NEV electromagnetic compatibility and the EU's F-Gas Regulation on fluorinated greenhouse gases are reshaping material selection and thermal design specifications. Japan's METI energy efficiency benchmarks for industrial equipment further tighten core loss thresholds. Stakeholders must monitor how evolving carbon border adjustments and rare earth supply chain disclosures alter sourcing economics for alloy powder feedstocks.
Market Dynamics
Automotive electrification is compressing product development cycles while simultaneously tightening reliability requirements through AEC-Q200 Rev E qualification mandates. This dual pressure is restructuring supplier relationships toward long-term qualification partnerships rather than transactional component sourcing.
Growth Catalysts
- NEV Electrification Mandates:China's dual carbon goals and GB standards for electromagnetic compatibility are accelerating procurement of low-loss magnetic components for onboard chargers and DC-DC converter modules.
- Datacenter Power Density:Hyperscale facilities are deploying multiphase voltage regulation architectures that demand high saturation current inductors capable of operating above one megahertz switching frequencies.
- Alloy Powder Innovation:Iron-silicon-aluminum and iron-nickel-molybdenum core formulations with engineered insulating coatings are suppressing eddy current losses in compact surface mount packages.
Market Restraints
- Rare Earth Supply Concentration:Alloy powder feedstock sourcing depends on concentrated rare earth processing capacity, exposing manufacturers to carbon border adjustment disclosure requirements and supply chain transparency mandates.
- AEC-Q200 Qualification Burden:Automotive OEMs now require IECQ certification alongside Rev E compliance, extending qualification timelines and freezing out non-specialized suppliers from safety-critical circuits.
- Ferrite Substitution in Consumer Electronics:Cost-sensitive smartphone and tablet manufacturers continue specifying manganese-zinc ferrite inductors where saturation current requirements permit, limiting metal composite penetration in high-volume portable segments.
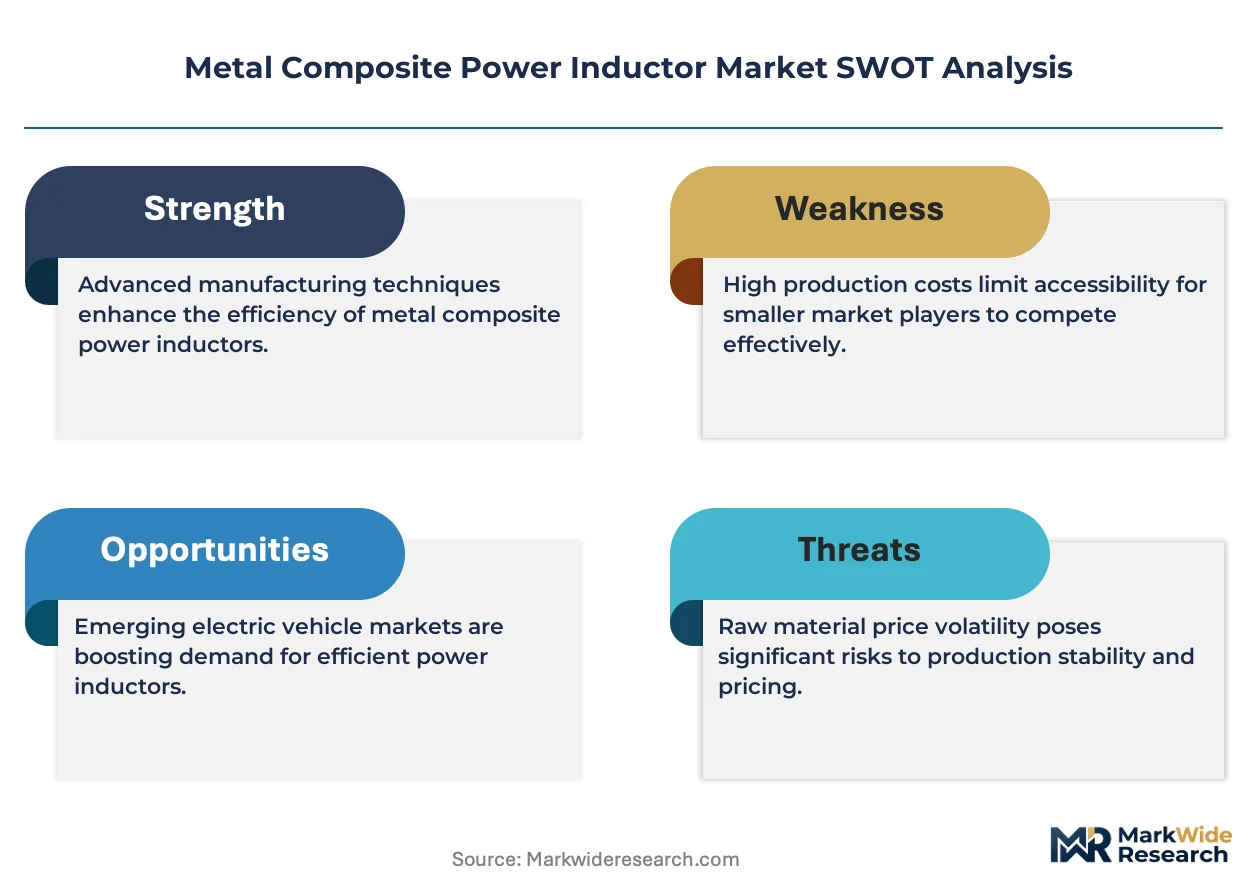
Strategic Opportunities
- Industrial Equipment Efficiency Mandates:Japan's METI energy efficiency benchmarks are tightening core loss thresholds, creating replacement demand for metal composite designs in motor drives and welding equipment.
- EU F-Gas Regulation Alignment:Thermal design specifications are shifting away from fluorinated greenhouse gas-dependent cooling systems, favoring inductor architectures with superior natural convection performance.
- Telecommunications Infrastructure:5G base station deployments and Open RAN architectures are requiring high-isolation power magnetics capable of operating in thermally constrained outdoor enclosures.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Core loss modeling at megahertz frequencies requires expertise in electromagnetic-thermal-mechanical co-simulation that remains concentrated among specialized magnetics engineers.
- Automotive Qualification Timeline Compression:NEV platform launch schedules are demanding AEC-Q200 certification cycles that outpace traditional passive component validation protocols, straining testing infrastructure.
- Legacy DC-DC Architecture Integration:Industrial equipment OEMs face firmware and control loop redesign costs when retrofitting metal composite inductors into existing voltage regulation implementations optimized for ferrite characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Composite Power Inductor Market |
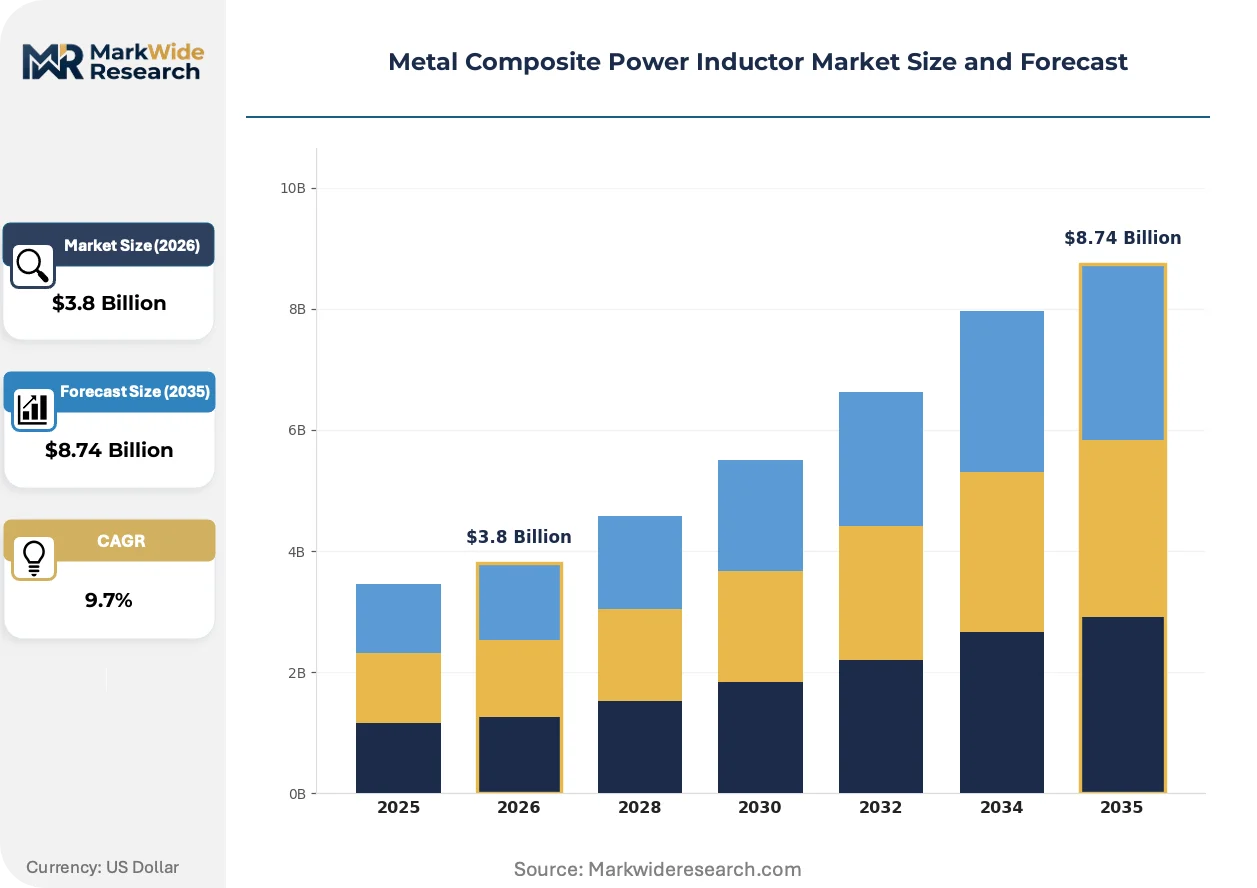
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Mount, Through Hole, Leaded, Unleaded End User: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications Application: Power Supply Units, DC-DC Converters, Voltage Regulators, RF Applications Installation: Automated, Manual, Soldering, Plug-in |
| Companies Covered | Bourns Inc., SAMSUNG ELECTRO-MECHANICS, TDK Corporation, KEMET, SUMIDA CORPORATION, Murata Manufacturing Co., Ltd., TAIYO YUDEN Co., Ltd., Abracon LLC, Vishay Intertechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Composite Power Inductor Market Shifts & Advancements
Material science advances in alloy powder insulation and winding automation are converging with automotive reliability mandates to redefine competitive differentiation. Manufacturers are racing to bridge the gap between laboratory core loss performance and mass-production consistency.
Sendust alloy cores with dual-layer organic-inorganic hybrid coatings are displacing conventional epoxy-insulated iron powder in EV onboard charger applications. Tier 1 automotive suppliers are qualifying these designs for 150°C continuous operation with less than 3% inductance drop at saturation. This displacement is compressing the addressable market for traditional iron powder inductors in powertrain applications above 11 kilowatts.
China's GB/T standards for NEV electromagnetic compatibility are forcing redesigns of DC-DC converter magnetics to suppress conducted emissions in the 150 kilohertz to 30 megahertz band. Domestic suppliers are investing in automated winding equipment to achieve the dimensional consistency required for repeatable parasitic capacitance control. South Korean and Japanese manufacturers with established East Asian production footprints are responding by localizing powder core pressing operations within China's bonded manufacturing zones.
Datacenter operators are consolidating power component procurement through direct relationships with magnetics specialists rather than distributor-mediated sourcing. This channel compression is most visible among hyperscale cloud providers in the United States and Germany, who are negotiating multi-year supply agreements contingent on demonstrated mean time between failures above one million hours. Component vendors are responding with dedicated field application engineering teams embedded at customer design centers.
Metal Composite Power Inductor Market Segmentation
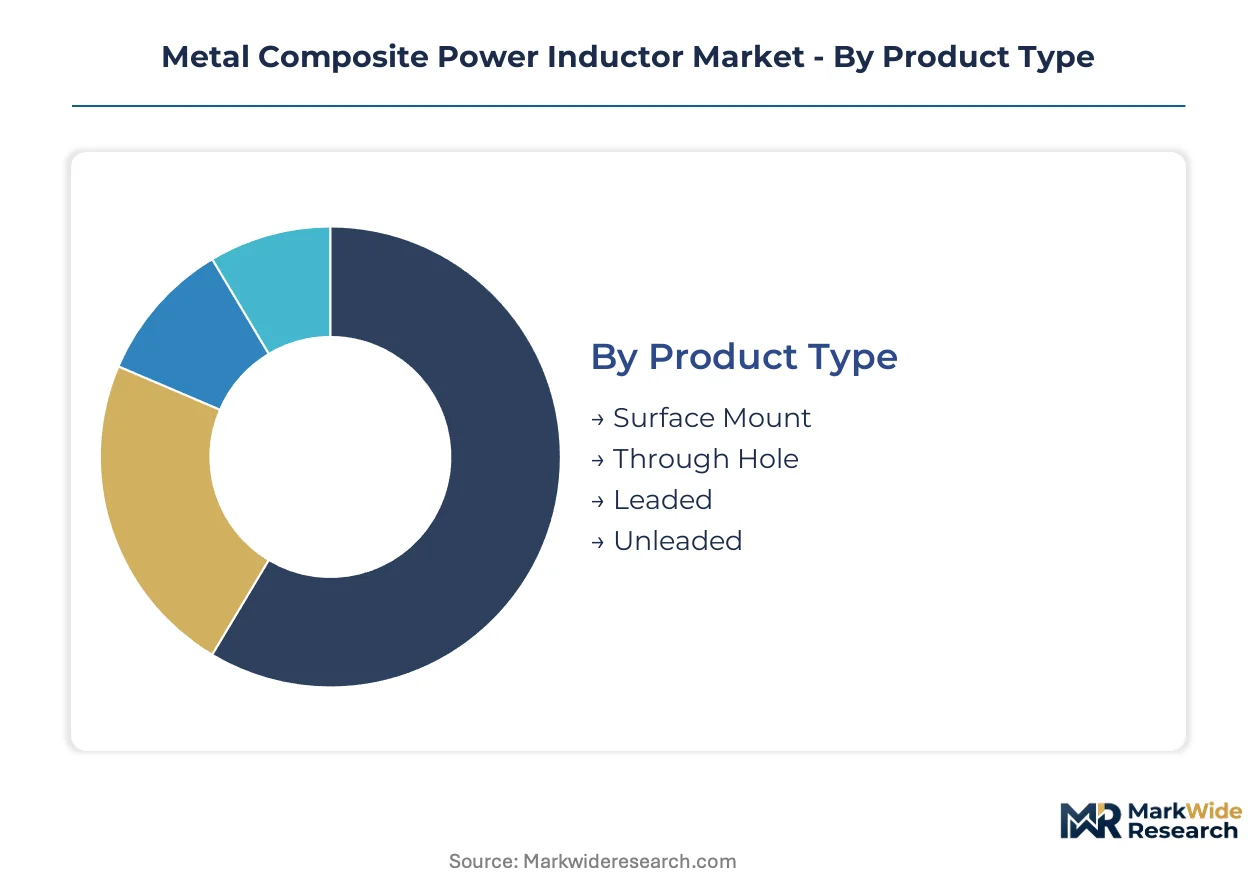
Metal composite power inductor segmentation reveals how substitution pressures from ferrite alternatives and mounting automation requirements reshape procurement priorities across customer tiers. Understanding these fault lines exposes where suppliers must defend specification premiums and where cost engineering dominates.
Product Type:
Surface mount formats face the most acute substitution threat from multilayer ferrite chip inductors in consumer electronics, while through hole configurations maintain structural insulation against displacement due to mechanical reliability requirements.
- Surface Mount:Compact rectangular packages with alloy powder cores and copper terminations suit high-density PCB layouts in smartphones and base stations. China's GB standards for NEV electromagnetic compatibility are accelerating automated placement adoption in onboard charger modules as domestic manufacturers invest in precision winding equipment.
- Through Hole:Radial or axial leaded designs with toroidal or block cores withstand mechanical vibration in industrial motor drives and welding equipment. Japan's METI energy efficiency benchmarks are tightening core loss thresholds, creating replacement demand for metal composite designs that ferrite cannot satisfy.
- Leaded:Axial-leaded configurations with epoxy-coated cores serve legacy telecommunications infrastructure and military avionics where soldering reworkability matters.
- Unleaded:Press-fit and compliant-pin formats eliminate solder thermal exposure for automotive powertrain modules requiring AEC-Q200 Rev E qualification.
Surface mount anchors the volume base while unleaded gains share at the steepest rate.
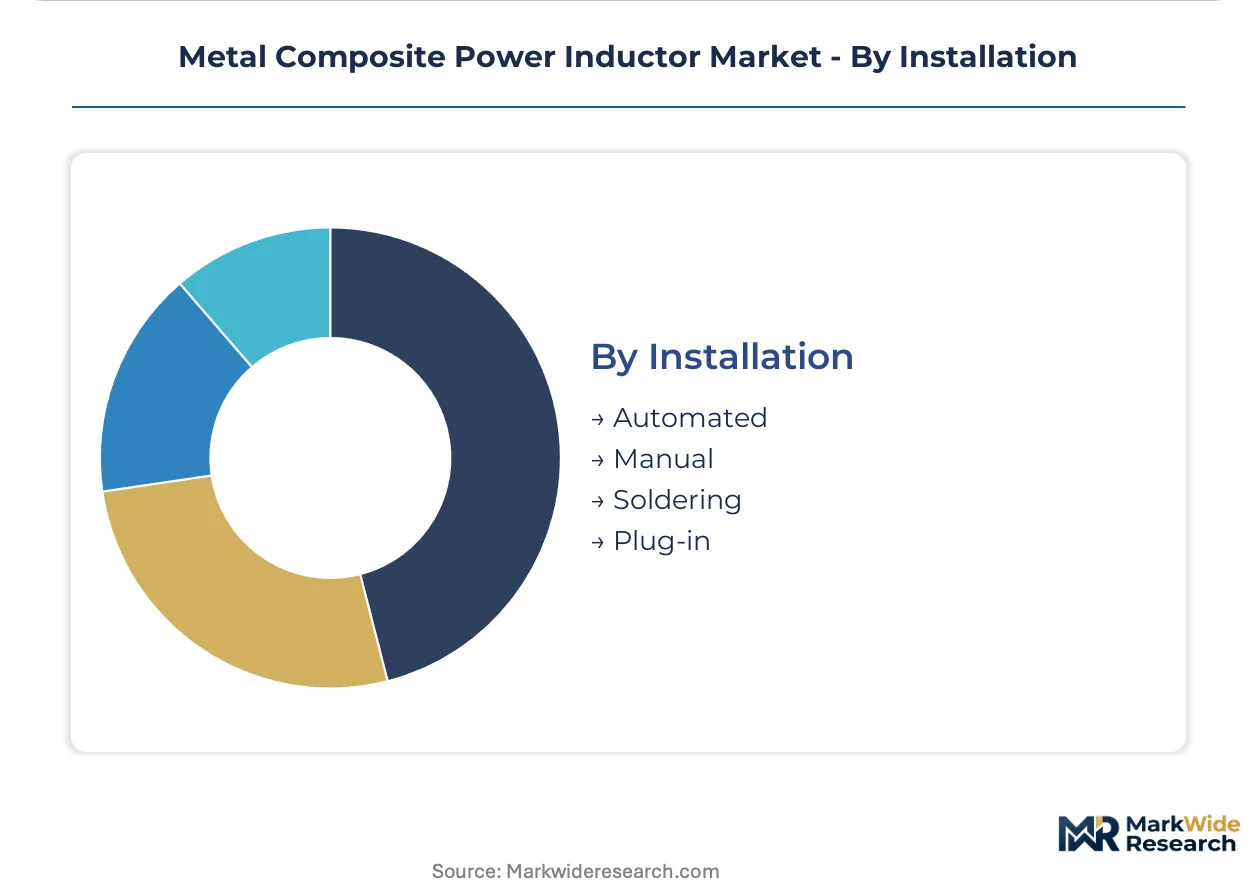
End User:
Cost tier stratification separates automotive qualification-intensive procurement from consumer electronics price sensitivity, with industrial equipment occupying a mid-tier efficiency-driven position.
- Automotive:Onboard chargers and DC-DC converter modules demand AEC-Q200 Rev E compliance alongside IECQ certification for safety-critical circuits. NEV platform launch schedules are compressing qualification timelines and freezing out non-specialized suppliers.
- Consumer Electronics:Smartphones and tablets specify manganese-zinc ferrite inductors where saturation current requirements permit, limiting metal composite penetration despite surface mount compatibility.
- Industrial Equipment:Motor drives and welding applications prioritize core loss performance under thermal stress over absolute cost minimization.
- Telecommunications:5G base stations and Open RAN architectures require high-isolation power magnetics in thermally constrained outdoor enclosures.
Automotive commands the premium tier while telecommunications expands most quickly.
Application:
Application segmentation tracks how voltage regulation architecture shifts toward multiphase topologies at varying speeds across end-use domains.
- DC-DC Converters:Multiphase voltage regulation architectures in hyperscale datacenters and NEV powertrains demand high saturation current inductors operating above one megahertz. Datacenter operators in the United States and Germany are consolidating procurement through direct supplier relationships contingent on demonstrated reliability above one million hours mean time between failures.
- Power Supply Units:AC-DC front ends in industrial equipment and telecommunications infrastructure require stable inductance under thermal cycling.
- Voltage Regulators:Point-of-load modules in computing and networking equipment prioritize compact footprint and low DC resistance.
- RF Applications:High-frequency filtering in base stations and radar systems demands controlled parasitic capacitance through dimensional consistency.
Power supply units anchor the installed base while DC-DC converters climb the fastest.
Installation:
Installation method segmentation reflects automation penetration rates and workforce skill availability across manufacturing geographies.
- Automated:Pick-and-place compatible surface mount packages dominate high-volume consumer electronics and automotive electronics manufacturing in East Asian clusters.
- Manual:Hand-soldered through hole assemblies persist in low-volume industrial equipment and repair-intensive telecommunications infrastructure.
- Soldering:Reflow and wave soldering processes accommodate leaded and surface mount formats with thermal profile optimization.
- Plug-in:Compliant-pin and press-fit connections enable solderless assembly for automotive modules requiring field serviceability.
Automated installation anchors throughput volumes while plug-in gains traction in automotive safety-critical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and South Korea export precision-wound metal composite inductors to German automotive OEMs and US hyperscale datacenter operators, with China's bonded manufacturing zones absorbing alloy powder pressing operations to serve domestic NEV producers.
China
NEV production quotas and GB/T electromagnetic compatibility standards are accelerating procurement of low-loss magnetic components for onboard chargers. The country's dual carbon goals mandate energy efficiency benchmarks that favor metal composite cores over traditional ferrite in high-current applications. Domestic suppliers in Suzhou and Dongguan are localizing automated winding equipment to meet dimensional consistency requirements for DC-DC converter modules.
Japan
METI energy efficiency benchmarks for industrial equipment are tightening core loss thresholds and creating replacement demand in motor drives and welding applications. Japanese manufacturers leverage multilayer co-firing expertise developed in ceramic capacitor production to advance compact high-isat inductor designs. Production clusters in Nagoya and Kyoto are expanding powder core pressing capacity to anchor premium EV powertrain contracts with European OEMs.
South Korea
Hyundai-Kia platform electrification and battery cell manufacturing expansion are driving high-current inductor demand for DC-DC converter modules. The country's national industrial regulator aligns component qualification with AEC-Q200 Rev E through KAT certification programs. Busan-Ulsan manufacturing corridors are attracting Japanese alloy powder suppliers to establish joint pressing operations for regional EV supply chains.
Germany
The EU F-Gas Regulation is shifting thermal design specifications away from fluorinated greenhouse gas-dependent cooling systems in automotive power electronics. German OEMs require IECQ certification alongside AEC-Q200 compliance for passive components in safety-critical circuits. Industrial clusters in Baden-Württemberg and Bavaria are consolidating procurement relationships directly with magnetics specialists rather than distributor channels.
United States
Hyperscale datacenter operators in Virginia and Oregon are deploying multiphase voltage regulation architectures demanding high saturation current inductors above one megahertz switching frequencies. NHTSA electrification mandates and EPA emissions standards are pressuring automotive suppliers to accelerate AEC-Q200 qualification cycles. Texas and Arizona manufacturing zones are attracting East Asian inductor specialists to establish captive powder core pressing operations.
Metal Composite Power Inductor Market Competitive Landscape
Listed leaders compete with private specialists across material science and winding automation capabilities. The vendor base stratifies into three tiers: integrated material-to-component manufacturers, winding automation specialists, and regional powder core suppliers. Archetypes include ferrite heritage diversifiers, alloy powder formulation specialists, and multilayer ceramic crossover players. Capacity expansion and backward integration into powder core production represent the dominant competitive moves as qualification timelines compress.
Among Japanese material science conglomerates, TDK Corporation and Murata Manufacturing Co., Ltd. exemplify the ferrite heritage diversifier archetype, leveraging ceramic and magnetic material expertise to anchor premium automotive contracts. Bourns Inc. represents the vertically integrated North American specialist model with in-house powder core formulation capabilities. South Korean fabricators including SAMSUNG ELECTRO-MECHANICS occupy positions bridging consumer electronics scale with automotive qualification infrastructure.
| Leading Market Players |
|---|
| Bourns Inc. |
| SAMSUNG ELECTRO-MECHANICS |
| TDK Corporation |
| KEMET |
| SUMIDA CORPORATION |
| Murata Manufacturing Co., Ltd. |
| TAIYO YUDEN Co., Ltd. |
| Abracon LLC |
| Vishay Intertechnology, Inc. |
| Others |
Supply & Pricing Matrix
Long-term qualification partnerships with automotive OEMs lock in multi-year offtake agreements that secure alloy powder feedstock access while stabilizing unit pricing visibility against rare earth volatility. These contractual structures concentrate procurement leverage among AEC-Q200 certified suppliers and compress margin flexibility for non-qualified competitors serving China's NEV and datacenter segments.
Pricing Analysis
Sendust alloy cores command premium positioning over conventional iron powder designs due to dual-layer organic-inorganic hybrid coating technology and 150°C continuous operation ratings. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates AEC-Q200 Rev E qualified products from standard offerings. Cost compression in consumer electronics tiers is intensifying because manganese-zinc ferrite substitutes satisfy saturation current requirements in smartphones and tablets. Consumer electronics buyers exhibit highest price sensitivity, while automotive powertrain procurement prioritizes reliability premiums over unit cost minimization.
Supply Chain Analysis
China and Japan anchor alloy powder pressing and precision winding operations, with South Korean fabricators bridging automotive qualification infrastructure and consumer electronics scale. Core formulations draw from iron-silicon-aluminum and iron-nickel-molybdenum feedstocks sourced through concentrated rare earth processing corridors. Single-source vulnerability in alloy powder insulation coating technology exposes manufacturers to carbon border adjustment disclosure requirements and supply chain transparency mandates. Distribution runs through direct relationships with hyperscale datacenter operators and Tier 1 automotive suppliers, bypassing traditional distributor channels in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where AEC-Q200 Rev E qualification timelines create regulatory entrenchment that freezes out non-specialized suppliers and locks in incumbent pricing power.
For Market Incumbents: Secure captive powder core pressing capacity within China's bonded manufacturing zones to defend against domestic supplier expansion and localize for GB/T electromagnetic compliance requirements. Deepen backward integration into iron-silicon-aluminum formulation to insulate margin structures from rare earth feedstock volatility and carbon border adjustment exposure. For New Entrants and Emerging Players: Field application engineering gaps in datacenter direct procurement channels create service-layer white-space where embedded technical support teams can differentiate against distributor-mediated sourcing. Target industrial equipment retrofit segments in Japan where METI efficiency mandates displace ferrite designs but legacy DC-DC architecture integration costs deter established automotive suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward alloy powder formulation specialists with demonstrated megahertz-frequency core loss modeling capabilities and existing IECQ certification infrastructure. Watch for inflection signals in multiphysics simulation talent scarcity resolution, as electromagnetic-thermal-mechanical co-simulation expertise concentration represents the binding constraint on premium product expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Core Production | Captive alloy pressing capacity insulates margins from rare earth volatility and carbon disclosure mandates. |
| AEC-Q200 Rev E Certification Investment | Automotive qualification entrenchment freezes out non-specialized competitors from safety-critical NEV circuits. |
| Automated Winding Equipment Deployment | Precision dimensional consistency enables GB/T electromagnetic compatibility compliance for DC-DC converter modules. |
| Direct Datacenter Procurement Relationships | Hyperscale operator consolidation bypasses distributor channels and locks in multi-year reliability-based agreements. |
| Sendust Alloy Core Formulation Advancement | Dual-layer hybrid coatings displace conventional iron powder in EV onboard chargers above 11 kilowatts. |
Research Methodology
The analysis maps surface mount, through hole, leaded, and unleaded product formats, each validated through magnetics design engineers, Tier 1 automotive supplier procurement officers, datacenter power infrastructure architects, and alloy powder metallurgists. Primary fieldwork combined with secondary validation against customs trade records, SEC 10-K component segment disclosures, METI energy efficiency benchmark publications, and GB/T standard technical committees enables bottom-up shipment triangulation against top-down voltage regulation architecture demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across product type, end user tier, application architecture, and installation automation level. CAGRs were derived from multiphase DC-DC converter adoption curves and NEV platform launch schedules, incorporating alloy powder core loss performance thresholds and AEC-Q200 qualification timeline compression factors as industry-specific forecast inputs.
Forecasts assume regulatory continuity in China's NEV mandate and GB standards, Japan's METI benchmarks, and EU F-Gas thermal design specifications; material policy shifts in rare earth supply chain disclosure or carbon border adjustment mechanisms would require re-modeling. Recalibration cycles align with material shifts in automotive electrification platform launches and datacenter multiphase architecture deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Impulse Relays Market
Electronic Components
Distribution Components Market
Electronic Components
Microcontroller Socket Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Audio Capacitor Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Serial Device Servers Market
Electronic Components
Amplifier Market
Electronic Components
Speaker Membranes Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Discrete Capacitors Market
Electronic Components
GPIO Expanders Market