
 Data Monetization Platform Market | 2026-2036
Data Monetization Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Data Monetization Platform Market Outlook
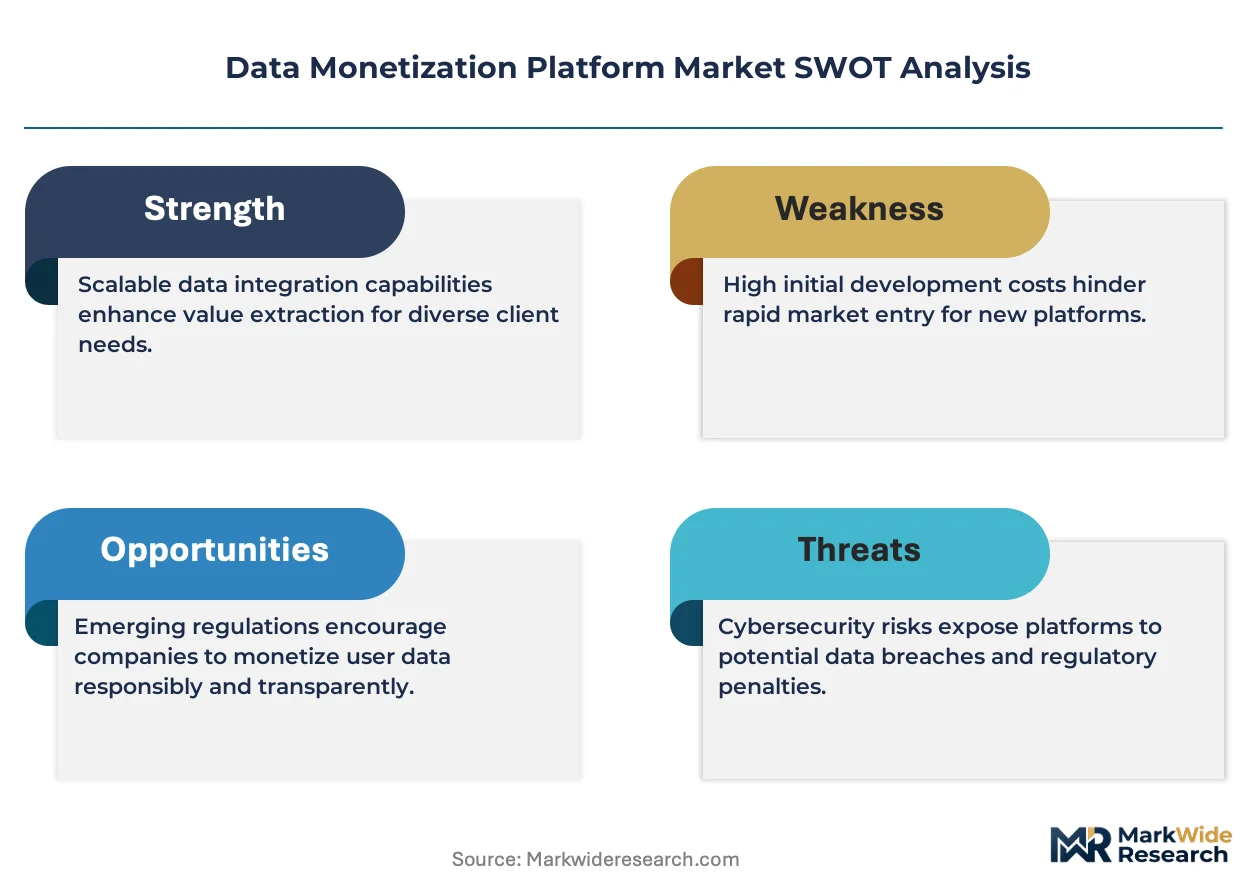
The gap between premium enterprise-grade data monetization platforms and commodity analytics tools is broadening. Reltio specializes in master data management architectures that sustain high-margin recurring revenue. IBM leverages its Watson analytics stack to dominate hybrid deployment environments for regulated industries.
A data monetization platform is a software infrastructure that ingests, governs, and transforms raw enterprise data into commercially valuable assets through APIs, marketplaces, or internal analytics workflows; these systems typically process petabyte-scale datasets with sub-second query latency for real-time decisioning. Cloud-based deployment leads in new bookings among retailers and telecom providers seeking elastic compute for seasonal data volumes. Subscription-based solution models are capturing the deepest margin pools as enterprises shift from perpetual licenses to consumption-driven pricing for data warehousing and real-time analytics services.
The EU AI Act and GDPR constrain automated profiling and cross-border data transfers, forcing platform vendors to embed privacy-preserving computation and regional data residency controls. The SEC's climate disclosure rules and the California Consumer Privacy Act compel financial institutions and retailers to invest in auditable data lineage tools that satisfy both investor transparency and consumer rights mandates. Stakeholders must weigh regulatory compliance costs against the revenue potential of first-party data marketplaces as third-party cookie deprecation accelerates.
Market Dynamics
Third-party cookie deprecation is forcing retailers and publishers to rebuild targeting infrastructure around first-party data assets, compressing vendor selection timelines and elevating governance requirements.
Growth Catalysts
- EU AI Act:Automated decision-making rules are accelerating investment in auditable data lineage tools among European financial institutions.
- Cloud elasticity:Telecom providers are adopting consumption-based pricing models to handle seasonal data volume spikes without stranded capacity.
- Programmatic infrastructure:United States-based media buyers are consolidating spend through platforms offering real-time audience segmentation.
Market Restraints
- Cross-border friction:GDPR data residency requirements fragment platform architectures and inflate operational overhead for multi-national deployments.
- Compute cost volatility:GPU and specialized AI accelerator pricing swings compress margins for real-time inference workloads at scale.
- API standardization gaps:Inconsistent data exchange protocols force expensive custom integration work between buyer and seller systems.
Strategic Opportunities
- Privacy-preserving computation:Differential privacy and federated learning techniques open regulated sectors previously closed to external data sharing.
- India's data localization mandate:Domestic cloud regions create captive demand for compliant platform deployments serving South Asian enterprises.
- Carbon disclosure convergence:SEC climate rules and CSRD alignment create bundled demand for ESG data products tied to financial risk models.
Industry Challenges
- Data engineering talent scarcity:Pipeline architecture and governance automation skills command premium compensation, constraining platform buildouts.
- Legacy system entanglement:On-premise data warehouses resist migration due to embedded business logic, delaying cloud-native feature adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Monetization Platform Market |
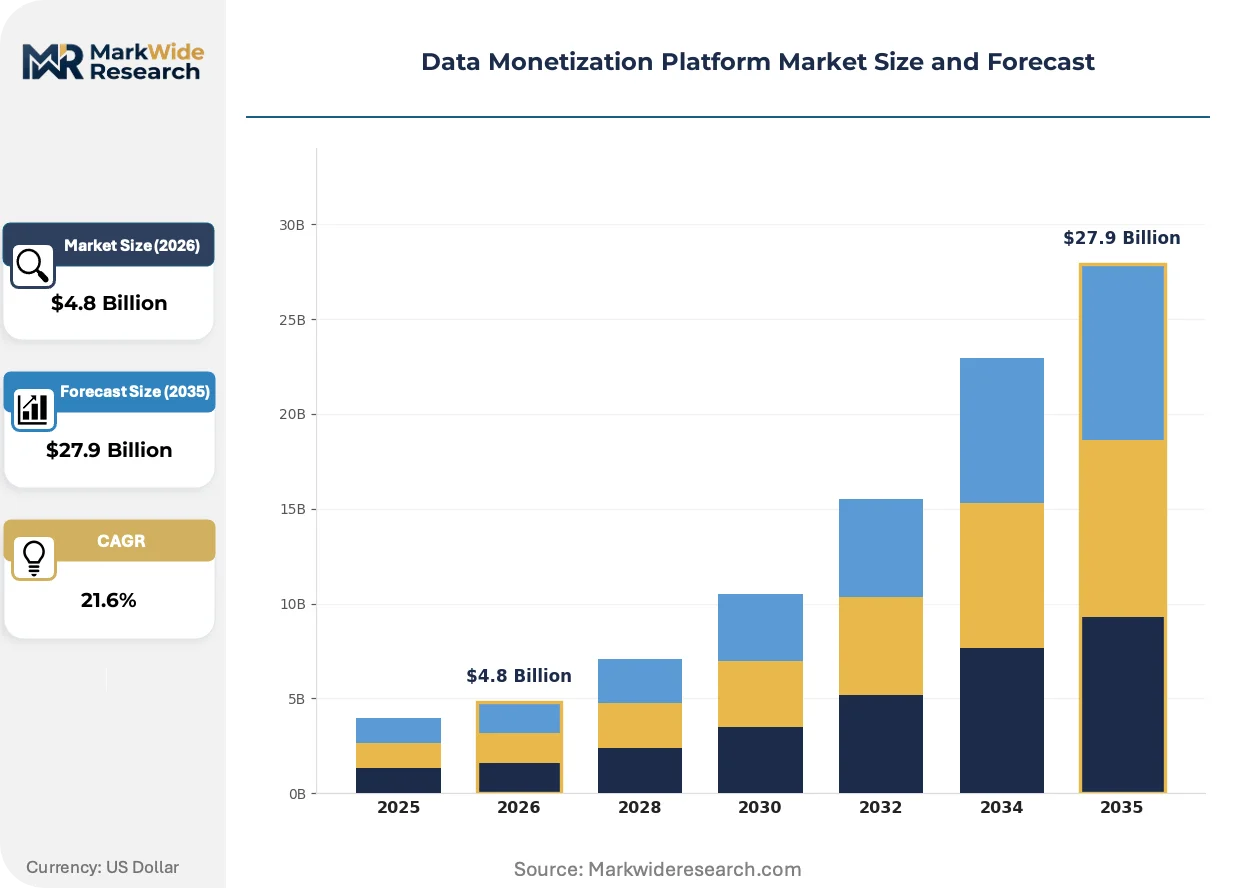
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $27.9 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Tenant Service Type: Data Integration, Analytics, Reporting, Consulting End User: Retailers, Financial Institutions, Telecom Providers, Healthcare Organizations Solution: Advertising Solutions, Data Warehousing, Subscription Models, Real-Time Analytics |
| Companies Covered | Reltio, Redknee, Accenture, Teradata, SAS, IBM, Infosys, Samsung ARTIK, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Monetization Platform Market Strategic Shifts
Real-time decisioning requirements are compressing batch processing windows and elevating edge-deployed inference architectures. Platform vendors are racing to embed governance automation without sacrificing query performance.
Confidential computing hardware is decentralizing trust assumptions for multi-party data collaborations. Pharmaceutical and financial services buyers in Germany and Switzerland are piloting enclave-based analytics to satisfy regulatory scrutiny. This architecture is decentralizing the market structure away from centralized data lakes toward distributed, verifiable computation nodes.
The EU AI Act's risk-tier classification system is redrawing procurement criteria for automated profiling tools. High-risk system providers must demonstrate human oversight mechanisms and bias audit trails. Retailers deploying recommendation engines across France, Italy, and Spain are restructuring vendor contracts to allocate compliance liability explicitly.
Subscription fatigue among mid-market enterprises is compressing pricing experimentation cycles. Buyers now demand consumption-based tiers with hard spend caps rather than committed annual contracts. This pattern is most visible among United Kingdom-based fintechs and digital publishers rebuilding ad-tech stacks post-cookie.
Data Monetization Platform Market Segmentation
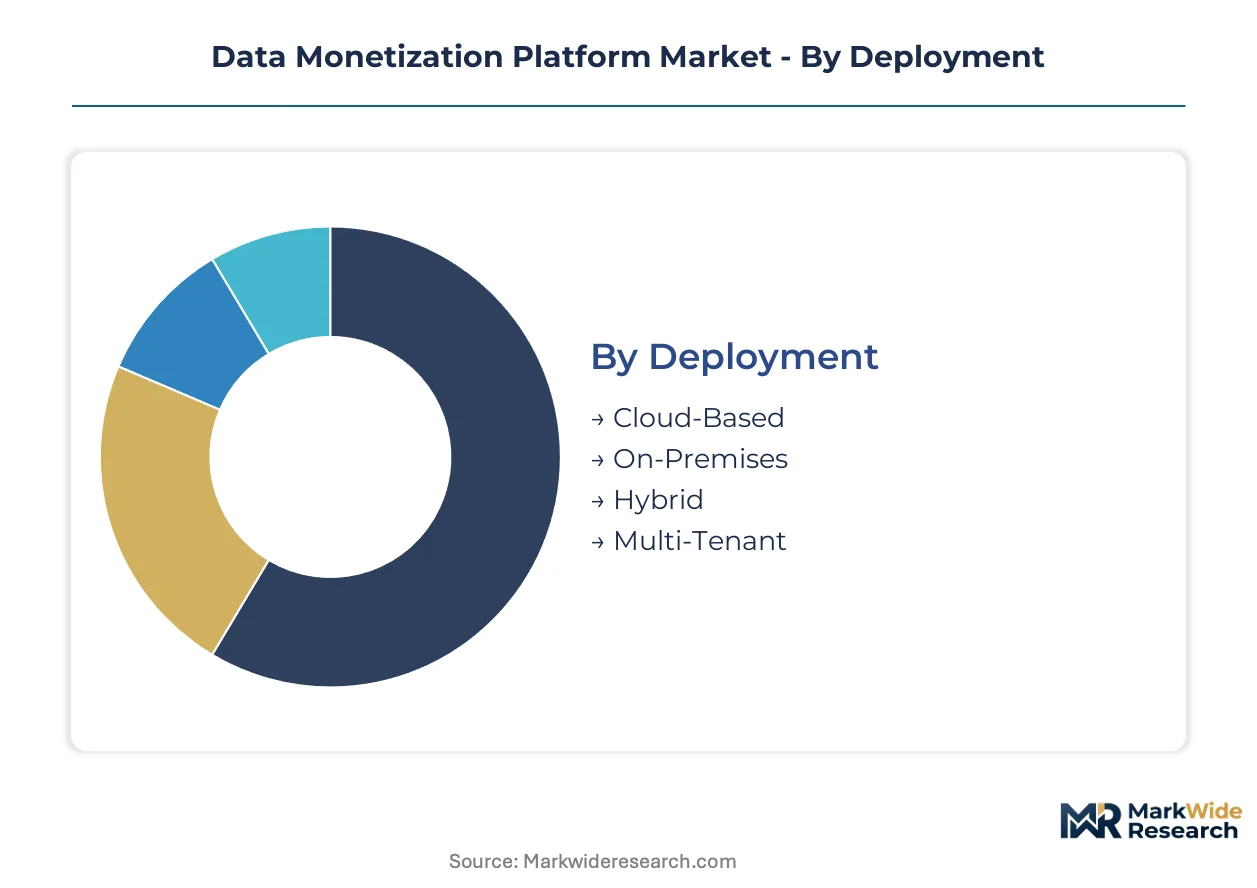
Segmentation in the data monetization platform market reveals how vendor capabilities align with divergent customer infrastructure maturity and regulatory exposure. Deployment architecture choices directly determine latency performance, compliance scope, and total cost of ownership across use cases.
Deployment:
Supply concentration among hyperscale cloud providers is compressing pricing for elastic compute while fragmenting regional compliance architectures.
- Cloud-Based:Elastic infrastructure provisions petabyte-scale storage with sub-second query latency for real-time decisioning. Retailers in the United States and telecom providers in India are consolidating bookings here, driven by seasonal volume spikes and domestic data localization mandates.
- Hybrid:Split architectures maintain sensitive data on-premises while pushing analytics workloads to public cloud nodes. Financial institutions across Germany and Switzerland favor this model to satisfy EU AI Act audit requirements without sacrificing computational scale.
- On-Premises:Legacy data centers with embedded business logic resist migration due to compliance certification dependencies.
- Multi-Tenant:Shared infrastructure instances reduce per-customer operational overhead for mid-market publishers rebuilding ad-tech stacks.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Service Type:
Margin pools concentrate in high-automation tiers where governance tooling reduces manual pipeline engineering hours.
- Data Integration:Pipeline orchestration and API standardization services that normalize disparate source systems into unified schemas. Telecom providers in South Korea and digital publishers in the United Kingdom are expanding procurement here as third-party cookie deprecation forces first-party data unification.
- Analytics:Statistical modeling and machine learning workflows that transform raw data into predictive features. Healthcare organizations in the United States are driving demand for HIPAA-compliant analytics environments that support population health risk stratification.
- Reporting:Automated dashboard generation and regulatory disclosure formatting for SEC climate rules and CSRD alignment.
- Consulting:Advisory services for data strategy, governance framework design, and vendor selection.
Integration and analytics services are gaining share fastest as enterprises prioritize automated pipeline architecture over manual consulting engagements.
End User:
Application intensity varies sharply by sector regulatory burden and first-party data asset maturity.
- Retailers:Customer analytics platforms that unlock transaction and behavioral data for targeted merchandising and programmatic advertising. United States-based retailers are expanding adoption fastest, consolidating spend through platforms offering real-time audience segmentation.
- Financial Institutions:Risk modeling and fraud detection systems that process transactional streams under strict audit requirements. European banks are restructuring vendor contracts to allocate EU AI Act compliance liability explicitly.
- Telecom Providers:Network optimization and subscriber analytics leveraging location and usage pattern data.
- Healthcare Organizations:Clinical data monetization for research partnerships and population health management.
Retailers currently dominate procurement volume. Financial institutions represent the steepest expansion trajectory as automated decision-making rules tighten.
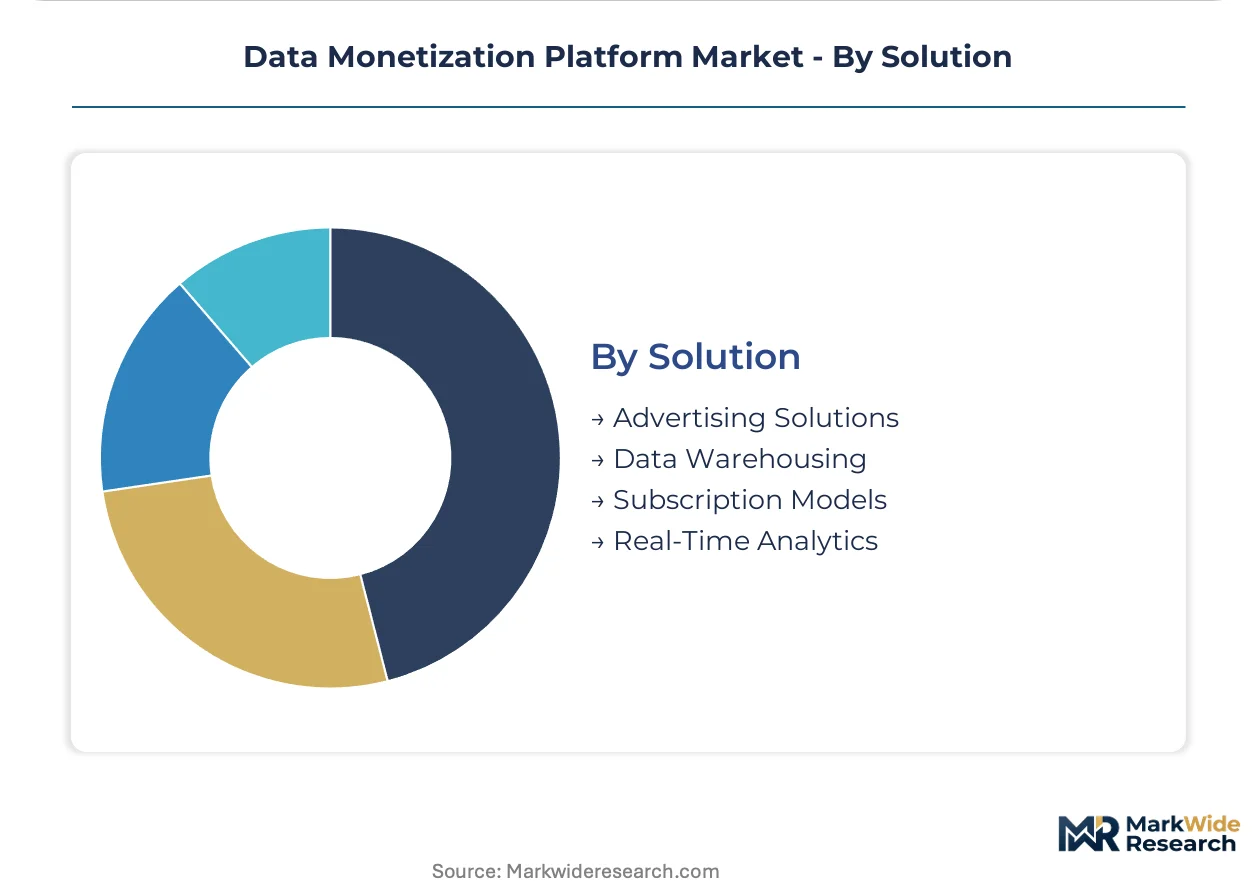
Solution:
Pricing models are shifting from perpetual licenses toward consumption-driven structures with hard spend caps.
- Real-Time Analytics:Stream processing architectures that enable sub-second inference for programmatic bidding and dynamic pricing. Media buyers in the United States are consolidating infrastructure here, compressing vendor selection timelines as cookie deprecation deadlines approach.
- Data Warehousing:Centralized storage systems with auditable lineage for regulatory disclosure and cross-functional analytics. Retailers in France and Italy are investing here to satisfy GDPR data residency requirements while enabling internal data marketplace development.
- Advertising Solutions:Audience targeting and measurement tools rebuilt around first-party data assets.
- Subscription Models:Recurring revenue platforms for external data product distribution.
Real-time analytics commands premium pricing today. Data warehousing solutions are climbing fastest as compliance-driven audit requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates enterprise cloud migration and programmatic advertising infrastructure, while Germany anchors privacy-preserving computation adoption under stricter regulatory frameworks. Demand patterns diverge sharply between these two poles of market maturity.
United States
Enterprise cloud migration and real-time audience segmentation drive procurement among retailers and media buyers. The SEC's climate disclosure rules compel financial institutions to invest in auditable data lineage tools. New York and San Francisco Bay Area clusters host the densest concentration of programmatic advertising infrastructure rebuilds.
Germany
EU AI Act compliance requirements accelerate investment in human oversight mechanisms and bias audit trails. The country's national data protection authority enforces strict cross-border transfer protocols. Frankfurt and Munich industrial clusters lead confidential computing pilots for pharmaceutical and financial services multi-party collaborations.
India
Domestic data localization mandates create captive demand for compliant cloud region deployments. The central bank's payment data storage requirements force telecom providers to re-architect subscriber analytics pipelines. Bengaluru and Hyderabad technology corridors concentrate real-time analytics talent for seasonal volume spike management.
United Kingdom
Subscription fatigue among fintechs and digital publishers compresses pricing experimentation toward consumption-based tiers with hard spend caps. The Information Commissioner's Office enforces GDPR-aligned behavioral data processing constraints. London's rebuilt ad-tech stack clusters drive fastest adoption of multi-tenant shared infrastructure instances.
South Korea
Telecom providers expand data integration procurement for first-party data unification as third-party identifiers deprecate. The country's national telecommunications regulator mandates location data handling protocols for network optimization analytics. Seoul Capital Area clusters concentrate pipeline orchestration engineering for API standardization services.
Data Monetization Platform Market Competitive Environment
Top-tier vendors anchor hybrid deployment architectures for regulated industries, while mid-tier specialists capture elastic compute demand among retailers and telecom providers. The market structure stratifies across three functional tiers: master data management architects, analytics stack integrators, and cloud-native infrastructure builders. Strategic moves concentrate on M&A for governance automation capabilities and geographic expansion into mandated data residency zones.
Within the enterprise integration tier, IBM and SAP exemplify hybrid deployment dominance for financial institutions navigating EU AI Act audit requirements. Reltio occupies a position representing master data management specialization that sustains high-margin recurring revenue streams. Accenture and Infosys sit within the services-heavy advisory archetype, anchoring consulting engagements for data strategy framework design. These five entities collectively illustrate how vendor positioning maps to customer infrastructure maturity and regulatory exposure intensity.
| Leading Market Players |
|---|
| Reltio |
| Redknee |
| Accenture |
| Teradata |
| SAS |
| IBM |
| Infosys |
| Samsung ARTIK |
| SAP |
| Others |
Value Chain & Pricing Dynamics
Consumption-based procurement preferences among United States retailers and United Kingdom fintechs are compressing vendor margins and forcing hyperscale cloud providers to restructure capacity deployment toward elastic compute pools, which in turn fragments regional pricing architectures and elevates cost volatility for real-time inference workloads.
Pricing Analysis
Capacity additions in India and South Korea are reshaping price floors for cloud-native data monetization platforms as domestic data localization mandates create captive regional demand. Subscription models with hard spend caps now dominate procurement conversations, with price differentiation resting on governance automation depth and sub-second query latency guarantees. Cost compression in mid-market tiers is intensifying because subscription fatigue compresses pricing experimentation cycles. United Kingdom fintechs exhibit highest price sensitivity, while German financial institutions accept premium tiers for EU AI Act compliance tooling.
Supply Chain Analysis
Freight cost volatility for specialized AI accelerators and GPU shipments from Taiwan and South Korea is elevating total cost of ownership for real-time analytics deployments. Supply concentration in United States hyperscale regions, Indian domestic cloud zones, and German confidential computing clusters creates divergent procurement pathways. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and liquid cooling infrastructure. Single-source vulnerability for advanced AI chips concentrated in Taiwan presents structural risk. Distribution runs through direct enterprise sales for regulated sectors and self-serve marketplaces for mid-market publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data monetization platform market functions as a stable compounder anchored by irreversible enterprise cloud migration and the structural necessity of first-party data infrastructure rebuilds.
For Market Incumbents: Acquire governance automation capabilities and regional data residency certifications to defend against emerging cloud-native challengers. Invest in confidential computing hardware partnerships for pharmaceutical and financial services buyers in Germany and Switzerland. Capacity expansion in Indian domestic cloud regions captures localization-mandated demand before competitors establish compliant footprints. For New Entrants and Emerging Players: Mid-market digital publishers in the United Kingdom rebuilding ad-tech stacks post-cookie represent the most penetrable buyer archetype. Privacy-preserving computation tooling for European healthcare data collaborations offers white-space expansion. Channel partnerships with systems integrators accelerate enterprise credibility without direct sales overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid deployment specialists serving EU AI Act compliance requirements. Long-term viability centers on vendors embedding auditable lineage and human oversight mechanisms into automated profiling systems. Watch for inflection signals in EU AI Act enforcement intensity and third-party cookie deprecation deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Governance automation capabilities from niche vendors satisfy EU AI Act audit requirements for German banks. |
| Geographic Expansion | Indian domestic cloud regions capture RBI-mandated payment data storage demand from telecom providers. |
| Platform Integration | Confidential computing hardware integration enables pharmaceutical multi-party collaborations under Swissmedic scrutiny. |
| Strategic Partnership | Hyperscaler alliances provide elastic compute for United States retailer seasonal volume spikes. |
| Product Launch | Real-time audience segmentation tools address compressed vendor selection timelines from cookie deprecation. |
Study Parameters
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with CTOs, data platform engineers, procurement officers at financial institutions, and compliance leads at retailers combined with secondary validation from SEC climate disclosure filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and TRAI data localization circulars. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map deployment architecture choices to latency performance and compliance scope across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern. CAGRs derive from elasticity-adjusted capacity buildouts and first-party data marketplace revenue trajectories. Forecast inputs incorporate cloud region expansion timelines and automated decision-making rule enforcement intensity.
Inputs from hyperscaler infrastructure disclosures and regulatory implementation guidance were available through the study window; gaps in confidential computing adoption rates and federated learning deployment scale introduce uncertainty bands. Forecasts reflect documented assumptions about cloud migration velocity and compliance cost pass-through. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Referral Management Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Location As a Service Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Data Extraction Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Indonesia Digital Software Solutions Market