
 India Digital Twin Market | 2026-2036
India Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Twin Market Insights
Market Context
Asset-light leasing models for IoT sensor infrastructure is tilting competitive dynamics toward firms that avoid heavy capex commitments. Simulanis Solutions leverages its immersive technology stack to dominate industrial training applications. Tata Consulting Engineers anchors large-scale deployment through its EPC relationships across power and infrastructure. Intangles Lab Private Limited specializes in automotive digital twins, sustaining deep integration with commercial vehicle OEMs.
Technical Definition and Segment Structure
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process, continuously synchronized through real-time data feeds from IoT sensors, SCADA networks, and enterprise systems to simulate behavior, predict failures, and optimize performance across operational lifecycles. Manufacturing applications command the largest deployment base, though energy management represents the fastest-growing margin pool as utilities deploy grid twins for load balancing and renewable integration. Cloud-based deployment is displacing on-premises installations among mid-sized enterprises, while edge computing architectures are gaining traction where latency constraints govern operational decisions.
Regulatory Environment
BIS standards for industrial IoT interoperability and CEA grid connectivity mandates are shaping product certification requirements for digital twin platforms serving power sector clients. The PLI scheme for advanced manufacturing and MeitY's data localization guidelines together influence whether vendors store process data within domestic cloud infrastructure or hybrid architectures. Stakeholders must monitor how evolving BIS cybersecurity standards for critical infrastructure reshape deployment architectures and vendor qualification criteria.
Market Dynamics
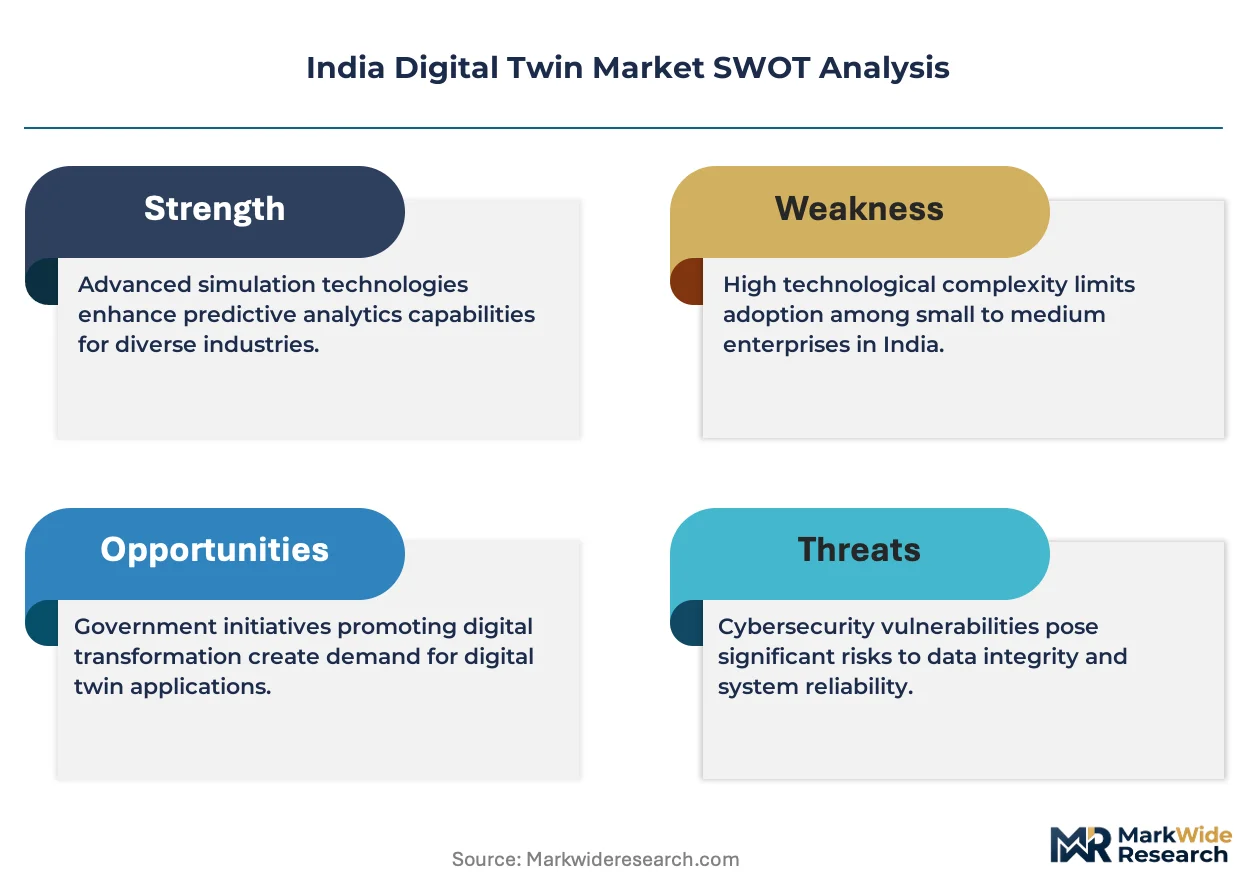
Asset-light leasing models for IoT sensor infrastructure are compressing capital barriers for mid-sized manufacturers in Gujarat and Maharashtra, tilting competitive dynamics toward platform vendors that avoid heavy capex commitments.
Growth Catalysts
- PLI scheme for advanced manufacturing:Production-linked incentives from MeitY are lowering upfront deployment costs for domestic OEMs in automotive and industrial machinery sectors.
- CEA grid connectivity mandates:Central Electricity Authority requirements for smart grid integration are accelerating utility adoption of digital twin platforms for load forecasting and renewable asset management.
- Process twins for predictive maintenance:Manufacturing plants across Pune, Ahmedabad, and Chennai are deploying real-time asset replicas to reduce unplanned downtime in continuous-process operations.
Market Restraints
- Domestic cloud infrastructure gaps:MeitY's data localization guidelines force vendors to maintain hybrid architectures, raising operational complexity for foreign platform providers.
- SCADA integration legacy debt:Brownfield manufacturing facilities retain proprietary control systems that resist standard API connectivity, extending implementation timelines.
- Specialized talent scarcity:Shortage of engineers with combined expertise in industrial automation, data science, and domain-specific process knowledge constrains deployment velocity.
Strategic Opportunities
- Small and medium enterprise penetration:Tier-2 manufacturing clusters in Coimbatore, Ludhiana, and Rajkot remain underserved by current vendor pricing models.
- Edge-to-cloud convergence:Integration of 5G private networks with containerized twin workloads enables sub-10-millisecond latency for safety-critical industrial applications.
- Renewable energy asset management:Solar and wind farm operators in Rajasthan and Tamil Nadu seek grid twins for predictive generation forecasting and inverter health monitoring.
Industry Challenges
- BIS cybersecurity certification timelines:Evolving standards for critical infrastructure create uncertainty in product roadmaps and customer qualification cycles.
- Interoperability protocol fragmentation:Competing industrial IoT standards from different automation vendors force costly middleware development for platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Twin Market |
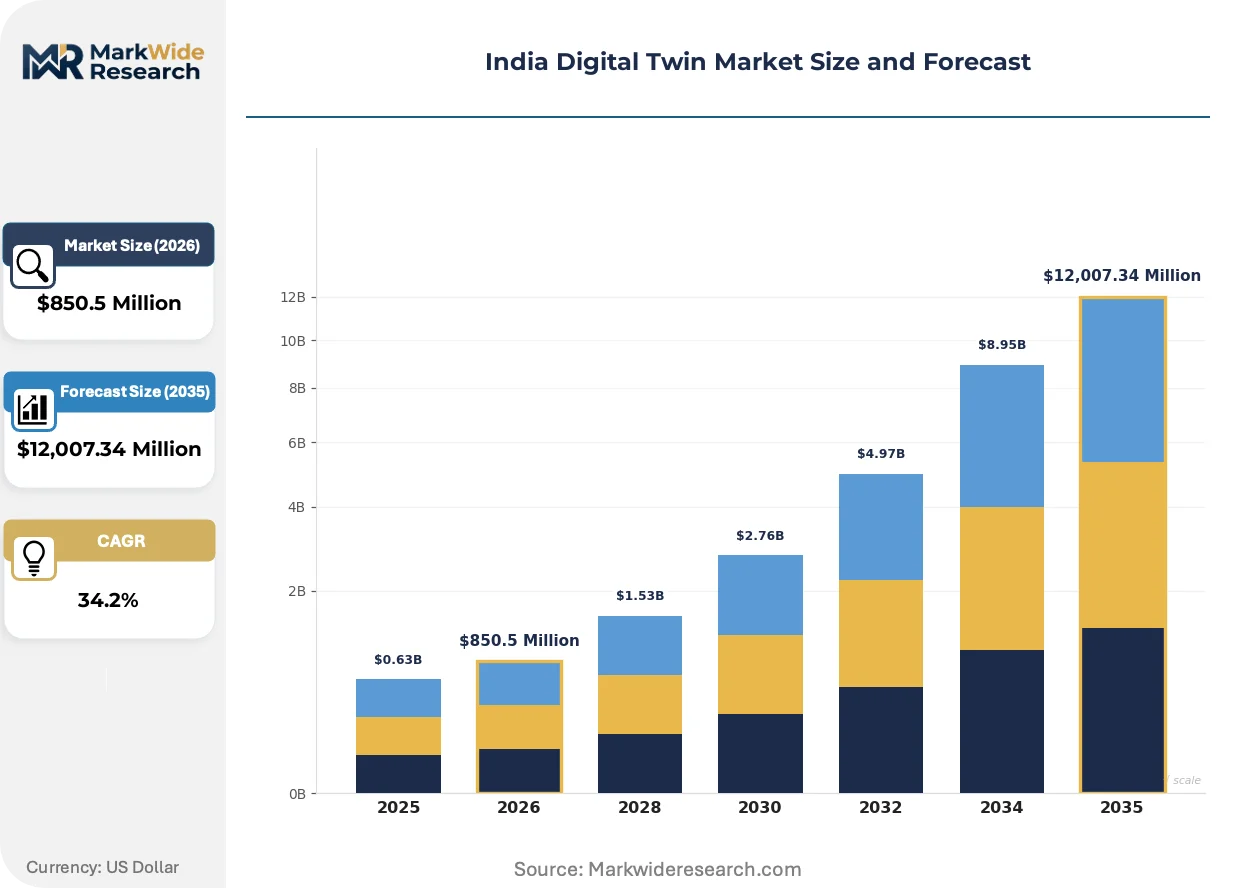
| Market Size in 2026 | $850.5 Million |
| Market Size in 2035 | $12,007.34 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Healthcare, Energy Management, Smart Buildings Technology: IoT, AI, Augmented Reality, Cloud Computing End User: OEMs, Utilities, Retailers, Healthcare Providers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Simulanis Solutions, Turiya Softech, Tata Consulting Engineers, Toobler, Faclon Labs, Cloudworx, YelloSKYE, Intangles Lab Private Limited, AIOTEL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Twin Market Trends and Innovations
Convergence of immersive visualization, edge AI, and sovereign cloud architectures is redefining how industrial operators interact with virtual replicas of physical assets.
Generative AI is collapsing the cost structure for creating and maintaining high-fidelity 3D asset models. Automotive OEMs in Chennai and Gurgaon are deploying neural radiance field reconstruction to generate photorealistic digital twins from standard camera footage. This compression eliminates months of manual CAD modeling, enabling rapid deployment across entire vehicle fleets.
BIS standards for industrial IoT interoperability are mandating unified communication protocols across brownfield and greenfield installations. The Bureau of Indian Standards framework forces automation vendors to abandon proprietary fieldbus architectures. Power sector clients now demand certified platforms that bridge legacy SCADA with modern MQTT-based sensor networks.
Performance-based contracting is replacing perpetual licensing among infrastructure EPCs. Tata Consulting Engineers and similar firms now negotiate twin platform access against operational uptime guarantees rather than software seats. This shift concentrates vendor risk and rewards predictive accuracy over feature breadth, with Maharashtra urban water utilities pioneering the model.
India Digital Twin Market Segmentation
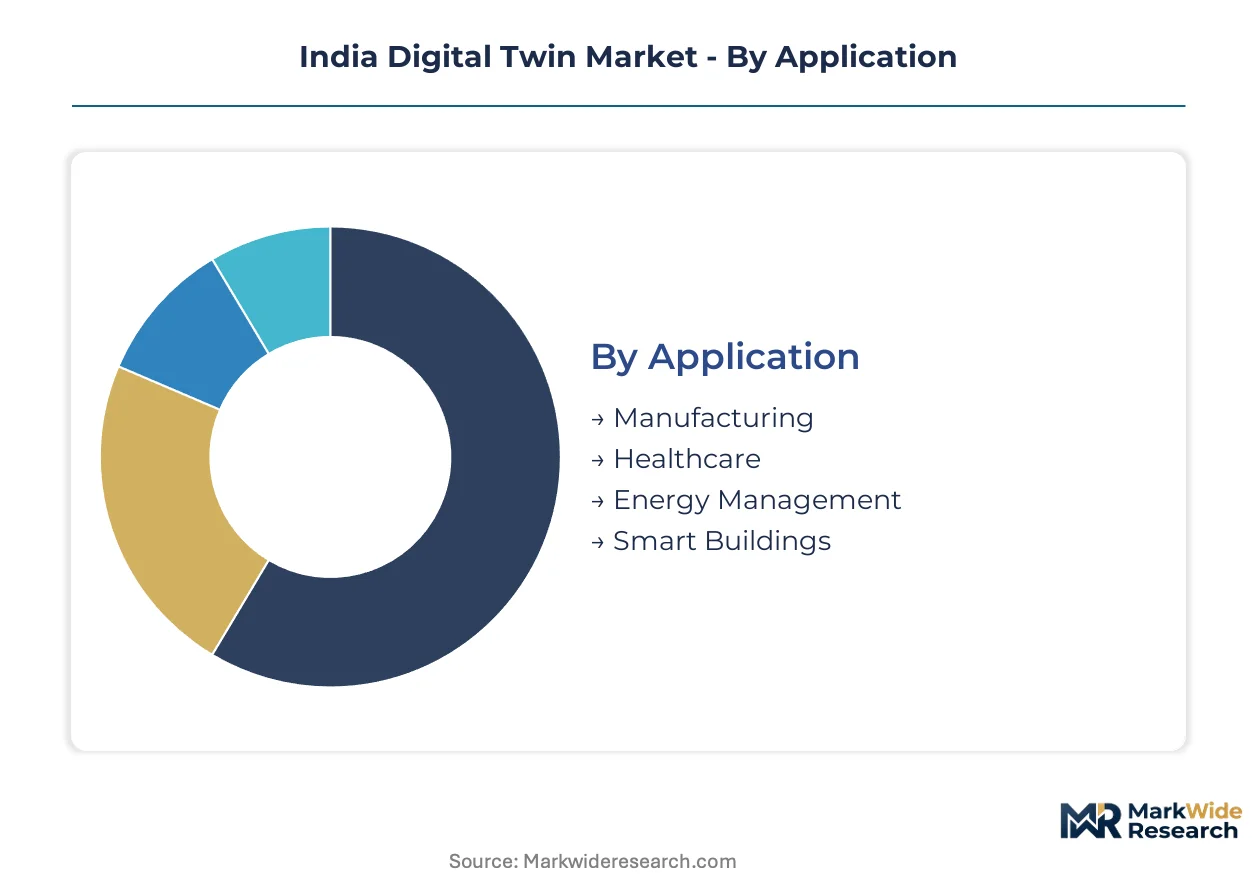
Digital twin deployment patterns in India fragment sharply across operational maturity and capital intensity. Manufacturing plants in Gujarat and Maharashtra cycle through platform refreshes faster than utility deployments, while healthcare and smart building applications remain nascent with extended evaluation timelines.
Application:
Manufacturing twins turn over fastest as automotive and industrial machinery OEMs iterate predictive maintenance models quarterly. Healthcare and smart building deployments cycle slowest due to regulatory validation and multi-stakeholder procurement processes.
- Manufacturing:Process twins for continuous operations dominate current deployment, with Pune and Ahmedabad facilities driving demand for real-time asset optimization and unplanned downtime reduction. Automotive OEMs in Chennai and Gurgaon represent the most active customer segment.
- Energy Management:Grid twins for load balancing and renewable integration are expanding most quickly, concentrated among Rajasthan solar operators and Tamil Nadu wind farm managers responding to CEA connectivity mandates.
- Healthcare:Patient-specific organ modeling and hospital facility twins remain pilot-phase, constrained by CDSCO validation requirements and data localization compliance under MeitY guidelines.
- Smart Buildings:Commercial real estate in Mumbai and Bengaluru deploys environmental and occupancy optimization twins, though ROI demonstration timelines extend 18-24 months versus manufacturing's 6-12 month cycles.
Manufacturing dominates installed base. Energy Management is where expansion concentrates.
Technology:
IoT sensor infrastructure and edge AI processors carry the steepest cost depreciation curves, forcing vendors toward leasing models. Cloud computing platforms and AR visualization layers maintain pricing power through subscription stickiness.
- IoT:Sensor networks providing real-time data feeds from SCADA and field devices constitute the foundational layer, with Gujarat manufacturing clusters driving highest device density per facility.
- AI:Machine learning models for predictive failure detection and generative 3D asset reconstruction command premium pricing, particularly neural radiance field implementations automating photorealistic twin creation from camera footage.
- Augmented Reality:Immersive visualization for remote maintenance and training applications concentrates in industrial machinery sectors, with Simulanis Solutions anchoring domestic capability.
- Cloud Computing:Sovereign cloud architectures compliant with MeitY data localization guidelines are displacing foreign hyperscaler deployments among power sector and defense-adjacent clients.
IoT commands the largest addressable spend. AI is where margin expansion concentrates.
End User:
OEM procurement cycles align with product development timelines, while utilities operate on decade-long asset management horizons. Retailers and healthcare providers exhibit the most fragmented decision-making with extended vendor qualification.
- OEMs:Automotive and industrial machinery manufacturers in Tamil Nadu and Maharashtra deploy twins across entire production lines, with commercial vehicle OEMs sustaining deepest platform integration through Intangles Lab partnerships.
- Utilities:State electricity boards and private renewable operators adopt grid twins for predictive generation forecasting, with Maharashtra urban water utilities pioneering performance-based contracting models.
- Retailers:Supply chain and inventory optimization twins remain limited to large-format operators in metro corridors, constrained by thin margins and competing digital investment priorities.
- Healthcare Providers:Hospital networks in Delhi and Bengaluru pilot surgical planning and facility management twins, though CDSCO certification timelines and specialist talent scarcity suppress deployment velocity.
OEMs dominate current revenue concentration. Utilities anchor the longest contract tenures.
Deployment:
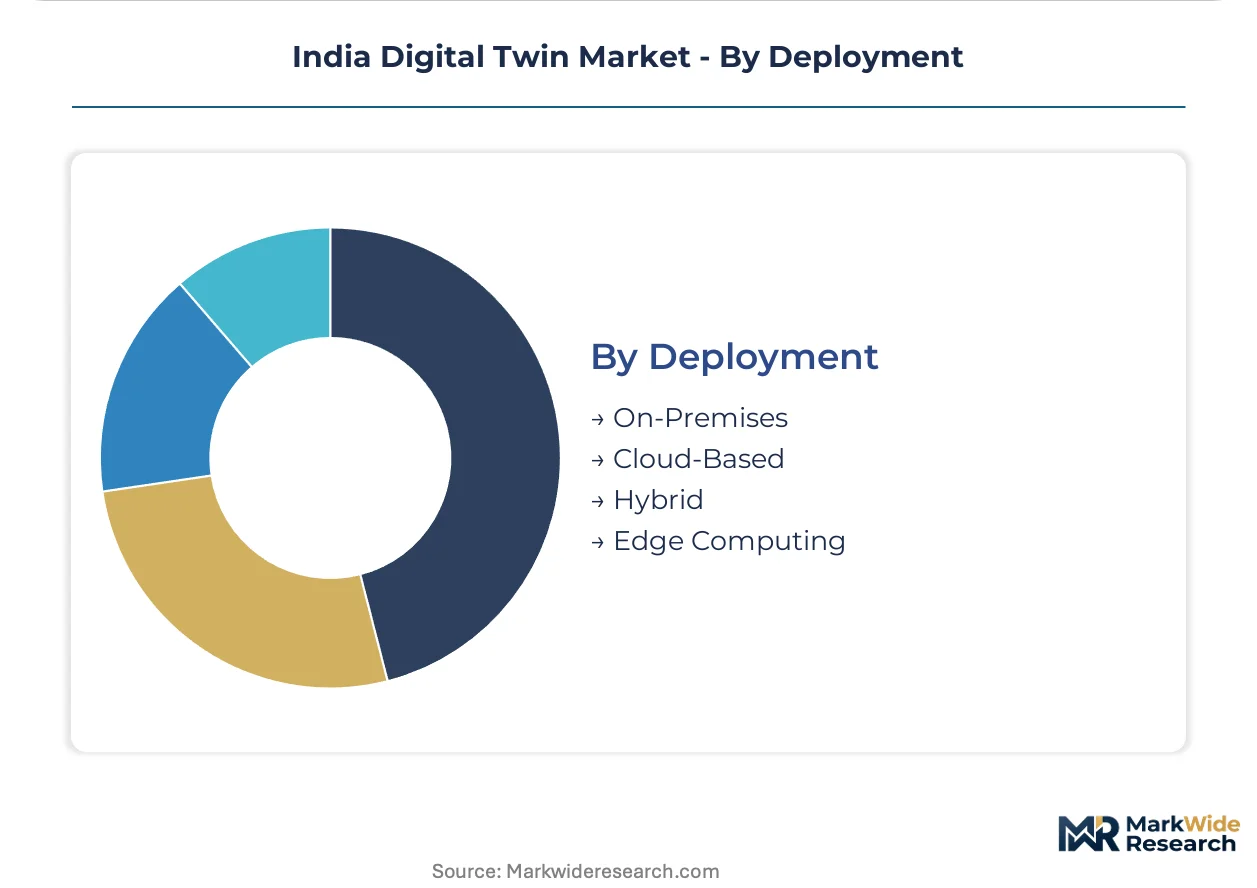
Cloud-based implementations scale fastest among mid-sized enterprises lacking legacy infrastructure. On-premises and edge architectures retain dominance where latency constraints or cybersecurity classifications govern operational decisions.
- On-Premises:Air-gapped installations persist in defense-adjacent manufacturing and critical infrastructure, though BIS cybersecurity certification timelines create vendor roadmap uncertainty.
- Cloud-Based:SaaS delivery models are compressing capital barriers for Tier-2 manufacturers in Coimbatore and Rajkot, with domestic cloud infrastructure investments accelerating compliance with data localization mandates.
- Hybrid:Architectures balancing edge processing with cloud analytics dominate brownfield manufacturing retrofits, bridging legacy SCADA with modern MQTT-based sensor networks under BIS interoperability standards.
- Edge Computing:Containerized twin workloads on 5G private networks enable sub-10-millisecond latency for safety-critical applications, with Tamil Nadu automotive facilities piloting converged edge-to-cloud architectures.
On-Premises retains the highest-value installed base. Cloud-Based is where customer acquisition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's digital twin market exhibits pronounced regional concentration, with western and southern states driving deployment momentum through manufacturing density and policy support. Export-oriented industrial corridors import sensor hardware and edge computing components while domestic software development and system integration capabilities expand.
Maharashtra
Pune and Mumbai manufacturing clusters deploy process twins for automotive and industrial machinery predictive maintenance. The state's implementation of MeitY's data localization guidelines shapes hybrid cloud architecture decisions among power sector clients. Maharashtra urban water utilities pioneer performance-based contracting models for twin platform access.
Gujarat
Ahmedabad and Vadodara process industries accelerate IoT sensor density for continuous operations optimization. PLI scheme incentives from the central government lower capital barriers for domestic OEM technology deployment. Chemical and pharmaceutical manufacturing corridors anchor the highest facility-level twin adoption rates nationally.
Tamil Nadu
Chennai automotive OEMs integrate digital twins across entire production lines for real-time asset optimization. CEA grid connectivity mandates accelerate utility adoption among renewable operators managing wind farm assets. Coimbatore's Tier-2 manufacturing clusters remain underserved by current vendor pricing models.
Karnataka
Bengaluru technology providers develop sovereign cloud architectures compliant with MeitY guidelines for defense-adjacent clients. The state's aerospace and electronics manufacturing bases pilot edge-to-cloud convergence on 5G private networks. Smart building deployments in commercial real estate extend ROI demonstration timelines versus manufacturing applications.
Haryana
Gurgaon automotive facilities deploy neural radiance field reconstruction for rapid photorealistic twin generation from camera footage. Proximity to Delhi-NCR concentrates healthcare pilot programs for patient-specific organ modeling. CDSCO validation requirements and specialist talent scarcity suppress deployment velocity in hospital network applications.
India Digital Twin Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the sensor and edge AI layer. The vendor base organizes around three strategic archetypes: immersive technology providers, engineering consultancy anchors, and automotive-focused specialists. Competitive dynamics tilt toward firms avoiding heavy capex commitments through asset-light leasing models. Consolidation pressure concentrates among mid-sized platform vendors seeking scale to serve utility and infrastructure EPC contracts.
Among domestic platform providers, Simulanis Solutions occupies a position within immersive visualization for industrial training, Tata Consulting Engineers anchors large-scale deployment through power and infrastructure relationships, and Intangles Lab Private Limited exemplifies deep automotive integration with commercial vehicle OEMs. These three represent distinct competitive vectors: experiential technology, EPC-project scale, and vertical sector specialization. Foreign hyperscalers face operational complexity from MeitY data localization guidelines, creating positioning space for domestic cloud infrastructure investments. BIS cybersecurity certification timelines for critical infrastructure create vendor roadmap uncertainty that rewards early compliance investment.
| Leading Market Players |
|---|
| Simulanis Solutions |
| Turiya Softech |
| Tata Consulting Engineers |
| Toobler |
| Faclon Labs |
| Cloudworx |
| YelloSKYE |
| Intangles Lab Private Limited |
| AIOTEL |
| Others |
Pricing and Supply Chain Analysis
Chinese sensor hardware concentration upstream feeds margin compression into Indian system integrators, while domestic cloud infrastructure investments downstream capture pricing power from MeitY compliance mandates. Platform vendors absorbing IoT depreciation through leasing models redistribute value toward AI and visualization software layers.
Pricing Analysis
Industrial OEM buyers anchor a SaaS-tiered pricing structure with premium subscriptions for predictive maintenance modules and economy tiers for basic asset monitoring. Price differentiation rests on BIS certification grade and edge AI inference capability, with certified platforms commanding substantial premiums. Cost compression in sensor hardware is intensifying because Chinese manufacturing scale and domestic PLI subsidies erode component margins. Tier-2 manufacturers in Coimbatore and Rajkot exhibit highest price sensitivity, while Maharashtra utilities negotiating performance-based contracts show lowest.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk for edge computing hardware and precision IoT sensors, forcing vendors toward ASEAN diversification. Component sourcing draws from China, Taiwan, and Vietnam for semiconductors and sensor modules, with Germany and Japan supplying high-reliability industrial automation components. Single-source vulnerability concentrates in neural processing units and specialized fieldbus adapters. Distribution runs through domestic system integrators anchoring EPC relationships, with direct OEM procurement gaining share among large automotive manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India digital twin market represents a high-growth disruption as generative AI collapses 3D asset modeling costs and BIS interoperability mandates force proprietary automation vendors toward open protocols.
For Market Incumbents: Pre-empt margin erosion in sensor hardware by deepening backward integration into edge AI chip design or captive cloud infrastructure deployment. Consolidate around EPC-project scale to defend against Tata Consulting Engineers' anchor position in power and water utilities. Invest early in BIS cybersecurity certification to capture critical infrastructure qualification cycles before foreign hyperscalers adapt to MeitY localization guidelines. For New Entrants and Emerging Players: Establish a beachhead in Tier-2 manufacturing clusters of Coimbatore, Ludhiana, and Rajkot where incumbent pricing models remain unaffordable. Target renewable energy asset management in Rajasthan solar and Tamil Nadu wind as the fastest-expanding margin pool with less entrenched vendor relationships. Pursue a partnership-first go-to-market with domestic cloud providers to shortcut data localization compliance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed immersive technology specialists and automotive-focused platform vendors with proven OEM integration. Five-to-ten year viability favors firms controlling sovereign cloud architectures or proprietary edge AI inference stacks rather than hardware-reselling intermediaries. Watch for inflection in 5G private network deployment velocity as the signal for edge-to-cloud convergence readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bridges legacy SCADA with MQTT networks under BIS interoperability mandates for brownfield manufacturing. |
| Strategic Partnership | Domestic cloud alliances shortcut MeitY compliance for foreign hyperscalers seeking power sector entry. |
| Acquisition of Specialist Firm | Absorbs scarce talent pools combining industrial automation, data science, and domain process knowledge. |
| Geographic Expansion | Tier-2 cluster penetration in Coimbatore and Rajkot captures underserved mid-sized manufacturer demand. |
| Product Launch | Neural radiance field reconstruction tools collapse photorealistic twin creation timelines for automotive OEMs. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at Gujarat and Maharashtra manufacturing facilities, CTOs at domestic platform vendors, procurement leads at Tamil Nadu automotive OEMs, and grid planning officers at state electricity boards, then refined through secondary validation against BIS certification records, CEA regulatory filings, MeitY policy circulars, and PLI scheme disbursement data. Bottom-up deployment estimates triangulated with top-down market sizing across the technology stack.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by application, technology, end user, and deployment architecture alongside regional adoption patterns and regulatory compliance tiers. CAGRs derived from installed base growth rates, platform refresh cycles, and policy incentive trajectories. Forecast inputs incorporated edge AI processor cost curves and 5G private network rollout timelines specific to industrial corridor development.
Sensitivities concentrate around BIS cybersecurity certification timeline delays, PLI scheme funding continuity, and foreign hyperscaler adaptation to data localization mandates. Forecasts reflect assumptions on interoperability standard enforcement and brownfield integration complexity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Container Orchestration Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Transport Management System Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Inventory Management Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Physical-Digital Integration Market