
 Data Labeling Solution and Services Market | 2026-2036
Data Labeling Solution and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Labeling Solution and Services Market Intelligence
Single-source dependency on captive labeling teams is rebalancing toward hybrid in-house and outsourced arrangements as model-training cycles compress. Scale AI sustains technology leadership in autonomous-vehicle LiDAR segmentation through proprietary tooling and API-first workflows. Appen Limited competes via a globally distributed crowd workforce that anchors multilingual and multicultural data coverage for natural-language models. CloudFactory Limited differentiates through managed workforce layers that integrate quality-assurance protocols directly into client pipelines.
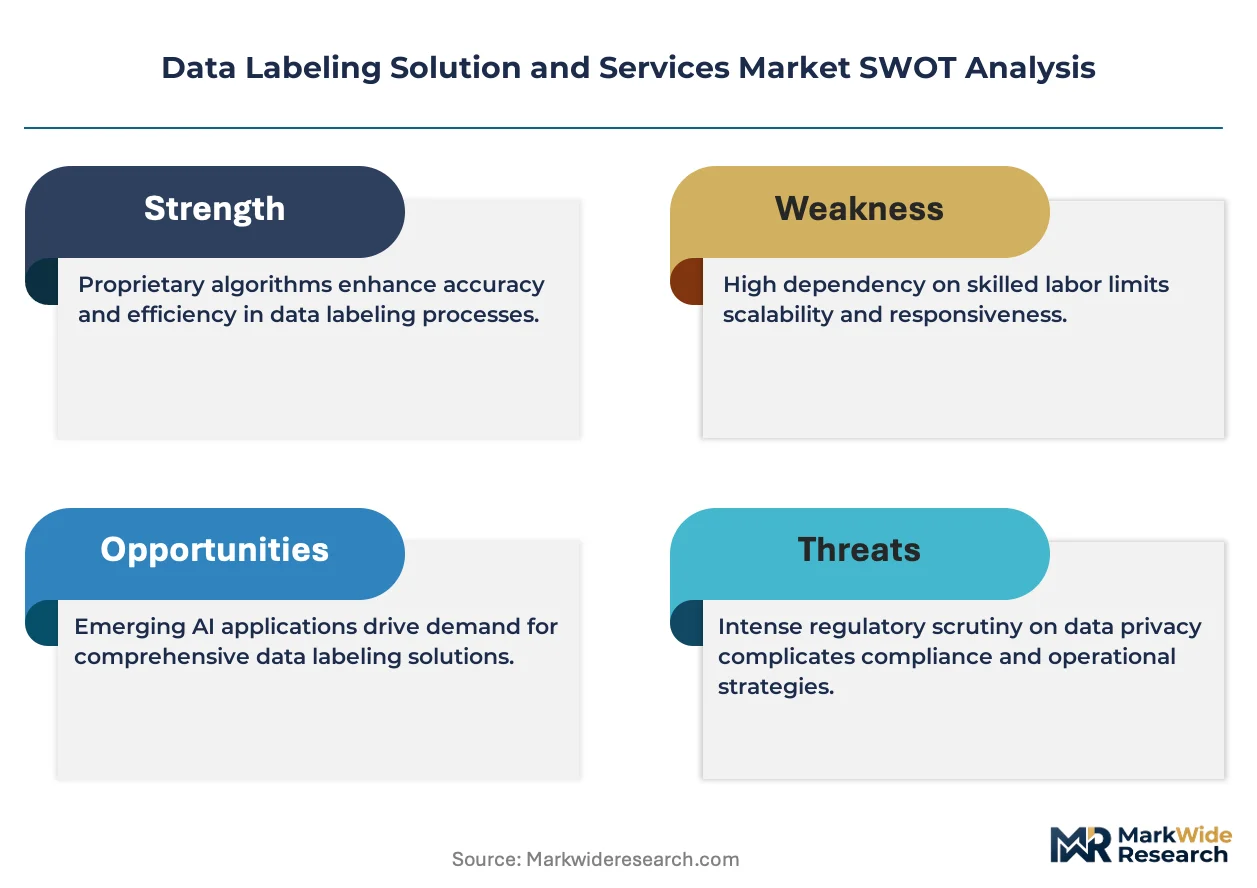
Data labeling solutions and services encompass the annotation, classification, and tagging of raw unstructured data—images, text, video, and audio—into structured formats suitable for machine-learning model training, typically delivered through cloud-based platforms with quality-control hierarchies and iterative feedback loops. Image annotation commands the largest current revenue pool due to computer-vision proliferation in automotive and retail, while text annotation accelerates fastest as large-language-model pretraining expands multilingual corpus needs. Cloud-based deployment dominates among AI-native startups seeking elastic scaling, though hybrid architectures gain traction among financial-services and healthcare providers managing sensitive data under jurisdictional constraints.
The EU AI Act imposes documentation and traceability mandates on high-risk AI training datasets, compelling labeling vendors to embed audit trails and bias-detection protocols. In the United States, the FDA's evolving software-as-medical-device framework and the NHTSA's autonomous-vehicle guidance create dual compliance tracks for healthcare and automotive labeling workflows. Stakeholders must monitor how divergent regulatory timelines across Brussels and Washington reshape vendor certification requirements and cross-border data-processing agreements.
Market Dynamics
The compression of model-training cycles from months to weeks is rebalancing labeling operations from captive teams toward hybrid in-house and outsourced arrangements, with autonomous-vehicle developers in California and Washington now demanding annotation velocity that internal workforces cannot sustain.
Growth Catalysts
- EU AI Act documentation mandates:High-risk AI training datasets now require embedded audit trails and bias-detection protocols, compelling enterprises to upgrade labeling infrastructure and expand vendor relationships.
- LiDAR segmentation demand:Autonomous-vehicle developers are scaling outsourced annotation pipelines to meet training-data velocity requirements for perception models.
- Cloud-based deployment elasticity:AI-native startups in the United States favor elastic scaling through cloud platforms over fixed-cost infrastructure investments.
Market Restraints
- Skilled annotator scarcity:Specialized domains like medical imaging and legal text require subject-matter expertise that crowdsourced workforces cannot reliably supply.
- Jurisdictional data-sovereignty rules:Financial-services and healthcare providers face constraints on cross-border data flows, fragmenting labeling operations across multiple in-country facilities.
- Quality-assurance cost escalation:Iterative feedback loops and multi-tier review hierarchies consume margin as dataset complexity rises for multimodal models.
Strategic Opportunities
- Synthetic data convergence:Generative AI and traditional annotation are converging to produce hybrid training datasets that reduce reliance on manual labeling for edge cases.
- India-based delivery centers:Underpenetrated relative to current demand, the country's multilingual workforce and cost structure attract natural-language model training contracts.
- FDA software-as-medical-device pathway:The evolving framework creates certified labeling workflows for healthcare AI, opening premium service tiers for compliant vendors.
Industry Challenges
- Annotation consistency at scale:Inter-annotator agreement degrades across distributed workforces, requiring continuous calibration protocols that slow throughput.
- Legacy system integration friction:Enterprise data pipelines built for batch processing resist real-time annotation APIs, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Labeling Solution and Services Market |
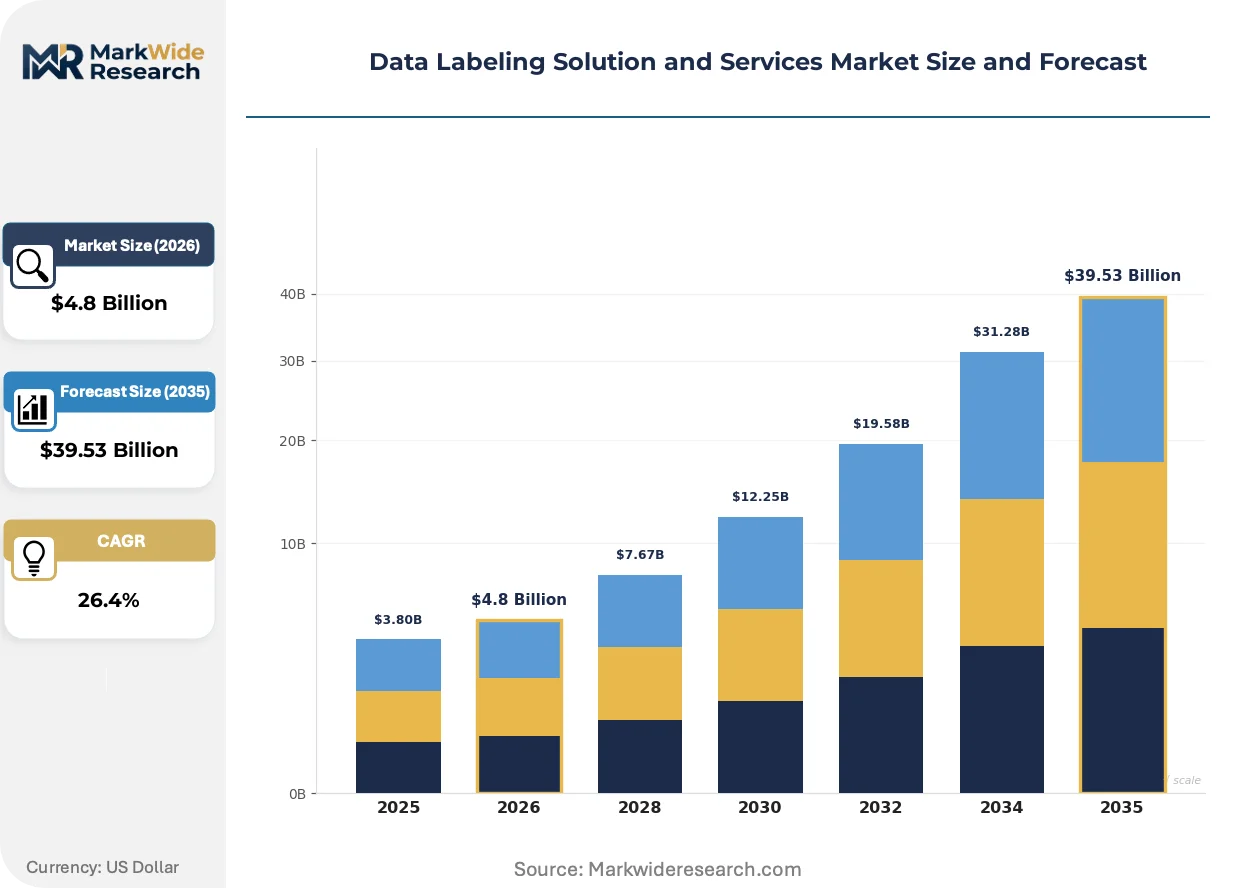
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $39.53 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Image Annotation, Text Annotation, Video Annotation, Audio Annotation Technology: Machine Learning, Natural Language Processing, Deep Learning, Human-in-the-Loop End User: Retail Industry, Automotive Sector, Healthcare Providers, Financial Services Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Appen Limited, Scale AI, Labelbox Inc., CloudFactory Limited, Cogito Tech LLC, Alegion Inc., Clickworker GmbH, Shaip, SuperAnnotate AI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Labeling Solution and Services Market Strategic Shifts & Innovations
Active learning and human-in-the-loop architectures are compressing annotation costs while synthetic data generation is displacing manual labeling for select computer-vision applications, reshaping how vendors structure workforce and technology investments.
Federated learning infrastructure is decentralizing data labeling operations by enabling model training across distributed datasets without centralizing raw data. Healthcare consortiums in Germany and pharmaceutical researchers in Switzerland are adopting this architecture to comply with GDPR and institutional review board requirements. The approach is compressing cross-border collaboration timelines while preserving jurisdictional data-sovereignty constraints.
The EU AI Act's risk-based classification system is tightening quality-assurance obligations for labeled datasets used in high-stakes applications. Automotive perception systems and medical diagnostic algorithms now face mandatory documentation and traceability requirements. European automotive suppliers are embedding bias-detection protocols directly into annotation workflows to preempt regulatory scrutiny.
Buyer concentration among hyperscaler cloud campuses and venture-backed AI labs is compressing vendor sales cycles and shifting contract structures toward outcome-based pricing. Annotation vendors serving California-based autonomous-vehicle developers now face penalty clauses for throughput shortfalls. The shift is visible most acutely in the United States, where procurement teams demand API-first integration and real-time quality dashboards.
Data Labeling Solution and Services Market Segmentation
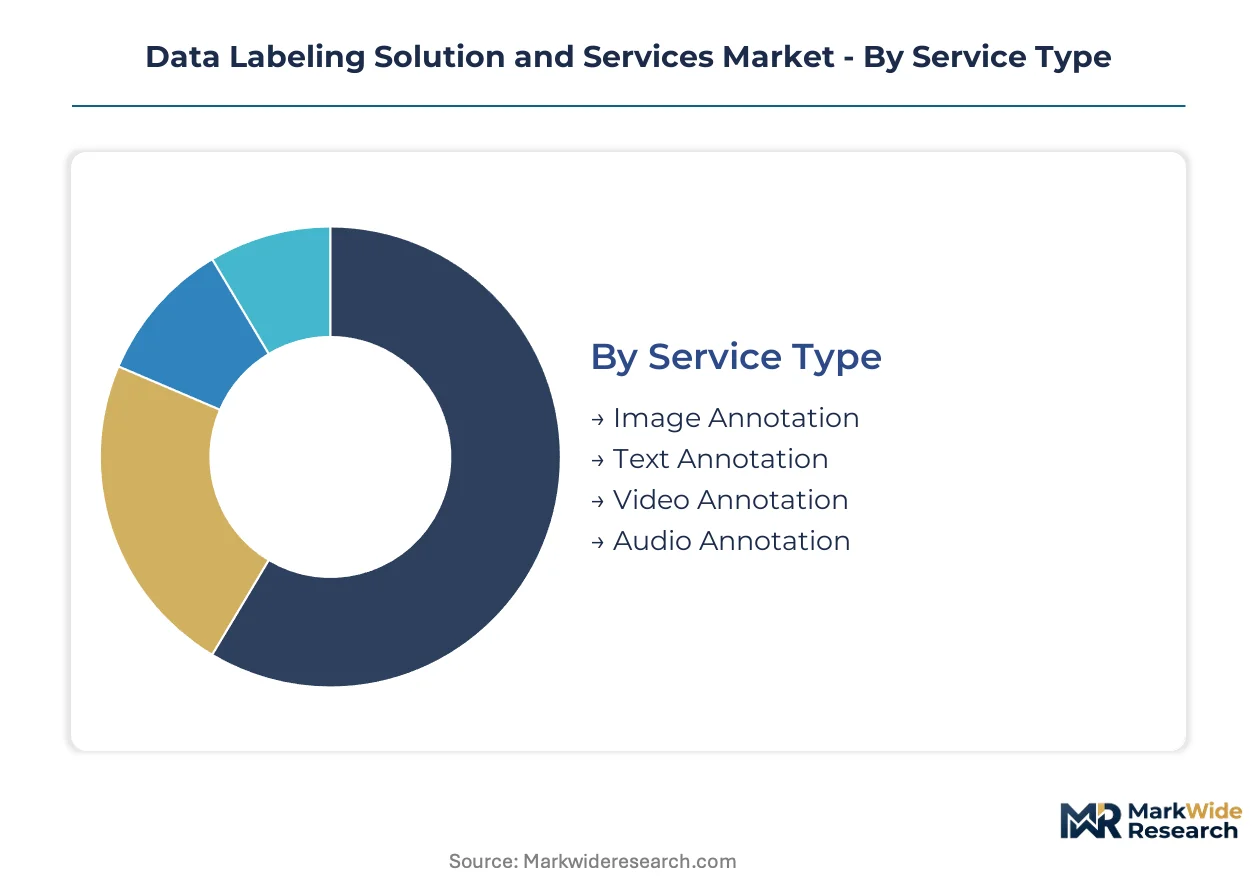
Segmentation in data labeling reveals how capital requirements, regulatory exposure, and workflow complexity fragment vendor capabilities across service modalities and deployment architectures. Understanding these divisions exposes where pricing power concentrates and where commoditization threatens margins.
Service Type:
Capital intensity varies sharply across annotation modalities, with video and LiDAR pipelines demanding specialized tooling investments that text annotation avoids.
- Image Annotation:Bounding boxes, polygons, and pixel-level segmentation for computer-vision training datasets. Automotive perception teams in California and Washington consume the majority of outsourced capacity for autonomous-vehicle development. LiDAR point-cloud segmentation commands premium pricing due to annotator scarcity and proprietary tooling requirements.
- Text Annotation:Named entity recognition, sentiment classification, and multilingual corpus structuring for large-language-model pretraining. Natural-language processing teams cluster around hyperscaler cloud campuses, driving elastic demand spikes that strain workforce availability.
- Video Annotation:Temporal object tracking and action recognition across frame sequences. Frame-by-frame labeling multiplies labor costs relative to static imagery, compressing margins for vendors lacking automated interpolation tools.
- Audio Annotation:Speech-to-text transcription, speaker diarization, and acoustic event detection. Specialized phonetic expertise for low-resource languages fragments supplier bases.
Image annotation absorbs the bulk of installed capacity; text annotation is expanding most quickly.
Technology:
Technology segmentation separates vendors by automation depth and human oversight integration, with implications for throughput economics and error-rate profiles.
- Machine Learning:Automated pre-labeling and quality scoring algorithms that reduce manual touchpoints. Retail demand for product-recognition datasets drives adoption of pre-annotation pipelines that accelerate throughput.
- Natural Language Processing:Syntactic parsing, semantic role labeling, and multilingual tokenization workflows. EU AI Act documentation mandates for high-risk language models tighten audit-trail requirements across European deployments.
- Deep Learning:Neural-network-assisted annotation for complex segmentation tasks in medical imaging and satellite imagery. GPU infrastructure costs create barriers to entry for smaller annotation providers.
- Human-in-the-Loop:Active learning architectures that route edge cases to expert reviewers while automating routine classifications. Financial services compliance teams favor this architecture for fraud-detection model training under audit scrutiny.
Human-in-the-loop architectures dominate premium pricing tiers; deep learning tooling is gaining share fastest among specialized medical and geospatial applications.
End User:
End-user segmentation maps divergent quality-assurance protocols and data-sovereignty constraints that reshape vendor selection criteria.
- Retail Industry:Product categorization, visual search training, and inventory recognition at scale. Seasonal demand surges around holiday cycles force capacity planning challenges.
- Automotive Sector:Perception-model training for autonomous-vehicle stacks, with LiDAR and camera fusion requirements. NHTSA guidance on autonomous-vehicle safety documentation imposes traceability obligations on annotation workflows.
- Healthcare Providers:Medical imaging annotation for diagnostic AI under FDA software-as-medical-device pathways. HIPAA constraints and institutional review board approvals fragment labeling operations across domestic facilities.
- Financial Services:Document extraction, KYC verification, and fraud-pattern labeling. Cross-border data-sovereignty rules force jurisdictional separation of sensitive customer datasets.
Automotive sector procurement absorbs the largest absolute spend; healthcare providers are expanding contract values fastest under regulatory compliance pressures.
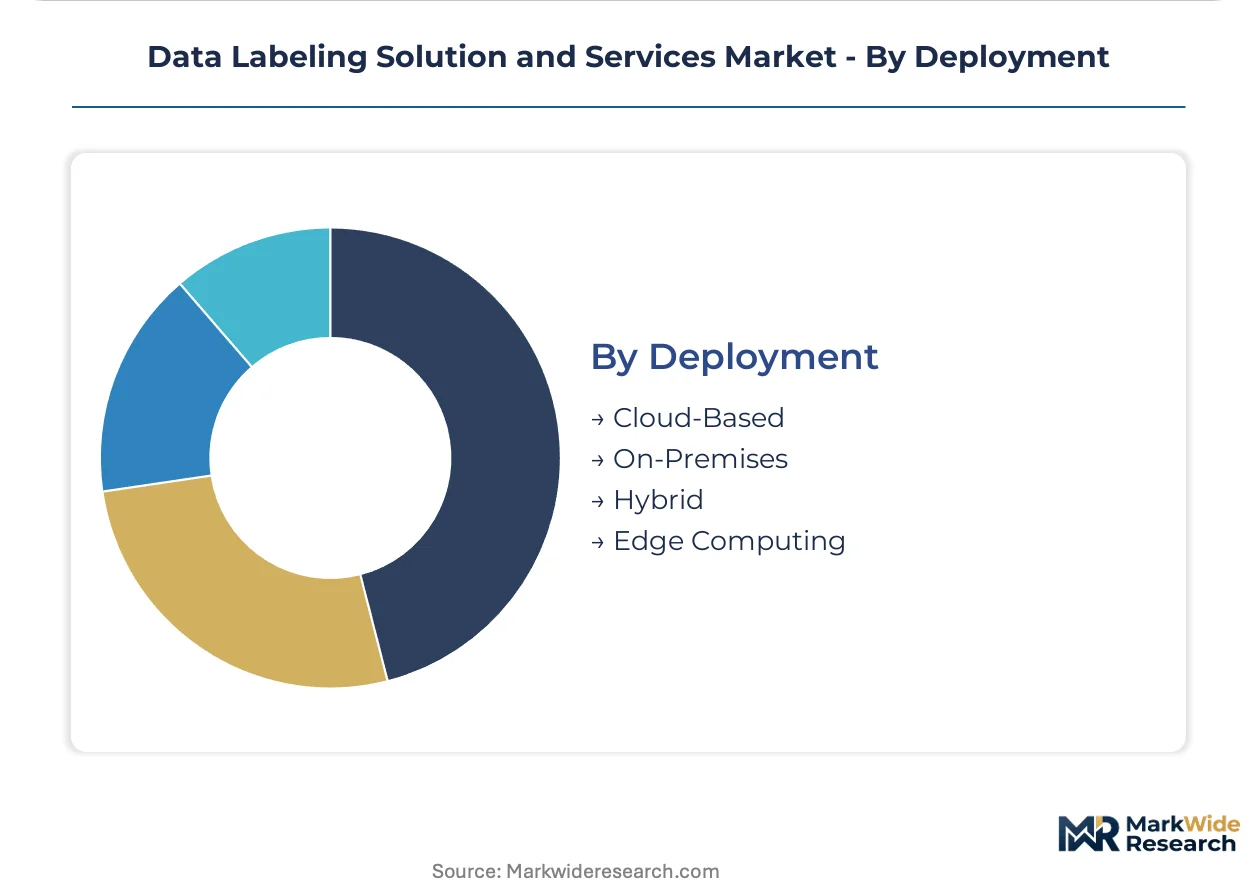
Deployment:
Deployment architecture determines capital allocation between vendor infrastructure and client-controlled environments, with security and latency trade-offs.
- Cloud-Based:Elastic scaling through API-first platforms with shared infrastructure costs. AI-native startups favor this model for variable workload patterns and minimal upfront commitment.
- On-Premises:Dedicated hardware installations within client data centers for air-gapped sensitive datasets. Defense and intelligence applications mandate this architecture regardless of cost premium.
- Hybrid:Split processing with pre-annotation in cloud and final review on-premises. Healthcare and financial services adopt this pattern to balance throughput against compliance exposure.
- Edge Computing:Distributed annotation nodes co-located with data capture sources. Manufacturing quality-control applications favor edge deployment to minimize latency in defect-detection feedback loops.
Cloud-based deployment holds the majority of active seats; hybrid architectures are climbing fastest as regulated industries seek compliance without sacrificing velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler cloud campuses and venture-backed AI labs anchor the raw compute locality driving data-labeling demand velocity across major economies.
United States
Autonomous-vehicle developers in California and Washington demand annotation throughput that internal workforces cannot sustain. The FDA's software-as-medical-device framework and the NHTSA's autonomous-vehicle guidance create dual compliance tracks for healthcare and automotive labeling workflows. Procurement teams in San Francisco and Seattle now mandate API-first integration and real-time quality dashboards.
Germany
Automotive perception systems and medical diagnostic algorithms face mandatory documentation requirements under the EU AI Act's risk-based classification. The KBA enforces traceability obligations on annotation workflows for autonomous-vehicle safety documentation. Stuttgart and Munich host embedded bias-detection protocols within supplier annotation pipelines to preempt regulatory scrutiny.
China
Computer-vision proliferation in retail and manufacturing drives image annotation demand at scale. The MIIT issues GB standards for AI training data quality that reshape vendor certification requirements. Beijing and Shenzhen clusters concentrate delivery centers serving domestic large-language-model pretraining contracts.
India
Natural-language model training contracts attract multilingual workforce capacity for corpus structuring and sentiment classification. The country's central bank and data-protection frameworks impose jurisdictional constraints on cross-border financial data flows. Bangalore and Hyderabad delivery centers scale underpenetrated capacity relative to current global demand.
Switzerland
Pharmaceutical researchers adopt federated learning architectures to comply with institutional review board requirements and preserve data sovereignty. Swissmedic oversees diagnostic AI training dataset standards that tighten quality-assurance obligations. Basel and Zurich consortiums compress cross-border collaboration timelines while maintaining GDPR-aligned protocols.
Data Labeling Solution and Services Market Key Industry Players
Global majors compete with regional champions across technology-platform and workforce-delivery dimensions, producing a tiered structure where scale-driven API providers, managed-workforce operators, and specialized tooling vendors occupy distinct competitive positions. The vendor base separates into three strategic archetypes: cloud-native platform builders with proprietary automation, crowd-sourced workforce aggregators with global reach, and managed-service operators embedding quality protocols directly into client pipelines. Dominant competitive moves include M&A to acquire automation tooling and strategic partnerships to secure anchor contracts with hyperscaler cloud campuses.
Within the cloud-native platform tier, Scale AI and Labelbox Inc. exemplify technology-first positioning through API-centric workflows and proprietary segmentation tooling. Appen Limited and CloudFactory Limited occupy the managed-workforce tier, anchoring globally distributed delivery models that emphasize quality-assurance integration. These four entities represent the structural fault lines between automation-heavy and labor-intensive service modalities.
| Leading Market Players |
|---|
| Appen Limited |
| Scale AI |
| Labelbox Inc. |
| CloudFactory Limited |
| Cogito Tech LLC |
| Alegion Inc. |
| Clickworker GmbH |
| Shaip |
| SuperAnnotate AI Inc. |
| Others |
Cost & Logistics Intelligence
The EU AI Act's risk-based classification system gates qualified supply and premium-tier pricing access, compelling vendors to embed audit trails and bias-detection protocols that separate certified providers from commodity competitors. Automotive perception teams and healthcare AI developers now pay substantial premiums for documentation-ready datasets that internal compliance teams can validate.
Pricing Analysis
Service-bundling separates vendors who include iterative quality review and regulatory documentation from those unbundling these as add-on fees. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with FDA software-as-medical-device pathway compliance commanding the highest tier. Cost compression in standard-tier image annotation intensifies as automated pre-labeling tools commoditize bounding-box work. AI-native startups exhibit the highest price sensitivity, while automotive OEMs prioritize throughput guarantees over per-unit costs.
Supply Chain Analysis
Workforce availability in India, the Philippines, and Eastern European delivery centers anchors global capacity for multilingual text annotation and specialized medical imaging review. Raw inputs draw from cloud compute infrastructure, proprietary annotation tooling licenses, and subject-matter expert labor pools. Single-source vulnerability concentrates in LiDAR segmentation specialists with proprietary 3D point-cloud platforms. Distribution runs through API-first platforms for elastic demand and managed service contracts for enterprise compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's documentation mandates have erected a cost-of-compliance moat that favors incumbent vendors with embedded quality infrastructure over lean entrants lacking certification depth.
For Market Incumbents: Extend automation tooling investments into synthetic data generation to defend margin position against pure-play labor arbitrage competitors. Scale AI and Labelbox exemplify this trajectory through proprietary LiDAR segmentation platforms. Capacity addition in India-based delivery centers secures multilingual workforce access for natural-language model training contracts. For New Entrants and Emerging Players: Cloud-native API marketplaces offer the most penetrable route for specialized tooling vendors targeting mid-market AI startups underserved by enterprise-focused incumbents. Federated learning infrastructure for healthcare consortiums represents underexploited white space in Switzerland and Germany. A compliance-first positioning against EU AI Act requirements differentiates against commodity crowd-labeled offerings. For Investors and Strategic Acquirers: FDA 510(k) clearance announcements for diagnostic AI models are the leading indicator that certified labeling workflow demand is accelerating. The five-to-ten-year viability window favors acquisition targets with healthcare regulatory expertise and automotive LiDAR tooling IP. Watch for NHTSA autonomous-vehicle safety documentation rulemaking as the signal for automotive labeling contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Proprietary LiDAR segmentation tooling commands premium pricing from California autonomous-vehicle developers. |
| Regulatory Approval Pathway | FDA software-as-medical-device certification opens healthcare AI labeling contracts with institutional review board requirements. |
| Geographic Expansion | India-based delivery centers capture natural-language model training demand from hyperscaler cloud campuses. |
| Platform Integration | API-first workflows with real-time quality dashboards satisfy procurement mandates from Seattle and San Francisco AI labs. |
| Strategic Partnership | Federated learning alliances with Swiss pharmaceutical researchers enable GDPR-compliant cross-border collaboration. |
Research Approach
Document review covered SEC filings from publicly traded data labeling vendors, EU AI Act implementation guidance, and NHTSA autonomous-vehicle safety documentation, complemented by interviews with CTOs at AI-native startups, procurement leads at automotive OEMs, regulatory affairs directors at healthcare AI developers, and workforce operations managers at managed service providers. Secondary validation drew from FDA software-as-medical-device guidance documents, hyperscaler cloud capex disclosures, and customs data on cross-border data processing services. Bottom-up capacity estimates triangulated against top-down spending analysis from enterprise AI training budgets.
Segmentation outputs reflect modeled dimensions across service type, deployment architecture, end-use industry, and technology automation depth throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating autonomous-vehicle LiDAR training data velocity and large-language-model pretraining corpus expansion. Industry-specific inputs included EU AI Act compliance cost curves and FDA diagnostic AI submission trends.
The model holds under stable regulatory implementation timelines; deviation in EU AI Act enforcement severity or NHTSA rulemaking acceleration would shift vendor certification investment returns. Forecasts assume continued hyperscaler cloud campus concentration in California and Washington. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Super Apps Market
Digital Solutions
UX Services Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Data Converter Market
Digital Solutions
Neuromarketing Solutions Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Database Management Platform Market