
 North America Enterprise Information Archiving (EIA) Market | 2026-2036
North America Enterprise Information Archiving (EIA) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Enterprise Information Archiving (EIA) Market Insights
Channel partnerships between cloud hyperscalers and compliance specialists is reshaping how enterprises procure archiving infrastructure. Proofpoint leverages its email security heritage to anchor cross-sell opportunities into regulated verticals. Commvault competes through data governance breadth that extends beyond archiving into broader information lifecycle management. Smarsh specializes in financial services compliance, dominating broker-dealer and wealth management segments where SEC Rule 17a-4 enforcement remains stringent.
Enterprise Information Archiving encompasses the systematic capture, indexing, storage, and retrieval of unstructured business communications—email, instant messages, social media, and files—within tamper-proof repositories that satisfy legal hold and audit requirements. Solutions must support immutable WORM storage, granular retention policies, and eDiscovery export formats such as PST and EDRM XML to serve litigation readiness and regulatory examination workflows. Cloud-based deployment leads absolute spending as CIOs trade capital intensity for operational elasticity, though hybrid architectures capture the fastest expansion as organizations bridge legacy on-premises tape systems with SaaS front-ends. Compliance archiving commands the deepest margin pools because financial and healthcare buyers prioritize defensibility over unit cost, while email archiving remains the highest-volume entry point.
FINRA, SEC, and HIPAA frameworks collectively dictate retention minimums, audit trail specifications, and breach notification timelines that directly shape vendor product roadmaps and enterprise procurement criteria. The SEC's Marketing Rule and FINRA's targeted examination letters on digital communications supervision have tightened enforcement, forcing wealth managers to replace grandfathered systems. State-level privacy statutes in California and emerging legislation in Canada add jurisdictional complexity to cross-border data residency decisions. Stakeholders must monitor regulatory divergence between US federal and provincial Canadian standards when architecting unified North American archiving estates.
Market Dynamics
Cloud hyperscalers are consolidating the vendor landscape by embedding compliance-grade storage into native productivity suites, forcing independent archiving specialists to differentiate through vertical AI and eDiscovery workflow depth.
Growth Catalysts
- FINRA digital communications supervision:Broker-dealers face intensified examination scrutiny on mobile messaging and social media archiving, compelling system replacements before enforcement deadlines.
- Healthcare data retention mandates:HIPAA audit protocol expansions require longer immutable storage for patient communications, driving hospital procurement of unified archiving platforms.
- AI-enabled search:Natural language processing accelerates legal hold responsiveness, reducing eDiscovery timelines from weeks to hours for litigation-ready enterprises.
Market Restraints
- Cloud egress cost volatility:Data retrieval fees from hyperscaler object storage create unpredictable budgeting for high-frequency eDiscovery users.
- Legacy tape infrastructure lock-in:Decades of on-premises WORM archives resist cloud migration due to chain-of-custody verification requirements.
- Cross-border data residency friction:Divergent provincial Canadian privacy standards complicate unified North American archiving estate architecture.
Strategic Opportunities
- Canadian banking compliance acceleration:OSFI guidance on electronic recordkeeping creates parallel procurement waves to US SEC-driven replacements.
- Slack and Teams message archiving:Collaboration platform adoption outpaces native compliance tooling, opening third-party integration white space.
- Generative AI content governance:Emerging requirements to archive AI-generated outputs and prompts establish new product categories.
Industry Challenges
- Forensic chain-of-custody expertise:Shortage of certified eDiscovery specialists delays litigation readiness validation for enterprise legal departments.
- Multi-cloud integration complexity:Hybrid environments spanning AWS, Azure, and Google Cloud require redundant compliance certification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Enterprise Information Archiving (EIA) Market |
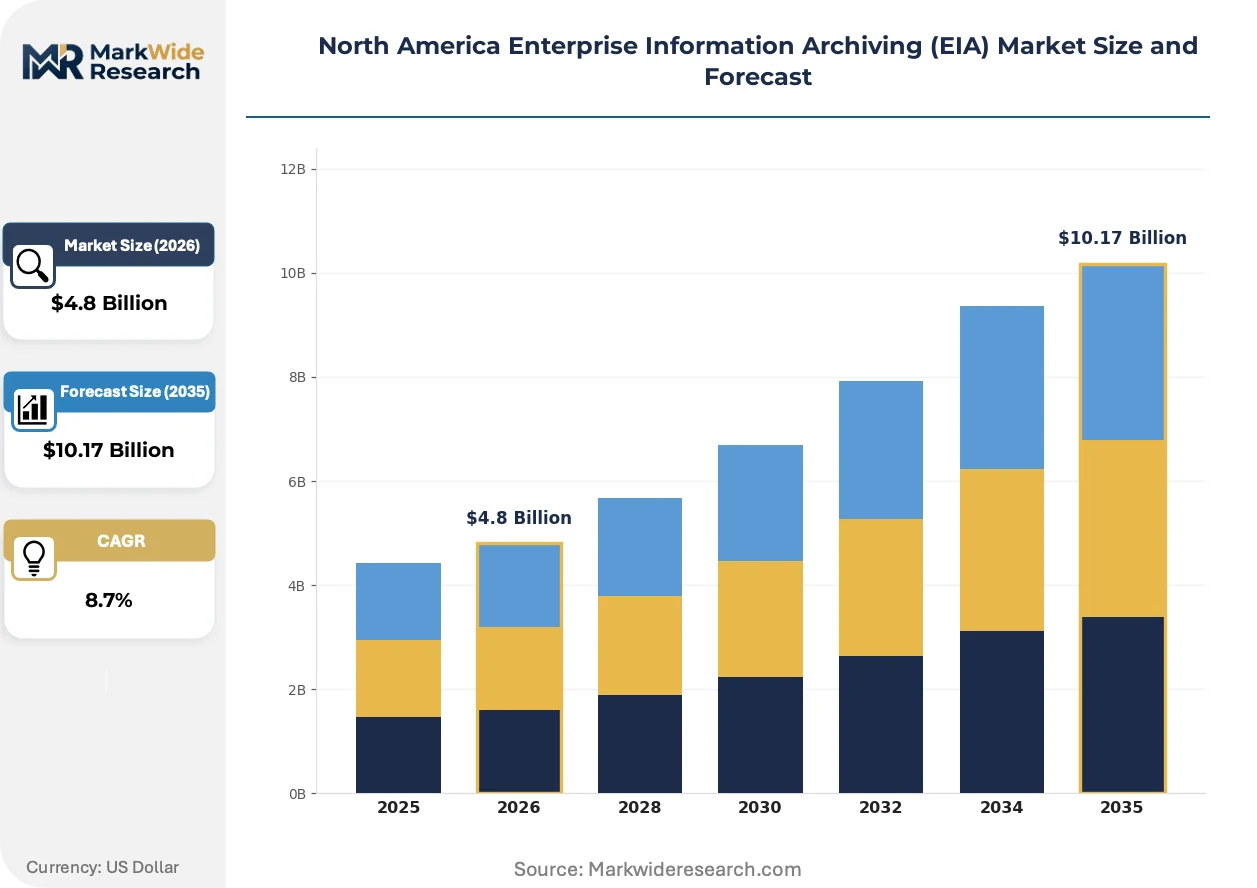
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Industry Vertical: Healthcare, Finance, Retail, Government Solution: Compliance Archiving, Email Archiving, File Archiving, Data Governance End User: Large Enterprises, SMEs, Public Sector, Non-Profits |
| Companies Covered | Proofpoint Inc, Commvault, Smarsh Inc, Global Relay Communications Inc, Veritas Technologies LLC, Barracuda Networks Inc, Microsoft, Open Text Corporation, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Enterprise Information Archiving (EIA) Market Trends and Innovations
Archiving infrastructure is converging with adjacent security and analytics stacks, blurring procurement boundaries between compliance, cybersecurity, and data governance functions.
AI-native classification engines are collapsing the distinction between archiving and active data management by enabling real-time sensitivity scoring and automated retention policy enforcement. Financial services compliance teams deploy these systems to preemptively flag communications requiring legal hold before human review. The compression of detection-to-action latency is eliminating batch-processing archival models.
SEC Marketing Rule enforcement has tightened retention requirements for investment adviser promotional materials across digital channels. Wealth management firms must now archive website content, podcast transcripts, and influencer collaboration records with the same rigor as email. This regulatory expansion is forcing technology refreshes among mid-sized registered investment advisers previously exempt from broker-dealer-grade systems.
Subscription consumption models are displacing perpetual license arrangements as legal departments prefer operational expenditure alignment to matter-based archiving needs. Enterprise procurement teams negotiate seat-based pricing tied to active user counts rather than storage volume. This shift is most pronounced among professional services firms with fluctuating headcounts and project-based litigation exposure.
North America Enterprise Information Archiving (EIA) Market Segmentation
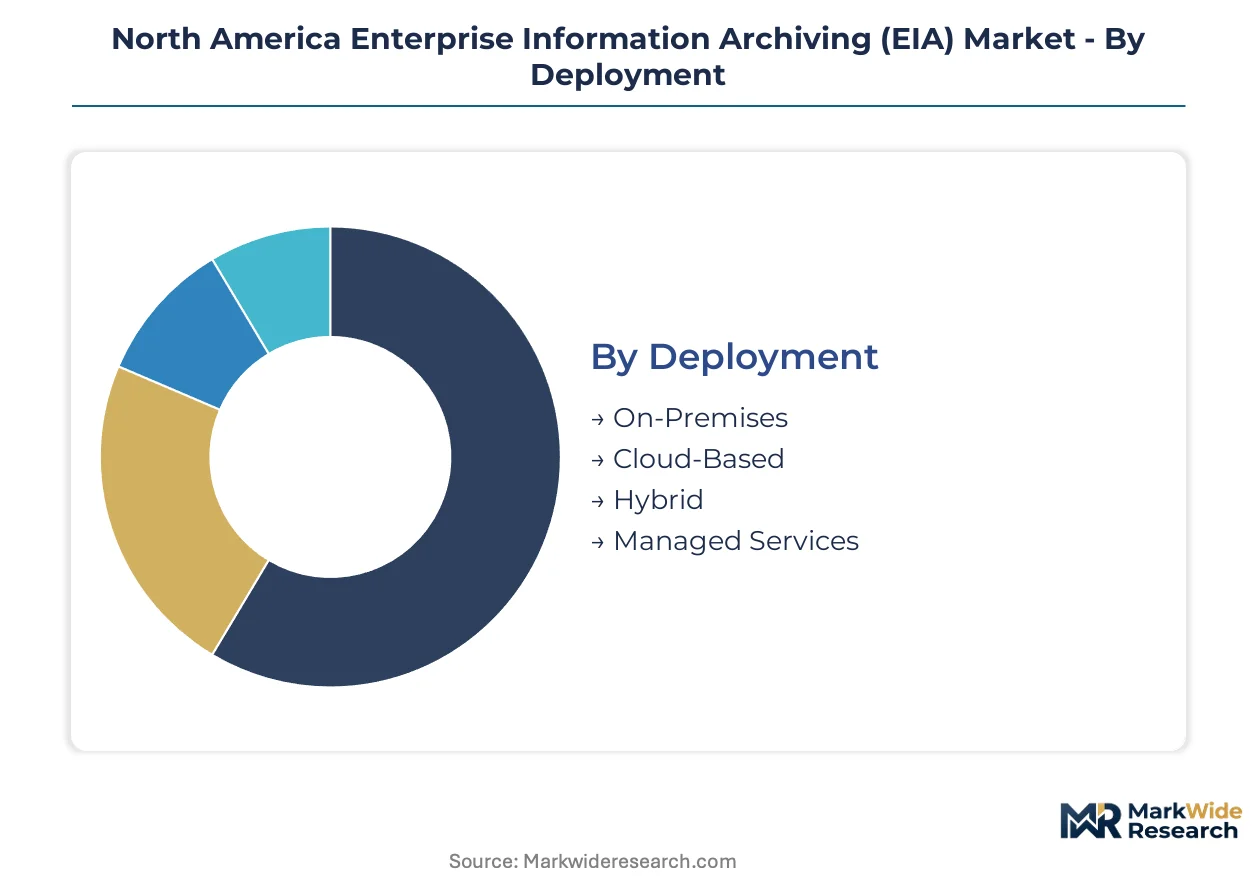
Enterprise Information Archiving procurement patterns diverge sharply across deployment models, regulatory exposure, and organizational scale. Understanding these fault lines clarifies where vendor roadmaps must align with buyer constraints.
Deployment:
Cost tier structures the deployment landscape, with capital intensity and operational elasticity trading off across buyer segments.
- On-Premises:Dedicated hardware infrastructure with localized WORM storage arrays satisfies stringent chain-of-custody requirements. Financial services firms in the United States with decades of grandfathered tape archives maintain these systems despite cloud migration pressure from SEC examination timelines.
- Cloud-Based:SaaS delivery eliminates capital expenditure and enables elastic storage scaling. Healthcare providers across Ontario and California deploy these solutions to meet HIPAA audit protocol expansions without data center overhead.
- Hybrid:Bridged architectures retain sensitive archives on-premises while pushing search indexes to cloud tiers. Canadian banking regulators' OSFI guidance accelerates hybrid adoption among Toronto-based institutions balancing US subsidiary compliance with domestic data residency.
- Managed Services:Outsourced operations transfer compliance liability to specialist operators. Mid-sized broker-dealers facing FINRA digital communications supervision deadlines contract these arrangements to accelerate deployment.
On-Premises holds installed capacity. Hybrid is rotating up the share rankings.
Industry Vertical:
Application context determines functional requirements, with regulatory intensity and litigation exposure shaping solution specifications.
- Healthcare:Patient communication archives must satisfy HIPAA retention minimums and state-level breach notification timelines. Hospital systems in Texas and Illinois prioritize immutable storage for clinical correspondence and telehealth session records.
- Finance:Broker-dealers and investment advisers face SEC Rule 17a-4 and FINRA examination standards. Wealth management firms in New York and Chicago replace grandfathered systems to archive mobile messaging and social media content under tightened Marketing Rule enforcement.
- Retail:Consumer transaction records and customer service correspondence require retention for payment card industry audits. E-commerce platforms in California manage high-volume email archiving with defensible eDiscovery export capabilities.
- Government:Federal, state, and municipal agencies maintain records under Freedom of Information Act and state sunshine laws. Public sector buyers in Washington D.C. and Ottawa prioritize tamper-proof repositories with granular access controls.
Finance commands premium pricing. Healthcare is climbing the fastest.
Solution:
Margin depth varies by functional specialization, with compliance-grade offerings capturing value over commodity storage.
- Compliance Archiving:Purpose-built repositories satisfy regulatory examination standards with audit trail completeness and legal hold automation. Financial services buyers prioritize defensibility over unit cost, deepening vendor margin pools.
- Email Archiving:High-volume capture of SMTP traffic remains the dominant entry point for enterprise procurement. Organizations across all verticals deploy these solutions first before expanding to adjacent communication channels.
- File Archiving:Structured and unstructured document repositories support long-term retention with full-text indexing. Legal departments in professional services firms leverage these systems for matter-based archival.
- Data Governance:Unified lifecycle management extends beyond retention to classification, discovery, and disposition automation. Large enterprises with complex information estates adopt these platforms to consolidate point solutions.
Compliance Archiving holds pricing power. Data Governance is gaining share fastest.
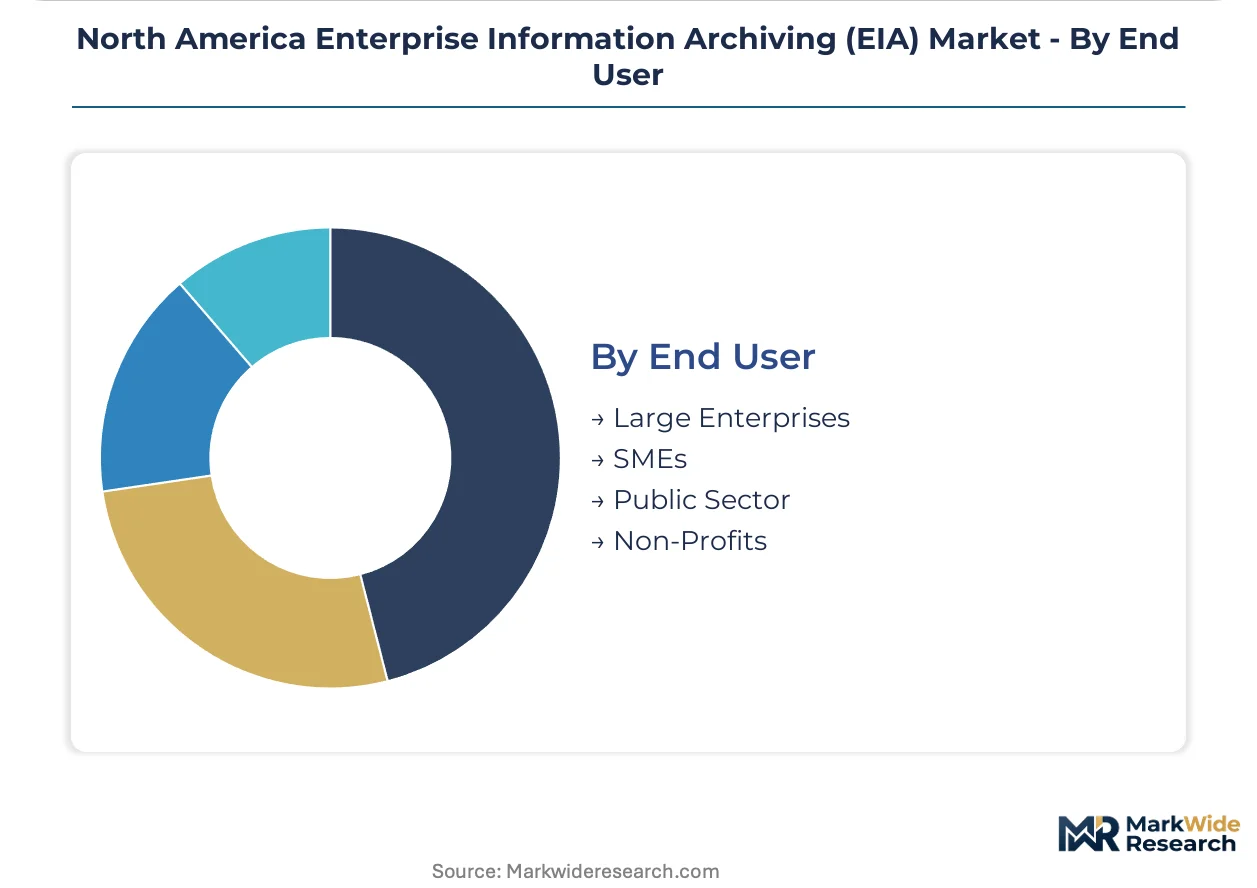
End User:
Customer type dictates procurement sophistication, with scale determining in-house capability versus outsourced dependence.
- Large Enterprises:Dedicated legal and compliance teams negotiate complex multi-year agreements with seat-based pricing. Fortune 500 firms in the United States deploy hybrid architectures spanning AWS, Azure, and Google Cloud with redundant certification maintenance.
- SMEs:Limited IT staff favor cloud-native solutions with minimal configuration overhead. Regional broker-dealers and medical practices purchase through channel partnerships with compliance specialists.
- Public Sector:Procurement governed by formal RFP processes with vendor qualification requirements. State agencies and federal departments prioritize FedRAMP and equivalent Canadian security certifications.
- Non-Profits:Constrained budgets drive preference for subscription consumption models aligned to grant funding cycles. Educational institutions and charitable organizations seek discounted licensing through consortium arrangements.
Large Enterprises anchor vendor revenue. SMEs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where SEC enforcement timelines command premium compliance budgets, while Canadian procurement operates under tighter cost constraints with OSFI-driven replacement cycles lagging 18-24 months behind US counterparts.
United States
Broker-dealers in New York and Chicago drive demand as FINRA examination scrutiny intensifies on mobile messaging archives. SEC Rule 17a-4 and Marketing Rule enforcement compel wealth managers to replace grandfathered systems ahead of regulatory deadlines. The Northeast corridor hosts the densest concentration of compliance-focused procurement teams negotiating seat-based SaaS arrangements.
Canada
Toronto-based institutions balance US subsidiary compliance with domestic data residency under OSFI electronic recordkeeping guidance. Provincial privacy divergence between Ontario, Quebec, and British Columbia complicates unified archiving estate architecture. Canadian banking regulators accelerate parallel timelines, creating procurement waves through 2025-2027 replacement cycles.
Mexico
Financial services firms in Mexico City Metro adopt cloud-native archiving as CNBV supervision of digital communications tightens. Cross-border data residency requirements for US-domiciled parent companies influence hybrid deployment preferences. Northern border states concentrate procurement activity tied to maquiladora supply chain documentation needs.
North America Enterprise Information Archiving (EIA) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular capture and indexing engines. The vendor landscape consolidates around cloud hyperscalers embedding compliance storage into productivity suites, while independent specialists defend position through vertical AI depth. Three archetypes dominate: security-platform extenders, data governance generalists, and compliance-native specialists. Strategic moves concentrate on channel partnerships with hyperscalers and AI-enabled workflow acquisitions.
Within the compliance-native tier, Smarsh Inc and Proofpoint Inc exemplify divergent heritage strategies—Smarsh anchoring financial services specialization, Proofpoint extending email security dominance into archiving cross-sells. Commvault occupies a position bridging data governance breadth with archiving adjacency, representing the generalist archetype competing through information lifecycle management scope rather than point compliance depth.
| Leading Market Players |
|---|
| Proofpoint Inc |
| Commvault |
| Smarsh Inc |
| Global Relay Communications Inc |
| Veritas Technologies LLC |
| Barracuda Networks Inc |
| Microsoft |
| Open Text Corporation |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler cloud infrastructure concentration in the United States concentrates margin capture downstream with compliance-native software vendors who layer regulatory defensibility atop commodity storage. Buyers absorb egress cost volatility while specialists extract premiums for AI-enabled search and legal hold automation.
Pricing Analysis
Configured-to-order deployments for hybrid architectures command substantial premiums over standard SaaS tiers due to legacy tape integration complexity. Three-tier pricing structure across premium compliance-grade, standard enterprise, and economy cloud-native levels stratifies the market, with FINRA-regulated broker-dealers showing least price sensitivity and mid-sized healthcare providers most. Cost compression in economy tiers intensifies because hyperscalers embed basic archiving into productivity suites. Certification investment in SEC Rule 17a-4 and HIPAA audit readiness drives price differentiation between defensible and commodity offerings.
Supply Chain Analysis
Upstream feedstock for archiving infrastructure draws from semiconductor fabrication in Taiwan and South Korea, enterprise storage manufacturing in the United States, and hyperscaler data center buildouts across Virginia, Oregon, and Quebec. Component dependencies include high-density NAND flash, specialized WORM tape media, and GPU clusters for AI indexing. Single-source vulnerability in advanced node semiconductors creates supply chain risk for on-premises appliance vendors. Distribution runs through direct enterprise sales teams, channel partnerships with compliance specialists, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American Enterprise Information Archiving represents a service-attach opportunity where managed compliance operations and AI-enabled eDiscovery subscriptions expand faster than base storage provisioning.
For Market Incumbents: Pre-empt hyperscaler encroachment by deepening vertical AI workflows for financial services litigation readiness. Anchor defensible market position through certification maintenance across AWS, Azure, and Google Cloud simultaneously. Acquire specialized eDiscovery boutiques to collapse detection-to-action latency below batch-processing competitors. For New Entrants and Emerging Players: Build out Slack and Teams archiving integrations where native compliance tooling lags collaboration adoption. Target mid-sized Canadian wealth managers facing OSFI electronic recordkeeping deadlines with rapid-deployment managed services. Lead with seat-based pricing aligned to active user counts rather than storage volume. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-native specialists with entrenched FINRA examination relationships rather than generalist data governance platforms. Long-term viability hinges on AI content governance capabilities for emerging generative AI archival requirements. Monitor SEC enforcement letter volume as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Classification Engine Development | Real-time sensitivity scoring collapses detection-to-action latency for legal hold workflows. |
| Hyperscaler Marketplace Partnership | Channel placement in AWS Marketplace and Azure Marketplace accelerates procurement velocity. |
| Vertical Acquisition of eDiscovery Boutique | Forensic chain-of-custody expertise shortage creates scarcity value for certified specialists. |
| Hybrid Architecture Certification Investment | Simultaneous AWS, Azure, and Google Cloud compliance certification defends against lock-in. |
| Generative AI Content Governance Product Launch | Archiving AI-generated outputs and prompts establishes defensible positioning in emerging category. |
Research Methodology
A standing panel of chief compliance officers, legal operations directors, FINRA examination consultants, and hyperscaler solution architects provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC enforcement actions, FINRA examination letters, HIPAA audit protocols, and hyperscaler capex disclosures. Bottom-up deployment modeling and top-down regulatory mandate sizing were triangulated to converge on market estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning deployment model, organization size, vertical regulatory intensity, and cross-border data residency complexity. CAGRs were derived from regulatory deadline pacing and replacement cycle timing rather than extrapolation. Modeled inputs included FINRA examination volume trends, SEC Marketing Rule enforcement patterns, and cloud egress fee trajectories.
Stress conditions across hyperscaler pricing volatility, legacy migration friction, and provincial Canadian privacy divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and cloud adoption curves. Cross-checking against vendor-reported seat counts and channel partner pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Video Management System Market
Digital Solutions
France Digital Twin Market
Digital Solutions
United States ICT Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Weather App Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
South Africa ICT Market
Digital Solutions
India ICT Market
Digital Solutions
Email Deliverability Tools Market