
 Europe Online Dating Services Market | 2026-2036
Europe Online Dating Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Dating Services Market Foresight
Young professional demand for relationship-oriented platforms is realigning product roadmaps across the sector. Match Group Inc. leverages its portfolio breadth to sustain cross-brand user migration across European markets. Bumble Inc. differentiates through women-first messaging architecture that anchors premium tier willingness-to-pay in Nordic and German cities. Parship Group GmbH specializes in psychometric compatibility scoring that dominates the German-speaking premium segment.
Europe online dating services encompass digital platforms that facilitate romantic partner discovery through algorithmic profile matching, real-time communication infrastructure, and subscription-gated feature access, operating primarily on cloud-native architectures with AI-driven recommendation engines. These services serve commercial purposes by converting user engagement into recurring revenue through tiered access models and in-app transaction layers. Mobile Applications capture the dominant share of session volume as smartphone-native behavior displaces desktop onboarding across all age cohorts. Premium Membership subscriptions concentrate margin pools among users over 35 seeking reduced ad exposure and enhanced visibility controls. Freemium models drive top-of-funnel acquisition among Young Adults while creating upgrade pathways through limited daily interaction caps.
The EU Digital Services Act and GDPR impose algorithmic transparency obligations and consent-driven data processing standards that elevate compliance costs for matching engine operators. EASA guidelines on dark pattern prohibition in digital interfaces directly constrain auto-renewal design practices across subscription flows. Platform operators must monitor regulatory enforcement divergence between Brussels-level harmonization and member state data protection authority interpretations to anticipate compliance investment requirements.
Market Dynamics
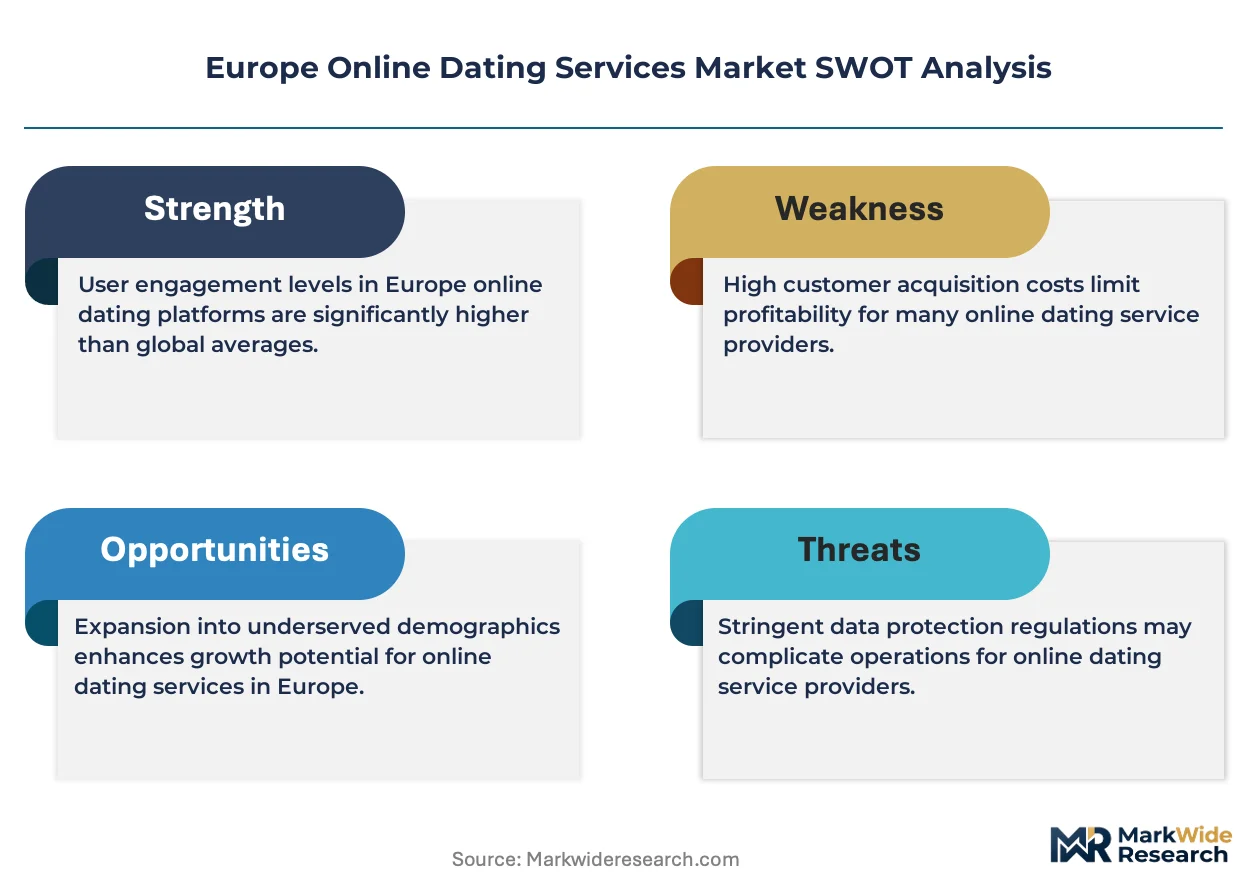
Algorithmic transparency mandates under the EU Digital Services Act are forcing platform operators to reengineer matching engines and consent architectures, elevating compliance investment as a structural cost layer distinct from R&D.
Growth Catalysts
- GDPR-compliant data portability:User control over profile data reduces switching friction and expands addressable pools for relationship-oriented platforms.
- Professionals aged 30-45:This cohort's preference for long-term partnership platforms commands premium subscription pricing and reduces churn volatility.
- Psychometric compatibility scoring:Standardized personality assessment integration deepens user investment and extends session duration metrics.
Market Restraints
- Algorithmic audit costs:The EU Digital Services Act mandates external review of recommendation engine logic, adding fixed compliance overhead.
- Dark pattern prohibition:EASA guidelines constrain auto-renewal interface design, compressing subscription conversion rates.
- Cloud infrastructure concentration:Reliance on hyperscale providers for real-time matching creates single-point vulnerability in data residency requirements.
Strategic Opportunities
- Nordic premium tier expansion:Copenhagen, Stockholm, and Oslo exhibit elevated willingness-to-pay for women-first messaging architectures.
- AI-driven conversation assistance:Natural language generation tools reduce cold-start friction for users initiating contact.
- Video verification protocols:Real-time identity confirmation addresses catfishing concerns and reduces moderation staffing intensity.
Industry Challenges
- Cross-border data localization:Member state divergence in GDPR enforcement creates fragmented engineering requirements for pan-European operators.
- Psychometric assessment standardization:Absence of validated compatibility metrics complicates product differentiation claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Dating Services Market |
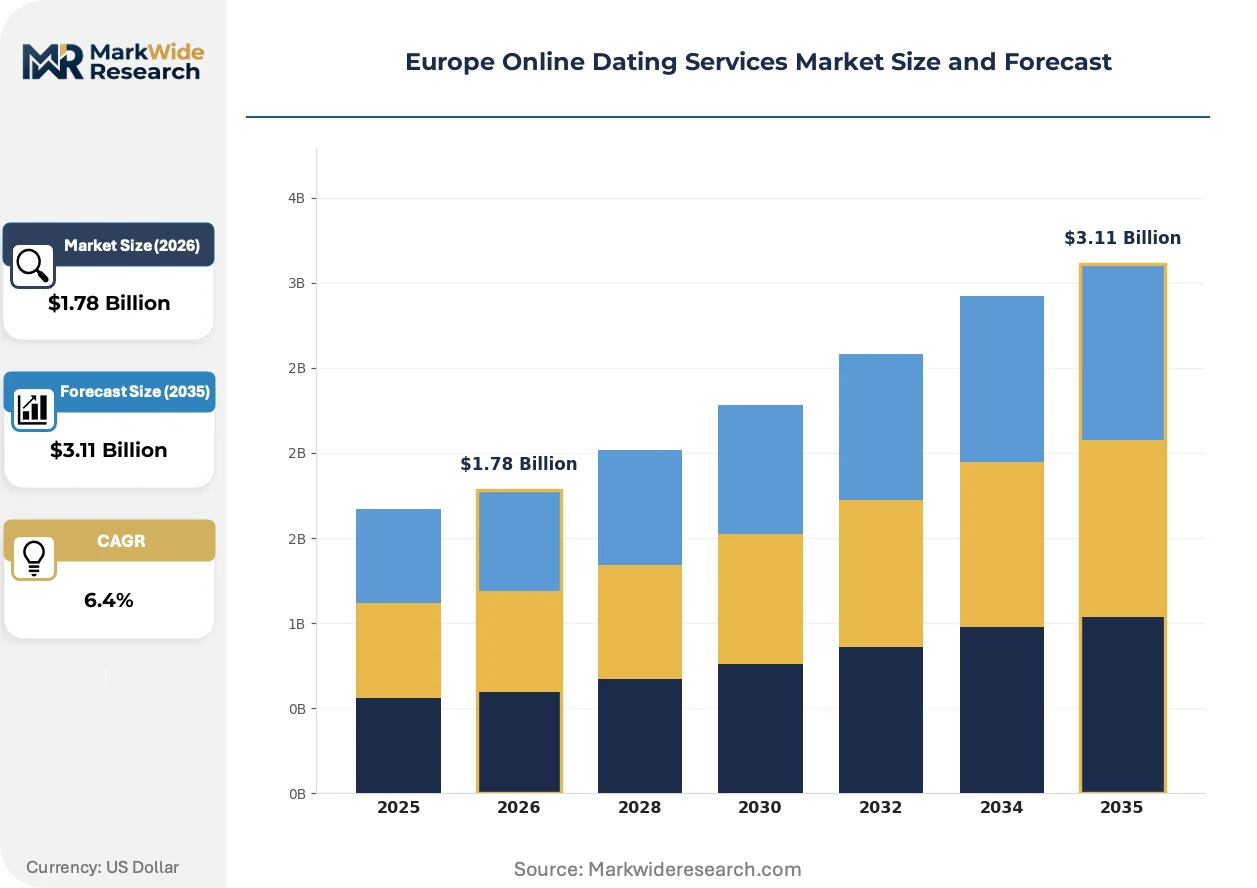
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Applications, Desktop Platforms, Matchmaking Services, Video Dating Subscription Model: Freemium, Monthly Subscription, One-Time Payment, Premium Membership User Demographic: Young Adults, Seniors, Professionals, LGBTQ+ Engagement Feature: Chat Functions, Video Calls, Virtual Events, Personality Tests |
| Companies Covered | Match Group Inc., Bumble Inc., Badoo Ltd., Happn (FTW and Co), Meetic SA, Parship Group GmbH, Spark Networks SE, Grindr Inc., ProSiebenSat.1 Media SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Dating Services Market Shifts & Advancements
Behavioral authentication and synthetic media detection are reshaping trust infrastructure across European platforms. Product roadmaps increasingly prioritize safety technology over feature expansion.
Video-first profile formats are overtaking static image galleries as the default user presentation layer. Young Adults in German metropolitan areas adopt video onboarding at the fastest clip. This format compression reduces misrepresentation incidents and elevates moderation automation feasibility.
The EU Digital Services Act's algorithmic transparency provisions require disclosure of ranking parameters in recommendation engines. Platform operators must document matching criteria for regulatory inspection. German and French data protection authorities are conducting the first wave of enforcement audits.
Subscription fatigue among Young Adults is fragmenting payment commitment patterns toward micro-transaction models. One-off visibility boosts and message prioritization tokens displace monthly recurring charges. This shift concentrates in UK urban markets where discretionary entertainment spending faces compression.
Europe Online Dating Services Market Segmentation
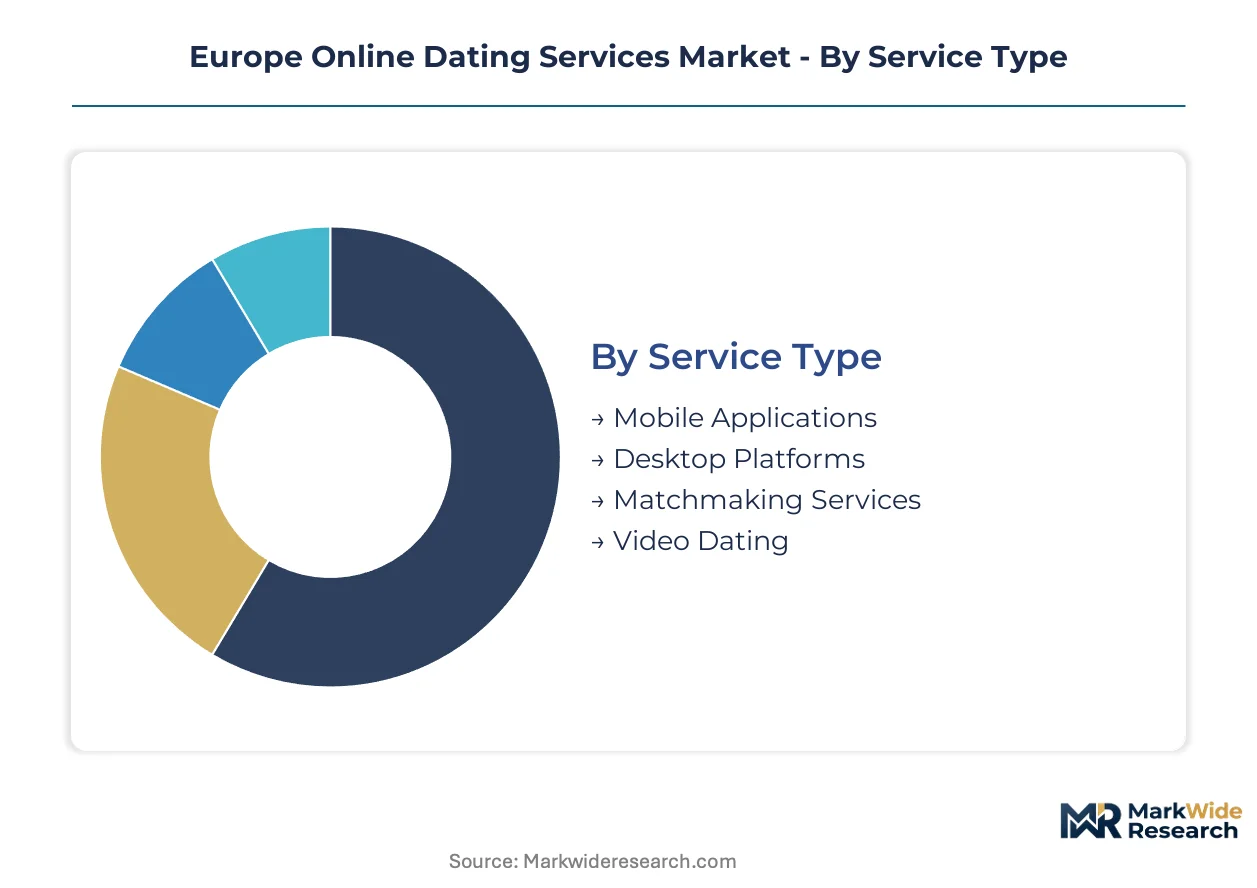
Segmentation in Europe online dating services reveals how platform operators architect revenue capture around device behavior, payment psychology, and life-stage relationship goals. Each dimension exposes distinct margin profiles and compliance exposure under EU Digital Services Act transparency mandates.
Service Type:
Device-native behavior and real-time infrastructure requirements drive platform selection decisions across European user cohorts.
- Mobile Applications:Native iOS and Android architectures dominate session volume through push-notification engagement loops and location-based matching. German and French urban professionals aged 30-45 generate the highest in-app purchase conversion rates for premium tier unlocks.
- Desktop Platforms:Browser-based interfaces retain utility for detailed profile curation and extended messaging sessions. UK subscribers over 50 exhibit persistent desktop preference for compatibility questionnaire completion, sustaining niche revenue pools despite aggregate decline.
- Matchmaking Services:Human-curated introductions command elevated price points through personalized screening and date coordination. Nordic markets concentrate demand for concierge-tier relationship brokerage.
- Video Dating:Real-time audiovisual infrastructure reduces catfishing incidents while elevating bandwidth and moderation costs. Stockholm and Copenhagen show fastest adoption among privacy-conscious demographics.
Mobile Applications lead on scale; Video Dating leads on momentum.
Subscription Model:
Payment commitment psychology and revenue predictability shape operator preference for recurring versus transactional monetization architectures.
- Freemium:Gated feature access drives top-of-funnel acquisition with daily interaction caps creating upgrade urgency. UK Young Adults exhibit highest propensity for micro-transaction conversion over monthly commitments.
- Monthly Subscription:Recurring billing anchors cash flow predictability for established platforms with retention-optimized onboarding flows. German-speaking markets sustain lowest churn rates among 35-plus demographics seeking ad-free experiences.
- One-Time Payment:Lifetime access or visibility boost purchases appeal to episodic users with low engagement frequency. French metropolitan markets concentrate this behavior among seasonal relationship seekers.
- Premium Membership:Tiered annual commitments bundle enhanced visibility controls and algorithmic priority ranking. Professionals aged 30-45 in Frankfurt, Munich, and Hamburg drive category expansion.
Premium Membership leads on scale; Freemium leads on momentum.
User Demographic:
Life-stage relationship intent and disposable income concentration determine platform positioning and feature development priorities.
- Young Adults:Users aged 18-29 prioritize volume-based discovery with low friction onboarding and social media integration. UK and Irish urban markets concentrate this segment's discretionary entertainment spending compression.
- Seniors:Users over 60 demand simplified interfaces and enhanced safety verification with relationship-oriented community norms. Paris and Berlin exhibit fastest-growing cohort concentration for dedicated silver-dating platforms.
- Professionals:Time-constrained users aged 30-45 seeking long-term partnership command highest willingness-to-pay for curated matching and reduced browsing burden. This demographic concentrates in German, Swiss, and Austrian metropolitan corridors.
- LGBTQ+:Identity-specific platforms and inclusive feature sets address safety concerns and community validation needs. Amsterdam, Copenhagen, and Barcelona sustain elevated platform loyalty and advocacy metrics.
Professionals leads on scale; Seniors leads on momentum.
Engagement Feature:
Communication modality selection reflects user comfort with synchronous interaction and trust establishment velocity.
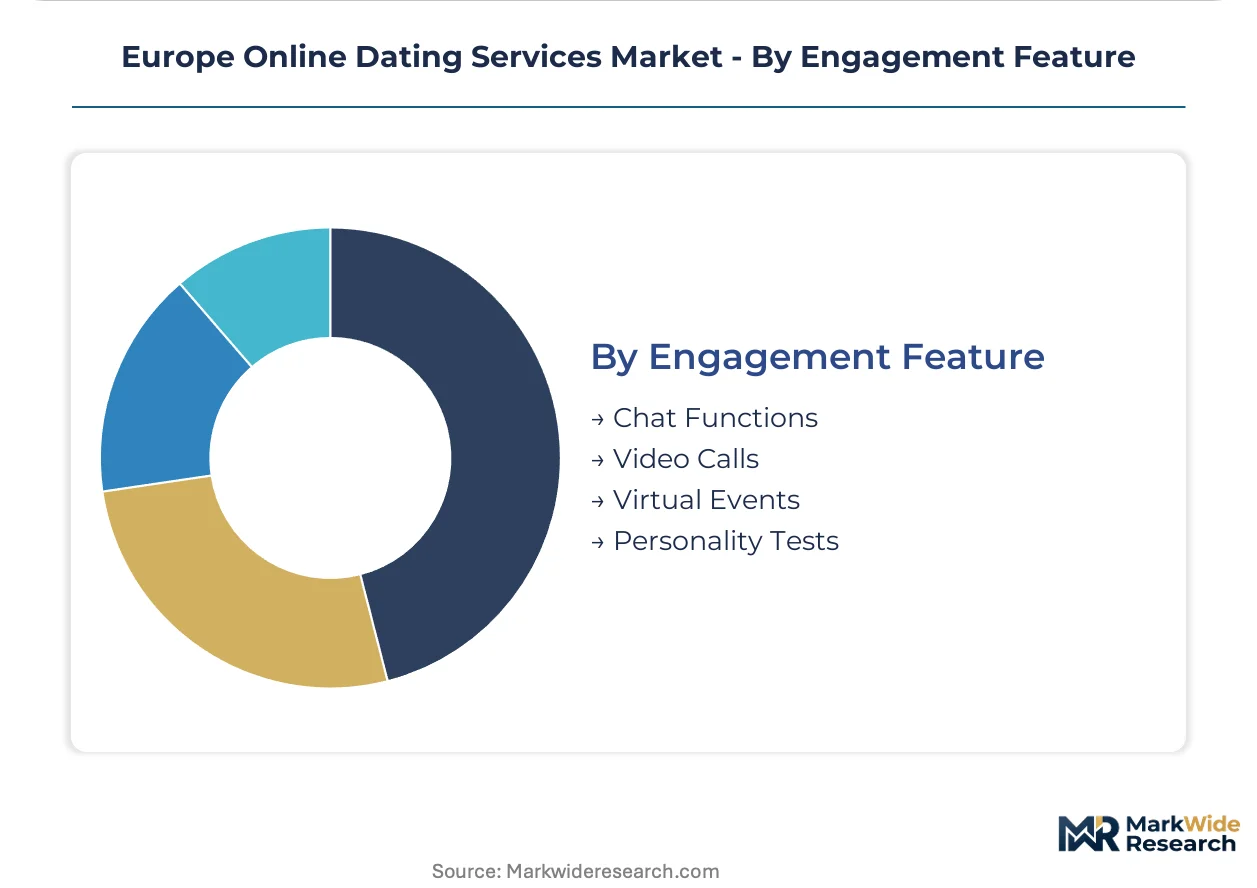
- Chat Functions:Asynchronous text messaging remains the default interaction layer with read receipts and typing indicators driving engagement loops. GDPR consent frameworks complicate message retention policies across German and French enforcement jurisdictions.
- Video Calls:In-app synchronous video reduces escalation friction to offline meetings while elevating real-time moderation requirements. Nordic cities adopt fastest due to existing comfort with digital service integration.
- Virtual Events:Group-based synchronous experiences create low-pressure discovery environments with community-building effects. UK lockdown-era adoption sustained post-pandemic among Young Adult cohorts.
- Personality Tests:Psychometric assessment integration deepens profile investment and extends session duration while creating differentiation for premium positioning. German-speaking markets exhibit highest completion rates for compatibility scoring protocols.
Chat Functions leads on scale; Video Calls leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping platform operations as compliance cost differentials between member states influence data center placement and engineering team distribution. GDPR enforcement intensity varies substantially across national data protection authorities, creating operational complexity for pan-European operators.
Germany
Psychometric compatibility scoring and premium subscription tiers command highest willingness-to-pay among Frankfurt and Munich professionals aged 30-45. The Federal Data Protection Authority (BfDI) enforces stringent algorithmic audit requirements under GDPR. Berlin anchors the largest engineering cluster for matching engine development.
United Kingdom
Micro-transaction models and freemium conversion pathways concentrate among London and Manchester young adults facing discretionary spending compression. The Information Commissioner's Office (ICO) scrutinizes dark pattern prohibition in subscription flows. Edinburgh sustains growing demand for senior-oriented platform features.
France
Seasonal relationship seekers in Paris and Lyon drive one-time payment adoption for episodic platform usage. The Commission Nationale de l'Informatique et des Libertés (CNIL) leads enforcement of EU Digital Services Act transparency mandates. Marseille exhibits emerging concentration for video-first profile formats.
Sweden
Women-first messaging architectures capture elevated premium tier adoption in Stockholm and Gothenburg. The Swedish Authority for Privacy Protection (IMY) coordinates Nordic alignment on consent-driven data processing standards. Malmö hosts specialized moderation technology development for real-time video verification.
Netherlands
LGBTQ+ platform loyalty and community validation features sustain above-average retention in Amsterdam and Rotterdam. The Autoriteit Persoonsgegevens (AP) enforces cross-border data localization requirements for pan-European operators. Eindhoven clusters AI-driven conversation assistance tooling development.
Europe Online Dating Services Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators extend cross-brand user migration pathways and algorithmic infrastructure reuse. The market exhibits consolidated characteristics at the holding-company level with fragmented brand-level positioning. Three archetypes prevail: portfolio conglomerates with multi-brand architectures, women-first messaging specialists, and psychometric compatibility purists. M&A activity and vertical integration into proprietary matching engine development represent the primary competitive vectors.
Within the portfolio conglomerate tier, Match Group Inc. and Spark Networks SE exemplify multi-brand consolidation strategies spanning casual and relationship-oriented positioning. Bumble Inc. anchors the women-first messaging specialist archetype with premium tier architecture optimized for Nordic and German urban markets. Parship Group GmbH occupies the psychometric scoring purist position with dominant share of German-speaking premium segments.
| Leading Market Players |
|---|
| Match Group Inc. |
| Bumble Inc. |
| Badoo Ltd. |
| Happn (FTW and Co) |
| Meetic SA |
| Parship Group GmbH |
| Spark Networks SE |
| Grindr Inc. |
| ProSiebenSat.1 Media SE |
| Others |
Supply & Pricing Matrix
Cloud compute spot pricing indices cascade through matching engine infrastructure costs, compressing margin pools for tier-two operators while hyperscale-leveraged incumbents absorb volatility through committed-use discounts. This input-cost asymmetry stratifies platform pricing power between established portfolio operators and emerging entrants.
Pricing Analysis
Direct-to-consumer subscription flows bypass intermediary margin layers entirely, concentrating pricing control with platform operators. Three-tier pricing structure across premium, standard, and economy levels segments willingness-to-pay by age cohort and relationship intent. Price differentiation hinges on algorithmic priority ranking depth and ad exposure reduction levels. Cost compression in standard-tier subscriptions is intensifying because GDPR compliance investments elevate fixed cost bases. Young Adults exhibit highest price sensitivity; Professionals aged 30-45 show lowest sensitivity due to time-scarcity premiums.
Supply Chain Analysis
Regional distribution centers for real-time video infrastructure cluster in Frankfurt, Amsterdam, and Stockholm to minimize latency for synchronous matching features. Cloud hyperscale providers in Ireland, Germany, and France anchor compute supply for algorithmic recommendation engines. Raw material dependencies center on GPU accelerator chips, fiber optic bandwidth, and renewable energy certificates for carbon-neutral data center claims. Single-source vulnerability in NVIDIA GPU supply chains creates procurement risk for AI-driven matching platforms. Distribution runs through direct API integration with mobile operating systems rather than physical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on psychometric assessment automation reducing human curation costs while premium-tier Professionals segment absorbs compliance-driven price increases. Operators capturing this dual lever will outpace competitors locked in freemium conversion struggles.
For Market Incumbents: Anticipate regulatory audit intensity escalation from German and French data protection authorities by pre-positioning algorithmic documentation infrastructure. Consolidate matching engine development in Berlin engineering clusters to capture talent density and BfDI relationship continuity. Defensive priority rests on proprietary psychometric IP acquisition to block Parship Group GmbH expansion vectors. For New Entrants and Emerging Players: Enter via video-first profile format specialization targeting Marseille and Copenhagen adoption clusters where incumbent positioning remains thin. White-space concentration sits in senior-oriented platform features for Paris and Berlin demographics with simplified interface requirements and enhanced safety verification. Go-to-market angle should leverage micro-transaction models displacing monthly commitments among UK Young Adults. For Investors and Strategic Acquirers: Asymmetric upside sits with women-first messaging architecture specialists holding Nordic premium tier penetration. Long-term viability favors operators with in-house matching engine development rather than hyperscale-dependent infrastructure. Acquisition target archetype: psychometric scoring platforms with validated compatibility metrics. Signal to watch: enforcement divergence between Brussels-level Digital Services Act harmonization and member state data protection authority interpretations.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Documentation | BfDI and CNIL audit readiness elevates compliance moats against undercapitalized competitors. |
| Psychometric IP Acquisition | Validated compatibility scoring captures German-speaking premium segment pricing power. |
| Video Verification Infrastructure | Real-time identity confirmation reduces moderation staffing intensity for Stockholm operators. |
| Nordic Premium Tier Expansion | Women-first messaging architectures command elevated willingness-to-pay in Copenhagen and Oslo. |
| Micro-Transaction Model Deployment | One-off visibility boosts displace monthly commitments among UK Young Adult discretionary compressors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with platform product managers, data protection compliance officers, subscription revenue analysts, and mobile UX researchers alongside secondary validation. Regulatory filings from BfDI, CNIL, ICO, and IMY anchored enforcement intensity calibration. App session data, cloud infrastructure capex disclosures, and tiered subscription pricing datasets supplied demand-side inputs. Bottom-up subscriber modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked historical subscription conversion patterns to projected freemium upgrade pathways across the analysis window. Segmentation dimensions spanned service type, subscription model, user demographic, and engagement feature complexity. CAGRs derived from cohort retention curves and pricing elasticity estimates. Forecast inputs incorporated GDPR compliance cost trajectories and Digital Services Act implementation timelines.
Inputs from data protection authority enforcement databases and platform financial disclosures were available through the study window; gaps in real-time algorithmic audit cost transparency introduce uncertainty bands around compliance investment projections. Forecasts reflect documented assumptions on regulatory harmonization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Weather App Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Revenue Management Solutions Market