
 Automatic Identification and Data Capture Market | 2026-2036
Automatic Identification and Data Capture Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Identification and Data Capture Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD), which requires detailed supply chain verification, is restructuring demand for advanced AIDC solutions. Zebra Technologies Corporation leverages its strong position in mobile computing and barcode scanning to serve logistics and retail customers navigating these new compliance demands. Cognex Corporation specializes in machine vision systems for high-speed manufacturing and quality assurance applications. Meanwhile, Honeywell International Inc. competes across a broad spectrum of end-user verticals with its extensive portfolio of data capture hardware and software.
Automatic Identification and Data Capture encompasses technologies designed to identify objects, gather data, and feed it directly into computer systems without manual entry. These systems utilize methods such as optical imaging for barcodes or radio waves for Radio Frequency Identification (RFID) tags. The primary commercial purpose is to improve data accuracy and operational speed in inventory management, asset tracking, and access control. While Barcode Scanning remains a foundational technology, RFID is gaining significant traction in high-volume logistics. Mobile Readers and Wearable Devices are the fastest-growing product segments, valued for their operational flexibility in dynamic environments like warehouses and retail floors.
The regulatory environment significantly shapes market requirements, with standards like ISO/IEC 18000 governing RFID air interface protocols. In healthcare, mandates such as the U.S. FDA's Unique Device Identification (UDI) system and the EU's Falsified Medicines Directive (FMD) compel item-level serialization. These regulations make robust AIDC systems essential for compliance in the pharmaceutical and medical device industries. The critical decision for end-users now involves balancing the cost-effectiveness of passive RFID for basic tracking against the superior real-time location data provided by active RFID systems.
Market Dynamics
The central force shaping the Automatic Identification and Data Capture market is the convergence of regulatory pressure for supply chain transparency and the strategic need for operational automation. Mandates like the EU's Corporate Sustainability Reporting Directive are accelerating investment in granular tracking technologies.
Growth Catalysts
- EU Falsified Medicines Directive:This regulation compels pharmaceutical supply chains to adopt item-level serialization, directly driving demand for 2D barcode scanners and RFID systems for compliance.
- Industrial Automation in China:A national strategic priority for industrial upgrading fuels large-scale deployment of AIDC in manufacturing and export hubs for process control and logistics efficiency.
- RFID Cost Reduction:Advances in tag manufacturing and reader technology lower the per-item cost of passive RFID, making it viable for high-volume applications like retail inventory management.
Market Restraints
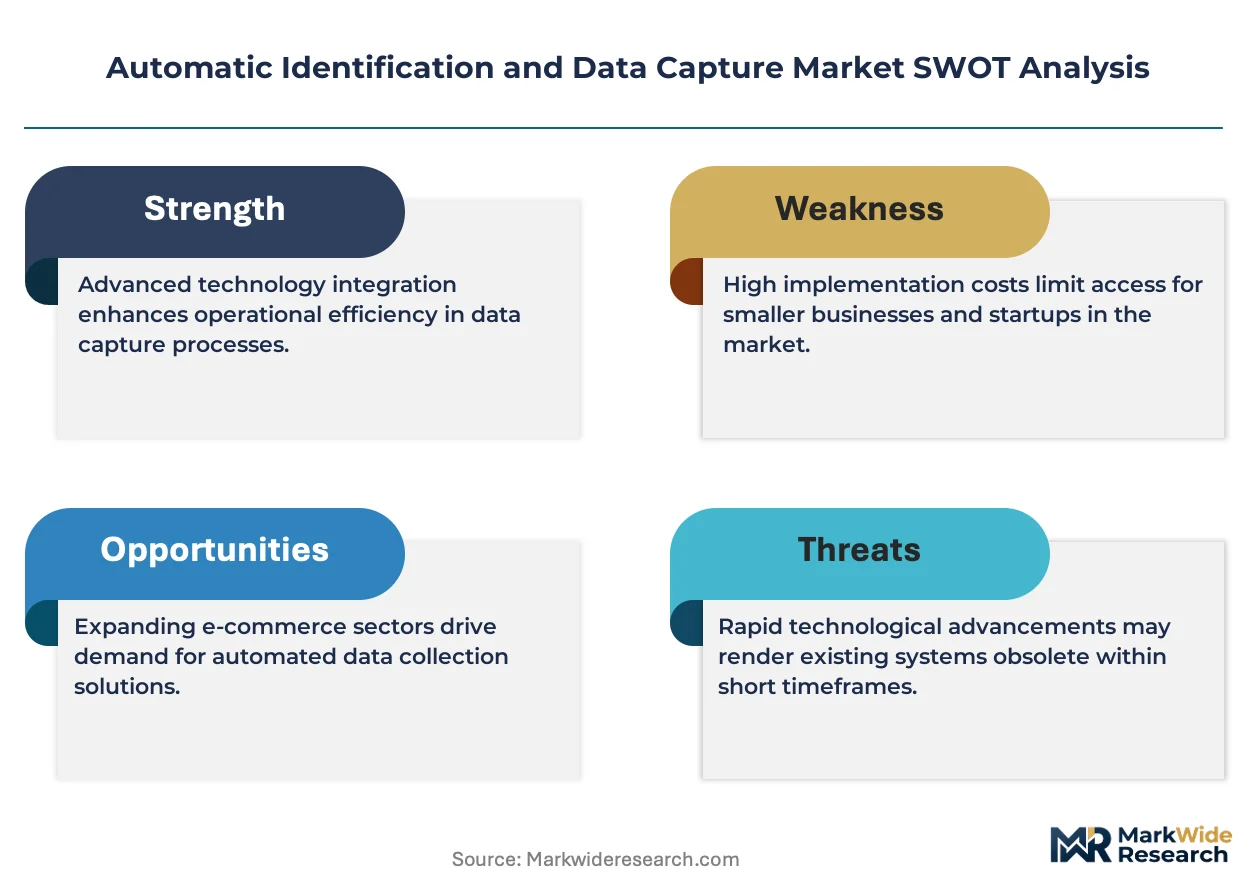
- High Initial Capex:The significant upfront investment required for active RFID infrastructure, including readers and software integration, deters adoption among small and medium-sized enterprises.
- System Interoperability:A lack of universal standardization across proprietary AIDC platforms creates integration challenges with existing Enterprise Resource Planning and Warehouse Management Systems.
- RF Signal Interference:In dense industrial environments with significant metal and liquid presence, radio frequency interference can degrade the read-rate accuracy of RFID systems, limiting reliability.
Strategic Opportunities
- Food Traceability:Growing consumer and regulatory demand for farm-to-fork transparency creates an opportunity for AIDC solutions, particularly QR codes and NFC tags, in the food and beverage industry.
- Healthcare Asset Management:Beyond regulatory compliance, hospitals can deploy RFID to track high-value mobile medical equipment, reducing loss and improving utilization rates across facilities.
- Convergence with AI:Integrating AIDC data streams with artificial intelligence platforms enables predictive analytics for inventory forecasting, demand planning, and supply chain risk identification.
Industry Challenges
- Data Security and Privacy:Protecting the sensitive operational data collected by AIDC systems from cyber threats is a critical challenge, especially with the proliferation of networked RFID readers in public spaces.
- Legacy System Integration:The complexity and cost of integrating modern AIDC technologies with outdated IT infrastructure in established manufacturing and logistics facilities slows down deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Identification and Data Capture Market |
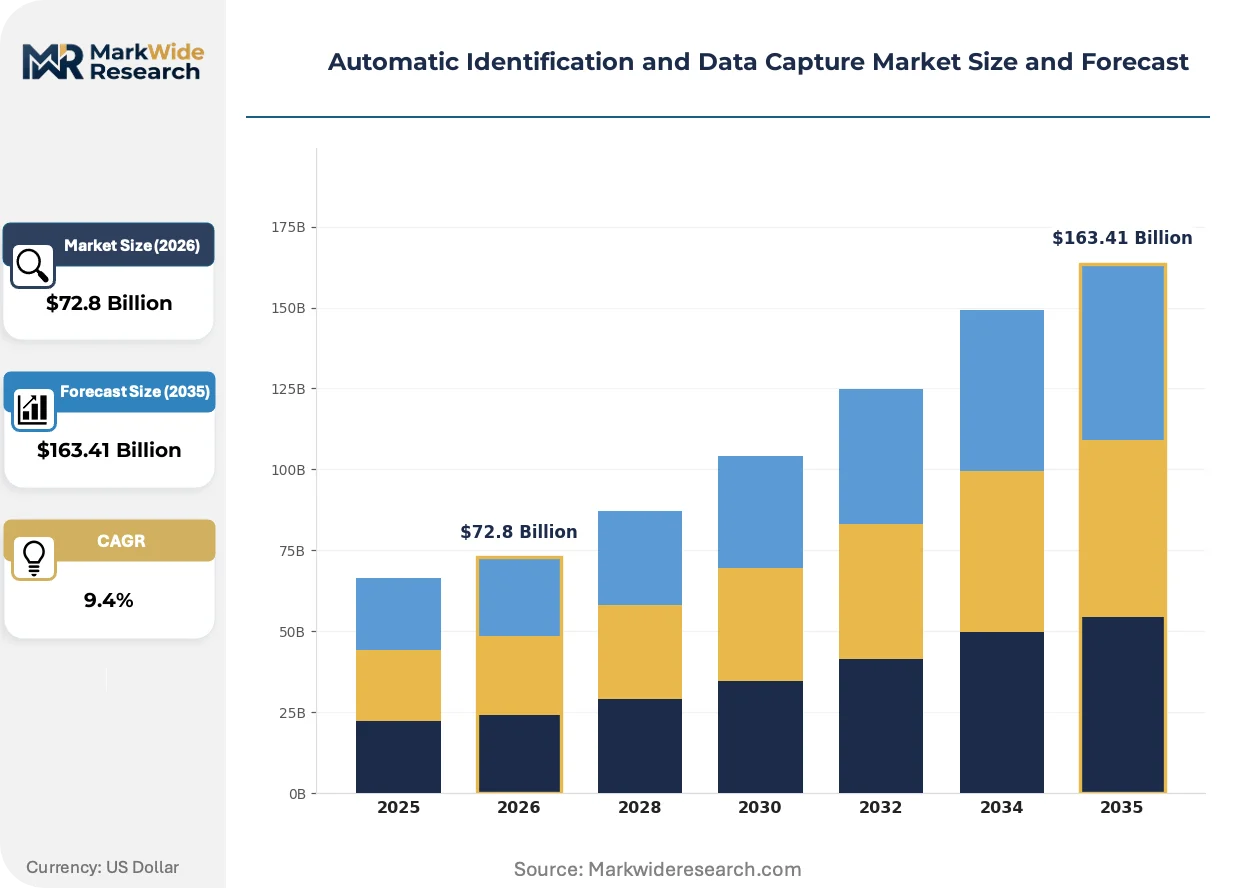
| Market Size in 2026 | $72.8 Billion |
| Market Size in 2035 | $163.41 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Barcode Scanning, Radio Frequency Identification, Magnetic Stripe, Optical Character Recognition, Biometric Recognition, Voice Recognition Application: Asset Tracking, Inventory Management, Access Control, Workforce Management, Document Verification, Supply Chain Monitoring Product Type: Fixed Readers, Mobile Readers, Wearable Devices, Sensors, Smart Cards, Labels End User Industry: Manufacturing, Transportation & Logistics, Retail, Government & Defense, Education, Telecommunications |
| Companies Covered | Cognex Corporation, Toshiba Tec Corporation, Zebra Technologies Corporation, Impinj Inc., Panasonic Corporation, Honeywell International Inc., SICK AG, Avery Dennison Corporation, Datalogic S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Identification and Data Capture Market Strategic Shifts & Innovations
Market evolution is defined by the transition from passive data collection to active intelligence. The integration of AIDC with IoT and advanced analytics is creating systems that not only identify but also interpret and predict operational events, generating actionable insights from raw data.
Machine vision represents a key AIDC technology that utilizes cameras and AI-based software for identification and quality inspection. High-speed manufacturing and logistics sectors are rapidly adopting it for automated sorting and defect detection. This technology is expanding into process optimization, using visual data to adjust production lines in real-time and moving beyond simple pass-fail analysis.
The U.S. FDA’s Unique Device Identification system mandates distinct identifiers for medical devices, tracked through a central database. This rule compels manufacturers to implement robust 2D barcode or RFID systems for item-level serialization and tracking. The medical device and diagnostics segments are most affected, investing heavily in compliant data capture hardware and management software.
A notable shift from one-time capital equipment purchases toward service-based consumption models is altering buying behavior. This disrupts the traditional hardware sales channel, creating space for providers offering AIDC-as-a-Service bundles that include hardware, software, and support. This trend is most prominent among mid-sized retail and e-commerce firms in North America seeking operational agility without large upfront costs.
Automatic Identification and Data Capture Market Segmentation
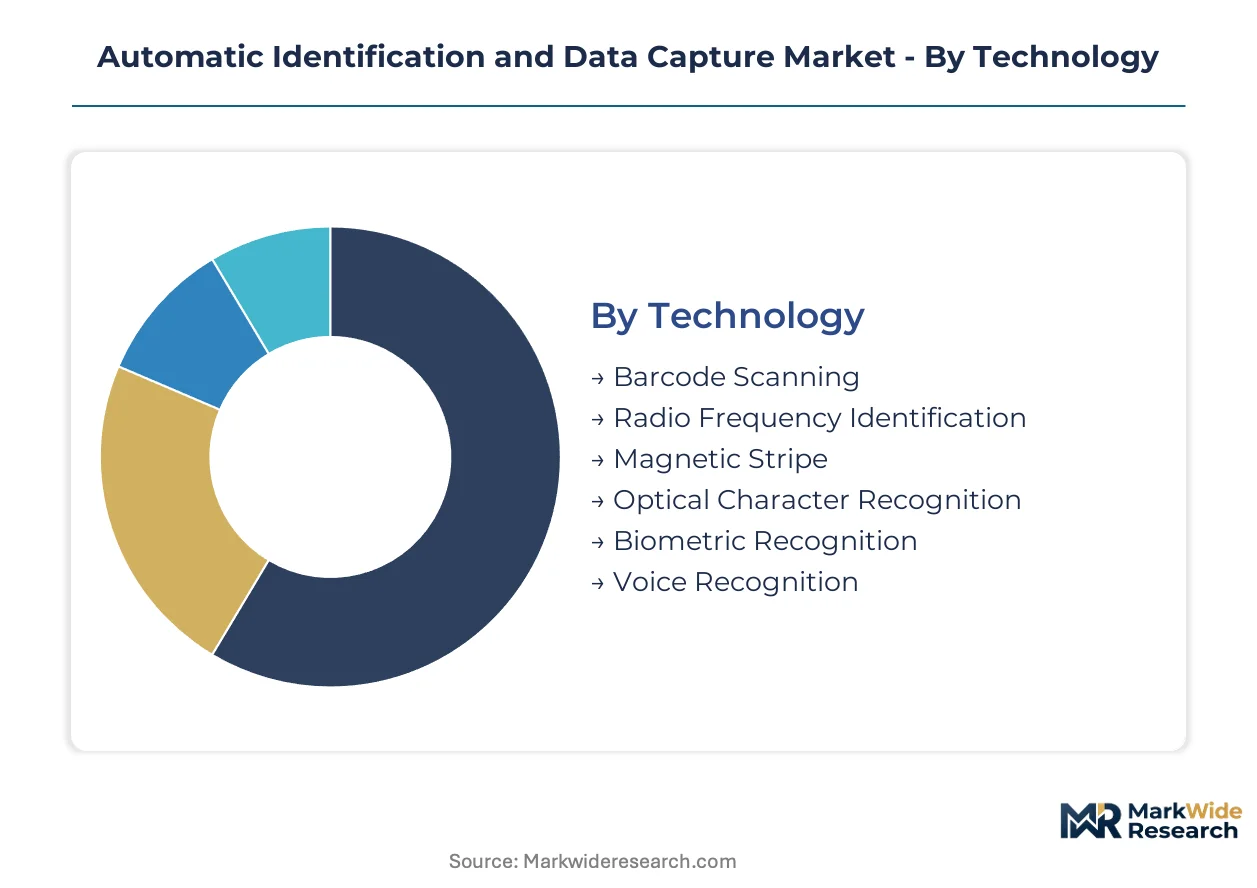
The Automatic Identification and Data Capture market categorizes technologies and solutions based on their technical characteristics, operational applications, product formats, and target industries. Understanding these segments is critical for identifying specific demand drivers and investment concentrations across the diverse AIDC ecosystem.
Technology:
The capital intensity of AIDC technologies varies significantly, influencing deployment strategies across industries.
- Barcode Scanning:This foundational technology utilizes optical readers to decode data from linear or 2D barcodes, offering cost-effective identification. Demand remains high in retail point-of-sale and warehouse receiving for efficient data entry.
- Radio Frequency Identification:RFID systems use radio waves to read data stored on tags, enabling automated tracking without line-of-sight. Its adoption is accelerating in high-volume logistics and inventory management due to falling tag costs and enhanced accuracy.
- Magnetic Stripe:Magnetic stripe technology stores data on a strip of magnetic material, primarily used in access control and payment cards. Its use is gradually declining as more secure and versatile alternatives emerge.
- Optical Character Recognition:OCR converts images of typed or handwritten text into machine-readable text, serving applications in document processing and data digitization.
- Biometric Recognition:Biometric systems identify individuals based on unique physical or behavioral characteristics like fingerprints or facial patterns, securing access control and workforce management.
- Voice Recognition:Voice recognition technology interprets spoken language, enabling hands-free data input in dynamic environments like warehouses and field services.
Barcode Scanning absorbs the bulk of installed capacity; Radio Frequency Identification is expanding most quickly.
Application:
The scope of AIDC applications ranges from internal operational efficiencies to external compliance requirements.
- Inventory Management:AIDC solutions streamline the tracking and management of goods within warehouses and retail stores, optimizing stock levels and reducing manual errors. This application is crucial for e-commerce fulfillment and manufacturing production lines.
- Supply Chain Monitoring:These applications provide real-time visibility into the movement of goods across the entire supply chain, from raw materials to final delivery. Regulatory mandates like the EU's CSRD drive demand for granular traceability in global logistics.
- Asset Tracking:Asset tracking involves monitoring the location and status of physical assets, such as equipment or vehicles, to improve utilization and prevent loss. Healthcare facilities use RFID for high-value medical equipment.
- Access Control:AIDC technologies manage and restrict entry to secure areas or systems, enhancing security protocols for facilities and data centers.
- Workforce Management:Solutions optimize employee scheduling, time tracking, and task allocation, often integrating with biometric or badge-based systems.
- Document Verification:This application uses AIDC to authenticate documents, reducing fraud and ensuring compliance in legal and administrative processes.
Inventory Management remains a primary driver for operational efficiency, while Supply Chain Monitoring is a critical factor for regulatory compliance.
Product Type:
Deployment flexibility dictates the suitability of various AIDC product types for dynamic operational environments.
- Mobile Readers:Handheld devices equipped with scanning or RFID reading capabilities offer portability and flexibility for data capture in diverse settings. These are widely adopted in retail, logistics, and field service operations.
- Wearable Devices:Compact, body-worn devices such as ring scanners or head-mounted displays enable hands-free operation, significantly boosting productivity in warehouses and manufacturing. Their ergonomic design reduces user fatigue.
- Fixed Readers:Permanently installed devices at choke points or entry/exit points automatically capture data as items pass by. They are common in automated production lines and distribution centers.
- Sensors:AIDC sensors detect and measure physical properties, often integrated with other systems for environmental monitoring or process control.
- Smart Cards:Smart cards embed microchips for data storage and processing, primarily used for secure identification, access, and payment applications.
- Labels:Labels incorporate barcodes or RFID tags, serving as the physical medium for data storage and identification across various products and assets.
Mobile Readers and Wearable Devices are paramount for real-time data access and operational flexibility in dynamic environments.
End User Industry:
Industry-specific regulatory mandates and operational priorities heavily influence AIDC solution adoption across diverse end-user sectors.
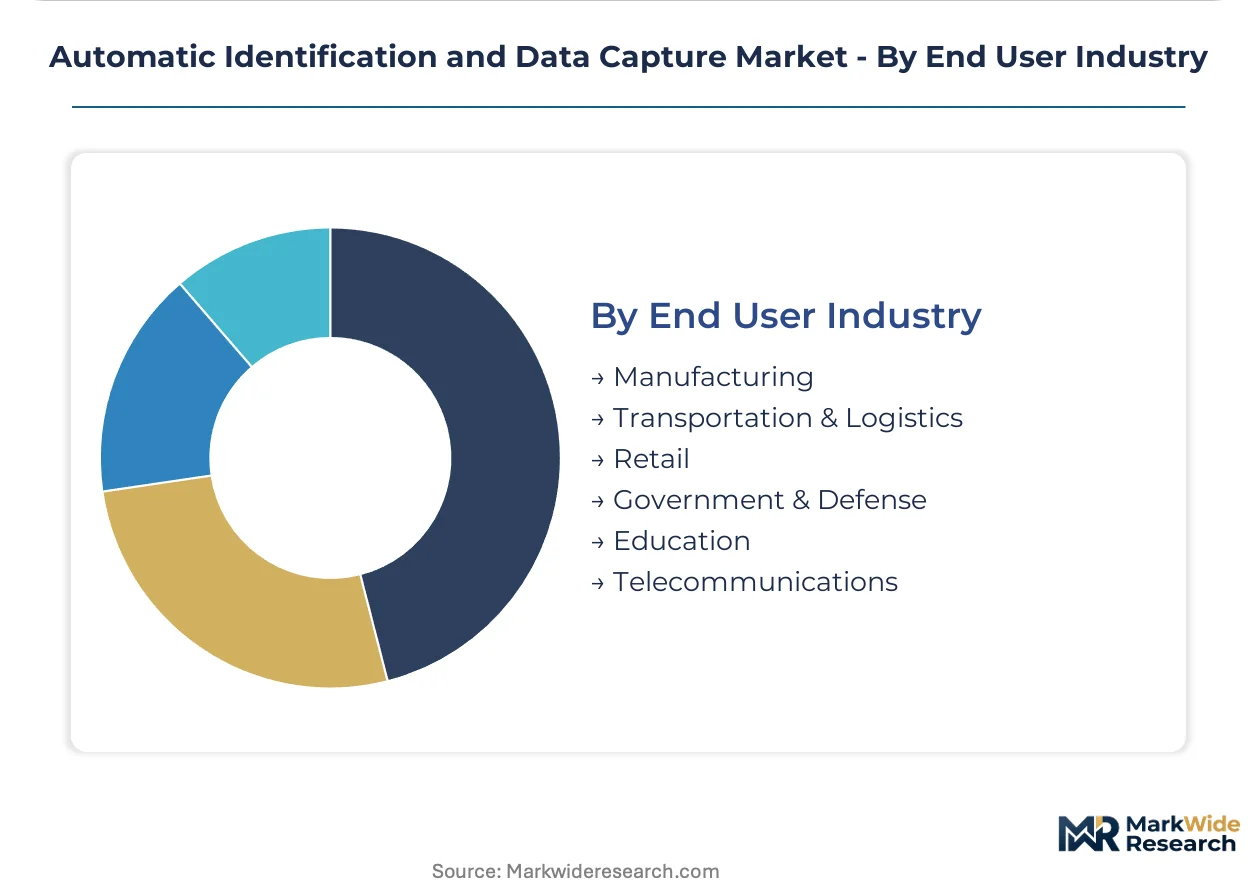
- Manufacturing:This sector leverages AIDC for process automation, quality control, and inventory tracking of raw materials and finished goods. China's industrial upgrading initiatives fuel significant deployment in manufacturing hubs.
- Transportation & Logistics:AIDC solutions enhance supply chain visibility, optimize fleet management, and streamline warehousing operations for global cargo and parcel carriers. The EU's CSRD accelerates adoption for granular tracking.
- Retail:Retailers use AIDC for inventory accuracy, point-of-sale efficiency, and loss prevention, with RFID gaining traction for item-level tracking.
- Government & Defense:These entities deploy AIDC for asset management, secure access control, and tracking sensitive equipment and personnel.
- Education:Educational institutions utilize AIDC for library management, student identification, and tracking IT assets within campuses.
- Telecommunications:The telecom sector employs AIDC for managing network infrastructure assets, inventory of equipment, and field service operations.
Efficiency gains in Manufacturing and traceability requirements in Transportation & Logistics define the primary demand patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automatic Identification and Data Capture market exhibits a clear divide between manufacturing hubs and consumption-driven economies. Demand for AIDC solutions concentrates in regions with extensive industrial bases and complex supply chains. This distribution reflects both production efficiency needs and stringent regulatory compliance requirements.
China
China's industrial automation initiatives generate significant demand for AIDC solutions, particularly in export-oriented manufacturing. The national strategic priority for industrial upgrading fuels large-scale deployment. The Yangtze River Delta, encompassing cities like Shanghai, sees extensive AIDC integration for process control and logistics.
United States
The United States market for AIDC solutions is driven by advanced healthcare asset management and e-commerce fulfillment operations. The U.S. FDA's Unique Device Identification (UDI) system mandates robust device tracking. Logistics corridors around major hubs like Chicago and Atlanta widely deploy advanced AIDC for warehouse optimization and enhanced supply chain visibility.
Germany
Germany’s advanced manufacturing sector and complex automotive logistics systems drive substantial AIDC adoption. The EU's Corporate Sustainability Reporting Directive (CSRD) further compels granular supply chain tracking. Industrial clusters in Bavaria and Baden-Württemberg actively integrate AIDC for Industry 4.0 initiatives and stringent quality assurance.
Japan
Japan's precision manufacturing and sophisticated retail inventory management systems create strong demand for AIDC technologies. METI actively promotes digital transformation initiatives. The Tokyo and Osaka metropolitan areas extensively utilize AIDC for high-speed logistics, automated retail operations, and advanced factory automation.
India
India's expanding logistics infrastructure and the need for pharmaceutical supply chain integrity are significant demand drivers for AIDC. The PLI scheme encourages local manufacturing capabilities, boosting AIDC demand. Major industrial corridors, such as the Delhi-Mumbai Industrial Corridor, adopt AIDC for efficient inventory management and critical asset tracking.
Automatic Identification and Data Capture Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with established technology providers alongside specialized solution developers and system integrators. The market exhibits characteristics of both consolidation among hardware giants and fragmentation within niche software and integration services. Strategic archetypes include diversified industrial conglomerates, focused AIDC specialists, and agile software-centric firms. Companies pursue portfolio diversification, strategic partnerships, and geographic expansion to solidify their market positions and enhance customer value.
Within the diversified industrial conglomerate tier, Honeywell International Inc. and Panasonic Corporation exemplify broad market presence across multiple end-user verticals. Zebra Technologies Corporation, meanwhile, represents a focused AIDC specialist, leveraging its strong position in mobile computing and barcode scanning for logistics and retail. These companies anchor the market through extensive product portfolios, global distribution networks, and continuous innovation. Their offerings span from foundational barcode systems to advanced RFID and mobile readers, addressing diverse operational demands.
| Leading Market Players |
|---|
| Cognex Corporation |
| Toshiba Tec Corporation |
| Zebra Technologies Corporation |
| Impinj Inc. |
| Panasonic Corporation |
| Honeywell International Inc. |
| SICK AG |
| Avery Dennison Corporation |
| Datalogic S.p.A. |
Cost & Logistics Intelligence
Diversified industrial conglomerates and focused AIDC specialists influence both supply behavior and pricing discipline across the Automatic Identification and Data Capture market. Their extensive product portfolios and global networks enable them to navigate complex supply chains and set market benchmarks.
Pricing Analysis
Price erosion across basic barcode scanning solutions traces to commoditization and increased competition from lower-cost manufacturers. The market operates with a hybrid pricing model, combining per-unit transactional sales for hardware with growing subscription-based services for software and support. Price differentiation often stems from the level of customization required for integration and the specific certification levels achieved, such as UDI compliance. Small and medium-sized enterprises exhibit higher price sensitivity compared to large enterprises in regulated industries like pharmaceuticals.
Supply Chain Analysis
Certification requirements, such as ISO/IEC 18000 for RFID air interface protocols, gate market access for many AIDC components. The supply chain for core components like microchips and optical sensors primarily concentrates in China, the United States, and Japan. The industry relies heavily on specialized semiconductor components and advanced polymers for labels and tags. A structural risk involves single-source vulnerability for highly specialized RFID reader chips. Downstream distribution typically runs through a network of direct sales teams, value-added resellers, and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automatic Identification and Data Capture market is largely a cost-of-compliance story, with regulations like the EU's Corporate Sustainability Reporting Directive creating a barrier-to-entry moat for established, compliant players.
For Market Incumbents: Extend existing product lines with advanced features, particularly in AI-powered analytics and machine vision capabilities. Strategic acquisitions of niche software providers can counter the threat from agile software-centric firms. Invest in certification processes for emerging regulatory mandates, such as new food traceability standards, to maintain market leadership. Deepen channel partnerships with system integrators to ensure seamless deployment and broader market reach.
For New Entrants and Emerging Players: Technology-first solutions, leveraging AI for predictive analytics in asset tracking, offer a strong entry point. Target underpenetrated applications like real-time food traceability using QR codes and NFC tags, or specialized healthcare asset management beyond basic UDI compliance. Mid-sized retail and e-commerce firms in North America represent a penetrable segment, seeking AIDC-as-a-Service bundles for operational agility without large upfront costs. Focus on offering integrated hardware-software solutions with strong support.
For Investors and Strategic Acquirers: Distressed-cycle entries favor strategic acquirers in the manufacturing and logistics technology sectors, seeking long-term value. The market's long-term viability is robust, driven by persistent regulatory pressure for transparency and the strategic imperative for automation across industries. Target agile software-centric firms specializing in AI integration or vertical-specific AIDC solutions. Increased M&A activity in AI/AIDC convergence serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Extension: Wearable Devices | Enhances operational flexibility and worker productivity in dynamic warehouse environments. |
| Platform Integration: AI & IoT | Generates predictive insights for inventory and supply chain risk, moving beyond passive data. |
| Strategic Partnerships: ERP/WMS Providers | Ensures seamless data flow and system interoperability, reducing integration challenges for end-users. |
| Acquisition of Specialist Firms: Machine Vision | Expands capabilities in high-speed quality control and automated defect detection for manufacturing. |
| Geographic Expansion: India's Industrial Corridors | Captures demand from expanding logistics infrastructure and local manufacturing initiatives. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. We engaged with supply chain managers, IT procurement specialists, logistics directors, and manufacturing plant engineers to gather qualitative insights. This approach facilitated bottom-up validation of market size estimates and top-down triangulation of growth forecasts.
The analytical framework reconciled multiple data streams across the analysis window, modeling market progression based on technology adoption and regulatory shifts. Segmentation dimensions included technology, application, product type, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future demand drivers, incorporating inputs like RFID tag unit costs and industrial automation investment levels.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade policies and rapid technological obsolescence in adjacent sectors. Forecasts reflect assumptions regarding stable economic conditions and consistent regulatory enforcement. A model refresh is warranted upon material change in global supply chain stability or major shifts in industrial automation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital BSS Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Business Information Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Construction Design App Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
UAE ICT Market