
 API Management Market | 2026-2036
API Management Market Size, Share, and Industry Trends Forecast 2026-2036
API Management Market Intelligence
Microservices architecture is rewriting how enterprises compose and expose software capabilities to internal and external consumers. Google leverages its cloud-native heritage to dominate containerized API orchestration, while Microsoft anchors enterprise workloads through Azure API Management's deep Active Directory integration. IBM sustains relevance among regulated industries with its emphasis on hybrid cloud governance and mainframe connectivity.
API Management encompasses the design, publication, security, monitoring, and analytics of application programming interfaces operating at throughput thresholds exceeding 10,000 transactions per second in high-volume deployments. The technology enables organizations to expose backend services as consumable endpoints while enforcing rate limiting, OAuth 2.0 authentication, and request transformation. Cloud deployment now leads solution type adoption as enterprises abandon capital-intensive on-premises gateway hardware, though hybrid configurations retain strongholds in sectors with data residency constraints. API Gateway solutions capture the largest margin pools due to their position as the compulsory traffic control layer, while Security and Authentication segments expand fastest as zero-trust architectures proliferate across financial and government networks.
The EU's PSD2 and GDPR frameworks mandate strong customer authentication and granular consent management, directly expanding demand for tokenization and audit-ready API analytics. In the United States, NIST cybersecurity guidelines and sector-specific FFIEC examinations shape procurement criteria for financial institutions selecting API infrastructure. Stakeholders must weigh sovereignty requirements against cloud agility when selecting deployment architectures, as divergent regulatory timelines across jurisdictions complicate unified platform strategies.
Market Dynamics
Microservices decomposition and zero-trust security mandates are forcing enterprises to rebuild API infrastructure around identity-centric traffic control rather than perimeter-based gateway appliances.
Growth Catalysts
- PSD2 Strong Customer Authentication:EU banks must expose payment initiation APIs with multi-factor consent flows, mandating tokenization infrastructure upgrades across Frankfurt and Amsterdam financial clusters.
- Healthcare data interoperability:US HIPAA-compliant FHIR APIs are unlocking clinical data exchange between hospital systems and telemedicine platforms, accelerating gateway procurement by provider networks.
- Container-native orchestration:Kubernetes sidecar proxy patterns are displacing centralized hardware appliances, with service mesh adoption surging among cloud-native fintech developers.
Market Restraints
- Specialized engineering scarcity:OAuth 2.0 and OIDC protocol expertise concentrates in Silicon Valley and London, inflating implementation costs for regional banks outside these talent pools.
- Data residency fragmentation:Divergent sovereignty requirements across Germany, France, and Singapore force redundant gateway deployments, eroding cloud cost advantages.
- Legacy SOAP entrenchment:Core banking systems in Japanese and Swiss institutions remain bound to XML-based protocols, constraining REST migration velocity.
Strategic Opportunities
- AI-powered anomaly detection:Behavioral biometrics integration with API traffic analysis is creating new premium tiers for fraud prevention in open banking corridors.
- Saudi fintech licensing wave:SAMA's regulatory sandbox is attracting payment API providers to Riyadh as the kingdom diversifies from hydrocarbon dependence.
- Edge computing convergence:5G MEC deployments are pulling API gateways closer to manufacturing floors and autonomous vehicle fleets, demanding sub-10ms latency architectures.
Industry Challenges
- Certificate lifecycle complexity:mTLS proliferation across microservices is overwhelming DevOps teams with PKI management overhead, delaying production deployments.
- Multi-cloud policy synchronization:Maintaining consistent rate limits and security rules across AWS, Azure, and GCP gateways requires expensive abstraction layer development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API Management Market |
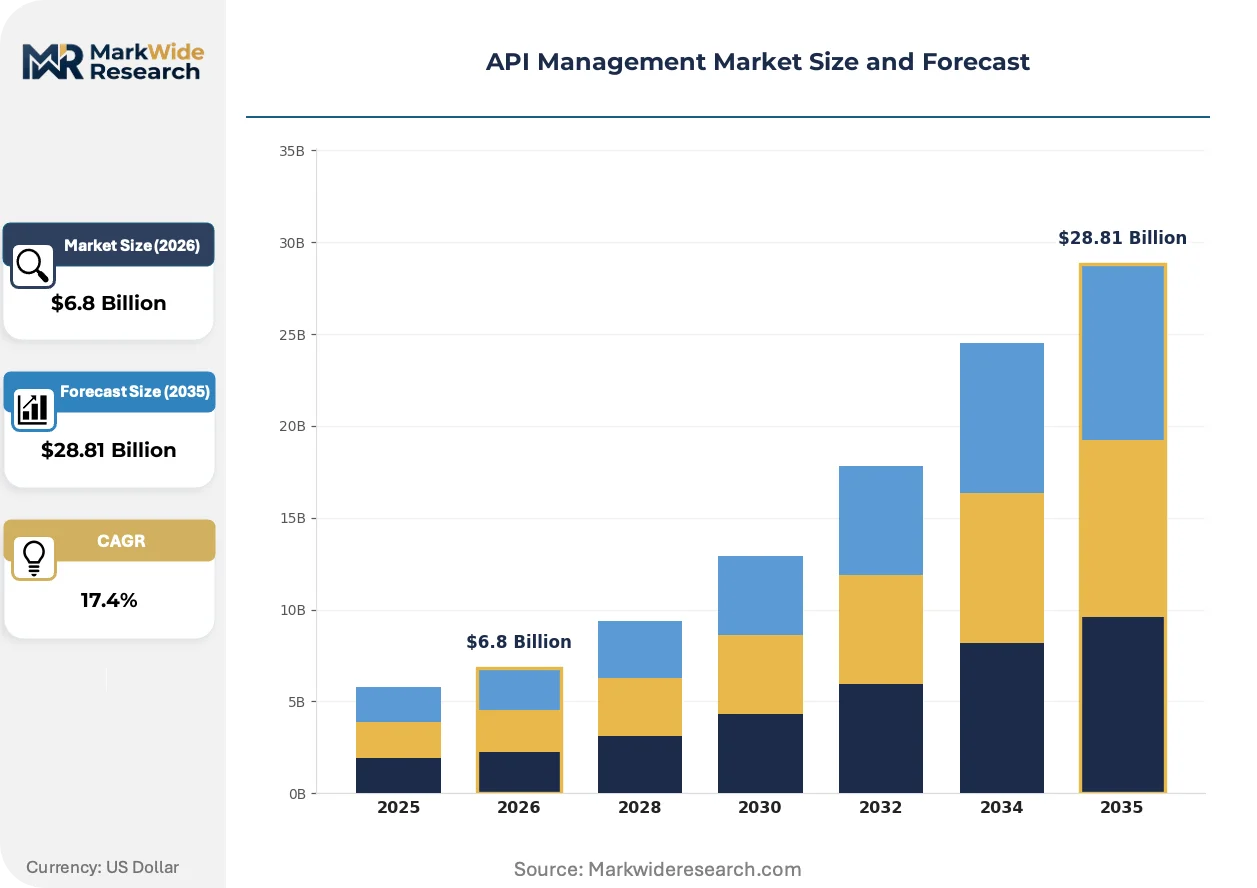
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Multi-Cloud Solution Type: API Gateway, API Analytics, Security & Authentication, Developer Portal Application: Mobile Integration, Enterprise Integration, Partner Integration, Data Monetization End User: Telecom Providers, Financial Institutions, Retail Chains, Government Agencies |
| Companies Covered | Google, Microsoft, IBM, AWS, MuleSoft, Axway, Software AG, Broadcom, TIBCO Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API Management Market Strategic Shifts & Innovations
API infrastructure is fragmenting into specialized control planes, with traffic management, security policy, and analytics decoupling from monolithic gateway appliances into composable software layers.
GraphQL query languages are rendering obsolete REST endpoint proliferation for mobile and frontend developers. E-commerce platforms and streaming services are consolidating hundreds of microservice calls into single request patterns. This compression is eliminating redundant payload serialization and collapsing frontend-backend contract maintenance overhead.
GDPR Article 30 record-keeping requirements are mandating automated API audit trails across European data controllers. Financial institutions and health tech operators must now capture every data subject access request with cryptographic integrity proofs. German automotive suppliers and Dutch insurance groups are prioritizing vendors with built-in compliance telemetry over pure performance benchmarks.
Developer experience portals are displacing traditional vendor sales cycles as the primary procurement channel. API documentation quality, sandbox provisioning speed, and SDK completeness now determine platform selection before commercial negotiations begin. This shift is most pronounced among Indian SaaS builders and Brazilian fintech startups accessing international payment networks.
API Management Market Segmentation
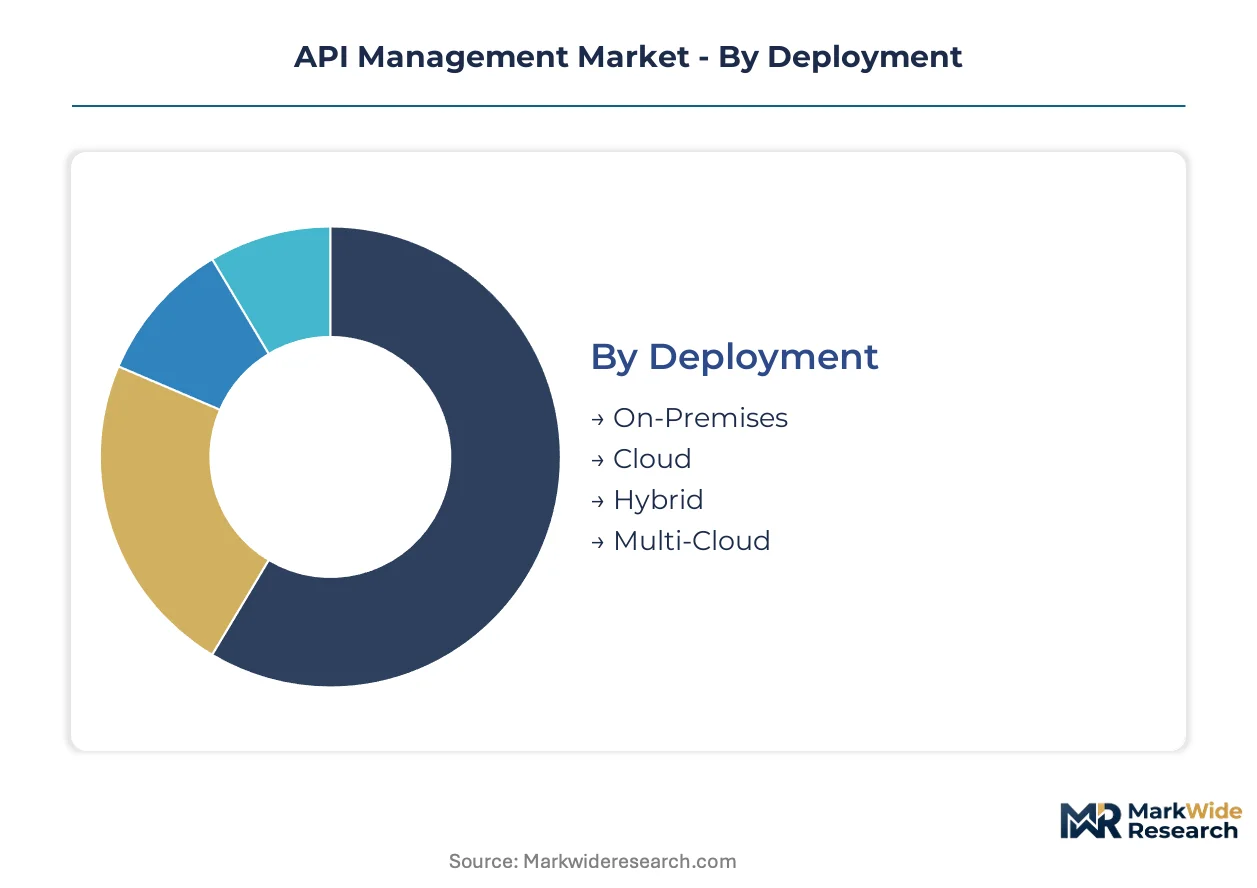
API management procurement patterns diverge sharply by infrastructure maturity and regulatory exposure. Deployment architecture choices determine capital intensity and compliance posture, while solution type selection reflects whether buyers prioritize traffic throughput, security hardening, or developer ecosystem expansion.
Deployment:
Cost tier stratification separates enterprises with legacy data center investments from cloud-native challengers seeking operational flexibility.
- On-Premises:Hardware gateway appliances deployed within owned facilities deliver sub-millisecond latency for high-frequency trading floors. Japanese and Swiss banking cores retain these configurations due to XML protocol entrenchment and conservative change management.
- Cloud:Consumption-based API gateway services eliminate capital expenditure and accelerate provisioning for fintech startups. Indian SaaS builders and Brazilian payment platforms favor this model for international market entry.
- Hybrid:Split traffic routing keeps sensitive authentication flows on-premises while exposing public endpoints through cloud infrastructure. German automotive suppliers deploy this architecture to satisfy GDPR data residency while maintaining supplier portal accessibility.
- Multi-Cloud:Abstraction layers spanning AWS, Azure, and GCP gateways reduce vendor lock-in for enterprises with distributed development teams. Financial institutions in Singapore and the Netherlands adopt this approach to negotiate pricing leverage across hyperscalers.
On-Premises retains the installed base among regulated incumbents. Cloud claims the steepest expansion trajectory as container-native fintechs scale without infrastructure debt.
Solution Type:
Application criticality drives solution investment sequencing, with traffic control preceding analytics and developer experience layers.
- API Gateway:Compulsory request routing, rate limiting, and protocol translation layer positioned at the network edge. Frankfurt and London financial clusters prioritize gateway throughput for open banking payment initiation volumes exceeding ten thousand transactions per second.
- API Analytics:Telemetry pipelines capturing latency distributions, error rates, and consumer behavior patterns. US hospital networks expanding HIPAA-compliant FHIR exchanges invest here to demonstrate interoperability compliance to CMS auditors.
- Security & Authentication:OAuth 2.0, OIDC, and mTLS policy enforcement protecting exposed backend services. EU PSD2 strong customer authentication mandates are accelerating tokenization infrastructure procurement across Amsterdam and Berlin.
- Developer Portal:Self-service documentation, sandbox provisioning, and SDK distribution platforms shortening sales cycles. Riyadh fintech licensees under SAMA's regulatory sandbox prioritize portal completeness to attract international API consumers.
API Gateway commands the established revenue base. Security & Authentication is climbing the fastest as zero-trust architectures proliferate across financial and government networks.
Application:
Integration depth requirements separate surface-level mobile connectivity from systemic enterprise transformation initiatives.
- Mobile Integration:Lightweight REST and GraphQL endpoints optimized for battery-constrained devices and intermittent connectivity. Streaming services and e-commerce platforms consolidate microservice calls to reduce payload serialization overhead.
- Enterprise Integration:SOAP-to-REST protocol bridging and legacy system API wrapping for core banking and ERP modernization. Japanese institutions face constraints here due to XML-based protocol entrenchment in settlement systems.
- Partner Integration:B2B supply chain and distributor network connectivity with contractual SLA enforcement. German automotive suppliers extend these APIs to tier-2 component manufacturers under EU supply chain transparency mandates.
- Data Monetization:Productized API tiers exposing aggregated datasets to external developers and researchers. Telemedicine platforms in the United States package de-identified clinical insights for pharmaceutical trial recruitment.
Enterprise Integration retains the largest deployment footprint. Data Monetization is gaining share fastest as platform business models displace direct service revenue.
End User:
Regulatory intensity and transaction volume characteristics differentiate buyer requirements across vertical sectors.
- Telecom Providers:5G network exposure APIs and subscriber identity management at carrier scale. Edge computing convergence is pulling gateways toward mobile edge computing nodes for autonomous vehicle and industrial IoT latency requirements.
- Financial Institutions:Open banking compliance, payment initiation, and account information services under PSD2 and FFIEC examination frameworks. Frankfurt and London clusters concentrate demand for tokenization and audit-ready analytics.
- Retail Chains:Omnichannel inventory synchronization and third-party marketplace seller integration. Brazilian and Indian retail platforms prioritize developer portal quality for international payment network access.
- Government Agencies:Citizen service APIs and inter-agency data sharing with sovereign cloud requirements. Singapore and UAE government digital identity programs drive procurement for hybrid deployment configurations.
Financial Institutions anchor the revenue base. Telecom Providers show the steepest expansion as 5G MEC deployments multiply edge gateway requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API management infrastructure flows from United States hyperscalers to European financial centers and Asian fintech clusters, with regulatory divergence shaping deployment architectures across destination markets.
United States
FFIEC examination frameworks and HIPAA compliance drive procurement across hospital networks and regional banks. NIST cybersecurity guidelines mandate zero-trust API architectures for federal contractors. Silicon Valley and Seattle tech corridors concentrate OAuth 2.0 engineering talent, inflating implementation costs for Midwestern institutions outside these pools.
Germany
PSD2 strong customer authentication mandates force tokenization upgrades across Frankfurt's banking core. GDPR Article 30 record-keeping requirements push automotive suppliers toward audit-ready API analytics. Bavarian industrial clusters deploy hybrid configurations to satisfy data residency while maintaining supplier portal accessibility.
United Kingdom
Open banking interoperability standards accelerate gateway procurement across London's fintech corridor. The Financial Conduct Authority's operational resilience requirements shape infrastructure selection criteria. Edinburgh and Manchester regional banks lag capital adoption due to specialized engineering scarcity.
Japan
METI digital transformation initiatives collide with conservative change management in core banking systems. XML-based protocol entrenchment in Tokyo and Osaka settlement systems constrains REST migration velocity. Swiss and Japanese institutions share legacy SOAP entrenchment patterns.
Singapore
Monetary Authority of Singapore fintech licensing attracts payment API providers to the city-state's regulatory sandbox. Data residency requirements force redundant gateway deployments alongside German and French sovereignty mandates. Multi-cloud abstraction layers reduce vendor lock-in for distributed development teams.
API Management Market Key Industry Players
On the supply side, the industry is consolidating around hyperscale cloud platforms while maintaining specialist tiers for regulated verticals. Strategic archetypes separate container-native orchestrators from hybrid governance specialists and mainframe connectivity incumbents. Dominant competitive moves include M&A to absorb service mesh capabilities and strategic partnerships to embed identity-centric traffic control into existing enterprise stacks.
Within the hyperscale tier, Google and Microsoft exemplify divergent enterprise engagement models, with the former leveraging cloud-native heritage and the latter anchoring workloads through directory integration. IBM occupies a position among regulated industries, sustaining relevance through hybrid cloud governance emphasis. These three entities represent the primary competitive anchors shaping procurement criteria across financial, healthcare, and government verticals.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| AWS |
| MuleSoft |
| Axway |
| Software AG |
| Broadcom |
| TIBCO Software |
| Others |
Cost & Logistics Intelligence
Frankfurt's financial infrastructure cluster concentrates cloud-native API gateway capacity, and this geographic density translates directly into pricing leverage for hyperscale providers serving EU-regulated banks. Containerized orchestration platforms from Silicon Valley and Seattle engineering pools command premium SaaS tiers, while regional system integrators in Mumbai and São Paulo compete on implementation cost.
Pricing Analysis
Next-generation service mesh architectures carry 40-60% subscription premiums over centralized gateway appliances, while legacy hardware configurations face accelerating depreciation. Three-tier pricing structure across premium, standard, and economy levels separates managed Kubernetes-native platforms from virtualized gateway instances and open-source self-managed deployments. Price differentiation hinges on certification grade (ISO 27001, SOC 2 Type II) and geographic data residency compliance. Pricing pressure stems from Indian SaaS builders and Brazilian fintechs driving commoditization of basic gateway throughput. Regional banks outside London and Silicon Valley talent pools exhibit highest price sensitivity, while Frankfurt and Singapore financial institutions prioritize compliance telemetry over cost.
Supply Chain Analysis
Upstream open-source project foundations in the United States feed commercial distributions through hyperscaler marketplaces. Software supply chains draw from container registry ecosystems anchored in California, Washington state, and Ireland data center clusters. Critical dependencies include Istio and Envoy proxy codebases, OAuth 2.0/OIDC protocol libraries, and hardware security module firmware. Single-source vulnerability concentrates in Google-controlled Kubernetes project governance, creating downstream risk for competing platform vendors. Distribution runs through cloud marketplace listings, direct enterprise sales, and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API infrastructure investment cycles track enterprise cloud migration waves, with current recovery momentum anchored in EU PSD2 compliance deadlines and US healthcare FHIR interoperability mandates.
For Market Incumbents: Pre-empt container-native challengers by acquiring service mesh specialist teams before talent costs inflate further. Fortify hybrid cloud governance positioning against Google and Microsoft hyperscale bundling. Invest in German and Singapore data center certifications to defend margin position against regional sovereign cloud requirements. For New Entrants and Emerging Players: Mid-market healthcare networks in the US Midwest represent the most penetrable entry point, as HIPAA-compliant FHIR expertise concentrates on the coasts. SAMA-licensed fintech infrastructure in Riyadh offers regulatory-sandbox acceleration with lower incumbent saturation. Lead with developer experience portals and rapid sandbox provisioning to bypass traditional procurement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-telemetry play because GDPR Article 30 and FFIEC examination frameworks permanently expand audit-ready API analytics demand. Target acquisition profiles center on firms with embedded zero-trust security policy engines and mainframe connectivity heritage. The signal to watch is Japanese banking consortium REST migration announcements, indicating legacy SOAP displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Service Mesh Capability Acquisition | Absorbs container-native orchestration talent before hyperscaler consolidation accelerates. |
| Hybrid Cloud Certification Investment | Captures German automotive and Singapore government data residency procurement requirements. |
| Developer Portal Platform Launch | Shortens sales cycles for Indian SaaS builders accessing international payment networks. |
| Healthcare FHIR Interoperability Partnership | Positions vendors for US hospital network CMS compliance demonstration requirements. |
| Edge Computing Gateway Deployment | Addresses 5G MEC latency requirements for autonomous vehicle and industrial IoT applications. |
Research Approach
A standing panel of platform engineering directors, API product managers, financial services CTOs, and healthcare IT procurement officers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory implementation databases. Bottom-up deployment modeling triangulated against top-down market sizing from cloud infrastructure spend tracking.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning deployment architecture, solution type, and regulatory exposure intensity. CAGRs derived from elasticity modeling against enterprise cloud migration velocity and compliance deadline clustering. Forecast inputs included PSD2 implementation timeline variance and Kubernetes adoption curves across financial services verticals.
Stress conditions across sovereign data residency fragmentation, OAuth 2.0 engineering talent scarcity, and legacy SOAP entrenchment persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and hyperscaler pricing discipline. Cross-checking against Gartner and Forrester enterprise infrastructure spend benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Consent Management Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Model Based Enterprise Market