
 North America Smart Card Market | 2026-2036
North America Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Card Market Analytics
PCI DSS compliance expansion is expanding the cost-of-entry calculus for new smart card vendors seeking bank and retailer contracts. HID Global Corporation leverages its physical access control heritage to dominate enterprise credentialing in the United States. IDEMIA sustains government identification contracts through manufacturing scale and established channel control with federal agencies. Infineon Technologies AG anchors semiconductor supply for contactless modules, competing on R&D intensity in secure element architectures.
A smart card is a pocket-sized card with embedded integrated circuits—either memory chips or microprocessors—typically manufactured from polyvinyl chloride or polycarbonate substrates with embedded RFID coils or contact pads, designed to store, process, and transmit data through physical contact or near-field communication. Its primary commercial purpose is to enable secure authentication, payment authorization, and identity verification across financial, governmental, and enterprise systems. Contactless smart cards lead product type deployment as transit agencies and payment networks prioritize tap-to-pay speed, while dual-interface smart cards capture expanding margin pools by serving both legacy contact and emerging contactless infrastructure. Within application segments, financial services maintains volume dominance though government identification shows structural acceleration from REAL ID enforcement and federal credentialing modernization.
The Federal Reserve Board shapes payment card security standards through oversight of banking infrastructure, while NIST publishes cryptographic guidelines that vendors must satisfy for federal procurement eligibility. FCC regulations govern NFC frequency bands and electromagnetic emissions for contactless devices operating in U.S. consumer environments. Stakeholders must monitor how state-level digital identity pilots in California and New York intersect with federal credentialing mandates to determine product roadmap prioritization.
Market Dynamics
Dual-interface credential deployment by major U.S. banks is compressing replacement cycles and forcing semiconductor vendors to reallocate fab capacity toward secure element architectures. This technology transition is reshaping procurement priorities across the financial services sector.
Growth Catalysts
- EMV chip mandates:Card network compliance deadlines in the United States and Canada sustain hardware replacement demand among issuing banks and credit unions.
- Contactless transit infrastructure:Metropolitan transportation agencies in Chicago, Toronto, and Vancouver prioritize tap-to-pay speed for commuter throughput.
- Federal credentialing modernization:REAL ID enforcement deadlines and PIV card upgrades drive government identification volume through established procurement channels.
Market Restraints
- Semiconductor supply concentration:Secure element fabrication relies on a limited number of European and Asian foundries, creating allocation risk during demand spikes.
- Polycarbonate substrate cost volatility:Petrochemical input fluctuations compress margins for card manufacturers serving price-sensitive municipal transit contracts.
- Mobile wallet substitution:Smartphone-based payment authorization reduces physical card issuance velocity among younger demographics in urban U.S. markets.
Strategic Opportunities
- State digital identity pilots:California and New York experimentation with mobile driver's licenses creates white space for credentialing vendors with platform integration capabilities.
- Healthcare access convergence:Dual-interface smart cards are integrating insurance verification with physical facility access for hospital networks in Texas and Florida.
- Enterprise logical access expansion:FIDO2 standards adoption by SaaS providers is opening procurement channels for cryptographic hardware tokens in the United States.
Industry Challenges
- PCI DSS certification timelines:Extended audit cycles for new vendors delay contract awards from major U.S. retailers and payment processors.
- Secure element design talent scarcity:Shortage of hardware security architects with side-channel attack mitigation expertise constrains R&D throughput in North American engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Card Market |
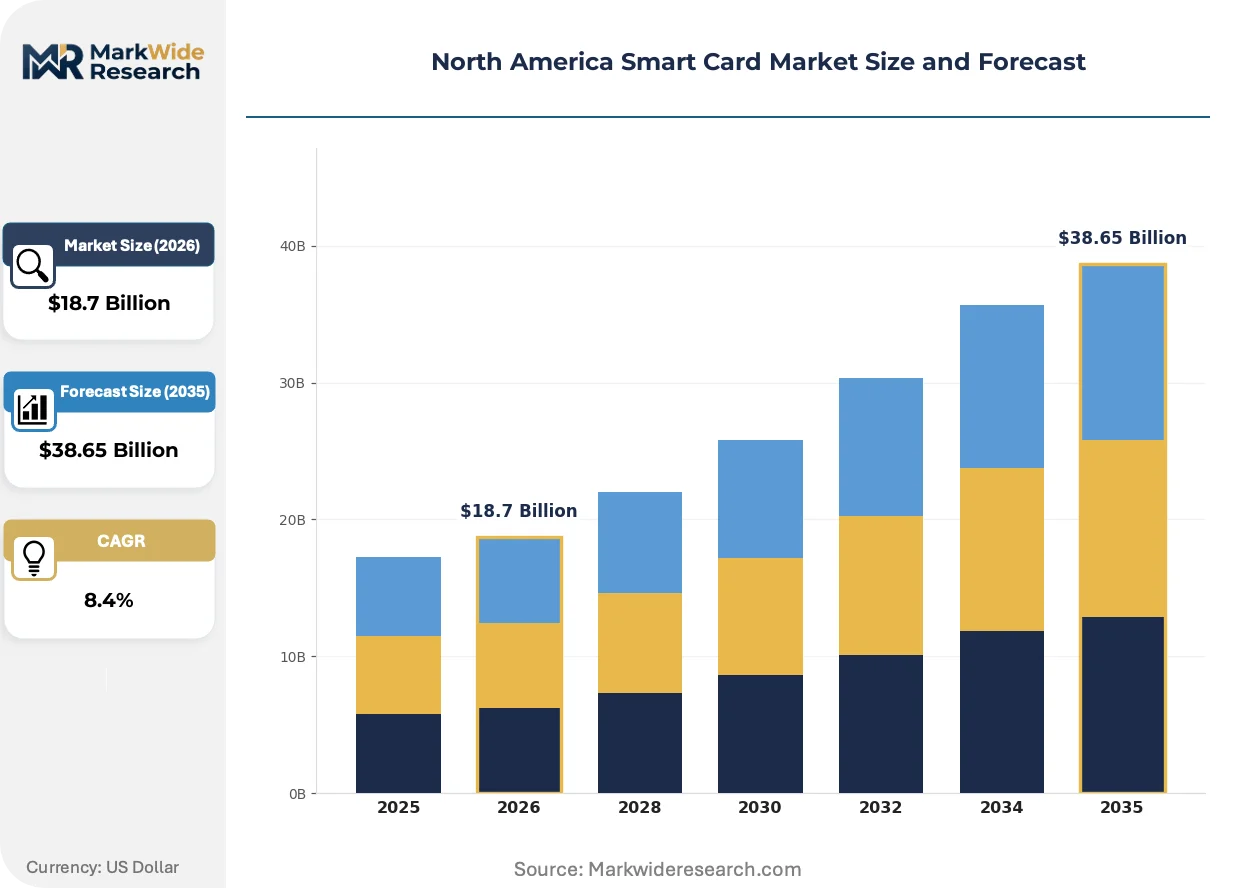
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Smart Cards, Contactless Smart Cards, Dual-Interface Smart Cards, Mobile Smart Cards Application: Financial Services, Government Identification, Transportation, Healthcare End User: Retailers, Banks, Government Agencies, Telecom Operators Technology: RFID, NFC, Microprocessor-Based, Optical |
| Companies Covered | CardLogix Corporation, HID Global Corporation, IDEMIA, Secura Key, CPI Card Group Inc, Giesecke+Devrient GmbH, Fingerprint Cards AB, Infineon Technologies AG, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Card Market Evolving Landscape
Biometric sensor miniaturization and post-quantum cryptographic migration are redefining hardware security requirements across payment and identity applications. Vendors must align roadmaps with these simultaneous technical transitions.
Embedded fingerprint sensors in payment cards are integrating capacitive or ultrasonic authentication directly into the card body. Large U.S. issuers are piloting these credentials for high-net-worth segments where card-present fraud tolerance is lowest. This integration is compressing the traditional separation between biometric capture and secure element processing, forcing silicon vendors to redesign die architectures.
FCC Part 15 regulations governing NFC electromagnetic emissions are tightening testing protocols for contactless devices operating in dense retail environments. Compliance costs are rising for module suppliers serving the U.S. market. Transit agencies in Boston and Seattle are delaying procurement decisions pending certification clarity, creating temporary demand pauses.
Consolidated credentialing is displacing single-purpose cards as employers and universities seek unified physical-logical access solutions. Healthcare systems in the U.S. Midwest are bundling building entry, parking, and network authentication into single dual-interface deployments. This pattern is most visible among integrated delivery networks acquiring physician practices and standardizing IT infrastructure.
North America Smart Card Market Segmentation
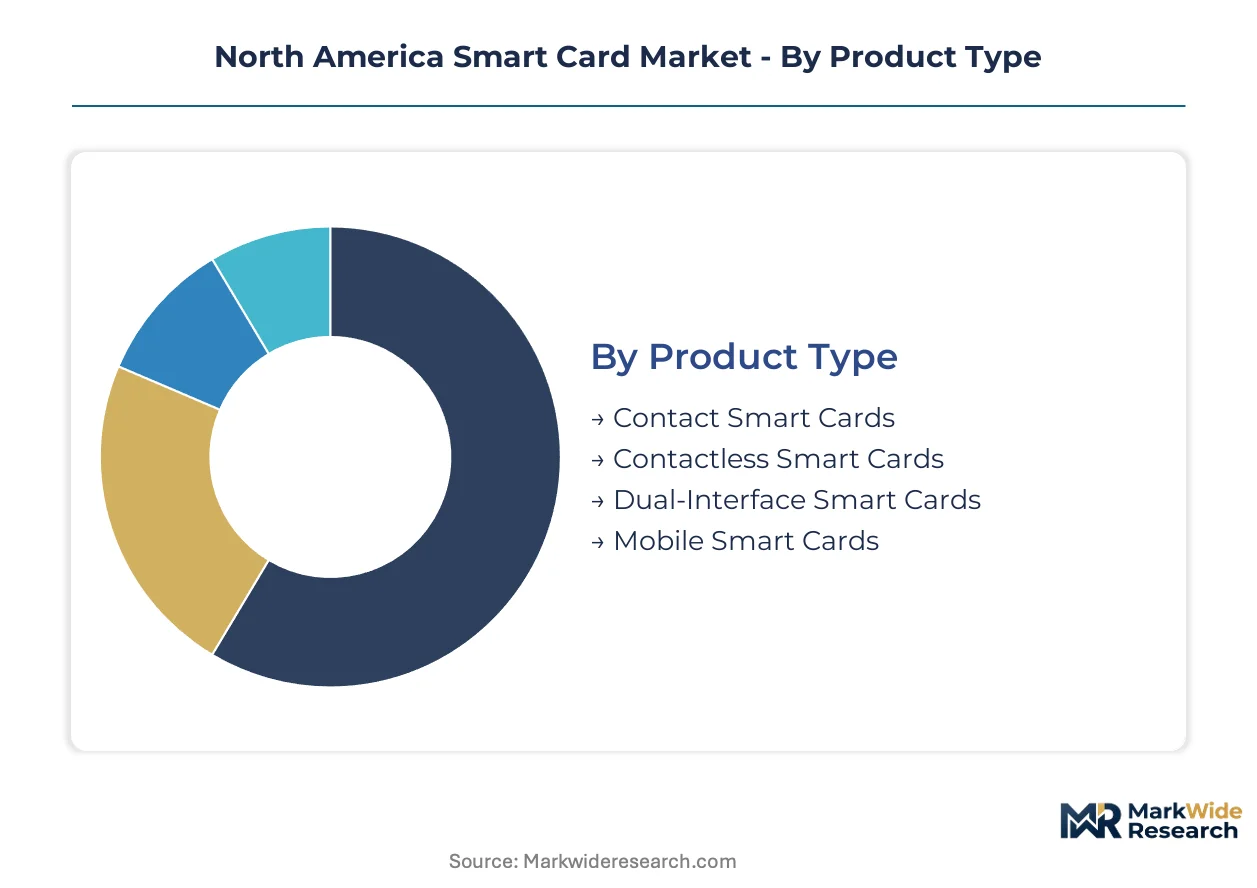
Smart card segmentation in North America reflects divergent procurement priorities across payment networks, federal agencies, and transit authorities. Buyers select product architectures based on infrastructure legacy, security mandates, and transaction speed requirements rather than cost alone.
Product Type:
Card form factors differentiate by interface mechanism and substrate integration, with buyers prioritizing either backward compatibility or tap-to-pay speed depending on deployment environment.
- Contact Smart Cards:These credentials rely on physical gold-plated pads mating with reader terminals to transmit data and power. EMV compliance deadlines at U.S. credit unions sustain procurement for ATM networks and legacy point-of-sale terminals not yet upgraded for contactless acceptance.
- Contactless Smart Cards:Embedded RFID coils enable near-field data exchange without physical insertion. Metropolitan transportation agencies in Chicago and Toronto specify these for commuter throughput where transaction speed directly impacts ridership capacity.
- Dual-Interface Smart Cards:Single credentials combining contact pads and contactless antennas serve banks migrating infrastructure incrementally.
- Mobile Smart Cards:Secure element emulation within smartphone secure enclaves targets younger demographics in urban U.S. markets.
Contact smart cards lead volumes today; dual-interface credentials are gaining share fastest.
Application:
Sector-specific compliance regimes shape specification requirements, with federal procurement channels operating on multi-year award cycles distinct from commercial payment network refresh timelines.
- Financial Services:Payment card issuance dominates unit economics, with PCI DSS certification requirements filtering vendor participation. Large U.S. banks specify dual-interface architectures to preserve terminal compatibility while enabling contactless acceptance expansion.
- Government Identification:REAL ID enforcement deadlines and PIV card modernization programs structure demand through established federal supply schedules. Polycarbonate substrate durability requirements exceed commercial payment card specifications.
- Transportation:Transit agency procurement prioritizes transaction speed and card durability under mechanical stress.
- Healthcare:Hospital networks in Texas and Florida pilot combined insurance verification and physical access credentials.
Financial services generates highest unit volumes; government identification shows steepest expansion trajectory from credentialing mandates.
End User:
Procurement sophistication varies sharply, with tier-one banks operating dedicated smart card engineering teams while municipal transit authorities rely on systems integrator intermediaries.
- Retailers:Major U.S. merchants drive contactless terminal deployment, specifying card acceptance standards that cascade backward to issuer credential specifications. PCI DSS audit requirements constrain vendor selection to established suppliers with certification history.
- Banks:Issuing institutions manage replacement cycles driven by EMV network mandates and fraud loss mitigation targets. Dual-interface specifications dominate new procurement as contactless acceptance infrastructure matures.
- Government Agencies:Federal credentialing programs operate through GSA supply schedules with multi-year award horizons.
- Telecom Operators:Subscriber identity module procurement follows 3GPP standards with carrier-specific customization requirements.
Banks represent the largest procurement pool; government agencies are expanding fastest from federal modernization programs.
Technology:
Semiconductor architecture selection determines security certification pathways, with FIPS 140-2 compliance mandatory for federal applications and EMVCo approval required for payment network participation.
- RFID:Radio-frequency identification operates at 13.56 MHz for contactless proximity applications. Transit agencies specify these for fare collection where read range and transaction speed outweigh cryptographic sophistication requirements.
- NFC:Near-field communication protocols enable bidirectional data exchange between card and reader. FCC Part 15 emissions compliance creates certification bottlenecks for module suppliers targeting dense retail environments.
- Microprocessor-Based:Embedded secure elements execute cryptographic operations within tamper-resistant silicon. These architectures anchor payment and identity applications requiring side-channel attack resistance.
- Optical:Laser-readable stripes provide visual authentication layers for government credentials requiring human-verifiable security features.
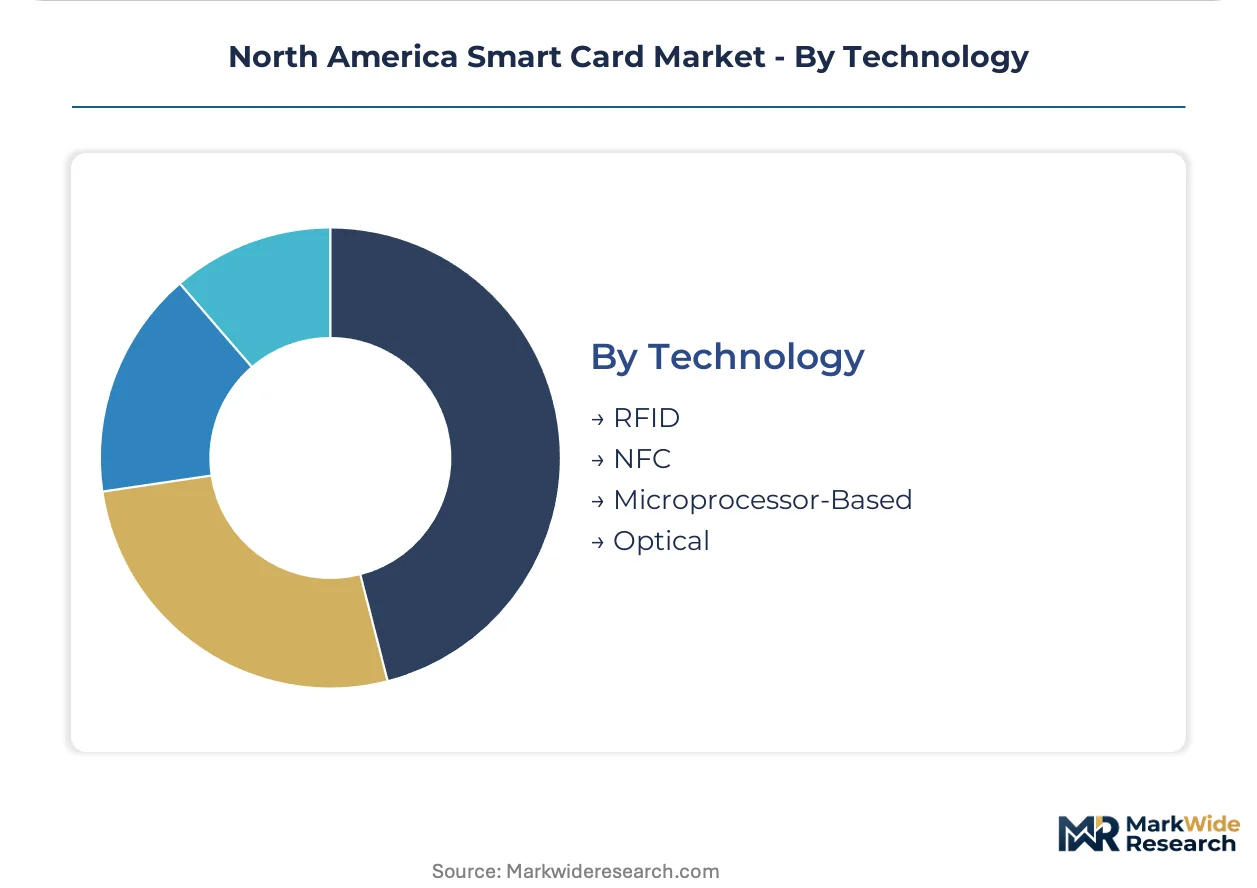
Microprocessor-based technology anchors revenue today; NFC is climbing the fastest from contactless payment network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart card industry traces its North American commercial roots to early bank card experiments in the United States during the 1960s, with subsequent EMV standardization and federal credentialing programs cementing regional production and procurement infrastructure across the continent.
United States
Dual-interface payment card issuance by large banks and federal PIV credentialing modernization sustain procurement volumes. The Federal Reserve Board oversees payment security standards while NIST publishes cryptographic guidelines for federal eligibility. Silicon Valley semiconductor design centers and East Coast financial services corridors anchor secure element R&D and card manufacturing.
Canada
Contactless transit infrastructure in Toronto and Vancouver drives municipal procurement alongside EMV network compliance at domestic banks. Health Canada regulates device safety for healthcare credentialing applications. The Greater Toronto Area concentrates card manufacturing and systems integration capabilities serving both domestic and cross-border contracts.
Mexico
Financial inclusion programs and banking sector modernization expand payment card issuance to underbanked populations. The central bank (Banco de México) mandates chip-based security standards for domestic payment networks. Mexico City anchors regional manufacturing partnerships supplying North American assembly operations.
North America Smart Card Market Competitive Landscape
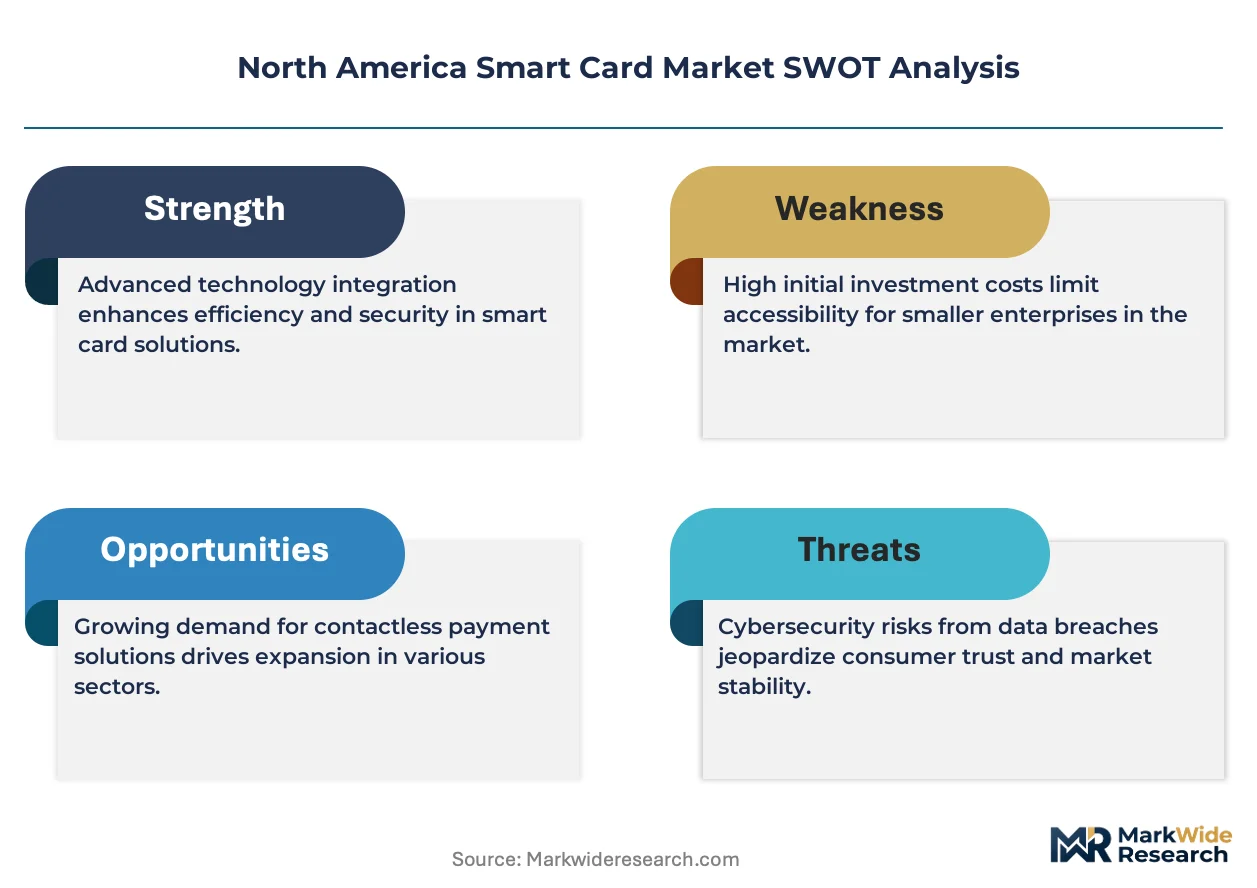
The competitive structure tilts toward diversified technology conglomerates with secure element fabrication capabilities. Semiconductor vendors and specialized card manufacturers coexist in a tiered hierarchy where federal certification history and PCI DSS compliance records filter vendor participation. Three archetypes dominate: silicon foundries supplying secure elements, integrated card manufacturers with inlay and personalization capabilities, and physical access control specialists extending into credentialing. Competitive moves center on fab capacity allocation toward secure element architectures and strategic partnerships with payment networks for certification acceleration.
Within the semiconductor supply tier, Infineon Technologies AG and NXP Semiconductors N.V. exemplify European-headquartered secure element suppliers anchoring North American payment and identity applications. IDEMIA occupies a position bridging manufacturing scale with established federal channel control. These three represent distinct competitive positioning: silicon-centric R&D intensity, integrated production and personalization, and government contracting heritage.
| Leading Market Players |
|---|
| CardLogix Corporation |
| HID Global Corporation |
| IDEMIA |
| Secura Key |
| CPI Card Group Inc |
| Giesecke+Devrient GmbH |
| Fingerprint Cards AB |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Others |
Value Network & Pricing Analysis
Hardware security architects concentrated in Silicon Valley and Austin command premium compensation that widens spreads between premium-certified and economy-tier smart card offerings. Labor-cost differentials in secure element design directly propagate into pricing-tier stratification across financial services and government procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FIPS 140-2 certification grade and EMVCo approval status driving price differentiation. Cost compression in economy-tier municipal transit contracts is intensifying because polycarbonate substrate volatility squeezes manufacturer margins. Banks with dedicated smart card engineering teams show least price sensitivity; small credit unions and transit authorities exhibit highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from tier-one banks, while systems integrator intermediaries serve price-sensitive municipal buyers. Secure element fabrication draws from Germany, Taiwan, and South Korea, with polycarbonate substrates and RFID antenna inlays as critical inputs. Single-source vulnerability in European and Asian foundries creates allocation risk during demand spikes. Distribution runs through GSA supply schedules for federal contracts and PCI DSS-certified channels for commercial payment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REAL ID enforcement deadlines and EMV network mandates structurally guarantee replacement-cycle demand regardless of macroeconomic conditions.
For Market Incumbents: Deepen backward integration into secure element design talent pools in North American engineering centers to offset hardware security architect scarcity. Expand fab capacity allocation toward post-quantum cryptographic architectures before certification requirements harden. Mobile wallet substitution among younger demographics threatens physical card issuance velocity; counter with biometric-integrated premium tier development.
For New Entrants and Emerging Players: The mid-tier price-point gap between FIPS-certified government credentials and economy transit cards offers entry space. Target healthcare access convergence in Texas and Florida hospital networks where dual-interface pilot programs lack established vendor relationships. Pursue state digital identity pilot partnerships in California and New York as beachhead procurement channels.
For Investors and Strategic Acquirers: Semiconductor conglomerates with secure element fabrication capabilities are the most active acquirer in this space. Long-term viability hinges on federal certification history and PCI DSS compliance records as irreproducible intangible assets. Monitor FCC Part 15 certification clarity for contactless modules as inflection indicator for transit agency procurement resumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | NIST guideline alignment secures federal procurement eligibility before mandate deadlines. |
| Biometric Sensor Integration | Capacitive fingerprint modules differentiate premium payment credentials for high-net-worth segments. |
| State Digital Identity Partnerships | California and New York mobile driver's license pilots open platform integration revenue streams. |
| Healthcare Access Convergence | Combined insurance verification and physical access credentials capture hospital network standardization budgets. |
| FIDO2 Standards Certification | Enterprise logical access expansion unlocks SaaS provider procurement channels for cryptographic hardware tokens. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions included smart card engineering directors at tier-one banks, federal procurement officers managing GSA supply schedules, semiconductor R&D leads, transit agency technology managers, and PCI DSS audit specialists. Secondary validation drew from NIST cryptographic guideline publications, FCC Part 15 regulatory filings, EMVCo compliance bulletins, Federal Reserve payment security reports, and hospital procurement databases. Bottom-up unit shipment modeling and top-down payment network refresh cycle analysis were triangulated against foundry capacity disclosures.
Segment-weighting applied product type, application sector, end-user sophistication tier, and semiconductor technology architecture across the analysis window. CAGRs were derived from replacement cycle velocity modeling tied to EMV mandate deadlines and federal credentialing program schedules. Secure element fabrication capacity allocation and polycarbonate substrate cost indices served as industry-specific forecast inputs.
Caveats apply where semiconductor supply concentration, FCC certification timeline delays, or mobile wallet substitution acceleration could materially shift the outlook. Forecasts reflect assumptions regarding EMV network compliance adherence and REAL ID enforcement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia System Integration Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Digital Metronome Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Dataops Platform Market
Digital Solutions
Smart Government Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Mexico Digital Showers Market