
 Asia-Pacific Multichannel Order Management Market | 2026-2036
Asia-Pacific Multichannel Order Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Multichannel Order Management Market Insights
Subscription-based SaaS financing is reconfiguring competitive entry barriers across the Asia-Pacific multichannel order management landscape. HCL Technologies leverages its IT services heritage to anchor enterprise-grade deployment capabilities for hybrid cloud architectures. Zoho Corporation competes through vertically integrated platform economics that sustain pricing flexibility for mid-market retailers. Oracle Corporation dominates high-complexity B2B order orchestration through its database-to-application stack control.
Multichannel order management systems coordinate inventory visibility, order routing, and fulfillment execution across disparate sales channels through API-centric software architectures that process real-time stock levels and delivery constraints. These platforms synchronize warehouse management systems, carrier networks, and customer-facing storefronts to minimize split shipments and stockout-driven cancellations. Cloud-based deployment leads adoption as retailers prioritize elastic capacity for seasonal demand spikes without capital-intensive infrastructure commitments. Software solutions capture the largest margin pools, while integration tools represent the fastest-expanding segment as legacy ERP systems require middleware connectivity to modern marketplaces.
TRAI's data localization mandates and India's PLI scheme for digital infrastructure are tightening cross-border data governance requirements for order management platforms operating across South Asian markets. Australia's ACCC consumer protection frameworks and Japan's METI e-commerce standards shape product authentication and returns processing specifications that vendors must embed natively. China's SAMR platform governance rules add compliance layers for foreign software providers serving mainland marketplace integrations. Stakeholders must evaluate sovereign cloud partnerships and in-region data residency architectures before committing to platform consolidation strategies.
Market Dynamics
Cloud-native API architectures are compressing deployment timelines for multichannel order management platforms across Southeast Asia, forcing established vendors to reconfigure their integration methodologies around real-time inventory federation rather than batch-processed data synchronization.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic production incentives are expanding captive fulfillment networks, creating demand for order orchestration systems that coordinate factory-direct shipments with marketplace channels.
- Real-time inventory federation:API-centric stock visibility layers are eliminating phantom inventory discrepancies that previously drove split shipments and customer churn in high-velocity retail segments.
- Southeast Asian e-commerce consolidation:Marketplace operators in Indonesia, Vietnam, and Thailand are mandating unified order management APIs for third-party sellers, accelerating platform standardization.
Market Restraints
- Cross-border data residency mandates:TRAI's localization requirements and China's SAMR platform governance rules impose redundant infrastructure investments for vendors serving multiple Asia-Pacific jurisdictions.
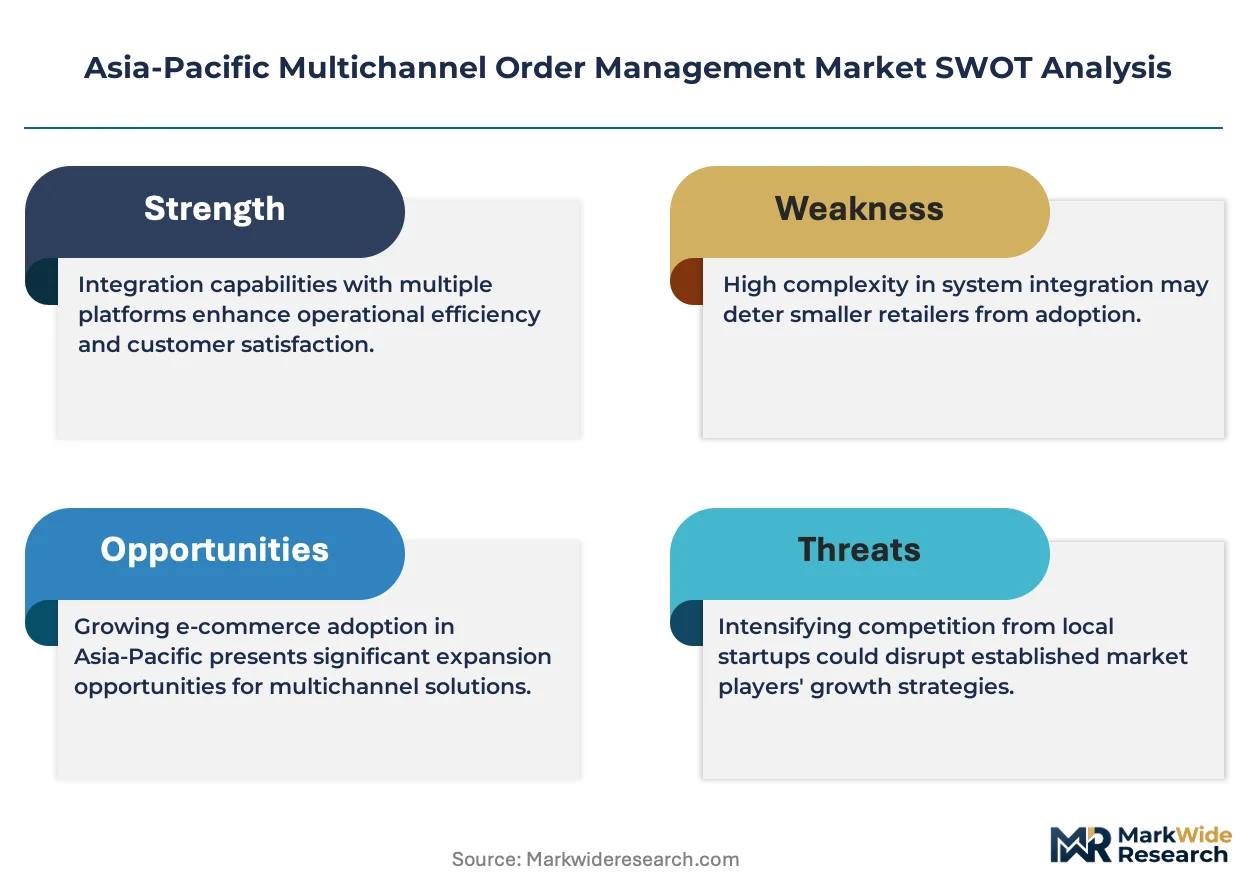
- Legacy ERP integration debt:Mid-market retailers in Australia and Japan operate on 15-20 year-old warehouse management systems that resist API connectivity without expensive middleware layers.
- Specialized talent scarcity:Cloud architecture engineers with omnichannel fulfillment expertise command premium compensation in Singapore and Bangalore, inflating implementation costs.
Strategic Opportunities
- Vietnam's manufacturing corridor expansion:Factory-to-consumer direct channels are underdeveloped relative to export volume, creating whitespace for order management platforms that bypass traditional distributor networks.
- AI-driven demand forecasting convergence:Machine learning modules for predictive replenishment are integrating with order orchestration engines, enabling dynamic safety stock adjustments before stockout events.
- Australia's retail technology modernization programs:Government co-financing for digital infrastructure upgrades is lowering adoption barriers for cloud-native order management among mid-tier department store chains.
Industry Challenges
- Fragmented carrier API standards:Last-mile logistics providers across India and Southeast Asia operate incompatible tracking protocols, forcing order management vendors to maintain dozens of custom integrations.
- Certification timeline compression:Japan's METI e-commerce standards and Australia's ACCC consumer protection frameworks require simultaneous compliance testing, extending product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Multichannel Order Management Market |
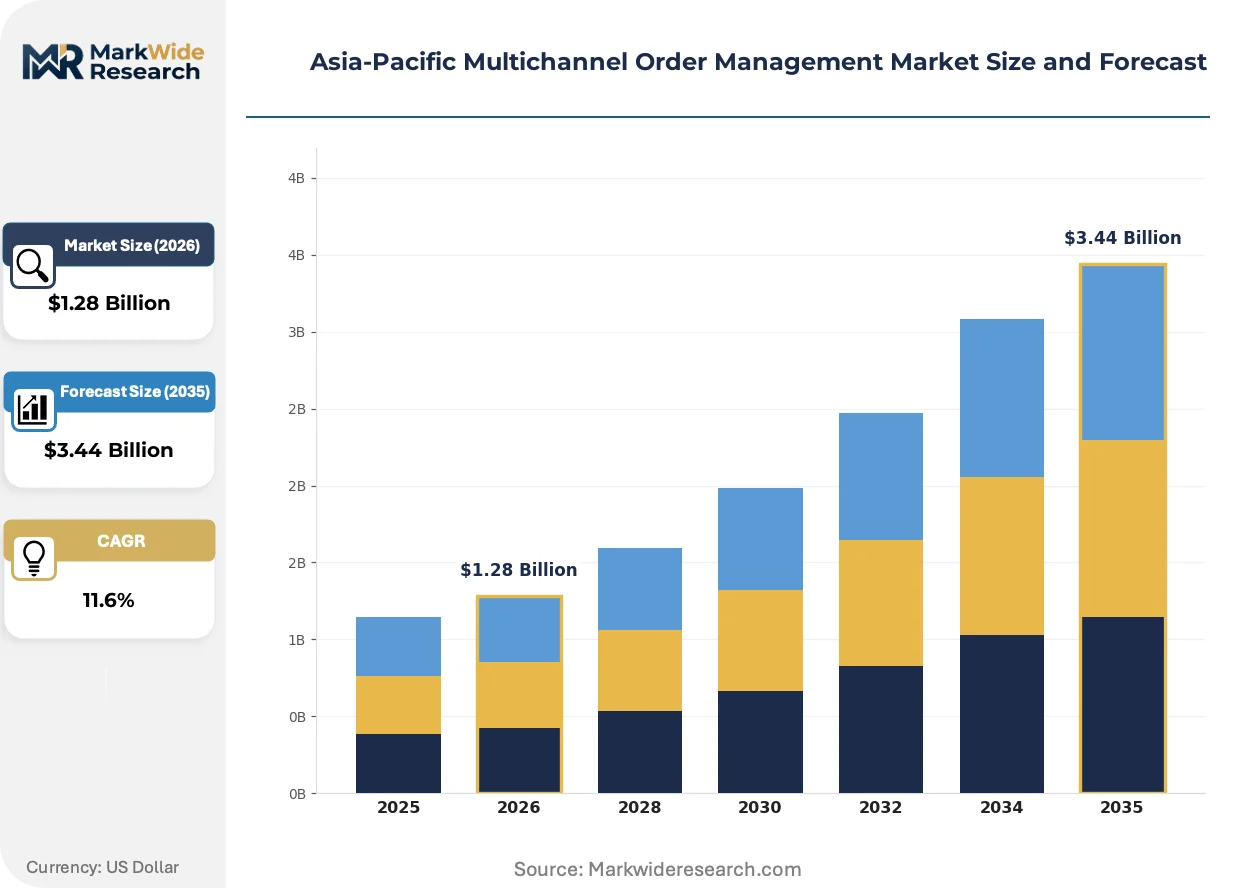
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $3.44 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Multi-tenant Solution Type: Software, Platform, Integration Tools, Analytics End User: Retailers, E-commerce Platforms, Wholesalers, Distributors Business Model: B2B, B2C, C2C, D2C |
| Companies Covered | HCL Technologies, Zoho Corporation, Vinculum, Unicommerce eSolutions, Delhivery, SAP SE, Oracle Corporation, IBM Corporation, Salesforce, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Multichannel Order Management Market Trends and Innovations
Distributed order management architectures are displacing centralized legacy systems as the default technical foundation, with three convergent developments reshaping platform capabilities and vendor competitive positioning across the Asia-Pacific retail technology stack.
Headless commerce middleware is virtualizing the traditional storefront-OMS coupling, enabling retailers to swap customer-facing channels without reconfiguring fulfillment logic. Fashion and electronics retailers in South Korea and Australia are adopting this decoupled approach fastest, driven by social commerce experimentation. The technology is virtualizing vendor lock-in risks that previously protected incumbent platform providers.
TRAI's data localization mandates and India's Digital Personal Data Protection framework are forcing order management vendors to deploy sovereign cloud instances or partner with domestic hyperscale providers. Industrial consequence includes duplicated infrastructure costs and fragmented product roadmaps across jurisdictions. Vendors serving India's metropolitan logistics corridors are responding by establishing Mumbai and Bangalore data centers with in-region engineering teams.
Direct-to-consumer channel experimentation is compressing traditional wholesale-retail procurement cycles, with brand manufacturers in China and Indonesia building owned storefronts that bypass marketplace intermediaries. This disintermediation is disrupting established distributor financing models and inventory risk allocation. The shift is most visible in Indonesia's consumer electronics vertical, where factory brands now operate parallel B2B and B2C order streams through unified orchestration layers.
Asia-Pacific Multichannel Order Management Market Segmentation
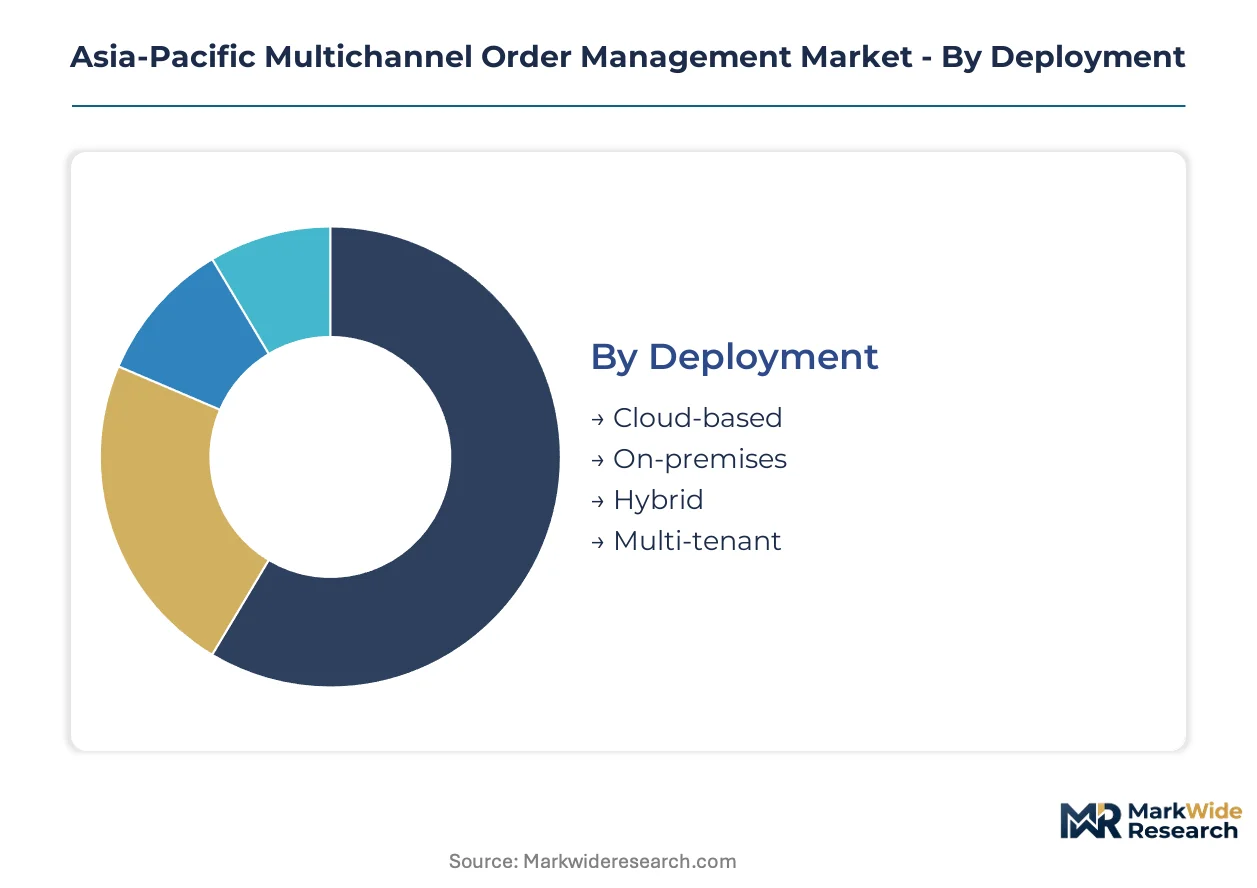
Multichannel order management platforms serve divergent operational requirements across the Asia-Pacific fulfillment ecosystem. Deployment architectures, solution configurations, and business model alignments determine integration complexity and total cost of ownership for retailers navigating fragmented marketplace environments.
Deployment:
Cloud-native configurations dominate Southeast Asian e-commerce expansions where elastic capacity absorbs seasonal demand volatility without infrastructure lock-in.
- Cloud-based:API-centric architectures federate real-time inventory across distributed warehouse networks. Singaporean fashion retailers and Indonesian marketplace sellers prioritize this model to avoid capital expenditure during expansion phases.
- On-premises:Legacy data center installations persist among Japanese department store chains and Australian grocery conglomerates with stringent internal security protocols. TRAI's data localization mandates and China's SAMR governance rules reinforce domestic hosting requirements for cross-border operators.
- Hybrid:Split architectures process sensitive customer data locally while pushing order orchestration logic to cloud instances. Indian electronics manufacturers adopting PLI scheme incentives favor this approach for factory-direct channel coordination.
- Multi-tenant:Shared infrastructure platforms reduce per-merchant costs for mid-market retailers in Vietnam and Thailand. SaaS economics enable smaller distributors to access enterprise-grade order routing without dedicated hardware investments.
Established volume favors on-premises installations among legacy retail conglomerates; emerging adoption favors cloud-based configurations among digital-native marketplace entrants.
Solution Type:
Functional depth determines margin capture and implementation timeline across the technology stack.
- Software:Standalone order management applications deliver core orchestration capabilities through configurable rule engines. Australian retail technology modernization programs channel government co-financing toward these deployments for mid-tier department store chains.
- Platform:End-to-end suites integrate inventory visibility, carrier management, and returns processing within unified codebases. South Korean electronics retailers and Chinese factory brands building D2C channels require this comprehensiveness to bypass marketplace intermediaries.
- Integration Tools:Middleware connectors bridge legacy ERP systems to modern marketplace APIs. These components expand most quickly as Japanese and Australian retailers confront 15-20 year-old warehouse management systems resisting native connectivity.
- Analytics:Predictive modules for demand forecasting and dynamic safety stock adjustment embed machine learning into orchestration workflows. Adoption concentrates among India's metropolitan logistics corridors where inventory velocity determines working capital efficiency.
Software solutions anchor current revenue concentration; integration tools are climbing the fastest as middleware demand outpaces greenfield platform purchases.
End User:
Channel complexity and order volume shape procurement priorities across the customer base.
- Retailers:Omnichannel department stores and specialty chains require unified visibility across physical storefronts, web properties, and marketplace presences. Australia's ACCC consumer protection frameworks mandate returns processing capabilities that influence vendor selection.
- E-commerce Platforms:Marketplace operators in Indonesia, Vietnam, and Thailand impose standardized order management APIs on third-party sellers. This enforcement accelerates platform consolidation and reduces vendor fragmentation.
- Wholesalers:B2B distributors manage complex pricing tiers, volume breaks, and contract terms across fragmented buyer networks. Procurement is shifting toward API-first architectures that accommodate custom integration requirements.
- Distributors:Third-party logistics providers coordinate multi-brand inventory pools across shared warehouse networks. India's PLI scheme for electronics manufacturing expands captive fulfillment networks requiring distributor-grade orchestration capabilities.
Revenue concentration sits with e-commerce platforms; wholesalers represent the steepest expansion trajectory as B2B digitization accelerates.
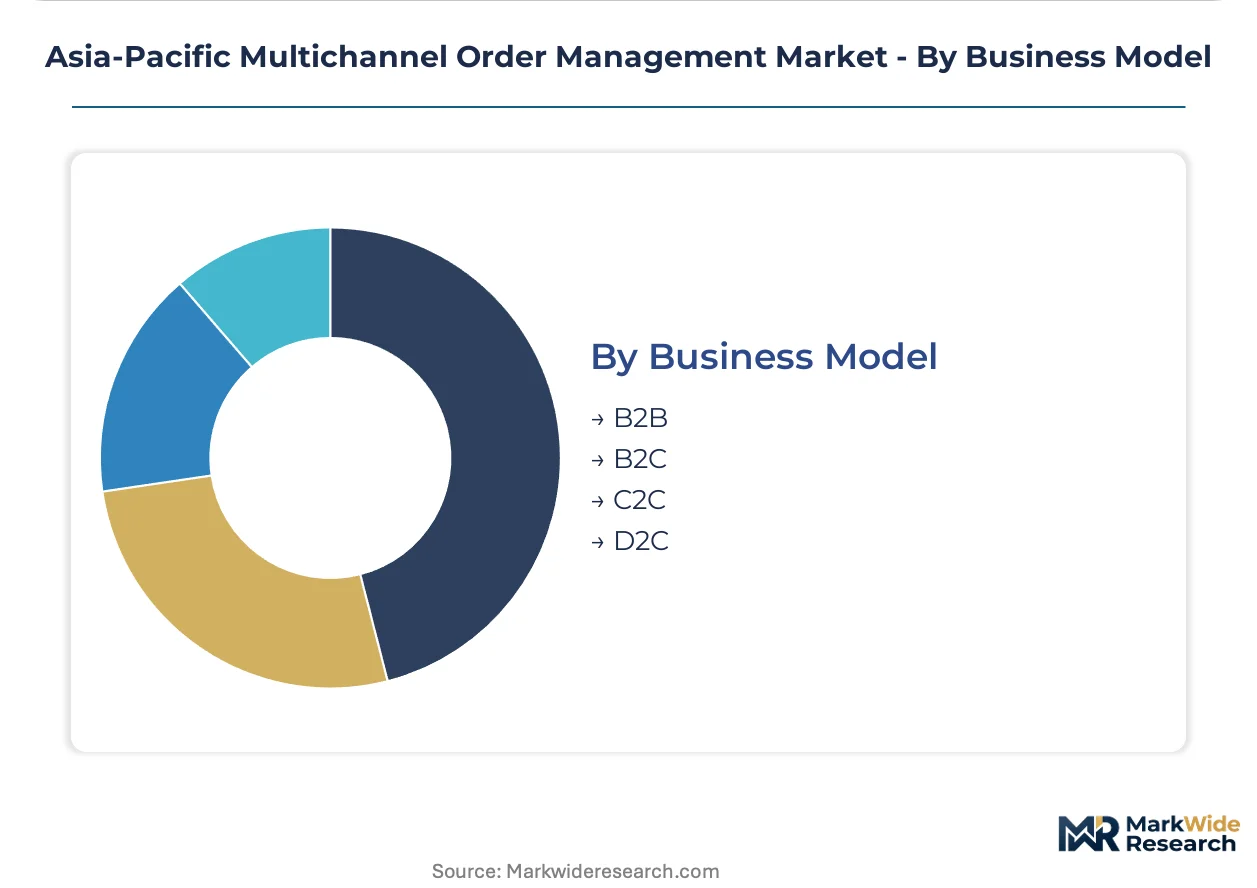
Business Model:
Transaction patterns determine workflow complexity and integration touchpoint density.
- B2B:High-value, low-frequency orders with negotiated terms, approval workflows, and contract pricing. Oracle Corporation dominates this segment through database-to-application stack control for complex order orchestration.
- B2C:High-velocity, standardized transactions demanding real-time inventory accuracy and automated carrier selection. Southeast Asian marketplace consolidation drives standardization across this category.
- C2C:Peer-to-peer marketplace transactions with irregular fulfillment patterns and limited seller infrastructure. Platform operators absorb order management complexity to reduce friction for individual sellers.
- D2C:Factory-to-consumer channels bypass traditional distributor networks. China's SAMR platform governance rules and Indonesia's consumer electronics vertical show the fastest D2C adoption as brand manufacturers build owned storefronts.
B2C transaction volume dominates current platform utilization; D2C channels gain share fastest as manufacturing brands disintermediate wholesale intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Singapore and Australia sits at a 40-60% premium over Southeast Asian markets, reflecting divergent infrastructure maturity and compliance cost absorption across the Asia-Pacific fulfillment corridor.
India
TRAI's data localization mandates and the PLI scheme for electronics manufacturing are expanding captive fulfillment networks. Mumbai and Bangalore logistics corridors concentrate platform deployment for factory-direct channel coordination. Domestic cloud infrastructure investments are accelerating sovereign hosting requirements for cross-border operators.
China
SAMR platform governance rules and dual carbon goals are tightening compliance layers for foreign software providers serving mainland marketplace integrations. Yangtze River Delta manufacturing clusters are driving D2C channel experimentation as factory brands bypass wholesale intermediaries. Shanghai-based hyperscale partnerships are emerging as mandatory for data residency compliance.
Australia
ACCC consumer protection frameworks and retail technology modernization programs are channeling government co-financing toward cloud-native deployments. Sydney and Melbourne metropolitan logistics networks anchor mid-tier department store chain upgrades. Returns processing specifications embedded in vendor selection criteria are reshaping procurement priorities.
Japan
METI e-commerce standards and JIS certification requirements are compressing product release cycles through simultaneous compliance testing. Kanto and Kansai retail conglomerates maintain stringent internal security protocols favoring hybrid architectures. Osaka-based warehouse management system upgrades are confronting 15-20 year legacy integration debt.
Southeast Asia
Indonesian marketplace operators mandate unified order management APIs for third-party sellers, accelerating platform standardization across Jakarta and Surabaya logistics hubs. Vietnamese manufacturing corridor expansion is creating whitespace for factory-to-consumer direct channels. Thailand's e-commerce consolidation is driving multi-tenant SaaS adoption among mid-market distributors.
Asia-Pacific Multichannel Order Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the middleware and analytics layers. The vendor base stratifies across three concentration levels: global enterprise suites, regional cloud-native specialists, and legacy ERP extenders. Two strategic archetypes dominate: vertically integrated platform providers and API-first integration tool vendors. Competitive moves center on sovereign cloud partnerships and headless commerce middleware acquisitions.
Within the IT services heritage tier, HCL Technologies anchors enterprise-grade deployment capabilities for hybrid cloud architectures. Zoho Corporation exemplifies vertically integrated platform economics sustaining pricing flexibility for mid-market retailers. Oracle Corporation occupies a position in high-complexity B2B order orchestration through database-to-application stack control.
| Leading Market Players |
|---|
| HCL Technologies |
| Zoho Corporation |
| Vinculum |
| Unicommerce eSolutions |
| Delhivery |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Salesforce |
| Others |
Pricing and Supply Chain Analysis
TRAI's data localization mandates as a regulatory chokepoint determine both tiered pricing spreads across sovereign cloud deployments and supply chain shape through forced in-region infrastructure duplication. Compliance cost absorption separates premium-priced hybrid architectures from economy-tier multi-tenant SaaS offerings.
Pricing Analysis
Enterprise retailers anchor subscription-based SaaS pricing across three-tier structures separating premium API-unlimited tiers from standard volume-capped and economy self-service levels. Price differentiation rests on integration complexity and data residency certification levels. Cost compression in the economy tier intensifies as Indonesian marketplace operators mandate standardized APIs for third-party sellers. Mid-market distributors in Vietnam and Thailand exhibit highest price sensitivity; Japanese department store chains with legacy ERP integration debt demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculus for hardware-dependent on-premises deployments. Software development concentrates in India, Singapore, and Australia; cloud infrastructure feeds from domestic hyperscale partnerships in Mumbai, Bangalore, and Sydney. Raw material dependencies span server components, data center real estate, and specialized talent pools. Distribution runs through direct vendor-to-retailer contracts and systems integrator channels including HCL Technologies and regional IT services providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific multichannel order management market sits at a platform-economics inflection where API standardization by Indonesian and Vietnamese marketplace operators is collapsing vendor fragmentation into interoperable layer-cake architectures.
For Market Incumbents: Entrench hybrid cloud deployment capabilities through sovereign cloud partnerships in Mumbai and Sydney data centers. Deepen backward integration into headless commerce middleware acquisitions before API virtualization erodes platform lock-in. Oracle Corporation's database-to-application stack control represents the defensive benchmark for high-complexity B2B order orchestration retention. For New Entrants and Emerging Players: Vietnam's manufacturing corridor expansion represents the most penetrable entry point for factory-to-consumer direct channel orchestration bypassing traditional distributor networks. Australia's retail technology modernization programs offer government co-financed adoption pathways for mid-tier department store chains. A vertical-specific go-to-market angle targeting Indonesia's consumer electronics vertical with unified B2B-B2C order stream capabilities accelerates initial traction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors API-first integration tool vendors over end-to-end suite providers. Long-term viability over a multi-year horizon favors acquisition targets with established carrier API connectivity across India's fragmented last-mile logistics landscape. The signal to watch is METI certification timeline compression in Japan forcing simultaneous compliance testing investments that strain smaller vendor balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Headless commerce middleware acquisitions virtualize storefront-OMS coupling for South Korean fashion retailers. |
| Strategic Partnership | Sovereign cloud alliances with domestic hyperscalers satisfy TRAI data residency mandates for cross-border operators. |
| Geographic Expansion | Mumbai and Bangalore data center investments capture India's PLI scheme electronics manufacturing fulfillment network growth. |
| Product Launch | AI-driven demand forecasting modules enable dynamic safety stock adjustments for India's metropolitan logistics corridors. |
| Acquisition of Specialist Firm | Middleware connectivity providers bridge 15-20 year-old Japanese warehouse management systems to modern marketplace APIs. |
Research Methodology
The analysis maps cloud-native, hybrid, and on-premises deployment configurations, each validated through platform engineering directors, IT procurement officers at retail conglomerates, systems integration specialists, and marketplace operator technical leads. Primary interview insights triangulate against secondary sources including TRAI regulatory filings, METI e-commerce standard documentation, ACCC consumer protection framework updates, and hyperscaler capex disclosures. Bottom-up merchant adoption modeling and top-down IT services market sizing converge through iterative reconciliation.
Forecast assumptions hold fixed TRAI's data localization enforcement intensity and India's PLI scheme continuation across the projection horizon. Segmentation dimensions span deployment architecture, solution type, end-user category, and business model. CAGRs derive from installed base growth rates, replacement cycle compression, and new merchant acquisition trajectories. Industry-specific inputs incorporate API standardization mandates by Indonesian marketplace operators and Australia's retail technology modernization program disbursement schedules.
Macroeconomic conditions sit as an overlay; deviation in cross-border data governance enforcement or cloud infrastructure investment cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and sovereign cloud partnership formation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Social Networking App Market
Digital Solutions
Electronic Discovery Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Mainframe Modernization Services Market