
 Intelligent Virtual Store Design Solution Market | 2026-2036
Intelligent Virtual Store Design Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Virtual Store Design Solution Market Foresight
Real-time ray tracing is restructuring rendering economics for virtual store environments, slashing hardware requirements while improving visual fidelity. Dassault Systèmes leverages its CATIA heritage to anchor high-fidelity simulation workflows for luxury retail flagships. Autodesk Inc. competes through Revit-integrated BIM pathways that bridge architectural planning with merchandising execution. Microsoft Corporation extends its Azure cloud fabric to sustain elastic compute for multi-user collaborative design sessions.
Intelligent virtual store design solutions comprise software platforms that generate photorealistic three-dimensional retail environments using spatial computing, physics-based lighting models, and behavioral simulation engines to optimize merchandise placement, traffic flow, and conversion metrics before capital deployment. Cloud-based solutions lead deployment architecture as elasticity matches the episodic nature of seasonal redesign cycles, while on-premise installations retain footholds among retailers with stringent data sovereignty requirements. Interactive platforms represent the fastest-growing product type as gesture-controlled and VR-native interfaces displace keyboard-mouse workflows for merchandising teams.
FCC guidelines on broadband infrastructure shape cloud delivery reliability for US retail deployments, while GDPR compliance requirements in Europe constrain how European retailers process customer behavioral data within simulation environments. The EU AI Act introduces additional scrutiny for automated layout optimization algorithms that influence purchasing decisions. Stakeholders must weigh regulatory fragmentation against the operational gains of centralized cloud architectures when selecting deployment models.
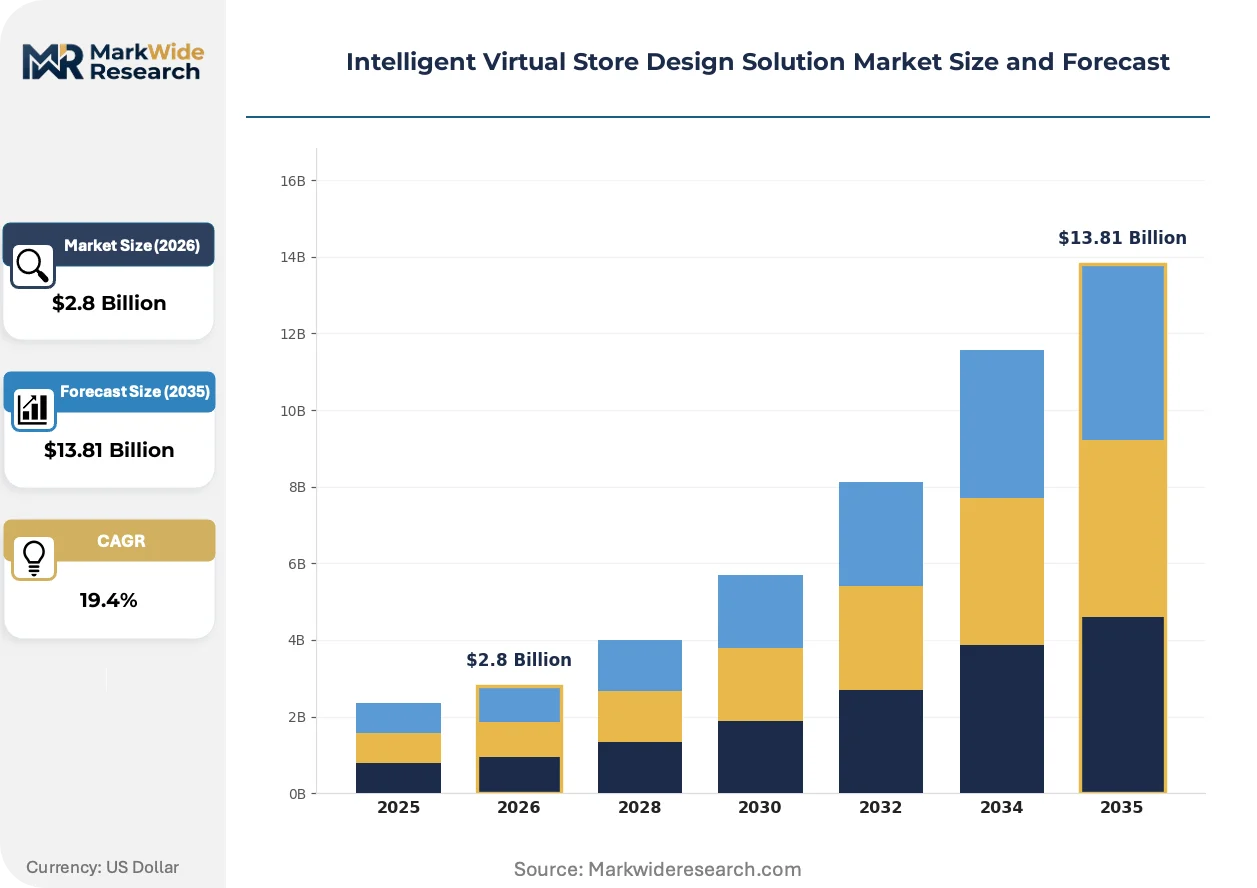
Market Dynamics
Cloud-native rendering pipelines are collapsing the cost barrier for photorealistic store simulation, forcing legacy on-premise vendors to rearchitect around GPU elasticity or cede mid-market accounts to SaaS entrants.
Growth Catalysts
- EU AI Act compliance mandates:Automated layout optimization tools face algorithmic transparency requirements that favor established platforms with audit-ready documentation, consolidating procurement toward enterprise-grade vendors.
- Flagship retail expansion:Luxury brands in Milan, Paris, and New York deploy digital twin workflows to prototype experiential zones before capital commitment, normalizing simulation as a standard pre-construction phase.
- Ray tracing hardware democratization:NVIDIA's RTX ecosystem and AMD's RDNA architectures slash per-workstation costs for real-time lighting simulation, extending high-fidelity tools from flagship specialists to regional retail chains.
Market Restraints
- Cloud egress cost volatility:Multi-terabyte asset libraries trigger unpredictable bandwidth charges that distort total cost of ownership calculations for seasonal redesign cycles.
- GDPR behavioral data constraints:European retailers cannot freely import customer movement patterns from physical stores into simulation environments, degrading traffic flow accuracy versus US counterparts.
- Rendering compute supplier concentration:AWS, Azure, and Google Cloud dominate GPU instance availability, creating pricing power asymmetry for vendors without multi-cloud orchestration capabilities.
Strategic Opportunities
- India organized retail buildout:Reliance Retail and Tata Trent expansion plans lack legacy CAD infrastructure, presenting greenfield SaaS adoption without migration friction.
- Quick-service restaurant simulation:Drive-thru throughput optimization and kitchen workflow modeling represent adjacent verticals with similar physics-based spatial requirements.
- US IRA commercial building incentives:Energy-efficient store design tax credits reward simulation platforms that integrate HVAC and lighting load modeling alongside merchandising workflows.
Industry Challenges
- Spatial computing talent scarcity:The intersection of architectural visualization, game engine scripting, and retail operations knowledge commands premium compensation that squeezes vendor margins.
- Enterprise ERP integration complexity:Merchandising data residing in SAP, Oracle, and custom legacy systems requires brittle middleware development for real-time inventory visualization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Virtual Store Design Solution Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Visualization Tools, Simulation Software, Interactive Platforms, Design Templates End User: Retail Chains, Independent Stores, E-commerce Platforms, Hospitality Businesses Deployment: Cloud-Based Solutions, On-Premise Installations, Hybrid Systems, Mobile Applications Service Type: Consultation Services, Custom Development, Technical Support, Continuous Training |
| Companies Covered | Cisco Systems, Dassault Systèmes, Adobe Inc., Autodesk Inc., IBM Corporation, InContext Solutions, Microsoft Corporation, SAP SE, Shopify Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Virtual Store Design Solution Market Shifts & Advancements
Generative AI is compressing asset creation timelines from weeks to hours, while spatial computing hardware maturation is shifting interaction paradigms from screen-based to embodied design review.
Neural radiance fields (NeRFs) and Gaussian splatting techniques are expanding into retail environment reconstruction, enabling merchandisers to capture existing store geometries with smartphone cameras rather than LiDAR scanning. Mid-market apparel chains in Germany and South Korea pilot these workflows for rapid seasonal resets. The technology is compressing site survey costs and accelerating renovation planning cycles for portfolios with hundreds of locations.
The EU AI Act's risk classification framework imposes documentation burdens on automated layout recommendation engines that influence purchasing decisions. Vendors serving European luxury houses must maintain technical files proving human oversight mechanisms. French and Italian retailers are responding by bifurcating product roadmaps, reserving full automation for US and Middle East deployments while deploying assistive-only modes in EU jurisdictions.
Merchandising teams increasingly reject perpetual license models in favor of consumption-based pricing tied to render minutes and concurrent user seats. This shift pressures vendors with legacy revenue recognition practices to restructure financial reporting. The transition is most visible among US specialty retailers with seasonal staffing fluctuations that render annual capacity planning impractical.
Intelligent Virtual Store Design Solution Market Segmentation
Retailers select virtual store design platforms based on technical sophistication, integration requirements, and capital constraints. Segmentation reveals how deployment preferences diverge between flagship luxury brands prioritizing photorealism and mid-market chains optimizing for speed-to-execution.
Product Type:
Replacement cycles accelerate as ray tracing hardware democratization renders legacy visualization tools obsolete within 24-36 months.
- 3D Visualization Tools:Photorealistic rendering engines leveraging real-time ray tracing and physics-based lighting models. Demand concentrates among Milan and Paris luxury houses prototyping experiential flagship zones where millimeter-accurate material representation determines capital approval.
- Simulation Software:Behavioral modeling platforms integrating customer flow algorithms and conversion prediction engines. Regional retail chains in Germany and South Korea deploy these for rapid seasonal resets across portfolios with hundreds of locations.
- Interactive Platforms:Gesture-controlled and VR-native interfaces displacing keyboard-mouse workflows for merchandising teams.
- Design Templates:Pre-configured store layouts with modular fixture libraries for standardized rollouts.
Volume placements concentrate in 3D Visualization Tools; the faster expansion belongs to Interactive Platforms.
End User:
Cost tier stratification separates enterprise procurement with dedicated simulation teams from self-service adoption by smaller operators.
- Retail Chains:Multi-location operators deploying digital twin workflows across flagship, full-line, and outlet formats. US specialty retailers with seasonal staffing fluctuations favor consumption-based pricing tied to render minutes rather than perpetual licenses.
- Hospitality Businesses:Hotels and cruise lines adapting retail simulation for onboard boutique and lobby store planning.
- E-commerce Platforms:Pure-play digital retailers building physical showrooms and pop-up formats.
- Independent Stores:Single-location merchants leveraging smartphone-based NeRF capture for renovation planning without LiDAR investment.
Procurement scale peaks with Retail Chains; Hospitality Businesses are climbing the fastest as experiential retail extends into accommodation sectors.
Deployment:
Application context dictates architecture choice—epodic seasonal redesigns favor elasticity while continuous operations prioritize latency control.
- Cloud-Based Solutions:Elastic compute matching episodic seasonal redesign cycles with GPU instance scaling. GDPR constraints in Europe degrade traffic flow accuracy versus US counterparts due to behavioral data import restrictions.
- Hybrid Systems:Split architectures keeping sensitive merchandising data on-premise while burst-rendering to cloud.
- On-Premise Installations:Fixed-capacity deployments retaining footholds among retailers with stringent data sovereignty requirements.
- Mobile Applications:Lightweight site survey and rapid markup tools for field merchandising teams.
Revenue concentration sits with Cloud-Based Solutions; Hybrid Systems are gaining share fastest as regulatory fragmentation complicates centralized architectures.
Service Type:
Customer maturity determines service mix—early adopters require heavy customization while scaled operations shift toward training and self-sufficiency.
- Custom Development:Bespoke middleware bridging simulation platforms with SAP, Oracle, and legacy ERP systems. The intersection of architectural visualization, game engine scripting, and retail operations knowledge commands premium project rates.
- Consultation Services:Strategic advisory on layout optimization and customer flow design.
- Technical Support:Break-fix and platform maintenance for production environments.
- Continuous Training:Ongoing skill development as generative AI compresses asset creation timelines and shifts required competencies.
Project bookings cluster in Custom Development; Continuous Training shows the steepest expansion trajectory as platform capabilities evolve faster than internal team skills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retailers concentrate procurement of virtual store design platforms, with flagship luxury brands and specialty chains driving SaaS adoption. FCC broadband infrastructure guidelines shape cloud delivery reliability for multi-user collaborative sessions. Cloud egress cost volatility distorts total cost of ownership calculations for seasonal redesign cycles.
United States
FCC guidelines on broadband infrastructure determine cloud delivery reliability for retail deployments across flagship and outlet formats. The IRA commercial building incentives reward simulation platforms integrating HVAC and lighting load modeling. New York and Los Angeles anchor luxury flagship prototyping where digital twin workflows normalize as standard pre-construction phases.
Germany
GDPR behavioral data constraints prevent European retailers from freely importing customer movement patterns into simulation environments. The EU AI Act imposes algorithmic transparency requirements on automated layout optimization tools. Berlin and Munich house mid-market apparel chains piloting NeRF capture workflows for rapid seasonal resets across hundreds of locations.
France
Luxury houses in Paris deploy high-fidelity simulation workflows for experiential flagship zones before capital commitment. EU AI Act risk classification frameworks mandate technical files proving human oversight mechanisms for automated recommendation engines. Milan-adjacent French retailers bifurcate product roadmaps, reserving full automation for non-EU deployments.
India
Reliance Retail and Tata Trent expansion plans present greenfield SaaS adoption without legacy CAD migration friction. The PLI scheme for electronics manufacturing indirectly supports cloud infrastructure buildout for retail technology adoption. Mumbai and Bangalore concentrate organized retail buildout where smartphone-based NeRF capture accelerates renovation planning for portfolio operators.
South Korea
Regional retail chains deploy behavioral modeling platforms for rapid seasonal resets across portfolios with hundreds of locations. The MFDS does not regulate this sector directly, though national data localization requirements shape cloud architecture decisions. Seoul anchors mid-market apparel chain adoption of Gaussian splatting techniques for existing store geometry capture.
Intelligent Virtual Store Design Solution Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors and emerging SaaS entrants contesting mid-market accounts. The vendor base organizes around three archetypes: heritage CAD platforms with retail verticalization, cloud-native challengers with consumption-based pricing, and ERP-integrated suite providers. Consolidation pressures favor vendors with multi-cloud orchestration capabilities over single-cloud dependencies. M&A activity targets middleware specialists bridging simulation engines with legacy merchandising systems.
Within the heritage platform tier, Dassault Systèmes and Autodesk Inc. occupy positions anchored by decades of architectural visualization heritage. Microsoft Corporation exemplifies the cloud fabric provider archetype, extending elastic compute infrastructure to sustain collaborative design sessions. These three represent divergent strategic postures: CAD-native depth versus cloud-native elasticity versus platform-layer abstraction.
| Leading Market Players |
|---|
| Cisco Systems |
| Dassault Systèmes |
| Adobe Inc. |
| Autodesk Inc. |
| IBM Corporation |
| InContext Solutions |
| Microsoft Corporation |
| SAP SE |
| Shopify Inc. |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investments by hyperscalers anchor supply positions for rendering compute while simultaneously compressing pricing power for independent software vendors lacking multi-cloud orchestration. This vertical integration into GPU elasticity shapes how platform providers structure consumption-based contracts and how buyers negotiate render-minute commitments.
Pricing Analysis
Volume placements concentrate in SaaS subscription tiers while margin capture belongs to enterprise custom development engagements. Three-tier pricing structure across premium, standard, and economy levels separates flagship luxury houses with dedicated simulation teams from mid-market regional chains favoring self-service adoption. Pricing pressure stems from cloud egress cost volatility distorting total cost of ownership for seasonal redesign cycles. Independent stores exhibit highest price sensitivity due to per-workstation cost constraints, whereas hospitality businesses demonstrate lowest sensitivity given experiential investment mandates.
Supply Chain Analysis
Freight costs for specialized GPU hardware shipments from Taiwan, South Korea, and USA concentrate supply risk for rendering infrastructure procurement. The vendor ecosystem draws from NVIDIA's RTX ecosystem for ray tracing silicon, AMD RDNA architectures for mid-tier workstations, and hyperscaler cloud fabrics for elastic burst capacity. Single-source vulnerability in GPU instance availability at AWS, Azure, and Google Cloud creates pricing power asymmetry for vendors without multi-cloud orchestration. Distribution runs through direct enterprise sales for flagship deployments and channel partners for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into rendering compute infrastructure represents the decisive competitive race, with upstream control over GPU supply chains and downstream capture of merchandising data flows determining long-term platform viability.
For Market Incumbents: Deepen ERP integration capabilities through bespoke middleware development bridging simulation engines with SAP and Oracle merchandising systems. Consolidate procurement toward audit-ready documentation suites that satisfy EU AI Act algorithmic transparency requirements for automated layout optimization tools. Cloud-native challengers with consumption-based pricing threaten mid-market accounts previously secured through perpetual licensing. For New Entrants and Emerging Players: Regional retail chains in India lacking legacy CAD infrastructure present the most penetrable buyer archetype for greenfield SaaS adoption. Quick-service restaurant drive-thru throughput optimization offers adjacent vertical expansion with similar physics-based spatial requirements. Go-to-market positioning should emphasize smartphone-based NeRF capture workflows that eliminate LiDAR investment barriers for portfolio operators with hundreds of locations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP suite providers seeking merchandising visualization capabilities. Long-term viability hinges on multi-cloud orchestration competencies that insulate against GPU instance pricing power asymmetry. Middleware specialists bridging simulation engines with legacy merchandising systems signal acquisition inflection as consolidation pressures intensify.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Revit-integrated BIM pathways at Autodesk bridge architectural planning with merchandising execution workflows. |
| Acquisition of Specialist Firm | Middleware developers connecting simulation engines to SAP merchandising systems command premium valuations. |
| Strategic Partnership | Azure cloud fabric extensions sustain elastic compute for multi-user collaborative design sessions. |
| Product Launch | Gesture-controlled VR-native interfaces displace keyboard-mouse workflows for seasonal merchandising teams. |
| Geographic Expansion | Reliance Retail and Tata Trent expansion in India enables greenfield SaaS adoption without migration friction. |
Research Methodology
Independent corroboration across primary interviews with retail technology executives, merchandising operations directors, and cloud infrastructure procurement officers underwrites the qualitative findings. Secondary validation draws from hyperscaler capex disclosures, SEC filings by listed retail technology vendors, and customs records for specialized GPU hardware shipments. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across deployment architectures and end-user categories.
Rate-of-change decomposition separates expansion in cloud-native rendering pipelines from contraction in perpetual license revenue recognition practices. The analytical framework models deployment model, organization size, vertical integration depth, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level adoption curves weighted by GPU elasticity penetration and seasonal redesign cycle frequency. Forecast inputs incorporate EU AI Act compliance timelines and FCC broadband infrastructure deployment schedules.
Revisions become necessary when hyperscaler GPU instance pricing shifts, EU AI Act enforcement interpretations diverge, or NeRF capture technology commoditizes site survey economics faster than projected. Forecasts reflect documented assumptions about cloud egress cost trajectories and spatial computing talent availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Dataops Platform Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Commodity Supply Chain Management Solution Market