
 Lead Generation Solutions Market | 2026-2036
Lead Generation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Generation Solutions Market Foresight
B2B technology is restructuring the core demand profile for lead generation solutions as enterprise software vendors replace retail and consumer brands as the largest client category. CIENCE Technologies leverages proprietary research teams to sustain high-touch appointment-setting services for complex sales cycles. WebFX anchors its competitive position through integrated SEO and paid media execution across mid-market accounts. Martal Group specializes in fractional sales development for North American SaaS entrants, competing on speed-to-pipeline rather than volume metrics.
Lead generation solutions encompass data-driven systems and managed services that identify, qualify, and nurture prospective customers through multi-channel outreach, typically incorporating intent signals, behavioral scoring, and CRM synchronization to optimize sales conversion rates. The primary commercial purpose centers on reducing customer acquisition cost while improving pipeline predictability for revenue teams. Email marketing and content marketing represent mature, high-margin segments where established vendors extract recurring value through proprietary audience databases and editorial workflows. AI analytics within the technology dimension is expanding fastest as predictive scoring and generative personalization reshape service economics. Subscription-based engagement models dominate enterprise relationships, though performance-based contracts are gaining traction among growth-stage buyers seeking risk-aligned partnerships.
The US Federal Trade Commission and state attorneys general enforce telemarketing and data privacy standards that constrain automated outreach cadences and list sourcing practices. The EU GDPR and ePrivacy Directive impose consent documentation requirements that elevate compliance costs for cross-border campaigns. Stakeholders must monitor emerging algorithmic transparency obligations under the EU AI Act as these frameworks extend to automated lead scoring and chatbot interactions, reshaping vendor liability and client procurement criteria.
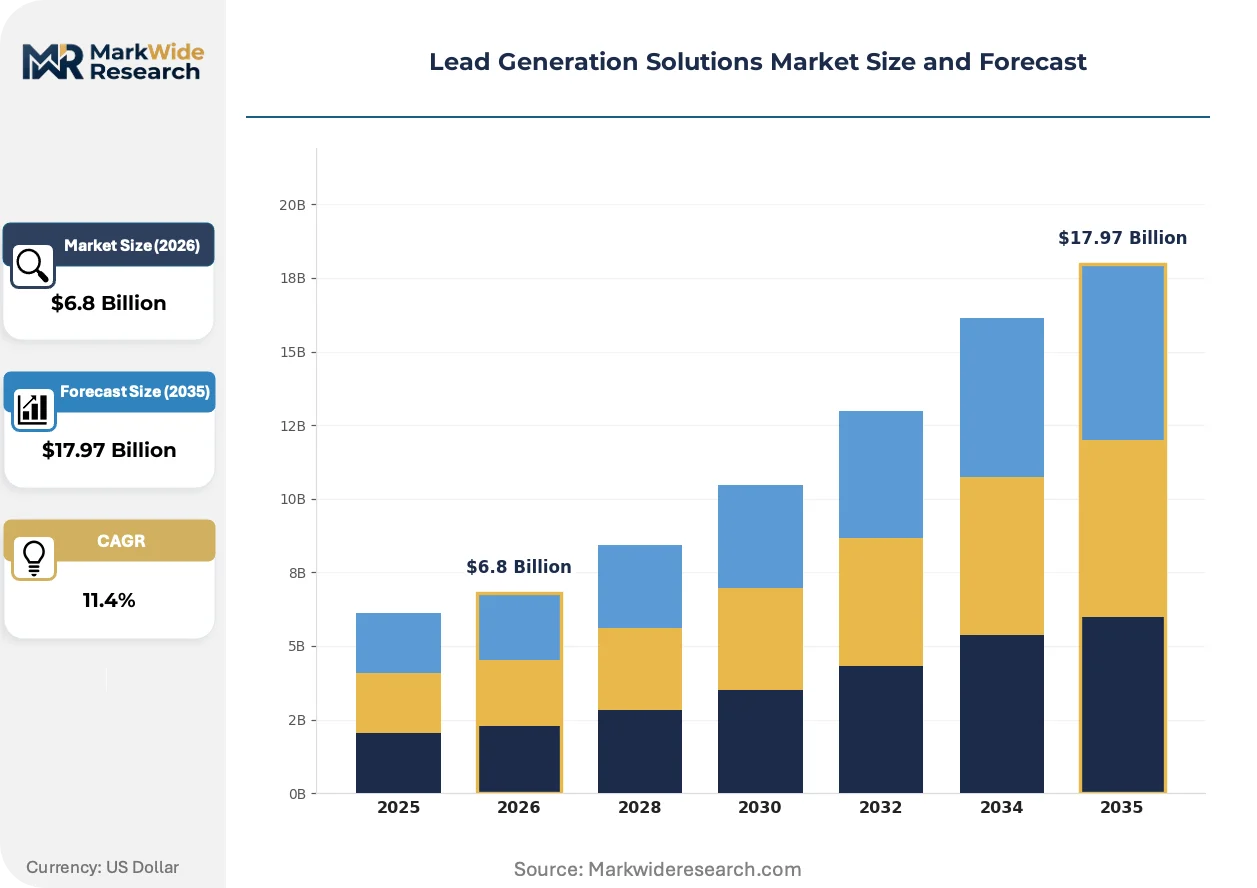
Market Dynamics
Intent-based prospecting tools are restructuring competitive economics as SaaS vendors and financial services firms replace retail brands as the primary demand source for lead generation solutions. The EU AI Act and US state privacy statutes are tightening consent requirements for automated outreach, elevating compliance architecture to a core vendor capability.
Growth Catalysts
- EU AI Act compliance infrastructure:Automated lead scoring and chatbot interactions now fall under algorithmic transparency obligations, creating demand for vendors with documented audit trails and consent management systems.
- India's startup ecosystem scaling:B2B sales operations across Bangalore, Mumbai, and Hyderabad are driving concentrated demand for appointment-setting services and fractional sales development.
- Intent signal integration:Behavioral data from content consumption patterns and technographic installs is enabling predictive prospecting that reduces customer acquisition cost for enterprise software vendors.
Market Restraints
- Cross-border data transfer friction:GDPR and ePrivacy Directive consent documentation requirements elevate operational costs for campaigns spanning European and North American markets.
- Third-party cookie deprecation:Google's phaseout of tracking identifiers in Chrome compresses addressable audience pools for programmatic lead acquisition channels.
- Sales development representative turnover:High attrition rates in outbound calling roles inflate training costs and degrade pipeline consistency for managed service providers.
Strategic Opportunities
- Generative personalization convergence:Large language models combined with proprietary intent databases enable dynamic email and LinkedIn outreach at scale previously requiring manual copywriting.
- Performance-based contract structures:Risk-aligned pricing models tied to qualified meetings or pipeline generated are gaining traction among growth-stage buyers with constrained upfront budgets.
- CRM synchronization depth:Native integrations with Salesforce, HubSpot, and Microsoft Dynamics that automate lead scoring updates and territory routing represent underexploited differentiation.
Industry Challenges
- Fractional sales talent scarcity:Experienced SDRs capable of navigating complex SaaS sales cycles command premium compensation, compressing margins for outsourced appointment-setting services.
- Multi-channel attribution complexity:Prospects engage across email, paid social, webinars, and direct mail, fragmenting credit assignment and complicating ROI demonstration to procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Generation Solutions Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Email Marketing, Content Marketing, Social Media Ads, SEO Tools Client Type: B2B Companies, E-Commerce, Startups, Enterprises Engagement Model: Pay-Per-Click, Subscription-Based, Freemium, Performance-Based Technology: CRM Software, Marketing Automation, Chatbots, AI Analytics |
| Companies Covered | MarketJoy, WebFX, CIENCE Technologies, Callbox, Belkins, Right Left Agency, Martal Group, SalesRoads, First Page Sage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Generation Solutions Market Shifts & Advancements
Predictive analytics and generative AI are compressing the economics of personalized outreach while regulatory frameworks reshape vendor liability and client procurement criteria across major markets.
AI-powered intent scoring engines aggregate technographic installs, content consumption patterns, and hiring signals to prioritize accounts with active buying cycles. Mid-market SaaS vendors and financial services firms are adopting these systems fastest, replacing static demographic filters with behavioral propensity models. The technology is expanding into real-time website personalization and dynamic sales playbooks that adapt messaging based on visitor firmographics.
The EU AI Act's risk-based classification system now covers automated systems that evaluate individuals for commercial purposes, including lead scoring algorithms and conversational chatbots. Vendors must maintain technical documentation, human oversight protocols, and transparency disclosures that elevate compliance costs but create defensible moats against less sophisticated competitors. European enterprise procurement teams are increasingly requiring AI conformity assessments as mandatory vendor qualification criteria.
Revenue operations teams are unbundling full-funnel agency retainers in favor of modular, outcome-aligned partnerships with specialized providers. Mid-market technology buyers now separate intent data licensing, creative production, and appointment-setting into distinct vendor relationships rather than consolidated managed services. This pattern is most pronounced in North American SaaS segments where procurement functions demand granular attribution and flexible contract terms.
Lead Generation Solutions Market Segmentation
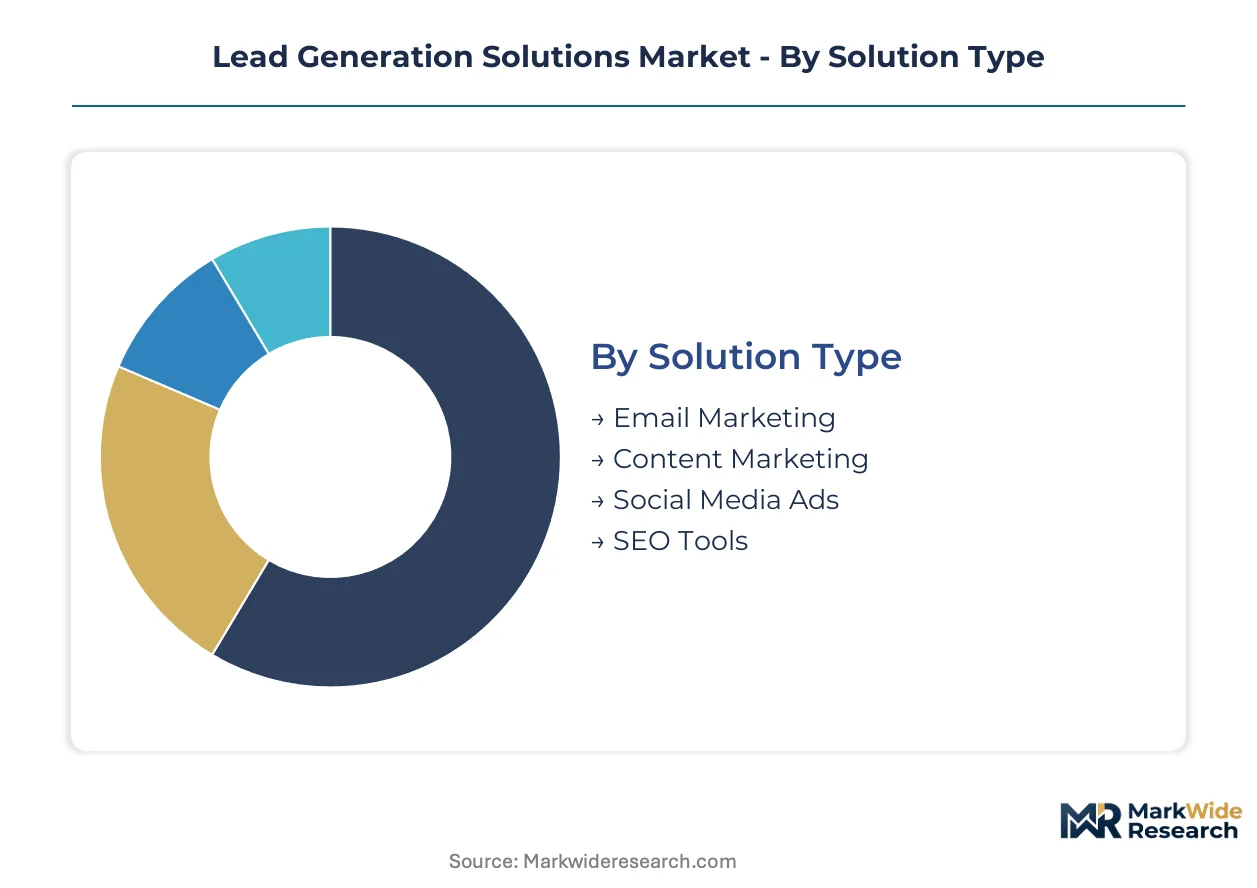
Lead generation solutions fragment across four critical dimensions that determine vendor capability requirements and client procurement criteria. Solution type dictates technical infrastructure investments. Engagement model shapes cash flow patterns and risk allocation between provider and buyer.
Solution Type:
Commercial buyers differentiate primarily by channel maturity and margin extraction potential rather than novelty or technical sophistication.
- Email Marketing:Proprietary audience databases and editorial workflows generate recurring revenue through list management and deliverability optimization. Demand concentrates among B2B SaaS vendors in North America seeking nurture sequences for extended sales cycles, constrained by GDPR and CAN-SPAM consent documentation burdens.
- Content Marketing:SEO-optimized assets and gated resource libraries attract inbound prospects through search authority building. Enterprises with complex products in financial services and healthcare verticals prioritize this channel, though attribution complexity complicates ROI demonstration to procurement teams.
- Social Media Ads:Paid amplification across LinkedIn, Meta, and emerging platforms targets demographic and firmographic segments.
- SEO Tools:Technical audit and keyword tracking platforms support organic traffic acquisition strategies.
Volume sits with Email Marketing; growth tilts toward AI Analytics.
Client Type:
Organizational scale and sales cycle complexity determine service customization depth and contract value thresholds.
- B2B Companies:Complex procurement processes and committee-based purchasing decisions demand account-based marketing approaches with multi-touch attribution. Technology vendors and professional services firms in the United States and Germany represent the core revenue base, facing pressure from fractional sales talent scarcity.
- Enterprises:Global coordination requirements and compliance mandates favor vendors with documented audit trails and cross-border data handling capabilities. Financial services conglomerates and healthcare systems prioritize GDPR and EU AI Act conformity assessments as mandatory qualification criteria.
- E-Commerce:Transaction velocity and cart abandonment recovery drive demand for automated trigger campaigns.
- Startups:Capital constraints and speed-to-revenue priorities favor performance-based pricing and rapid deployment timelines.
Revenue concentrates with Enterprises; expansion accelerates fastest among Startups.
Engagement Model:
Payment structure alignment with outcome measurability separates mature vendor relationships from experimental pilots.
- Subscription-Based:Recurring access to platforms and managed services provides predictable revenue streams and customer lifetime value optimization. SaaS vendors and mid-market agencies across the United Kingdom and Australia standardize on monthly or annual retainers, though procurement teams increasingly demand usage-based adjustments.
- Performance-Based:Fees tied to qualified meetings, pipeline generated, or closed revenue align vendor incentives with client outcomes. Growth-stage technology buyers with constrained upfront budgets drive adoption, accelerating most quickly in India's scaling startup ecosystem.
- Pay-Per-Click:Direct media cost pass-through with management fees supports campaign-specific testing.
- Freemium:Tiered feature access converts self-serve users to paid tiers through usage thresholds.
Margins favor Subscription-Based; contract velocity peaks with Performance-Based.
Technology:
Integration depth with existing revenue operations infrastructure determines vendor selection above standalone feature differentiation.
- AI Analytics:Predictive scoring engines aggregate technographic installs, content consumption patterns, and hiring signals to prioritize accounts with active buying cycles. Mid-market SaaS vendors and financial services firms adopt these systems fastest, replacing static demographic filters with behavioral propensity models.
- CRM Software:Native synchronization with Salesforce, HubSpot, and Microsoft Dynamics automates lead scoring updates and territory routing. Enterprise procurement teams mandate pre-built connectors as table stakes, elevating integration architecture to core competitive differentiation.
- Marketing Automation:Workflow orchestration across email, social, and web channels enables scaled personalization.
- Chatbots:Conversational interfaces qualify prospects and schedule meetings through natural language processing.
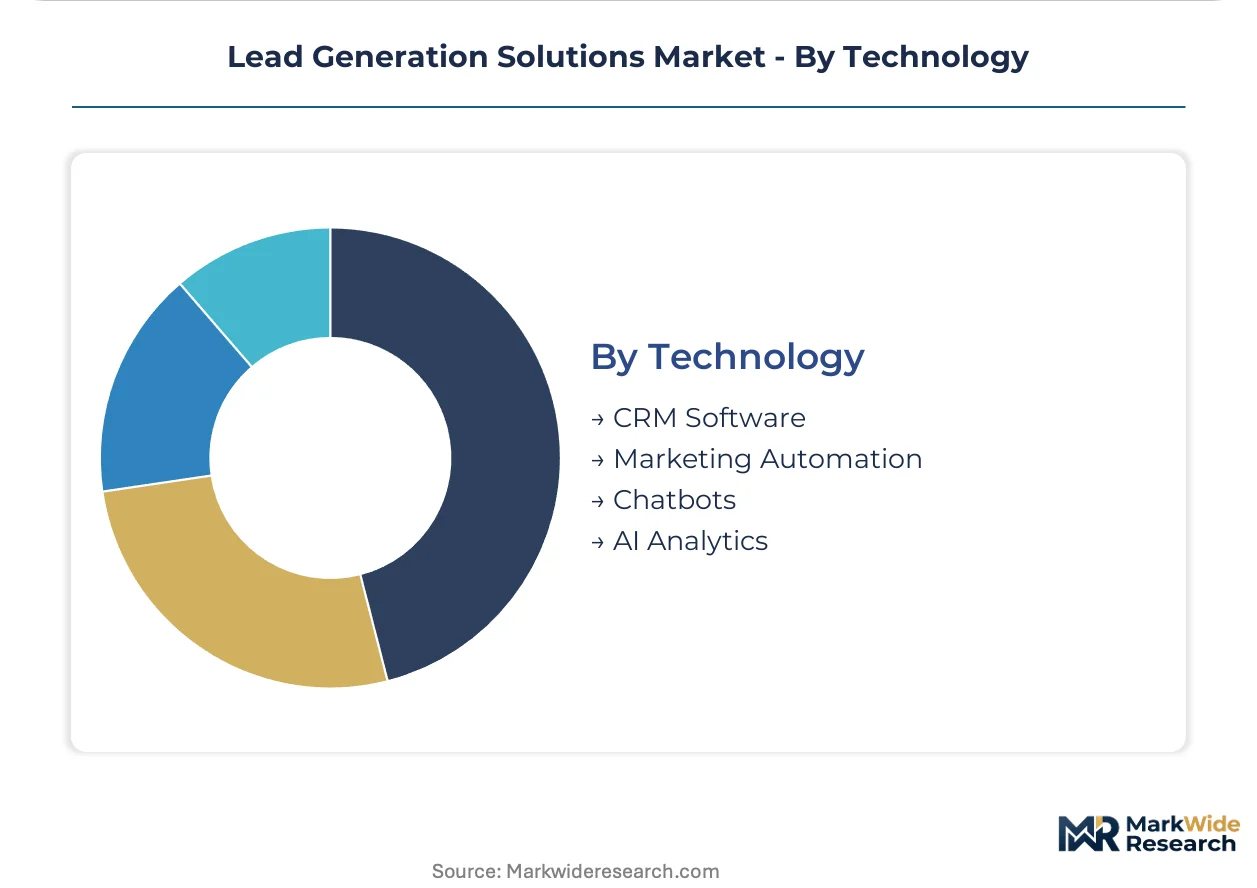
Adoption depth centers on CRM Software; capability expansion runs through AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Hyderabad concentrate India's startup ecosystem, driving demand for fractional sales development and appointment-setting infrastructure as B2B operations scale.
United States
Enterprise software vendors and financial services firms in New York and San Francisco generate concentrated demand for intent-based prospecting tools. The FTC enforces telemarketing standards that constrain automated outreach cadences. Austin and Boston host scaling SaaS clusters where procurement teams mandate native CRM integrations as table stakes.
Germany
Industrial automation and B2B manufacturing sectors in Munich and Stuttgart prioritize account-based marketing for complex procurement cycles. The EU AI Act imposes algorithmic transparency obligations on automated lead scoring systems. Berlin's startup density creates demand for performance-based contract structures among capital-constrained growth-stage buyers.
India
Bangalore, Mumbai, and Hyderabad anchor the fastest-expanding demand pool as venture-backed SaaS companies scale outbound sales operations. TRAI regulations govern telemarketing consent frameworks for cross-border campaigns. The Delhi-NCR corridor concentrates fractional SDR providers serving North American technology clients through time-zone arbitrage.
United Kingdom
London's fintech and professional services clusters drive subscription-based engagement with managed lead generation providers. GDPR and ePrivacy Directive compliance requirements elevate vendor qualification criteria for cross-border data handling. Manchester and Birmingham host mid-market agencies unbundling full-funnel retainers into modular service relationships.
Lead Generation Solutions Market Competitive Landscape
Top-tier vendors anchor enterprise relationships through integrated technology stacks, while mid-market specialists compete on speed-to-pipeline and outcome-aligned pricing. The vendor base stratifies across three tiers: full-service agencies with proprietary research capabilities, technology-enabled platforms emphasizing AI analytics, and boutique providers offering fractional sales talent. Strategic differentiation runs through M&A consolidation of intent data assets and deepening CRM synchronization architecture.
Within the technology-enabled tier, CIENCE Technologies and WebFX exemplify contrasting positioning archetypes, while Martal Group occupies a specialist niche in fractional sales development. CIENCE Technologies represents the high-touch managed service model with proprietary research teams. WebFX anchors the integrated digital marketing vector combining SEO and paid media execution. Martal Group exemplifies the speed-focused boutique structure targeting North American SaaS entrants with rapid deployment timelines.
| Leading Market Players |
|---|
| MarketJoy |
| WebFX |
| CIENCE Technologies |
| Callbox |
| Belkins |
| Right Left Agency |
| Martal Group |
| SalesRoads |
| First Page Sage |
| Others |
Supply & Pricing Matrix
The EU AI Act's algorithmic transparency mandates gate premium-tier pricing access for lead generation vendors with documented audit trails and consent management infrastructure, while excluding non-compliant providers from enterprise procurement shortlists in Germany and France.
Pricing Analysis
Lead-time-driven pricing separates vendors delivering qualified meetings within 30-day windows from those requiring extended research cycles, with premium tiers commanding 40-60% markups for speed-to-pipeline guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth with Salesforce, HubSpot, and Microsoft Dynamics ecosystems. Cost compression in the mid-market tier is intensifying because fractional SDR talent scarcity inflates personnel costs for appointment-setting services. Startup buyers in India and Southeast Asia exhibit highest price sensitivity, while financial services conglomerates in London and New York demonstrate lowest sensitivity due to compliance-driven vendor stickiness.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from SaaS vendors and financial services firms, bypassing intermediary agencies for native CRM-integrated solutions. Proprietary intent data assets concentrate in the United States, United Kingdom, and Israel, where technographic install tracking and content consumption pattern aggregation feed predictive scoring engines. Raw material dependencies center on third-party cookie alternatives, first-party data collection infrastructure, and large language model API access for generative personalization. Single-source vulnerability runs through dominant intent data providers, with tariff exposure minimal but regulatory restriction risk elevated under GDPR and EU AI Act cross-border enforcement. Distribution runs through certified partner networks and direct sales teams serving enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
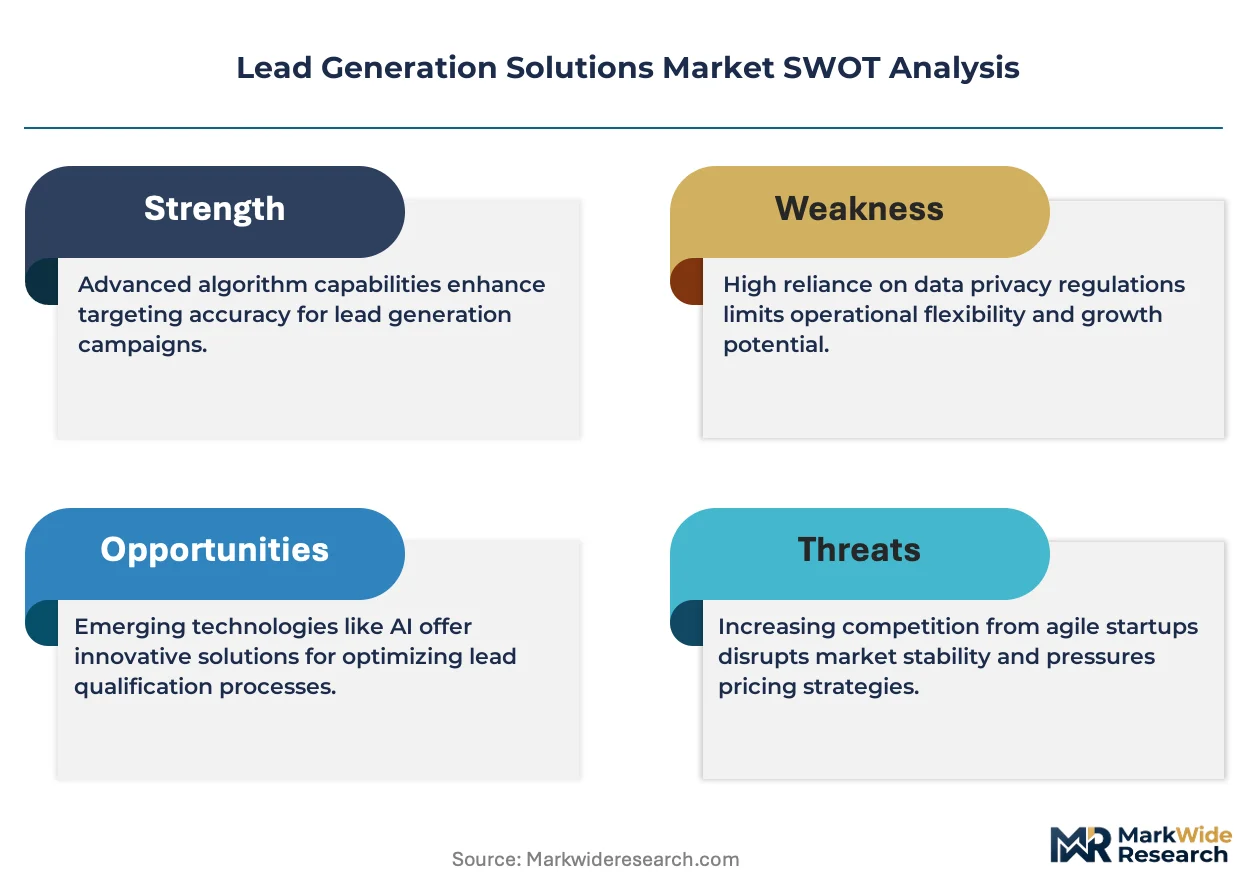
The EU AI Act's risk-based classification system for automated lead scoring creates a compliance moat that rewards vendors with pre-built audit documentation and human oversight protocols, raising barrier-to-entry costs for undercapitalized entrants.
For Market Incumbents: Deploy proprietary intent database consolidation to defend against unbundling trends as mid-market buyers separate data licensing from creative production and appointment-setting services. Acquire specialized providers in Bangalore and Hyderabad to capture India's scaling startup ecosystem demand while compressing delivery costs through time-zone arbitrage. Backward integration into first-party data collection infrastructure reduces dependency on deprecating third-party cookie alternatives. For New Entrants and Emerging Players: Enter via performance-based contract structures targeting growth-stage SaaS vendors in Berlin and Austin with constrained upfront budgets and speed-to-revenue priorities. White-space concentration sits with fractional sales development for North American SaaS entrants seeking rapid deployment timelines without enterprise-scale minimum commitments. Go-to-market leverage centers on native HubSpot and Salesforce integrations as table-stakes qualification for procurement shortlists. For Investors and Strategic Acquirers: EU AI Act conformity assessment mandates becoming standard procurement criteria is the leading indicator that compliance infrastructure will separate acquirable assets from stranded technology. Long-term viability favors vendors with documented algorithmic transparency protocols and cross-border data handling capabilities serving financial services and healthcare verticals. Acquisition target archetype: mid-market specialists with proprietary research teams and established GDPR audit trails. Signal to monitor: procurement teams mandating AI conformity assessments as mandatory vendor qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Intent Data Asset Acquisition | Consolidation of proprietary technographic and behavioral databases creates defensible moats against unbundling trends. |
| EU AI Act Compliance Infrastructure | Pre-built audit trails and human oversight protocols unlock enterprise procurement access in Germany and France. |
| India Delivery Center Expansion | Bangalore and Hyderabad operations capture cost arbitrage serving North American SaaS clients. |
| Performance-Based Contract Rollout | Risk-aligned pricing structures penetrate capital-constrained startup segments in Austin and Berlin. |
| Native CRM Integration Deepening | Salesforce, HubSpot, and Microsoft Dynamics connectors automate lead scoring updates and territory routing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with revenue operations leaders, SDR team managers, procurement officers at enterprise SaaS vendors, and compliance directors at financial services firms. Bottom-up triangulation cross-validated vendor-reported contract values against top-down market sizing derived from FTC enforcement actions, EU AI Act implementation guidance, and TRAI telemarketing consent framework disclosures. Secondary sources encompassed GDPR enforcement databases, EU AI Act risk classification documentation, and startup ecosystem investment tracking from Indian venture capital disclosures.
Data-stream reconciliation across intent data licensing volumes, appointment-setting service contracts, and AI analytics platform subscriptions informed segmentation modeling. The analytical framework projected expansion across solution type, engagement model, client scale, and technology integration depth throughout the forecast period. CAGRs derived from historical contract value trajectories adjusted for regulatory implementation timelines and third-party cookie deprecation impacts. Industry-specific inputs incorporated SDR attrition rate trends, CRM integration adoption curves, and cross-border data transfer cost escalations under GDPR and ePrivacy Directive enforcement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or unexpected third-party cookie deprecation delays. Periodic stress-testing of base assumptions is recommended, particularly regarding fractional sales talent availability in North American markets and intent data provider consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
UAE ICT Market
Digital Solutions
Data Classification Tool Market