
 UK Virtual Tour Market | 2026-2036
UK Virtual Tour Market Size, Share, and Industry Trends Forecast 2026-2036
UK Virtual Tour Market Insights
The capability gap between hardware-owning platform operators and software-only service providers is collapsing as cloud rendering commoditizes photogrammetry pipelines. Matterport sustains its position through proprietary camera-to-cloud workflows that lock in recurring subscription revenue. Giraffe360 competes by shipping its own 360-degree camera hardware to estate agency clients on monthly plans. Pan 3Sixty anchors its model in hospitality specialization, controlling premium venue visualization contracts across London and Edinburgh.
A virtual tour constitutes an interactive digital reconstruction of physical space, typically assembled from 360-degree image spheres or LiDAR point clouds with six degrees of freedom navigation, enabling remote spatial exploration through web browsers or immersive displays. The technology serves commercial purposes spanning property marketing, venue pre-booking assessment, and educational site familiarization. Real estate applications dominate current deployment volumes, while hospitality and tourism segments show the steepest adoption curves as booking platforms mandate immersive previews. Photogrammetry-based delivery commands premium pricing due to mesh accuracy requirements, whereas WebGL streaming solutions capture volume through browser-native accessibility without headset dependency.
The UK Information Commissioner's Office enforces GDPR-aligned consent protocols for facial capture in 3D scans, while the Advertising Standards Authority scrutinizes property representation accuracy in virtual tour depictions. Trading Standards coordinates with the Competition and Markets Authority to prevent misleading spatial measurements in commercial listings. Stakeholders must monitor evolving digital asset classification debates at HM Revenue and Customs, as virtual tour archives may attract property tax reassessment scrutiny under intangible asset frameworks.
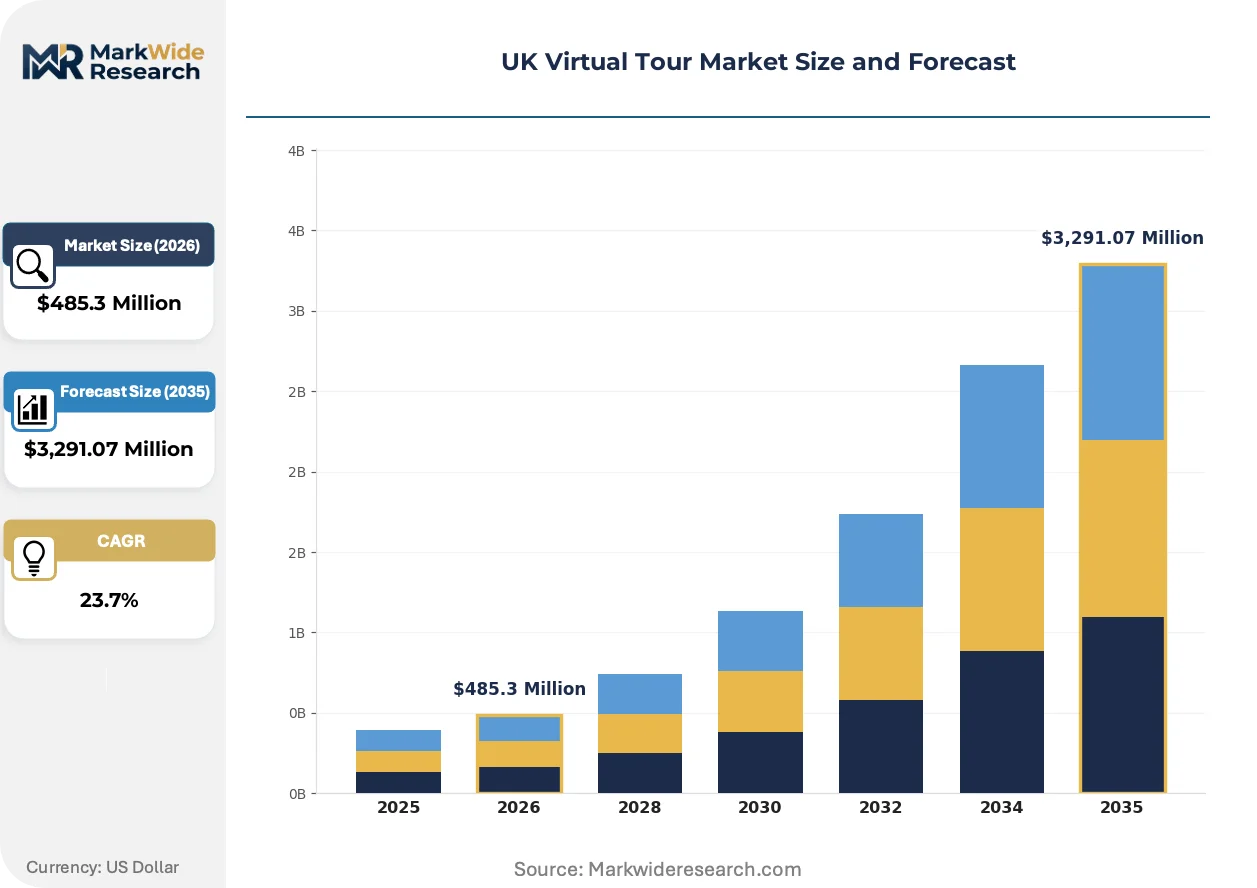
Market Dynamics
Cloud rendering pipelines are collapsing the cost barrier between professional photogrammetry studios and self-service estate agents, redistributing competitive advantage toward platform operators who control distribution rather than hardware ownership.
Growth Catalysts
- GDPR-aligned biometric consent frameworks:The UK Information Commissioner's Office guidance creates compliance clarity that accelerates 3D scanning deployment in residential property marketing.
- Photogrammetry commoditization:WebGL streaming solutions eliminate headset dependency, expanding addressable audiences beyond early adopters to mainstream property browsers.
- Urban corridor concentration:Estate platforms serving London and Manchester now mandate virtual tours as standard listing features, normalizing buyer expectations across England's primary housing markets.
Market Restraints
- Hardware subscription lock-in:Proprietary camera-to-cloud workflows tether agencies to recurring equipment fees that resist margin compression.
- Biometric capture liability:GDPR enforcement on facial data in 3D scans exposes vendors to consent-protocol litigation and operational disruption.
- Photogrammetry cost premium:Mesh accuracy requirements for commercial venue contracts sustain elevated pricing that limits volume penetration.
Strategic Opportunities
- Hospitality specialization:Premium venue visualization contracts across Edinburgh and London remain undercontested outside incumbent operators.
- Advertising Standards Authority scrutiny:Emerging property representation accuracy mandates create first-mover advantage for platforms with verified measurement protocols.
- HM Revenue and Customs asset classification:Virtual tour archive taxation debates position compliant vendors for intangible asset framework alignment.
Industry Challenges
- Spatial measurement certification:Trading Standards coordination with the Competition and Markets Authority demands rigorous dimensional verification that strains quality assurance pipelines.
- LiDAR-to-browser workflow integration:Six-degrees-of-freedom navigation requires specialized engineering talent scarce outside immersive technology hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Virtual Tour Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $3,291.07 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Real Estate, Hospitality, Education, Tourism, Event Planning Technology: 360-Degree Cameras, VR Headsets, Drone Imaging, WebGL, Photogrammetry End User: Residential Buyers, Travel Agencies, Educational Institutions, Venue Managers Distribution Channel: Direct Sales, Online Platforms, Mobile Applications, Real Estate Portals, Marketing Agencies |
| Companies Covered | Giraffe360, Pan 3Sixty, Matterport, Metareal Stage, 360 Virtual Tours, Virtual Tour Company, 360imagery, Nikreations, EyeSpy360, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Virtual Tour Market Trends and Innovations
Browser-native accessibility is severing the link between immersive property visualization and specialized hardware ownership, forcing business model reinvention across capture, processing, and delivery layers.
LiDAR point cloud reconstruction is displacing photogrammetry as the dominant capture methodology for commercial venue contracts. Hospitality operators in Edinburgh and London now specify sub-centimeter mesh accuracy that only structured light scanning delivers. The technology is displacing volume-oriented 360-degree image spheres from premium-tier service offerings.
The UK Advertising Standards Authority now scrutinizes spatial measurement accuracy in virtual tour depictions, extending consumer protection frameworks into digital property representation. Estate agencies must archive capture metadata to defend against misrepresentation claims. London-based residential platforms face the steepest compliance velocity as transaction volumes attract regulatory attention.
Buyer behavior now favors pre-viewing spatial exploration that eliminates physical site visits from initial property shortlisting. Estate agents in Manchester and Birmingham report compressed viewing-to-offer cycles as immersive previews filter unmotivated prospects. This pattern concentrates in England's urban corridors where inventory velocity determines agency profitability.
UK Virtual Tour Market Segmentation
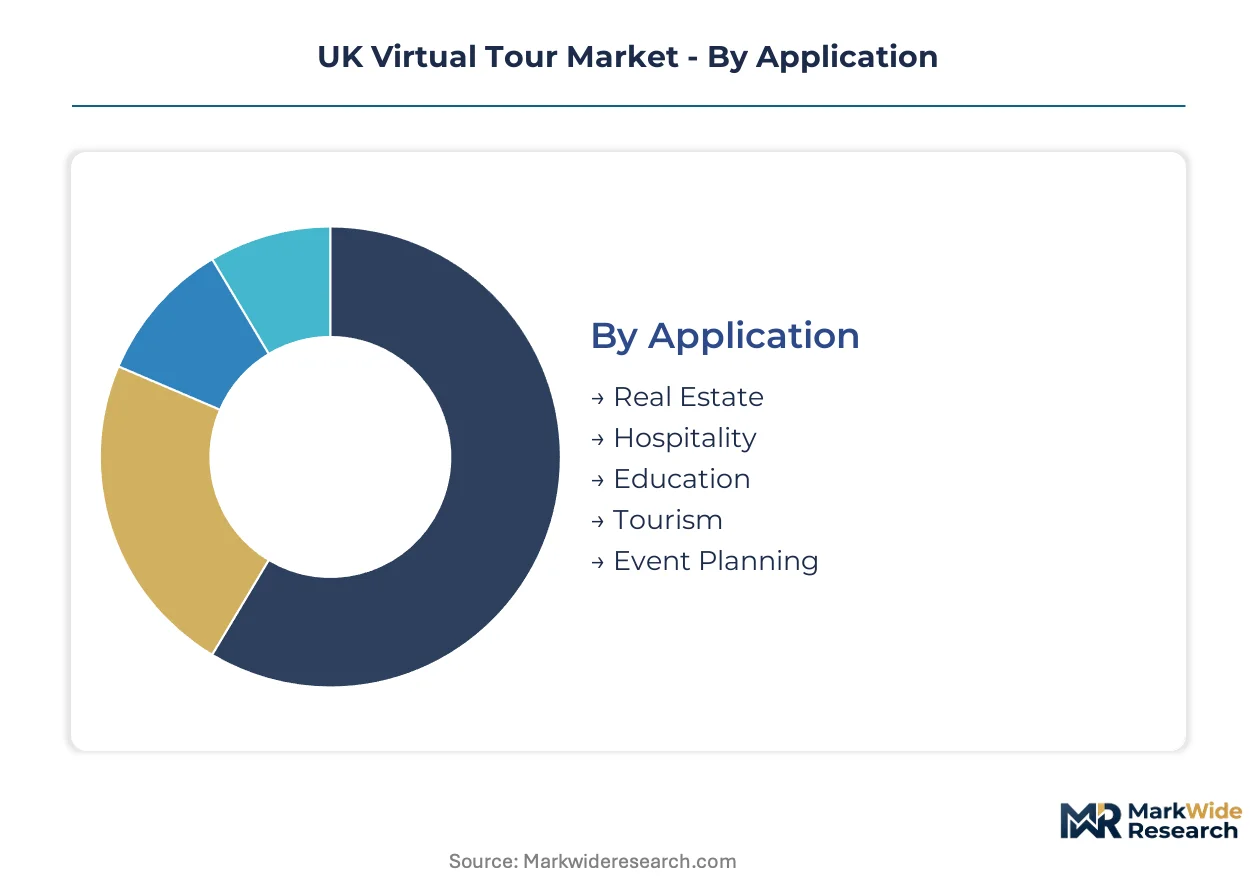
Segmentation reveals how capture technology costs and platform access routes determine vendor profitability across England's property marketing corridors. Application concentration in residential real estate concentrates margin pools where listing volume and compliance velocity intersect.
Application:
Premium pricing pools concentrate where mesh accuracy requirements meet contractual liability exposure.
- Real Estate:LiDAR point cloud reconstruction dominates London and Manchester residential listings where six-degrees-of-freedom navigation filters unmotivated prospects. Estate agents mandate immersive previews as standard features, compressing viewing-to-offer cycles.
- Hospitality:Sub-centimeter accuracy specifications from Edinburgh and London venue operators sustain photogrammetry premiums. Structured light scanning displaces 360-degree spheres from premium-tier contracts as booking platforms mandate immersive previews.
- Education:Campus familiarization drives adoption across English universities with international recruitment pipelines.
- Tourism:Pre-booking assessment tools gain traction among regional destination marketing organizations.
- Event Planning:Venue visualization contracts concentrate in corporate conference segments.
The dominant share belongs to Real Estate, while Hospitality is closing the gap fastest.
Technology:
Hardware ownership requirements fragment competitive positioning between capital-intensive capture and browser-native delivery.
- 360-Degree Cameras:Cloud rendering pipelines collapse cost barriers for self-service estate agents. Shipped hardware on monthly plans locks agencies into recurring subscription revenue streams.
- Photogrammetry:Mesh accuracy requirements for commercial venue contracts sustain elevated pricing that limits volume penetration. WebGL streaming solutions eliminate headset dependency for mainstream property browsers.
- WebGL:Browser-native accessibility severs hardware ownership requirements from immersive visualization.
- VR Headsets:Early adopter dependency constrains addressable audience expansion.
- Drone Imaging:Exterior capture supplements interior reconstruction for rural property portfolios.
Photogrammetry commands the highest unit margins, though WebGL is expanding most quickly through accessibility gains.
End User:
Procurement authority determines whether sales cycles route through platform subscriptions or enterprise contracts.
- Residential Buyers:Pre-viewing spatial exploration eliminates physical site visits from initial property shortlisting. Buyer behavior favors immersive previews that filter unmotivated prospects across Birmingham and Manchester corridors.
- Venue Managers:Premium hospitality contracts in Edinburgh and London specify capture metadata archiving for Advertising Standards Authority compliance.
- Travel Agencies:Booking platform mandates accelerate immersive preview adoption.
- Educational Institutions:International recruitment budgets fund campus visualization investments.
Residential Buyers generate the largest volume base, with Venue Managers driving the steepest expansion trajectory.
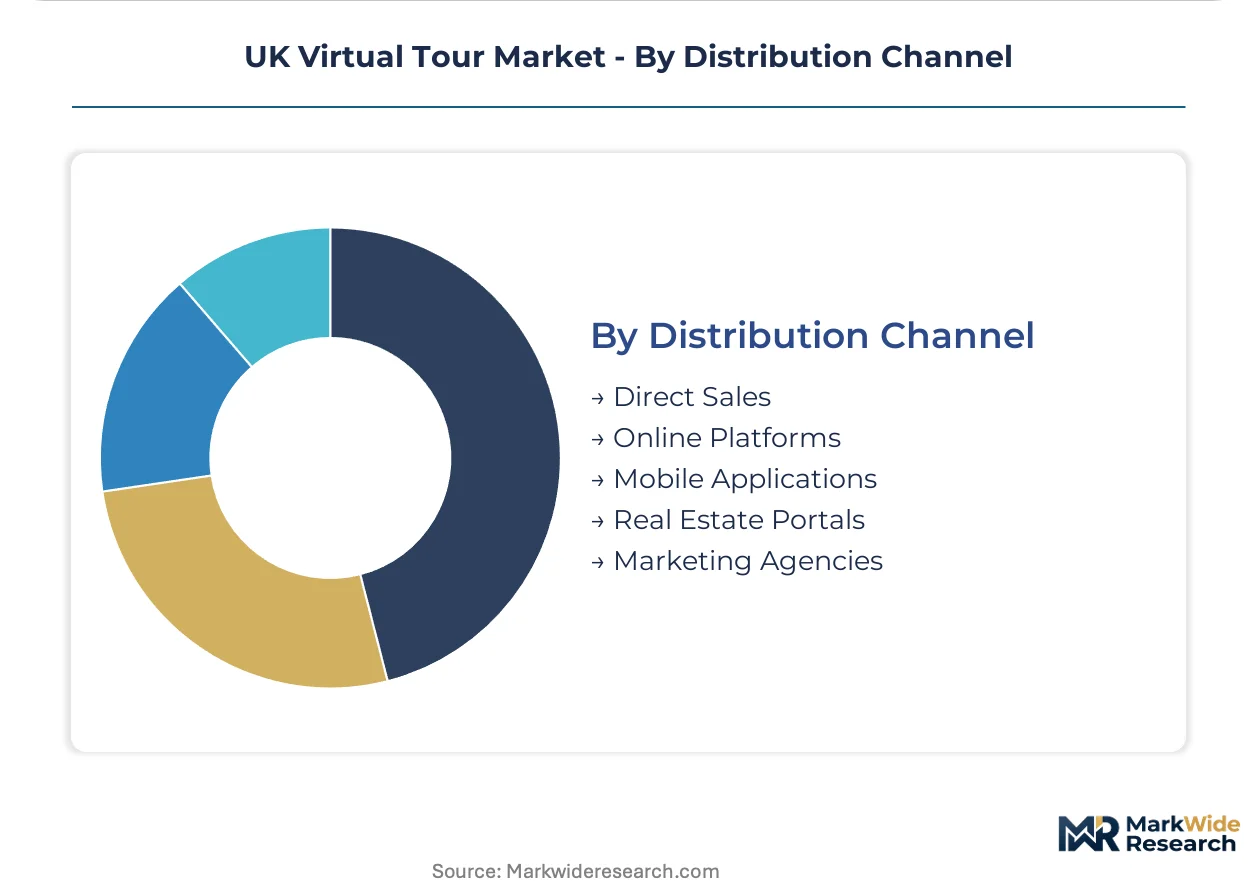
Distribution Channel:
Channel control determines whether vendors capture recurring revenue or one-time project fees.
- Real Estate Portals:Platform operators controlling distribution extract margin from agencies through mandatory listing feature requirements. London-based residential platforms face the steepest compliance velocity as transaction volumes attract regulatory attention.
- Direct Sales:Enterprise hospitality contracts in Edinburgh and London bypass intermediary platform fees.
- Online Platforms:Self-service accessibility redistributes advantage toward software-only providers.
- Mobile Applications:Browser-native streaming reaches property browsers without app installation friction.
- Marketing Agencies:White-label service provision captures mid-tier venue visualization demand.
Real Estate Portals hold the dominant position, while Direct Sales is gaining share fastest among premium contract segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply across UK sub-regions, with London agencies accepting premium capture costs while Northern England operators prioritize subscription affordability. This demand-elasticity gradient shapes vendor go-to-market strategies and platform feature prioritization.
London and Southeast
Estate agencies in Greater London mandate LiDAR-grade virtual tours as standard listing features, driven by compressed transaction cycles and international buyer expectations. The Advertising Standards Authority scrutinizes spatial measurement accuracy most intensively here, forcing platforms to archive capture metadata defensively. Canary Wharf and Kensington residential clusters generate the highest per-listing technology spend nationally.
Midlands
Birmingham and Nottingham property platforms favor browser-native WebGL solutions that eliminate hardware ownership barriers for mid-tier agencies. Trading Standards coordination with the Competition and Markets Authority enforces dimensional verification protocols that strain quality assurance pipelines. The region's industrial heritage sites drive hospitality visualization demand alongside residential applications.
North England
Manchester anchors the steepest adoption curve outside London, with estate agents reporting compressed viewing-to-offer cycles from immersive previews. GDPR-aligned biometric consent frameworks from the UK Information Commissioner's Office create compliance clarity that accelerates 3D scanning deployment. Liverpool and Leeds follow as secondary concentration nodes for platform subscription growth.
Scotland
Edinburgh's premium hospitality sector specifies sub-centimeter mesh accuracy for venue visualization contracts, sustaining photogrammetry pricing premiums. The Scottish Information Commissioner enforces data protection protocols parallel to UK-wide GDPR frameworks. Glasgow's university sector drives campus familiarization adoption for international student recruitment pipelines.
Wales and Northern Ireland
Rural property portfolios in Cardiff and Belfast corridors supplement interior reconstruction with drone imaging for exterior capture, expanding addressable use cases. Lower listing volumes concentrate procurement authority with regional marketing agencies rather than platform-direct subscriptions. Devolved regulatory frameworks maintain alignment with UK-wide advertising and data protection standards.
UK Virtual Tour Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK virtual tour market. The vendor base clusters around three strategic positions: hardware-owning platform operators extracting recurring subscription revenue, software-only providers capitalizing on cloud-rendered accessibility, and hospitality specialists commanding premium venue contracts through accuracy certification. Consolidation pressure concentrates among mid-tier capture service providers as browser-native delivery commoditizes photogrammetry pipelines. Dominant competitive moves include vertical integration into proprietary camera-to-cloud workflows and geographic specialization around England's urban corridors.
Among hardware-integrated platform operators, Matterport and Giraffe360 exemplify the subscription-lock archetype through proprietary camera-to-cloud workflows. Pan 3Sixty occupies a specialist position anchoring premium hospitality visualization contracts. These three company patterns illustrate how vendor profitability depends on controlling distribution rather than capture technology ownership.
| Leading Market Players |
|---|
| Giraffe360 |
| Pan 3Sixty |
| Matterport |
| Metareal Stage |
| 360 Virtual Tours |
| Virtual Tour Company |
| 360imagery |
| Nikreations |
| EyeSpy360 |
| Others |
Pricing and Supply Chain Analysis
Three-to-five-day hardware fulfillment windows for 360-degree camera kits concentrate procurement power with platform operators who bundle capture devices into recurring subscriptions, tilting pricing leverage toward vendors controlling distribution rather than manufacturing.
Pricing Analysis
Extended service contracts and capture metadata archiving drive lifetime value beyond initial hardware shipments. The market operates on a SaaS-tiered subscription structure where monthly camera rental fees anchor recurring revenue. Price differentiation rests on mesh accuracy certification and GDPR compliance bundling. Cost compression in self-service tiers intensifies as cloud rendering eliminates proprietary hardware dependencies. Mid-tier estate agencies in Northern England exhibit the steepest price sensitivity, while London hospitality operators absorb photogrammetry premiums.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes delays LiDAR sensor shipments from Chinese and Taiwanese component manufacturers. The hardware layer draws from Shenzhen assembly clusters and German optics specialists. Structured light scanning modules and CMOS image sensors constitute critical input dependencies. Single-source vulnerability concentrates in high-precision lens sourcing. Distribution runs through platform-direct fulfillment to estate agency networks, bypassing traditional electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
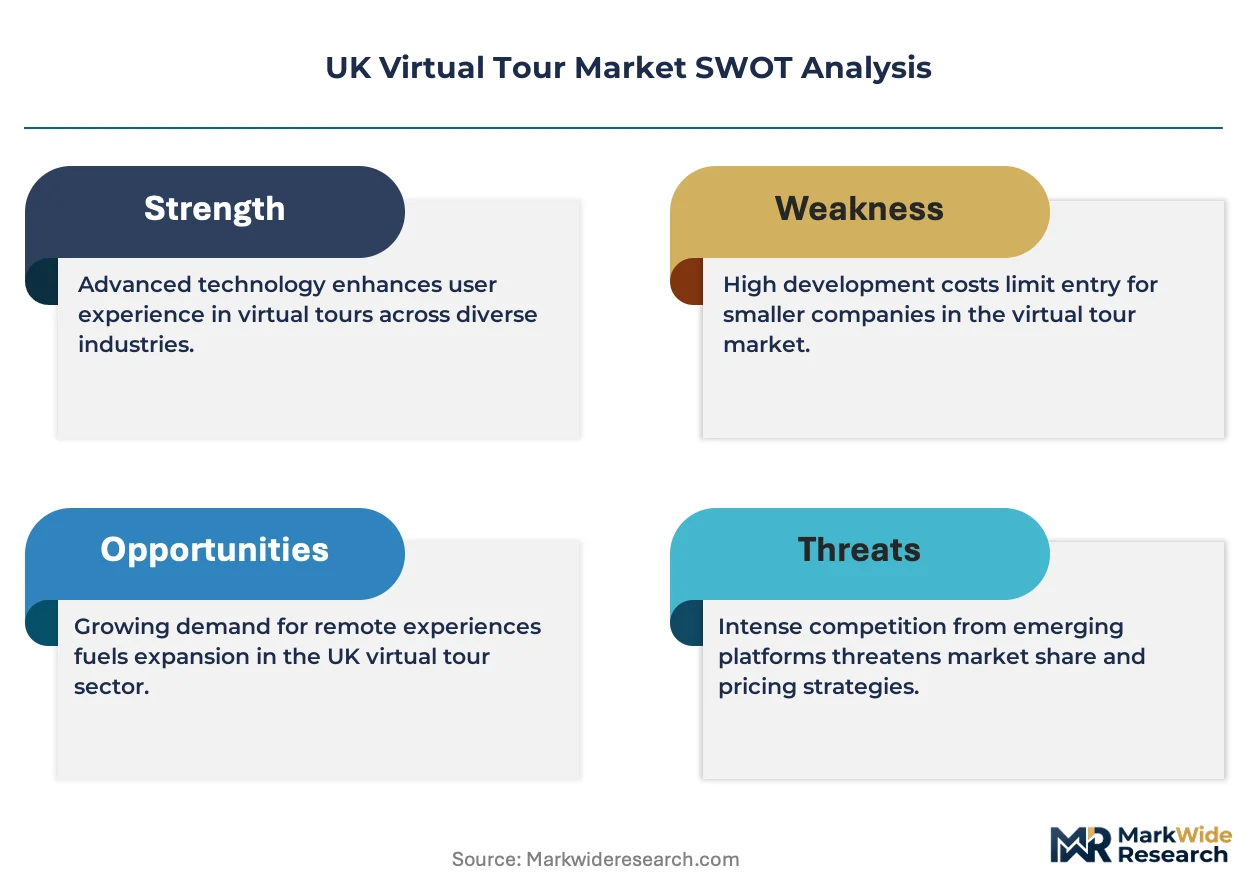
Browser-native WebGL streaming disrupts hardware-centric business models, with GDPR enforcement on biometric capture creating compliance differentiation that separates viable platforms from stranded technology investments.
For Market Incumbents: Consolidate around proprietary camera-to-cloud workflows that lock estate agencies into recurring subscription revenue. Acquire photogrammetry studios in Edinburgh and London to defend premium hospitality contracts against software-only entrants. Channel control remains the critical lever as browser-native delivery commoditizes capture technology.
For New Entrants and Emerging Players: Mid-tier venue visualization in Birmingham and Nottingham presents the most penetrable white space, where incumbent hospitality specialists maintain limited presence. Target self-service estate agents with WebGL-native platforms that eliminate hardware ownership barriers. A freemium tier with GDPR-aligned consent tooling accelerates initial agency adoption.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because recurring subscription revenue from camera-to-cloud workflows generates predictable cash flows resistant to commoditization. Acquisition targets should display vertical integration into proprietary hardware with established agency lock-in. Monitor Advertising Standards Authority enforcement velocity as the signal indicating which platforms possess defensible compliance infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates camera-to-cloud workflows with estate agency CRM systems, embedding recurring subscription revenue. |
| Acquisition of Specialist Firm | Captures Edinburgh and London photogrammetry studios with sub-centimeter accuracy certification for hospitality contracts. |
| Product Launch | Introduces GDPR-aligned biometric consent tooling that differentiates platforms under UK Information Commissioner's Office scrutiny. |
| Strategic Partnership | Aligns with Manchester and Birmingham real estate portals to mandate virtual tours as standard listing features. |
| Geographic Expansion | Estimates addressable agency volume across Northern England corridors where immersive preview adoption accelerates fastest. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with virtual tour platform executives, estate agency technology directors, and UK Information Commissioner's Office compliance officers; and secondary validation against Companies House filings, property portal listing requirement disclosures, and Advertising Standards Authority enforcement notices. Bottom-up triangulation across agency subscription volumes and top-down reconciliation against platform revenue disclosures anchored market sizing.
Across the analysis window, the forecasting framework modeled deployment by technology layer, application segment, and urban corridor concentration. CAGRs derived from segment-level adoption curves weighted by compliance velocity and platform mandate expansion. WebGL streaming penetration rates and LiDAR hardware shipment volumes supplied industry-specific forecast inputs.
Forecasts assume regulatory continuity in UK GDPR enforcement and Advertising Standards Authority scrutiny regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market