
 IT Asset Management Solutions (ITAM) Market | 2026-2036
IT Asset Management Solutions (ITAM) Market Size, Share, and Industry Trends Forecast 2026-2036
IT Asset Management Solutions (ITAM) Market Insights
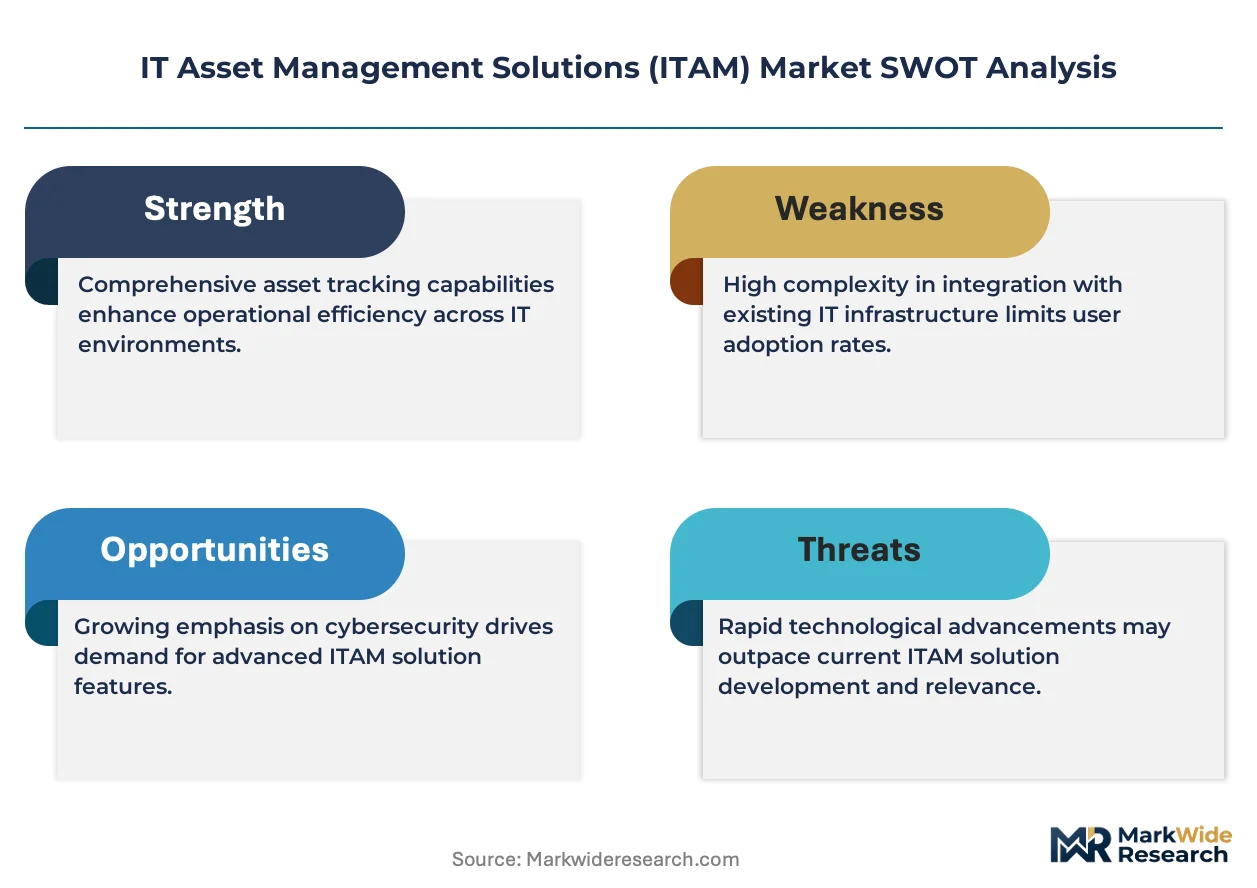
Modular bundling of ITAM capabilities with adjacent IT service management platforms is shifting procurement patterns across enterprise buyers. ServiceNow leverages its workflow engine to embed asset discovery within broader digital operations suites. BMC Software anchors its competitive stance through deep mainframe and distributed infrastructure specialization. Flexera differentiates via software license optimization layered into hardware asset tracking.
IT Asset Management Solutions encompass software systems, hardware inventories, cloud service catalogs, and consulting engagements that track, monitor, and optimize technology assets across their full lifecycle from procurement through disposal. These platforms integrate discovery agents, configuration management databases, and financial depreciation engines to enforce compliance, reduce audit exposure, and eliminate redundant software spend. Cloud-based and SaaS deployment models are capturing the fastest expansion as organizations retire on-premises discovery infrastructure. Hardware asset tracking remains the most mature revenue pool with established refresh cycles, while consulting services around implementation and integration command premium margins due to talent scarcity.
US SEC cybersecurity disclosure mandates and HIPAA data governance requirements are compelling healthcare and financial enterprises to maintain auditable asset inventories with real-time vulnerability mapping. European operators face overlapping pressure from GDPR data location tracking and the EU AI Act's hardware provenance documentation standards. Stakeholders must weigh cloud-native platform consolidation against hybrid deployment flexibility as regulatory scope broadens beyond traditional software compliance into embodied carbon and circular economy reporting.
Market Dynamics
Cloud migration is compressing deployment timelines for ITAM platforms as enterprises retire on-premises discovery infrastructure in favor of agentless SaaS architectures. This structural shift is redrawing competitive boundaries between pure-play asset tracking vendors and workflow-integrated platform providers.
Growth Catalysts
- SEC Cybersecurity Disclosure Mandates:US financial services firms must maintain real-time asset inventories with vulnerability mapping, forcing upgrades from spreadsheet-based tracking to automated discovery platforms.
- Healthcare Data Governance:HIPAA audit requirements are compelling hospital systems to deploy configuration management databases that map every endpoint handling protected health information.
- Agentless Discovery Technology:API-based asset scanning without endpoint installation is removing deployment friction in highly regulated environments where software agents face security review delays.
Market Restraints
- Implementation Cost Concentration:Professional services for CMDB integration consume 40-60% of first-year project budgets, limiting adoption among mid-market buyers without dedicated ITAM staff.
- Legacy System Entrenchment:Mainframe and distributed infrastructure running COBOL-based asset registers creates data synchronization friction with modern cloud-native discovery tools.
- Specialized Talent Scarcity:Shortage of consultants certified in both ITIL frameworks and cloud architecture is extending deployment timelines and inflating day rates.
Strategic Opportunities
- EU AI Act Hardware Provenance:Documentation requirements for training infrastructure create new compliance revenue streams for asset lifecycle tracking vendors serving European AI developers.
- India Enterprise Digitization:PLI scheme beneficiaries in electronics manufacturing are building greenfield ITAM capabilities without legacy technical debt.
- Carbon Accounting Convergence:Integration of embodied carbon tracking with financial depreciation engines addresses emerging CSRD reporting obligations for European industrial operators.
Industry Challenges
- Multi-Cloud Visibility Gaps:Shadow IT proliferation across AWS, Azure, and GCP environments outpaces discovery tool coverage, creating persistent blind spots in asset inventories.
- Software License Optimization Complexity:Oracle and Microsoft audit defense requires specialized expertise that most internal procurement teams lack, forcing reliance on external consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Asset Management Solutions (ITAM) Market |
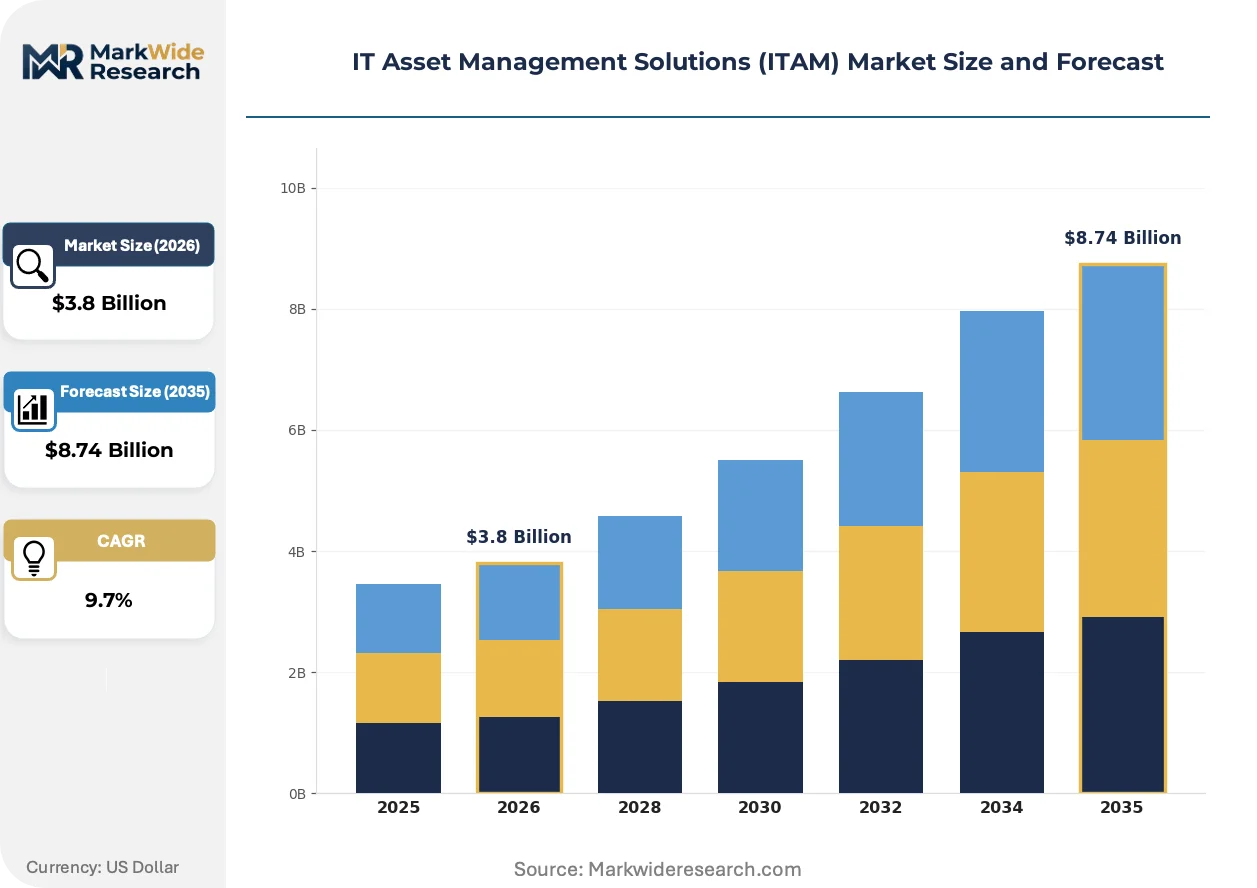
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Cloud Services, Consulting Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Departments, Enterprises, Managed Service Providers, Educational Institutions Service Type: Implementation, Maintenance, Support, Training |
| Companies Covered | ServiceNow, IBM, BMC Software, Flexera, Snow Software, Oracle, Ivanti, Hewlett Packard Enterprise, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Asset Management Solutions (ITAM) Market Trends and Innovations
Artificial intelligence is embedding predictive capabilities into ITAM workflows, shifting platforms from reactive inventory systems toward proactive lifecycle optimization engines. This transformation is compressing refresh cycles and redefining vendor value propositions.
Agentless discovery is consolidating market share among cloud-native enterprises by eliminating endpoint installation requirements. Financial services and healthcare buyers with strict security review processes are adopting API-based scanning at accelerated rates. This architecture is consolidating previously fragmented point solutions into unified SaaS platforms with embedded vulnerability correlation.
GDPR data location tracking mandates are forcing European operators to map physical server locations against processing activities. The regulation is driving demand for geofenced asset tagging and cross-border data flow documentation. German critical infrastructure operators under BSI IT-Grundschutz framework are deploying specialized hardware lifecycle modules to satisfy provenance requirements.
Subscription-based pricing models are displacing perpetual license structures across enterprise procurement. Chief information officers are negotiating consumption-aligned contracts that scale with cloud asset growth rather than fixed device counts. This shift is most visible in North American financial services, where operating expense treatment aligns with SEC disclosure cost management priorities.
IT Asset Management Solutions (ITAM) Market Segmentation
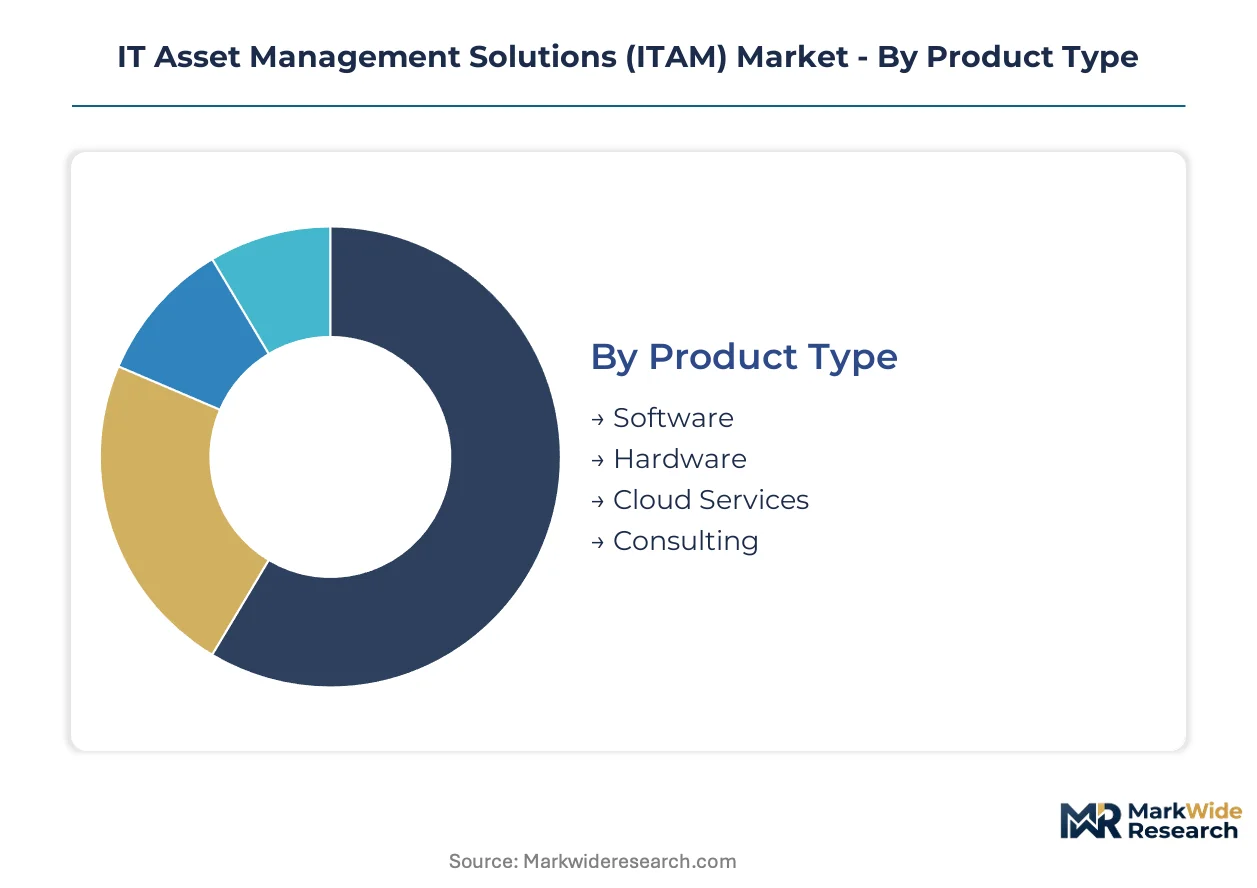
ITAM market segmentation reveals divergent growth trajectories across deployment architectures and buyer sophistication tiers. Procurement patterns split sharply between enterprises consolidating platforms and mid-market buyers prioritizing implementation speed over functional depth.
Product Type:
Software dominates revenue volume while consulting commands premium pricing through talent scarcity. Hardware tracking retains steady replacement-cycle demand.
- Software:Discovery agents, configuration management databases, and license optimization engines form the core technology stack. Financial services firms in the United States deploy these platforms to satisfy SEC cybersecurity disclosure mandates with real-time vulnerability mapping.
- Hardware:Physical asset tracking through RFID tags, barcode systems, and IoT sensors manages server lifecycle and endpoint inventory. German critical infrastructure operators under BSI IT-Grundschutz framework drive specialized demand for provenance documentation.
- Cloud Services:Native asset catalogs for AWS, Azure, and GCP environments.
- Consulting:Implementation and integration services around CMDB deployment.
Today's leader: Software. Tomorrow's challenger: Cloud Services.
Deployment Model:
Cloud-native architectures are displacing on-premises infrastructure as enterprises prioritize subscription economics over capital expenditure. Hybrid deployments persist where regulatory data residency conflicts with cloud migration timelines.
- Cloud-Based:Multi-tenant platforms with API-first discovery eliminate endpoint agent installation. Healthcare systems facing HIPAA audit requirements adopt these architectures to accelerate deployment without security review bottlenecks.
- SaaS:Fully managed subscription offerings with embedded workflow integration. North American financial services buyers favor consumption-aligned contracts that scale with cloud asset growth rather than fixed device counts.
- On-Premises:Self-hosted discovery infrastructure in air-gapped environments.
- Hybrid:Split deployments retaining sensitive asset data on-premises while leveraging cloud analytics.
Cloud-Based and SaaS together are gaining share fastest as agentless discovery removes deployment friction.
End User:
Enterprise buyers consolidate adjacent IT service management functions while managed service providers build multi-tenant delivery capabilities. Educational institutions represent an underpenetrated tier with distinct procurement rhythms.
- Enterprises:Large organizations integrating ITAM with service desks and financial systems. These buyers negotiate enterprise-wide platform contracts spanning hardware lifecycle, software compliance, and cloud cost optimization.
- Managed Service Providers:Third-party operators delivering ITAM as a managed service to client portfolios. MSPs require multi-tenant architectures and standardized APIs to maintain margins across diverse client infrastructure.
- IT Departments:Internal technology organizations with departmental procurement authority.
- Educational Institutions:Universities and school systems with seasonal refresh cycles and grant-funded implementations.
Enterprises anchor current spending. Managed Service Providers are climbing the fastest as outsourcing accelerates.
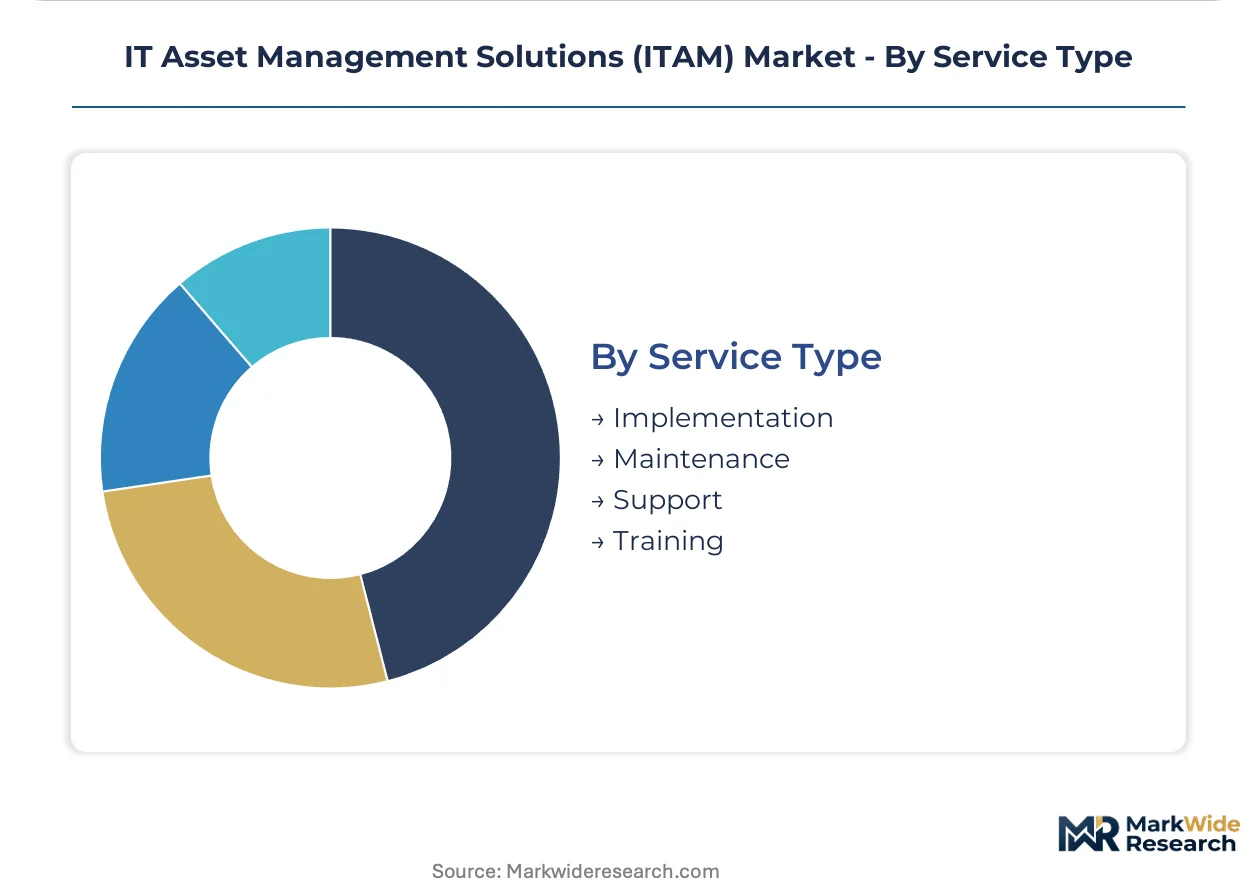
Service Type:
Implementation services consume disproportionate first-year budgets while maintenance contracts provide recurring revenue stability. Training margins compress as certification programs proliferate.
- Implementation:Professional services for CMDB integration, data migration, and workflow configuration. These engagements consume 40-60% of first-year project budgets and require ITIL-certified consultants with cloud architecture expertise.
- Maintenance:Ongoing platform updates, patch management, and technical health monitoring. Healthcare and financial services buyers in the United States treat these contracts as essential for maintaining audit-ready asset inventories.
- Support:Help desk and break-fix services for production incidents.
- Training:Certification programs and knowledge transfer for internal ITAM staff.
Implementation commands premium day rates today. Maintenance contracts are expanding most quickly as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IT asset management solutions trace their enterprise-scale origins to United States technology corridors where early software vendors built configuration management databases for federal contractors and financial institutions during the 1990s digital infrastructure build-out.
United States
Financial services firms in New York and Chicago deploy ITAM platforms to satisfy SEC cybersecurity disclosure mandates requiring real-time asset inventories with vulnerability mapping. HIPAA enforcement by federal regulators compels hospital systems in Boston and Houston to maintain auditable configuration management databases. The San Francisco Bay Area hosts the largest concentration of cloud-native ITAM vendors developing agentless discovery architectures.
Germany
Critical infrastructure operators in Frankfurt and Munich procure hardware lifecycle modules to comply with BSI IT-Grundschutz framework provenance requirements. The EU AI Act's documentation standards for training infrastructure create compliance revenue streams for asset tracking vendors serving Stuttgart's automotive AI developers. Industrial manufacturers in the Ruhr region integrate embodied carbon tracking with depreciation engines to meet CSRD reporting obligations.
United Kingdom
London-based financial institutions negotiate consumption-aligned ITAM contracts that scale with cloud asset growth rather than fixed device counts. GDPR data location tracking mandates force Manchester and Birmingham data center operators to map physical server locations against processing activities. The UK's national cybersecurity center pressures critical infrastructure owners to retire spreadsheet-based asset tracking.
India
PLI scheme beneficiaries in Bengaluru and Hyderabad electronics manufacturing build greenfield ITAM capabilities without legacy technical debt. RBI guidelines for financial sector cyber resilience drive adoption of automated discovery platforms among Mumbai banking institutions. The country's national IT regulator pushes data localization requirements that complicate cloud-based asset management deployments.
Japan
Tokyo-headquartered conglomerates consolidate ITAM with adjacent IT service management functions to reduce vendor sprawl. METI guidance on supply chain cybersecurity prompts Osaka manufacturers to deploy hardware provenance tracking for industrial control systems. Fukuoka's emerging fintech cluster represents an underpenetrated tier with distinct seasonal procurement rhythms tied to fiscal year cycles.
IT Asset Management Solutions (ITAM) Market Competitive Landscape
The competitive structure tilts toward platform-integrated providers over pure-play specialists. Workflow-embedded vendors capture enterprise renewals by anchoring asset discovery within broader digital operations suites. Three archetypes dominate: IT service management platforms with native asset modules, standalone license optimization specialists, and infrastructure hardware vendors bundling discovery tools. Consolidation through strategic partnerships and API-first ecosystem expansion represents the dominant competitive vector.
Among United States-based platform providers, ServiceNow and BMC Software exemplify the workflow-integrated archetype, while Flexera occupies a position within the license optimization specialist tier. These three companies anchor the competitive landscape by representing divergent strategic postures: ServiceNow leverages its workflow engine, BMC Software maintains deep infrastructure specialization, and Flexera layers software license optimization into hardware tracking. Each archetype targets distinct procurement patterns among enterprise buyers, managed service providers, and compliance-driven regulated industries.
| Leading Market Players |
|---|
| ServiceNow |
| IBM |
| BMC Software |
| Flexera |
| Snow Software |
| Oracle |
| Ivanti |
| Hewlett Packard Enterprise |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Agentless discovery architectures are compressing deployment timelines while simultaneously redrawing cost economics and vendor consolidation patterns across enterprise procurement. API-first SaaS platforms eliminate endpoint installation overhead, concentrating pricing power among workflow-integrated providers while fragmenting pure-play specialists into acquisition targets.
Pricing Analysis
Subscription-based consumption models with consumption-aligned scaling dominate enterprise procurement, separating premium workflow-integrated suites from mid-tier standalone discovery tools and economy-tier open-source alternatives. Price differentiation hinges on ITIL certification depth and embedded vulnerability correlation capabilities. Cost compression in mid-market tiers is intensifying because hyperscaler-native alternatives commoditize basic asset scanning. Healthcare systems facing HIPAA audit requirements exhibit highest price sensitivity due to implementation budget constraints, while financial services firms under SEC mandates show lowest sensitivity given compliance failure costs.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating concentrates qualified implementation partners in the United States, Germany, and India, creating tiered access to enterprise deployment pipelines. Software development draws from cloud infrastructure APIs, configuration management database engines, and embedded AI prediction modules. Single-source vulnerability in hyperscaler API dependencies exposes discovery platforms to service discontinuation risks. Distribution runs through direct enterprise sales teams and managed service provider channels with multi-tenant delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAM market expansion represents a geographic-arbitrage play between German BSI IT-Grundschutz compliance premiums and Indian PLI scheme greenfield cost advantages. Regulatory divergence between EU hardware provenance mandates and Asia-Pacific digitization incentives creates divergent return profiles.
For Market Incumbents: Deploy workflow engine deepening to anchor asset discovery within broader digital operations suites. Consolidate adjacent IT service management functions to defend against pure-play license optimization specialists. Counter cloud-native entrant threats by accelerating mainframe-to-cloud data synchronization capabilities. Acquire agentless discovery startups to neutralize API-first competitive pressure. For New Entrants and Emerging Players: Managed service providers represent the fastest channel to enterprise access without direct procurement friction. Target Indian electronics manufacturing PLI beneficiaries building first-generation ITAM capabilities without legacy technical debt. Penetrate European AI developer segments facing EU AI Act hardware documentation requirements. Lead with carbon accounting convergence messaging to differentiate against established compliance-focused incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone license optimization specialists lacking workflow integration depth. Five-to-ten year viability favors platform-embedded vendors with recurring revenue bases over project-dependent implementation boutiques. Acquisition target archetype: agentless discovery firms with healthcare or financial services reference bases. Watch SEC enforcement intensity around cybersecurity disclosure timelines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding asset discovery within ServiceNow or BMC workflow engines captures enterprise renewal cycles. |
| Agentless Discovery Development | API-based scanning without endpoint installation accelerates HIPAA-regulated healthcare deployments. |
| Carbon Accounting Convergence | Integrating embodied carbon tracking addresses CSRD reporting for German industrial operators. |
| Multi-Tenant Architecture Investment | Enables managed service providers to deliver ITAM across diverse client infrastructure profitably. |
| EU AI Act Compliance Module | Hardware provenance documentation captures Stuttgart automotive AI developer compliance budgets. |
Research Methodology
Multiple input streams — primary interviews with IT procurement officers, platform engineers, and channel partners; secondary validation through SEC cybersecurity disclosure filings, HIPAA audit documentation, and hyperscaler capex disclosures; plus customs data on enterprise software imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed ITAM vendor product strategists, managed service provider operations leads, and healthcare technology compliance officers across the United States, Germany, and India. Secondary sources included BSI IT-Grundschutz framework updates, EU AI Act regulatory texts, and RBI cyber resilience guidelines.
Historical spending patterns were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled encompassed deployment architecture, organization size tier, vertical regulatory intensity, integration complexity level, and regional adoption pattern. CAGRs were derived from regression analysis against cloud migration velocity indicators and compliance mandate enforcement timelines. Forecast inputs included SEC disclosure audit frequency projections and EU CSRD reporting obligation phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler API policy changes and ITIL certification program evolution. Model outputs reflect documented assumptions regarding cloud migration timelines and regulatory enforcement intensity. A model refresh is warranted upon material change in SEC cybersecurity disclosure audit frequency or EU AI Act hardware documentation interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Master Data Management Market
Digital Solutions
Europe API Management Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Ad Intelligence Software Market