
 South Africa ICT Market | 2026-2036
South Africa ICT Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa ICT Market Analytics
Enterprise-grade fibre connectivity is redrawing competitive boundaries in South Africa's ICT landscape. Vodacom Group Ltd leverages its extensive mobile money and enterprise network infrastructure to sustain leadership in both consumer and B2B segments. MTN Group Ltd anchors its position through aggressive 5G rollout and data centre investments in key metros. Telkom SA SOC Ltd differentiates via its Openserve fibre wholesale arm and government contract concentration.
Information and communications technology in South Africa encompasses telecommunications infrastructure, data processing systems, and digital service delivery platforms operating across copper, fibre, wireless, and satellite transmission media with latency specifications critical for real-time financial and healthcare applications. The primary purpose spans enabling enterprise digitization, government service delivery, and consumer connectivity across a dual economy with significant rural-urban divides. Cloud Services and Cybersecurity within the Service Type dimension command expanding margin pools as enterprise migration accelerates and ransomware threats intensify against South African targets. Hybrid Cloud deployment configurations are gaining structural prominence as organizations balance data sovereignty requirements against scalability needs, particularly within Financial Institutions and Government Agencies constrained by POPIA and archival regulations.
ICASA governs spectrum allocation and licensing frameworks, while the POPI Act mandates data protection standards that reshape cloud architecture procurement across healthcare and financial verticals. National Treasury's preferential procurement regulations and B-BBEE ICT sector codes further condition market access for foreign technology vendors and local content requirements. Stakeholders must weigh spectrum auction timing, data localisation enforcement thresholds, and evolving cybersecurity certification mandates when calibrating capital allocation across infrastructure and service layers.
Market Dynamics
Spectrum licensing reforms by ICASA and the national broadband policy are compressing infrastructure deployment timelines, forcing incumbents to accelerate fibre and 5G capital commitments ahead of auction clarity.
Growth Catalysts
- Enterprise Cloud Migration:Financial institutions in Johannesburg and Cape Town are expanding hybrid cloud footprints to balance POPIA compliance against scalability requirements.
- ICASA Spectrum Framework:The regulator's accelerated licensing timelines for 5G and mmWave bands are unlocking infrastructure investment across metropolitan corridors.
- Ransomware Intensification:Cyberattack frequency against healthcare and banking targets is elevating managed security services from discretionary to mandatory procurement categories.
Market Restraints
- Input Cost Volatility:Fibre optic cable and semiconductor component prices fluctuate with rand-dollar exchange rate instability, compressing margin visibility for network operators.
- Supply Concentration:Submarine cable landing stations and international bandwidth terminate through a limited set of coastal facilities, creating single-point vulnerability for inland connectivity.
- Regulatory Friction:B-BBEE ICT sector codes and preferential procurement thresholds from National Treasury extend vendor qualification timelines for foreign technology providers.
Strategic Opportunities
- Eastern Cape Underpenetration:Fibre density in Gqeberha and rural Eastern Cape municipalities lags Gauteng and Western Cape benchmarks, creating greenfield deployment zones.
- Edge Computing Convergence:Integration of 5G radio access networks with distributed data centres enables sub-10 millisecond latency for autonomous mining and port logistics applications.
- SMME Digital Enablement:Government agency mandates for small business digitization are opening channel partnerships for bundled connectivity and cloud productivity suites.
Industry Challenges
- Specialized Talent Scarcity:Cloud architecture and zero-trust cybersecurity skills command premium compensation in Johannesburg and Cape Town, constraining service delivery scaling.
- Legacy System Integration:Mainframe-dependent financial institutions face multi-year timelines to containerize core banking platforms for hybrid cloud deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa ICT Market |
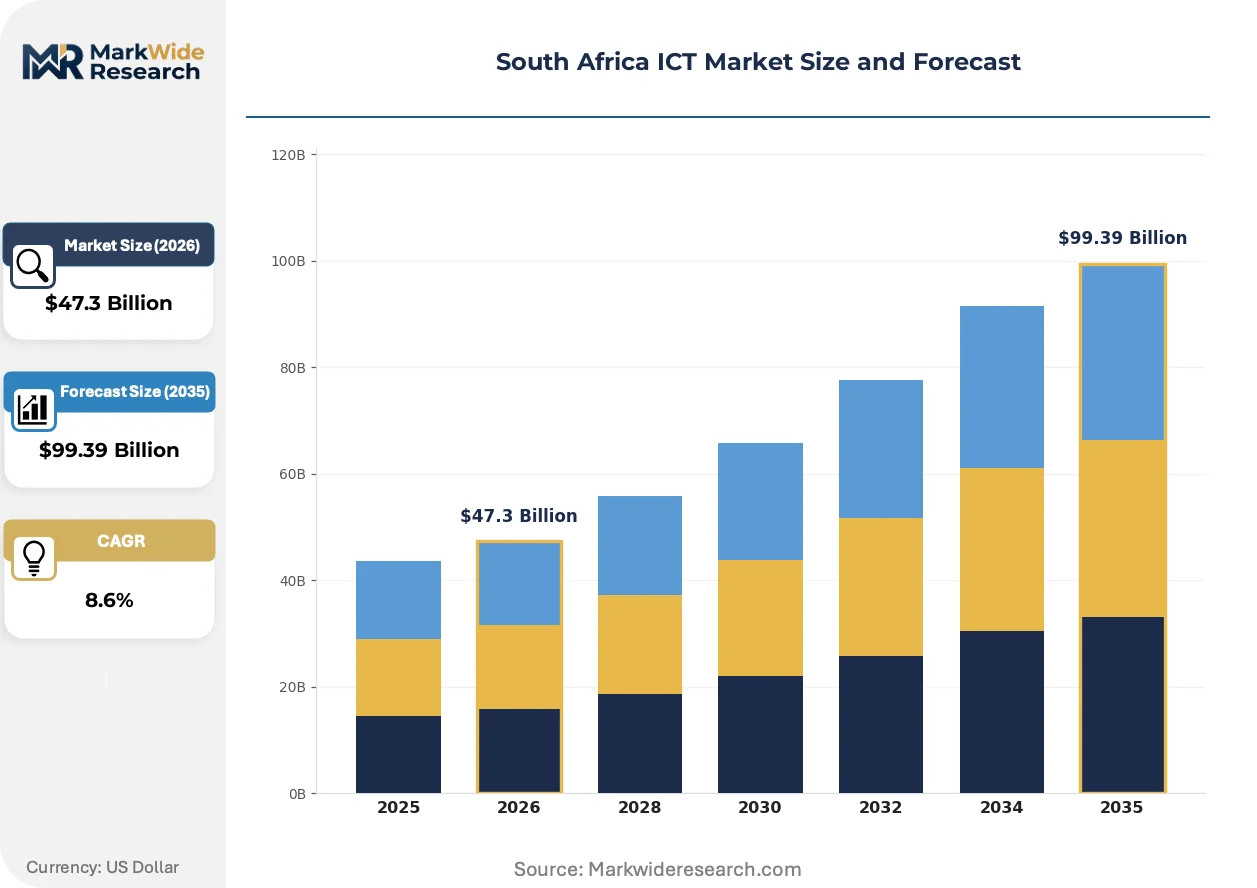
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $99.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Cybersecurity, IT Consulting, Managed Services End User: Healthcare Providers, Financial Institutions, Educational Institutions, Government Agencies Technology: Artificial Intelligence, Big Data, Internet of Things, Blockchain Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Vodacom Group Ltd, MTN Group Ltd, Telkom SA SOC Ltd, NTT Ltd, Dell Technologies Inc, Datacentrix, Altron Karabina, Westech, NETCONFIG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa ICT Market Evolving Landscape
Software-defined networking and AI-driven network operations are displacing hardware-centric infrastructure management, compressing operational headcount requirements while elevating automation investment priorities across enterprise and service provider segments.
Software-defined wide area networking is displacing MPLS-based private circuits in enterprise branch connectivity. Mining houses and retail chains with distributed footprints across Mpumalanga and KwaZulu-Natal are adopting SD-WAN at 18-month replacement cycles. This displacement is collapsing traditional carrier revenue from leased-line services while redistributing value toward overlay security and application-aware routing vendors.
POPIA enforcement thresholds from the Information Regulator are mandating data residency and encryption standards that reshape cloud procurement architecture. Healthcare providers and insurers must now certify that patient records remain within national borders, forcing hyperscale providers to establish local availability zones. The Western Cape and Gauteng health departments are prioritizing vendors with certified local data centre presence over cost-optimized offshore alternatives.
Subscription-based IT consumption models are replacing perpetual license procurement across mid-market enterprises. Managed service providers in Durban and Pretoria are unbundling hardware, software, and operational support into monthly per-seat arrangements. This shift is most pronounced among legal practices and accounting firms where capital expenditure constraints intersect with compliance-driven technology refresh requirements.
South Africa ICT Market Segmentation
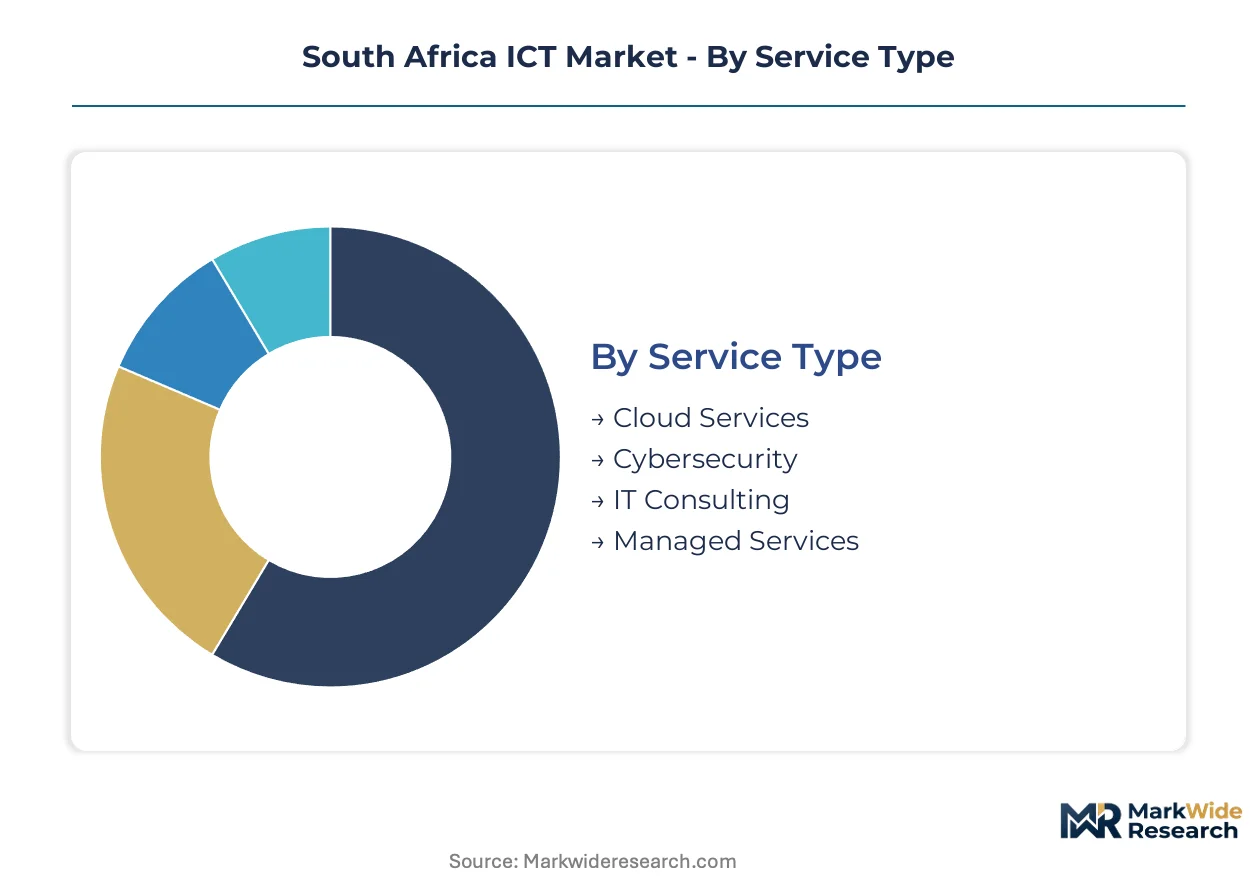
South Africa's ICT market exhibits distinct procurement patterns across service layers, with POPIA compliance and B-BBEE certification requirements fragmenting vendor selection criteria. Understanding these segment boundaries reveals where margin pools concentrate and where regulatory friction creates structural barriers to entry.
Service Type:
ICASA's spectrum licensing timelines and the Information Regulator's POPIA enforcement thresholds differentiate procurement urgency across service categories, with data residency mandates elevating certain segments above others.
- Cloud Services:Hybrid and multi-tenant architectures dominate enterprise procurement in Johannesburg and Cape Town, where financial institutions balance scalability against POPIA-mandated data sovereignty. Local availability zones from hyperscale providers are displacing offshore-first strategies among healthcare and banking clients.
- Cybersecurity:Managed detection and response services command premium pricing as ransomware campaigns intensify against Gauteng healthcare networks and Western Cape municipal systems. Zero-trust architecture implementations are accelerating among insurers and asset managers with distributed workforces.
- IT Consulting:System integration and legacy modernization projects concentrate in Pretoria and Durban, serving government agencies and parastatals navigating B-BBEE procurement codes.
- Managed Services:End-user computing and network operations outsourcing gains traction among Eastern Cape and Mpumalanga enterprises lacking internal technical capacity.
Cloud Services handles the majority of throughput; Cybersecurity is expanding most quickly on share.
End User:
Cost tier differentiation separates enterprise-grade deployments from constrained public sector budgets, with compliance burden intensity varying sharply across institutional categories.
- Financial Institutions:Banks and insurers in Johannesburg's Sandton corridor drive hybrid cloud investment, with POPIA audit requirements mandating encrypted data lakes and certified local data centre presence. Core banking containerization projects stretch across multi-year timelines.
- Government Agencies:National Treasury's preferential procurement regulations and B-BBEE ICT sector codes structure vendor qualification, with SITA and provincial departments prioritizing local content thresholds over pure cost optimization.
- Healthcare Providers:Western Cape and Gauteng health departments require patient record residency within national borders, forcing cloud architecture decisions toward certified domestic infrastructure.
- Educational Institutions:Universities and TVET colleges balance connectivity scaling against capital constraints, with NSFAS disbursement integration driving student information system upgrades.
Financial Institutions absorb the largest technology spend; Government Agencies face the most elongated procurement cycles.
Technology:
Application maturity determines where pilot projects convert to production deployments, with latency-sensitive use cases commanding infrastructure priority.
- Artificial Intelligence:Natural language processing and computer vision applications concentrate in financial services fraud detection and mining safety monitoring, with Johannesburg-based data science talent scarcity constraining scaling velocity.
- Big Data:Real-time analytics platforms serve retail chains and logistics operators across KwaZulu-Natal and Mpumalanga, integrating point-of-sale and fleet telemetry streams.
- Internet of Things:Sensor networks for predictive maintenance and smart metering expand in manufacturing and utility verticals, with 5G radio access networks enabling sub-100 millisecond response times.
- Blockchain:Distributed ledger pilots remain confined to trade finance and identity verification use cases, with regulatory ambiguity limiting production deployment.
Big Data carries the heaviest processing load; Artificial Intelligence is climbing the fastest on investment priority.
Deployment:
Customer type and data sensitivity dictate architecture selection, with regulated industries maintaining on-premises or private cloud dominance despite public cloud cost advantages.
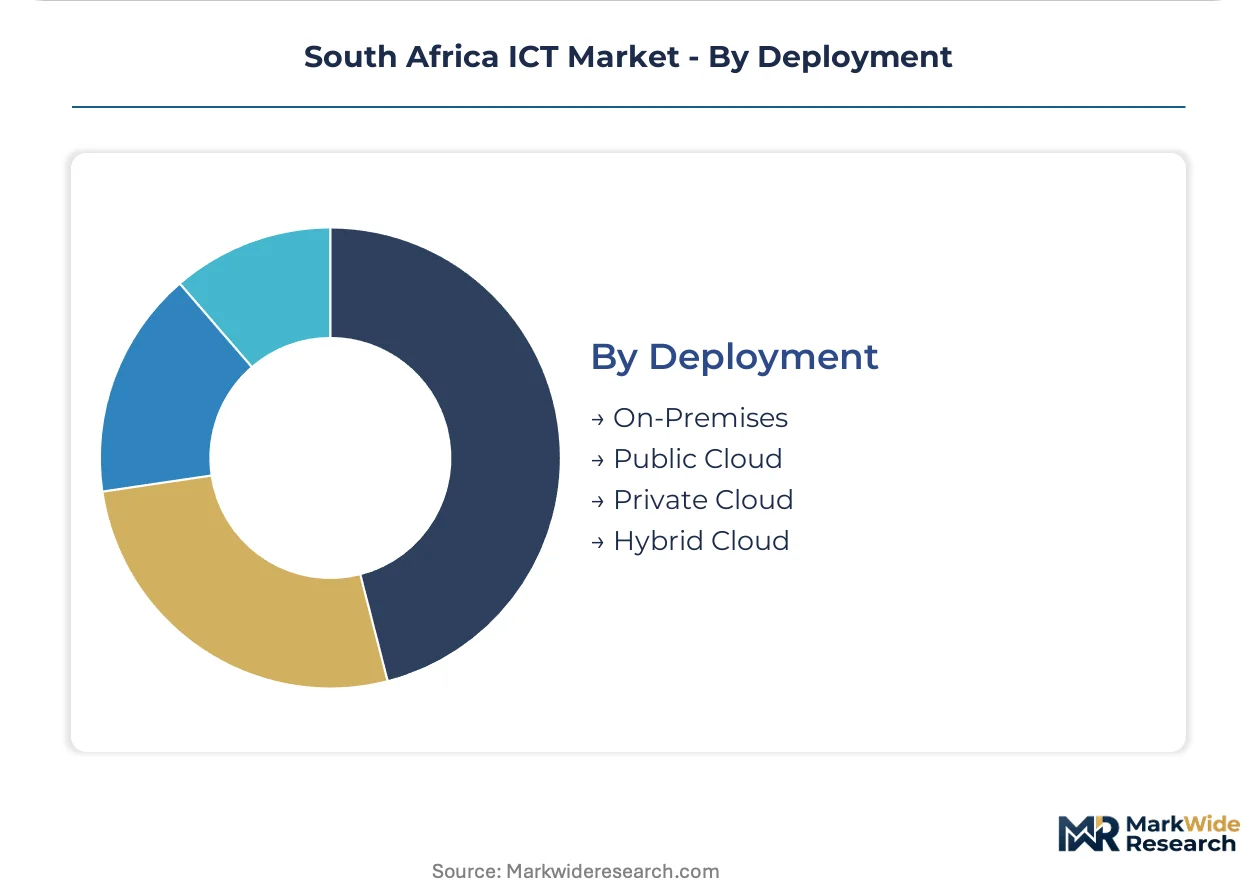
- Hybrid Cloud:Workload portability between on-premises infrastructure and public cloud resources addresses POPIA compliance while preserving elasticity, dominating financial and healthcare procurement.
- Private Cloud:Dedicated tenant environments serve government agencies and defense contractors with classified or sensitive operational requirements, often delivered through certified local data centre operators.
- On-Premises:Legacy mainframe and specialized hardware persists in core banking and industrial control systems, with containerization roadmaps extending replacement timelines.
- Public Cloud:Software-as-a-service productivity suites and development environments attract SMME adoption in Durban and Port Elizabeth, where capital constraints favor operational expenditure models.
Hybrid Cloud dominates enterprise architecture decisions; Public Cloud is gaining share fastest among mid-market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's ICT trade balance tilts toward service imports, with hardware component dependence on Asian manufacturing centers and software licensing outflows to US and European vendors. Metropolitan infrastructure investment concentrates in three provincial corridors, while rural connectivity gaps persist despite universal service obligations.
Gauteng
Sandton's financial district drives enterprise cloud consumption, with banks and insurers mandating hybrid architectures for POPIA compliance. ICASA's spectrum auction timelines accelerate 5G base station deployment across Johannesburg and Pretoria. The Tshwane-Johannesburg corridor hosts the densest fibre-to-the-business penetration nationally, with data centre operators expanding cooling capacity for AI workloads.
Western Cape
Cape Town's tech startup ecosystem attracts venture capital for fintech and healthtech platforms requiring low-latency infrastructure. The provincial health department enforces patient data residency rules that privilege local cloud availability zones. Atlantis and Stellenbosch industrial zones concentrate submarine cable landing stations and hyperscale data centre construction.
KwaZulu-Natal
Durban's port logistics sector deploys IoT sensor networks for container tracking and predictive maintenance. Transnet's digital modernization programs channel procurement toward local B-BBEE-certified systems integrators. The Dube TradePort special economic zone anchors edge computing investments for real-time supply chain visibility.
Eastern Cape
Gqeberha's automotive manufacturing cluster lags in fibre density, creating greenfield opportunities for infrastructure operators. Provincial education department connectivity programs depend on National Treasury conditional grants with delayed disbursement cycles. The Coega industrial development zone attracts data centre investment through tax incentive structures.
South Africa ICT Market Competitive Landscape
Concentration sits with integrated telecommunications operators controlling spectrum, fibre, and mobile money infrastructure. The market structure exhibits tiered competition: three national mobile network operators dominate connectivity, mid-tier systems integrators capture enterprise transformation projects, and specialized cybersecurity boutiques serve regulated verticals. Dominant competitive moves include fibre wholesale unbundling and data centre vertical integration.
Among Johannesburg-listed operators, Vodacom Group Ltd and MTN Group Ltd exemplify the integrated connectivity archetype, while Telkom SA SOC Ltd occupies a distinctive position through wholesale fibre and government contract concentration. NTT Ltd represents the multinational systems integrator tier competing for enterprise cloud migration mandates.
| Leading Market Players |
|---|
| Vodacom Group Ltd |
| MTN Group Ltd |
| Telkom SA SOC Ltd |
| NTT Ltd |
| Dell Technologies Inc |
| Datacentrix |
| Altron Karabina |
| Westech |
| NETCONFIG |
| Others |
Value Network & Pricing Analysis
SD-WAN overlay services displacing MPLS circuits simultaneously redraw procurement geography toward software vendors and compress carrier pricing power across Johannesburg and Cape Town enterprise corridors. This substitution shifts value capture from hardware-centric infrastructure providers to application-aware routing specialists while fragmenting buyer concentration.
Pricing Analysis
Financial institutions anchor subscription-based pricing structures across hybrid cloud and managed security categories. Three-tier pricing structure across premium, standard, and economy levels separates POPIA-certified domestic deployments from uncertified offshore alternatives, with volume scale and compliance grade as primary differentiation drivers. Cost compression in mid-market connectivity stems from rand-dollar volatility pressuring imported hardware costs. SMMEs exhibit highest price sensitivity, while government agencies prioritize B-BBEE certification thresholds over pure cost optimization.
Supply Chain Analysis
Submarine cable landing stations at Melkbosstrand and Mtunzini underwrite international bandwidth availability for Gauteng and KwaZulu-Natal data centres. Hardware component sourcing draws from China, South Korea, and Taiwan for fibre optic equipment and semiconductor infrastructure. Single-source vulnerability concentrates at coastal landing facilities with limited redundancy for inland connectivity. Distribution runs through certified systems integrators and direct carrier relationships serving enterprise and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's ICT market sits at a platform-economics inflection where API interoperability between banking cores and cloud service providers is rewiring competitive moats around data sovereignty compliance.
For Market Incumbents: Shield enterprise relationships by deepening captive supply of certified local data centre capacity ahead of hyperscale availability zone expansion. Accelerate fibre wholesale unbundling to neutralize MTN and Vodacom's radio access network advantages in underpenetrated Eastern Cape municipalities.
For New Entrants and Emerging Players: Lead with zero-trust cybersecurity bundles targeting healthcare providers in Western Cape and Gauteng where POPIA enforcement has elevated managed detection from discretionary to mandatory procurement. Channel partnerships with B-BBEE-certified systems integrators unlock government agency access constrained by preferential procurement regulations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier cloud consultancies in Durban and Pretoria holding government transformation contracts. Long-term viability hinges on recurring revenue concentration versus project dependency. Watch ICASA spectrum auction timing as inflection signal for infrastructure capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API interoperability between banking cores and cloud providers rewires competitive positioning around POPIA compliance. |
| Geographic Expansion | Fibre density buildout in Eastern Cape automotive clusters captures greenfield enterprise demand outside saturated Gauteng corridors. |
| Strategic Partnership | Channel alliances with B-BBEE-certified integrators unlock National Treasury procurement pathways for foreign technology vendors. |
| Acquisition of Specialist Firm | Zero-trust cybersecurity boutiques in Cape Town command premium valuations amid ransomware intensification against healthcare targets. |
| Product Launch | Edge computing nodes at 5G base stations enable sub-10 millisecond latency for autonomous mining applications in Mpumalanga. |
Research Methodology
Cross-validation between primary interviews with network operations directors, cloud procurement officers, and ICASA regulatory affairs leads and secondary validation through SEC filings, hyperscaler capex disclosures, and SITA procurement databases anchors the qualitative findings. Bottom-up triangulation across service provider revenue disclosures and top-down reconciliation against National Treasury ICT expenditure reports ensures segmentation integrity.
Sensitivity analysis across the projection horizon models service type, end user vertical, deployment architecture, and geographic adoption pattern dimensions. CAGRs derive from historical trajectory fitting adjusted for spectrum licensing timelines and POPIA enforcement intensity. Forecast inputs incorporate rand-dollar exchange rate assumptions and submarine cable capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside ICASA regulatory clarity and National Treasury disbursement continuity would require recalibration. Forecasts reflect documented assumptions regarding enterprise cloud migration velocity and cybersecurity procurement prioritization. Practitioners should keep alternative scenarios live as spectrum auction outcomes and data localisation enforcement thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Europe ICT Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Global DDI Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Revenue Management Software Market