
 APAC Digital Signage Market | 2026-2036
APAC Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Digital Signage Market Outlook
The capital-intensity divergence between display panel fabricators and software-integrated systems providers is reorganizing competitive hierarchies across the APAC Digital Signage landscape. Samsung Electronics Co Ltd leverages in-house semiconductor capacity to control display driver costs and refresh rate performance. LG Display Co Ltd anchors its position through OLED panel specialization for premium commercial installations. Leyard Optoelectronic Co Ltd dominates fine-pitch LED manufacturing for command-center video walls in Chinese infrastructure projects.
APAC Digital Signage encompasses networked visual communication systems comprising display panels, media players, content management software, and connectivity infrastructure engineered for luminance levels exceeding 500 nits in ambient-light environments, with primary commercial purpose centered on dynamic audience engagement in high-traffic physical spaces. LCD installations retain volume leadership across retail and transportation applications due to established supply chains and lower per-unit costs, while OLED segments command margin concentration in hospitality and corporate settings where color fidelity and form-factor flexibility justify premium positioning. Interactive Displays technology is expanding fastest within Education end-user deployments as touch-enabled collaborative platforms replace static whiteboard infrastructure.
Japan's METI enforces JIS standards for electromagnetic compatibility and thermal efficiency in public display installations, while China's MIIT administers GB standards governing energy consumption metrics for commercial screen networks. South Korea's MFDS intersects with healthcare digital signage through medical-grade display certification requirements for diagnostic imaging applications. Stakeholders must weigh regulatory compliance costs against localization advantages when selecting manufacturing footprints and content delivery architectures across fragmented national standards regimes.
Market Dynamics
China's MIIT energy-efficiency mandates are compressing display technology refresh cycles across commercial infrastructure networks. Panel fabricators must retool manufacturing lines to meet GB standards for luminance-per-watt performance, accelerating capital redeployment from LCD toward LED and OLED platforms.
Growth Catalysts
- Transit corridor digitization:Japan's urban rail operators are replacing static wayfinding with networked LED arrays. METI infrastructure grants cover 40% of installation costs for stations exceeding 100,000 daily passengers.
- Retail engagement mandates:Southeast Asian mall operators now require tenant digital displays as lease conditions. Interactive touchscreens drive dwell-time metrics tied to rent escalation clauses.
- MIIT dual-carbon alignment:China's GB 21520-2023 standard mandates 30% power reduction in commercial displays. LED backlighting transitions qualify manufacturers for provincial green technology subsidies.
Market Restraints
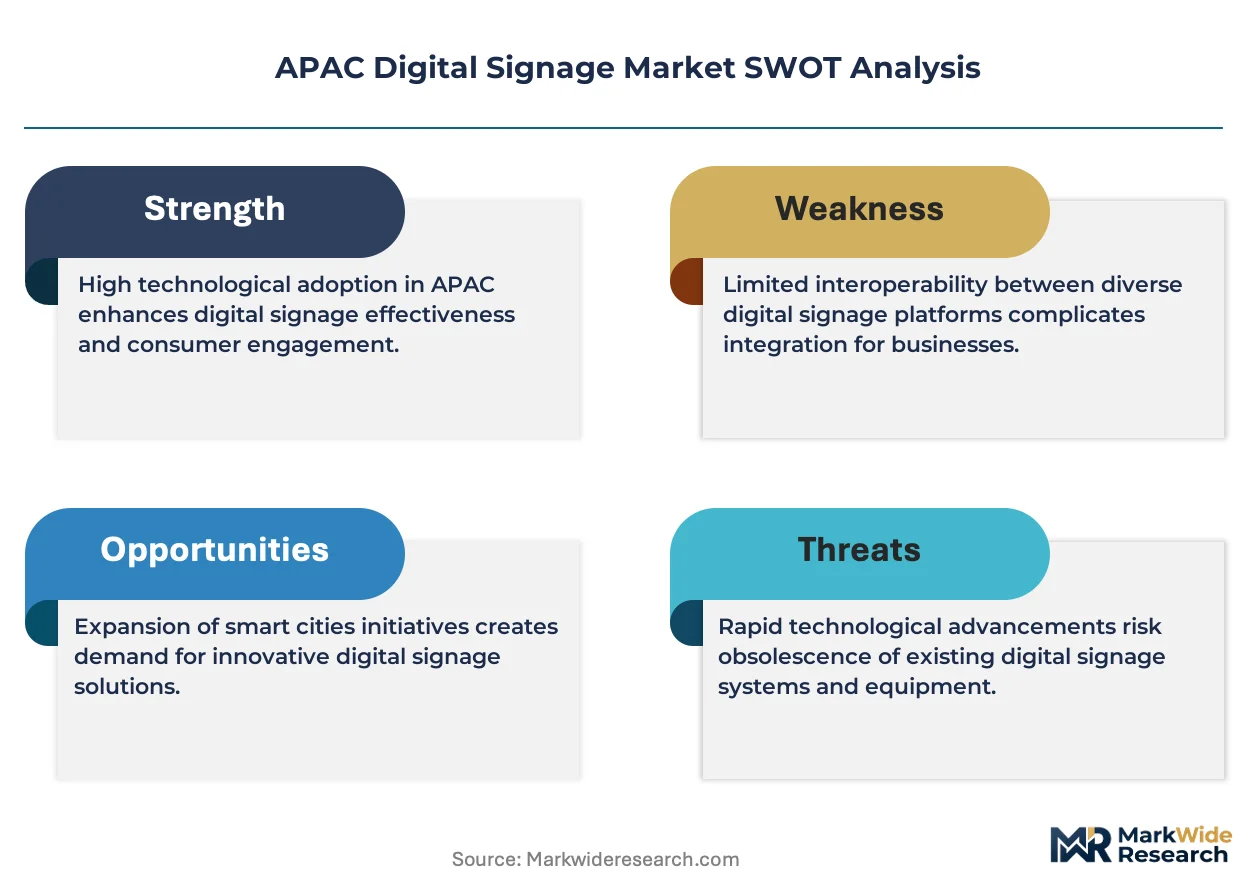
- Driver IC supply concentration:Taiwan and South Korean foundries control 78% of display driver semiconductor capacity. Geopolitical friction creates 14-20 week lead time volatility for panel assemblers.
- OLED material cost structure:Phosphorescent emitter compounds require iridium and platinum feedstocks. Precious metal price swings compress margin predictability for premium commercial installations.
- Fragmented national certification:Each APAC jurisdiction maintains distinct electromagnetic compatibility testing. JIS, GB, and KC mark requirements force redundant engineering cycles for cross-border deployments.
Strategic Opportunities
- Vietnam manufacturing migration:Panel assembly lines are relocating to Bac Ninh and Hai Phong industrial zones. Labor cost differentials and EU-Vietnam FTA tariff advantages attract Korean and Japanese capital.
- Healthcare diagnostic integration:South Korea's MFDS medical-grade display certification creates a protected segment. Surgical and radiology applications command 3-4x pricing multiples versus commercial signage.
- 5G-8K convergence:China's MIIT spectrum allocation enables uncompressed 8K content distribution. Sports venues and command centers are piloting real-time ultra-high-definition streaming without fiber trenching.
Industry Challenges
- Firmware integration complexity:Legacy content management platforms lack API compatibility with cloud-native analytics stacks. System integrators face 6-9 month customization timelines for mixed-vendor environments.
- Thermal engineering talent scarcity:High-brightness outdoor installations require specialized heat dissipation design. The talent pool for computational fluid dynamics modeling concentrates in Shenzhen and Seoul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Digital Signage Market |
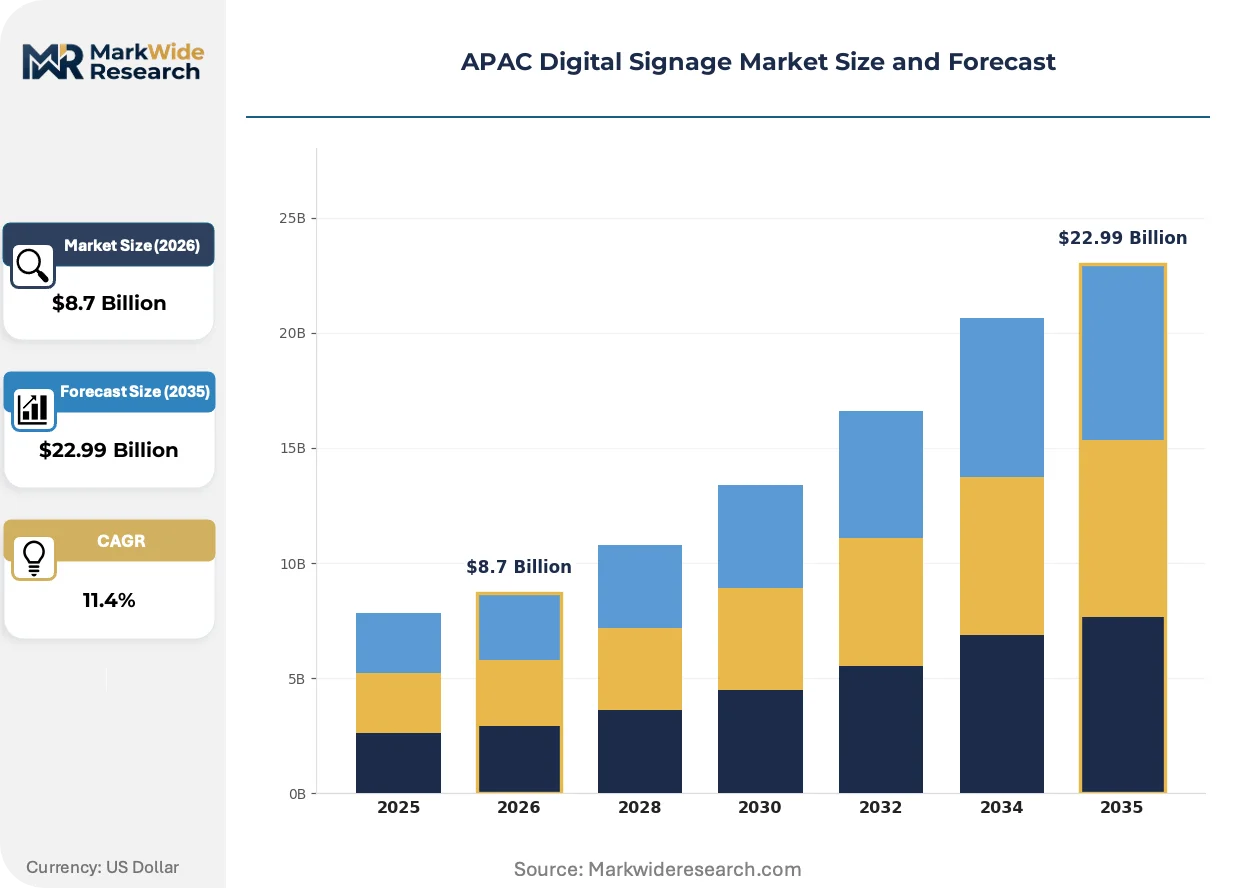
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Projectors Application: Retail, Transportation, Hospitality, Education End User: Corporate, Government, Entertainment, Healthcare Technology: Interactive Displays, Digital Posters, Video Walls, Projection Mapping |
| Companies Covered | Panasonic Corporation, Barco NV, LG Display Co Ltd, Leyard Optoelectronic Co Ltd, Hitachi Ltd, Samsung Electronics Co Ltd, Sony Corporation, AUO Corporation, NEC Display Solutions Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Digital Signage Market Strategic Shifts
Active-matrix mini-LED backlighting is compressing the performance gap between LCD cost structures and OLED visual quality. This technology convergence is redrawing segment boundaries across retail, corporate, and public infrastructure applications.
Mini-LED local dimming zones now exceed 2,000 per panel in commercial-grade products. Japanese broadcast studios and Chinese luxury retail chains are adopting these displays for HDR content presentation. The technology is supplanting direct-view OLED in applications where 2,000+ nit sustained brightness proves essential.
South Korea's MFDS revised medical display performance standards in 2023, mandating luminance stability tracking for diagnostic monitors. Equipment vendors must submit 10,000-hour aging test data for certification renewal. Radiology departments in Seoul and Busan are accelerating replacement cycles to meet the new compliance window.
Content-as-a-service contracts now displace perpetual software licenses among mid-market retail chains. Australian and Singaporean operators prefer subscription models bundling creative production, scheduling, and remote monitoring. This procurement evolution compresses upfront capex while locking in recurring vendor relationships across 36-48 month terms.
APAC Digital Signage Market Segmentation
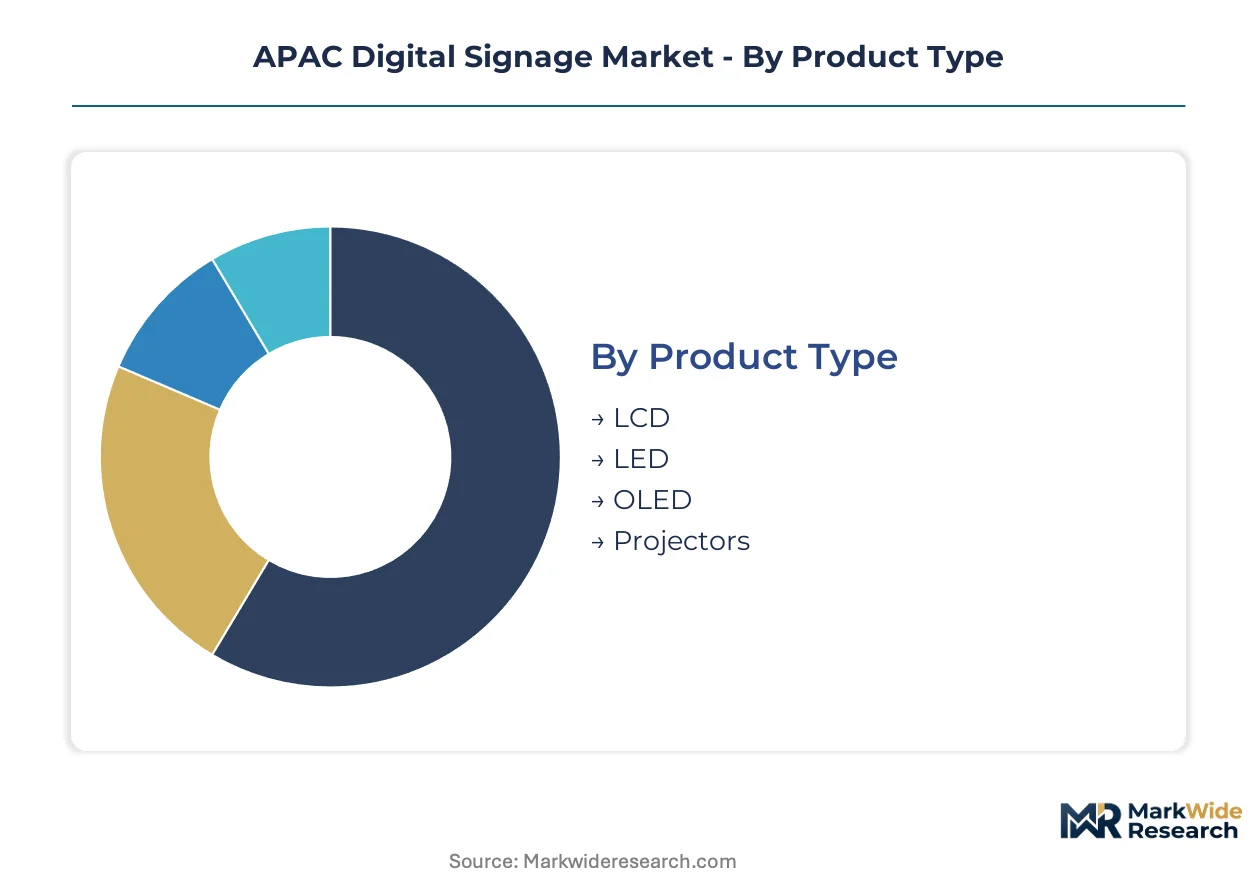
Display technology choices in APAC Digital Signage directly determine channel economics and installation complexity. Panel fabricators route LCD volumes through established distribution networks while OLED and LED platforms demand specialized system integrator relationships.
Product Type:
LCD panels move through mass-market distributors serving retail and transit operators. LED and OLED platforms require direct manufacturer-to-integrator relationships for custom engineering support.
- LCD:Thin-film transistor arrays with fluorescent or LED edge-lit backlighting dominate volume shipments. Japan's urban rail corridors and Southeast Asian mall operators specify these units for cost-sensitive wayfinding deployments where 500-700 nit brightness suffices.
- LED:Direct-view fine-pitch modules using surface-mounted diode packages achieve 2,000+ nit output for outdoor visibility. Chinese infrastructure projects and South Korean corporate campuses drive specification for command-center video walls requiring seamless bezel-free construction.
- OLED:Organic electroluminescent layers enable sub-3mm profiles and infinite contrast ratios.
- Projectors:Laser-phosphor or lamp-based projection systems for temporary or immersive installations.
By volume, LCD leads. By growth pace, LED is ahead.
Application:
End-use environments impose distinct performance specifications that fragment procurement channels and margin structures.
- Retail:Point-of-sale and window-facing displays prioritize 1,500+ nit brightness for daylight readability. Southeast Asian mall operators mandate tenant-installed digital signage as lease conditions, creating recurring replacement cycles tied to fit-out renovations.
- Transportation:Wayfinding and arrival-time displays require 24/7 operational reliability. Japan's METI infrastructure grants cover installation costs for stations exceeding 100,000 daily passengers, accelerating LED array deployment across Tokyo-Osaka corridor networks.
- Hospitality:Lobby and conference installations emphasize aesthetic integration and color fidelity.
- Education:Interactive collaborative platforms replacing static whiteboard infrastructure.
Transportation commands the highest unit reliability specifications. Education is expanding most quickly as touch-enabled platforms displace legacy classroom equipment.
End User:
Budget authority and procurement compliance requirements vary sharply across institutional buyer categories.
- Corporate:Campus networks and meeting room infrastructure. South Korean chaebol headquarters specify OLED for executive floors while standardizing LCD for general workforce areas.
- Government:Public information systems and command centers. China's MIIT energy-efficiency mandates accelerate LED transitions in municipal procurement frameworks.
- Entertainment:Venues and experiential installations demanding high-refresh-rate performance.
- Healthcare:Diagnostic imaging and patient communication displays. South Korea's MFDS medical-grade certification creates protected pricing tiers for surgical and radiology applications.
Government procurement volumes fluctuate with infrastructure budget cycles. Healthcare maintains the steepest pricing premiums due to regulatory compliance requirements.
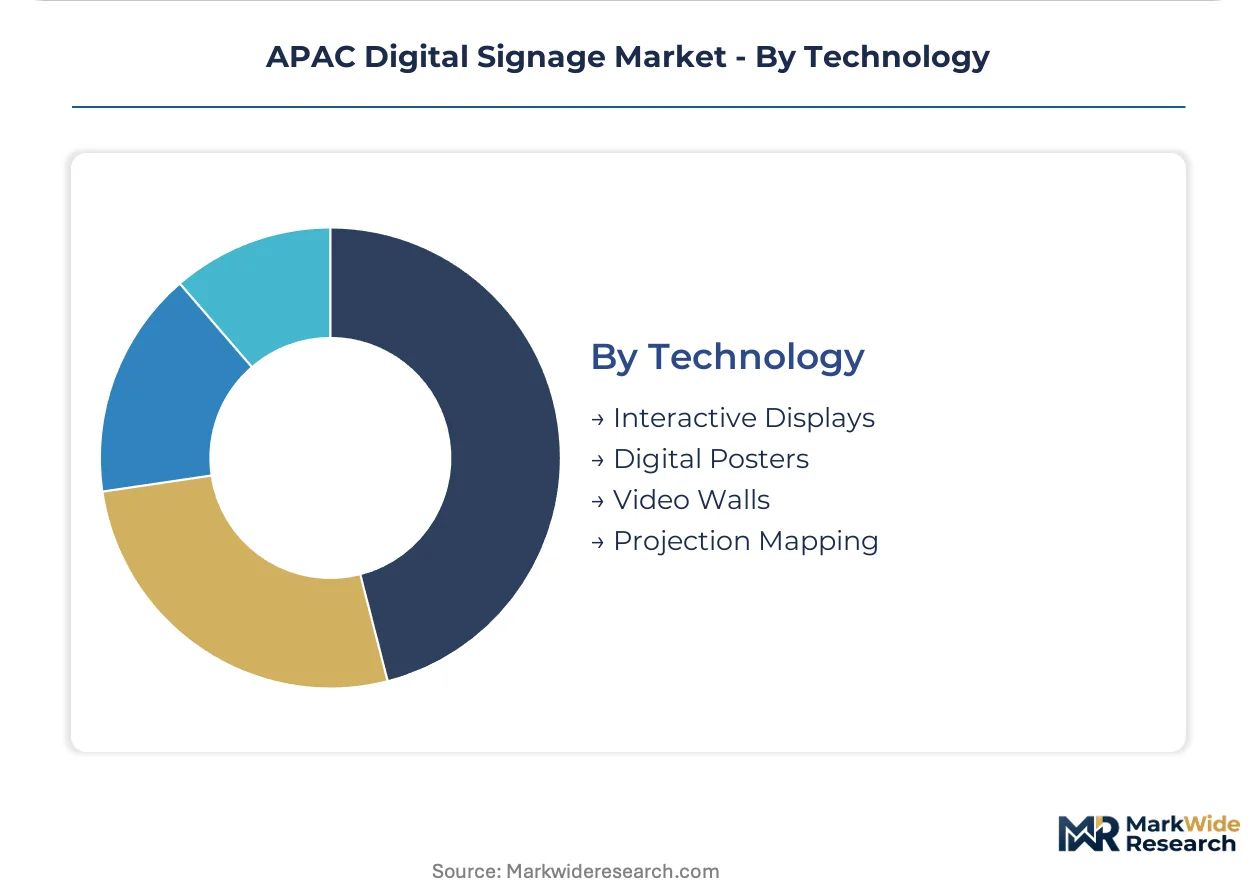
Technology:
Hardware-software integration depth separates commodity display sales from recurring service revenue models.
- Interactive Displays:Projected-capacitive or infrared touch overlays enabling multi-user collaboration. Australian and Singaporean education ministries specify these platforms for classroom modernization programs.
- Digital Posters:Standalone networked screens with integrated media players. Southeast Asian quick-service restaurant chains deploy these for menu board automation.
- Video Walls:Tiled display arrays requiring bezel compensation and color calibration.
- Projection Mapping:Geometric correction software enabling irregular surface illumination.
Digital Posters ship in highest unit volumes. Interactive Displays are gaining share fastest as touch interfaces become standard in education and corporate meeting spaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region. Southeast Asian retail chains prioritize per-unit cost minimization for high-volume deployments. Japanese transit operators and South Korean corporate campuses accept substantial premiums for reliability specifications and visual performance.
China
MIIT energy-efficiency mandates are accelerating LED backlighting transitions across commercial display networks. Provincial green technology subsidies under the dual-carbon framework reward manufacturers meeting GB 21520-2023 luminance-per-watt standards. Shenzhen and Dongguan industrial clusters concentrate panel assembly and driver IC packaging capacity for domestic infrastructure projects.
Japan
Urban rail operators are replacing static wayfinding with networked LED arrays across Tokyo-Osaka corridor stations. METI infrastructure grants cover 40% of installation costs for facilities exceeding 100,000 daily passengers. Nagoya and Osaka manufacturing bases supply high-reliability components for 24/7 transit applications.
South Korea
Chaebol headquarters specify differentiated display tiers across corporate campus networks. MFDS medical-grade certification requirements create protected pricing for diagnostic imaging applications in Seoul and Busan hospital systems. Suwon and Gumi industrial zones anchor OLED panel specialization and semiconductor driver production.
Vietnam
Panel assembly lines are relocating to Bac Ninh and Hai Phong industrial zones to capture labor cost differentials. EU-Vietnam FTA tariff advantages attract Korean and Japanese capital for re-export manufacturing. Ho Chi Minh City logistics corridors are developing as distribution hubs for Southeast Asian retail chains.
Australia
Education ministries specify touch-enabled collaborative platforms for classroom modernization programs. Content-as-a-service subscription models displace perpetual software licenses among mid-market retail operators. Sydney and Melbourne metropolitan procurement frameworks favor bundled creative production and remote monitoring contracts.
APAC Digital Signage Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the APAC Digital Signage landscape. Panel fabricators with captive semiconductor capacity control display driver costs and refresh rate performance, while specialized LED manufacturers command premium positioning in fine-pitch command-center applications. The competitive structure organizes around three strategic archetypes: diversified electronics conglomerates, display technology specialists, and system integration providers. Dominant competitive moves include manufacturing footprint migration to lower-cost jurisdictions and vertical integration into content management software stacks.
Among diversified electronics conglomerates, Samsung Electronics Co Ltd and LG Display Co Ltd occupy positions spanning semiconductor, panel, and system-level capabilities. Leyard Optoelectronic Co Ltd exemplifies the specialized manufacturer archetype with concentrated exposure to fine-pitch LED video wall applications. These three companies represent distinct strategic postures: integrated component-to-system control, OLED technology specialization, and infrastructure-scale LED deployment expertise.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Barco NV |
| LG Display Co Ltd |
| Leyard Optoelectronic Co Ltd |
| Hitachi Ltd |
| Samsung Electronics Co Ltd |
| Sony Corporation |
| AUO Corporation |
| NEC Display Solutions Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan and South Korean foundries lock in display driver IC supply and stabilize unit economics for panel assemblers navigating MIIT energy-efficiency transitions. These arrangements tie procurement visibility to GB 21520-2023 compliance timelines while buffering against geopolitical lead time volatility.
Pricing Analysis
After-sales service revenue tiers spanning remote monitoring, firmware updates, and field maintenance now drive lifetime value capture across APAC Digital Signage deployments. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade MFDS-certified displays from commercial LED arrays and entry-level LCD units. Cost compression in standard-tier LCD panels is intensifying because of Vietnam manufacturing migration and labor arbitrage. Southeast Asian retail chains exhibit highest price sensitivity, while South Korean healthcare systems accept substantial premiums for diagnostic imaging certification.
Supply Chain Analysis
Just-in-time inventory strategies dominate downstream distribution, while strategic stockpiling of iridium and platinum feedstocks buffers OLED emitter compound volatility. Panel assembly concentrates in China, Vietnam, and South Korea, with driver IC fabrication drawing from Taiwan and South Korean foundries. Raw material dependencies span indium tin oxide substrates, gallium nitride semiconductors, and rare-earth phosphors. Single-source vulnerability in display driver capacity creates structural exposure. Distribution runs through specialized system integrators for LED and OLED platforms, while LCD volumes move via mass-market distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC Digital Signage is approaching a platform-economics inflection where content management software stacks determine vendor stickiness beyond hardware refresh cycles. Interoperability between cloud-native analytics and legacy firmware is reshaping procurement authority toward IT departments.
For Market Incumbents: Compound defensive positioning through backward integration into semiconductor driver design and captive OLED material refining. Samsung Electronics Co Ltd and LG Display Co Ltd should deepen in-house production of display controllers to offset Taiwan foundry concentration risk. Certification investment in MFDS medical-grade tiers protects margin pools from commodity LCD erosion.
For New Entrants and Emerging Players: Content-as-a-service subscription gaps in Australian and Singaporean mid-market retail chains offer white-space entry points. Southeast Asian education ministries specifying interactive collaborative platforms represent the most penetrable segment. A go-to-market angle bundling creative production with hardware leasing bypasses incumbent perpetual-license relationships.
For Investors and Strategic Acquirers: Specialized LED system integrators with command-center project expertise represent the priority acquisition archetype. Long-term viability hinges on software recurring revenue ratios exceeding hardware dependency. Watch for 5G-8K convergence pilot outcomes in Chinese sports venues as inflection signal for infrastructure upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captive semiconductor capacity insulates Samsung and LG from Taiwan foundry lead time volatility. |
| Content-as-a-Service Platform Launch | Subscription bundling locks in Australian retail chains across 36-48 month recurring terms. |
| MFDS Medical-Grade Certification Investment | Protected pricing tiers in Seoul and Busan hospital systems command 3-4x commercial multiples. |
| Vietnam Manufacturing Footprint Expansion | Bac Ninh and Hai Phong zones capture EU-Vietnam FTA tariff advantages for Korean and Japanese capital. |
| 5G-8K Convergence Pilot Deployment | MIIT spectrum allocation enables real-time ultra-high-definition streaming without fiber trenching in Chinese venues. |
Study Parameters
The analysis maps LCD, LED, OLED, and projector sub-sectors, each validated through display panel procurement managers, transit authority engineering directors, retail mall operations executives, and healthcare biomedical equipment specialists. Primary interview insights triangulate against MIIT regulatory filings, METI infrastructure grant disclosures, MFDS certification databases, and customs trade records for display component flows. Bottom-up unit shipment modeling reconciles with top-down market value estimates across technology and application dimensions.
Consistency checks validate volume and value outputs against external benchmarks spanning the projection horizon. The analytical framework models by display technology, application environment, end-user institution type, and software integration depth. CAGRs derive from segmented growth trajectory blending rather than single-point extrapolation. Forecast inputs incorporate MIIT dual-carbon policy implementation pace and METI transit corridor digitization grant uptake.
Underlying assumptions cover GB 21520-2023 compliance timelines and Taiwan foundry capacity stability, with deviation risk concentrated in geopolitical friction escalation and iridium price volatility. Forecasts reflect documented conditions without scenario-weighted probability layers. Revision becomes warranted when driver IC lead time volatility crosses 20-week thresholds or when OLED material cost swings exceed medical-grade pricing absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Inventory Management Market
Digital Solutions
Product As a Service Market
Digital Solutions
Utility Cases Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Australia ICT Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Bahrain ICT Market