
 Global Online Dating Services Market | 2026-2036
Global Online Dating Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Dating Services Market Outlook
ISO/IEC 27001 certification for information security management is bifurcating the competitive landscape as platforms without accredited data protection frameworks face exclusion from enterprise partnership channels and institutional advertising budgets. Match Group leverages its portfolio breadth to sustain cross-platform user retention economies. Bumble Inc anchors its position through women-first interface architecture that differentiates its brand in saturated North American and European markets.
Online dating services constitute digitally delivered interpersonal matching platforms that employ behavioral analytics, geolocation telemetry, and preference taxonomy engines to broker romantic or social connections between registered users. The primary commercial purpose centers on monetizing user attention through subscription tiers, in-application microtransactions, and targeted advertising inventory. Subscription services capture the dominant margin pool as recurring revenue models outperform advertising-dependent free services in lifetime value metrics. Mobile apps lead device type penetration due to persistent connectivity and push-notification engagement mechanics, while algorithmic matching displaces manual curation as machine learning inference costs decline.
The Federal Trade Commission in the United States polices deceptive subscription practices and romance scam liability, while the European Union's GDPR imposes strict consent architecture and data portability mandates that elevate operational compliance costs. China's Personal Information Protection Law and India's Digital Personal Data Protection Act introduce additional localization and processing restrictions for platforms operating across these jurisdictions. Stakeholders must monitor evolving encryption standards and age-verification mandates as regulatory fragmentation intensifies platform architecture complexity.
Market Dynamics
Algorithmic matchmaking infrastructure is bifurcating the competitive landscape as platforms with proprietary machine learning inference capabilities capture disproportionate user engagement metrics against legacy manual-curation systems. This technical divergence compounds with regulatory fragmentation across data protection jurisdictions.
Growth Catalysts
- GDPR Compliance Architecture:European data portability mandates are forcing platform investments in interoperable user profile systems that reduce switching friction and expand addressable market depth.
- Mobile-First Engagement Mechanics:Persistent connectivity and push-notification optimization are driving session frequency improvements among young adult demographics in India and Brazil.
- Behavioral Analytics Engines:Preference taxonomy systems that ingest cross-platform interaction data are improving match quality scores and reducing subscriber churn rates.
Market Restraints
- Data Localization Mandates:China's Personal Information Protection Law and India's Digital Personal Data Protection Act impose server residency requirements that fragment technical infrastructure and elevate operational costs.
- Input Cost Concentration:Cloud compute and GPU inference pricing volatility tied to NVIDIA supply constraints compresses margin expansion for mid-tier platforms.
- Substitution Threat:Social audio platforms and interest-based community applications are capturing romantic connection formation outside dedicated dating interfaces.
Strategic Opportunities
- Southeast Asia Penetration:Indonesia, Vietnam, and the Philippines exhibit low subscription saturation relative to smartphone penetration depth, creating whitespace for localized interface adaptation.
- ISO/IEC 27001 Certification:Accredited information security frameworks unlock enterprise partnership channels and institutional advertising budgets currently inaccessible to uncertified competitors.
- Video-First Interface Convergence:Synchronous streaming technology integration with asynchronous matching algorithms is enabling premium tier differentiation through real-time chemistry assessment.
Industry Challenges
- Machine Learning Talent Scarcity:Recommendation system engineers with production-scale behavioral modeling experience command compensation premiums that strain mid-cap platform R&D budgets.
- Age-Verification Infrastructure:Emerging mandates from the UK's Online Safety Bill and similar frameworks require biometric or document-based validation systems with unproven technical reliability at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Dating Services Market |
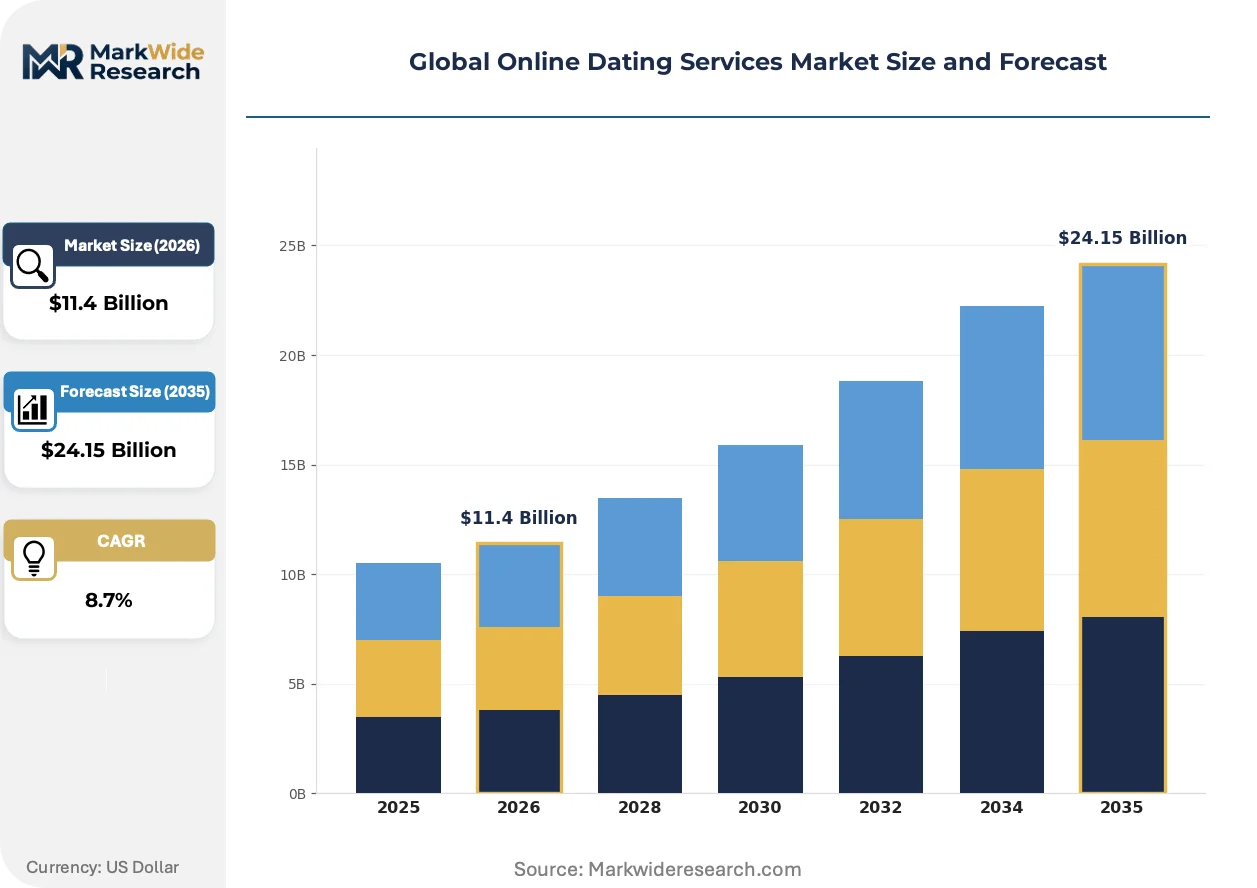
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Free Services, Subscription Services, Premium Features, Niche Platforms User Demographics: Young Adults, Seniors, Professionals, LGBTQ+ Matchmaking Method: Algorithmic Matching, Manual Matching, Group Events, Speed Dating Device Type: Mobile Apps, Websites, Desktop Applications, Social Media Integration |
| Companies Covered | Match Group, Bumble Inc, The Meet Group, eHarmony, Grindr LLC, Spark Networks, Happn SAS, Hinge, Coffee Meets Bagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Dating Services Market Strategic Shifts
Generative artificial intelligence is reshaping user interface design and content moderation workflows across online dating platforms. Three distinct vectors of technical and behavioral change are compressing competitive differentiation cycles.
Large language model-powered conversation assistance is bifurcating the user experience landscape. Premium subscribers gain access to real-time messaging suggestions and icebreaker generation, while free-tier users face degraded organic interaction quality. Young male demographics in the United States and United Kingdom are adopting these tools fastest, creating engagement asymmetries that platforms must architect around.
The European Union's Digital Services Act imposes algorithmic transparency requirements on content ranking and recommendation systems. Dating platforms must now disclose primary ranking parameters and provide alternative chronological feed options. This regulatory pressure concentrates compliance burden on smaller operators lacking dedicated policy infrastructure, advantaging scaled incumbents with Brussels lobbying capacity.
Subscription fatigue is compressing free-to-paid conversion timelines as users consolidate recurring charges. Platforms are responding with microtransaction-based feature unlocking and advertising-supported tiers that were previously deprioritized. This behavioral shift is most pronounced in Germany and France, where household subscription density across digital services has reached saturation thresholds.
Global Online Dating Services Market Segmentation
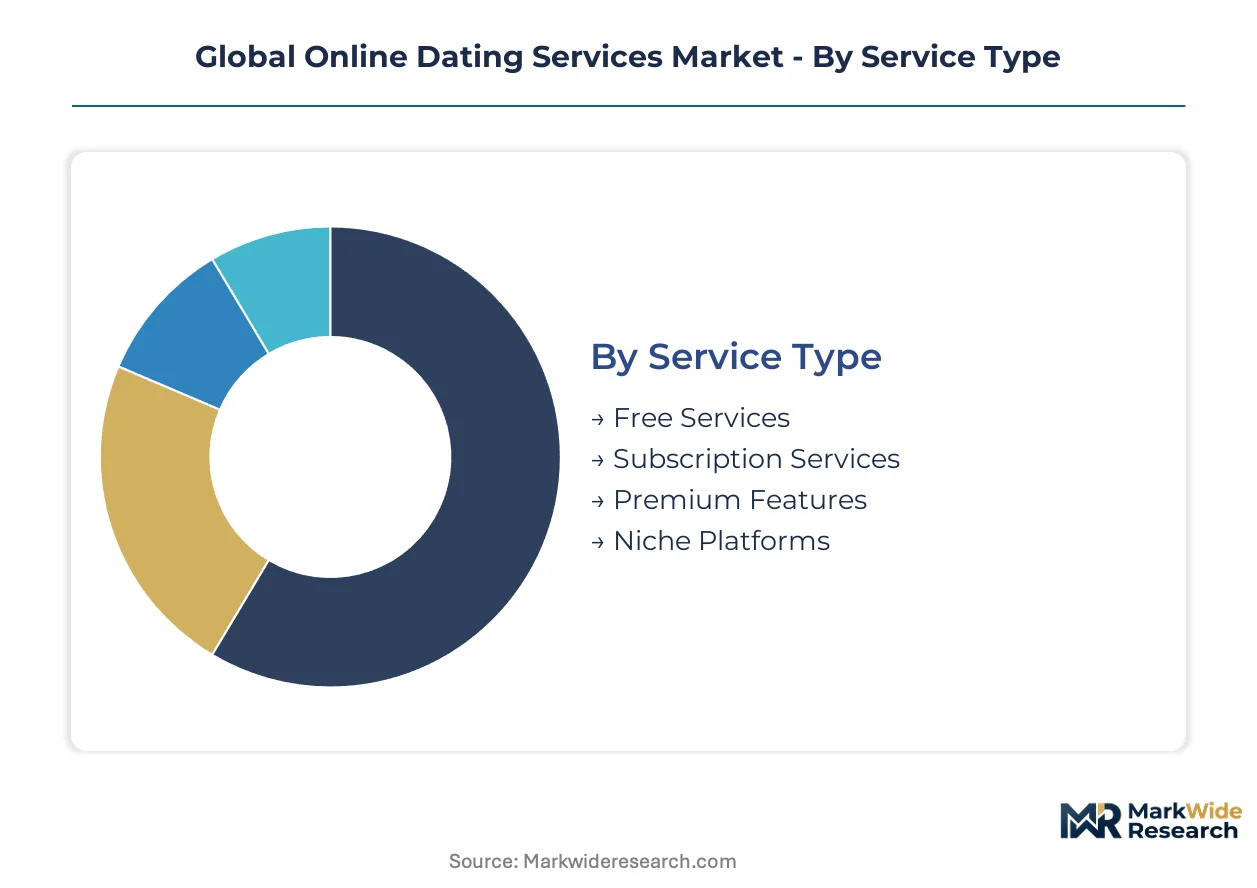
Segmentation in online dating services determines monetization architecture and compliance exposure. Service type influences recurring revenue stability, while demographics shape feature development roadmaps and regulatory scrutiny intensity across jurisdictions.
Service Type:
GDPR consent frameworks and FTC subscription disclosure rules create divergent compliance burdens across monetization models, with recurring billing systems facing heightened audit intensity.
- Subscription Services:Recurring revenue engines with tiered access to advanced filtering, unlimited messaging, and profile visibility boosts. Demand concentrates among professionals in the United States and Germany where household digital subscription density supports premium willingness-to-pay, though churn management costs escalate as competition intensifies.
- Free Services:Advertising-supported models with limited daily swipes and delayed match reveals. Young adults in India and Brazil drive volume here, constrained by advertiser CPM compression and iOS privacy framework limitations on targeted inventory.
- Premium Features:Microtransaction unlocks for one-time boosts, read receipts, and incognito browsing modes.
- Niche Platforms:Vertically specialized interfaces targeting religious affiliation, specific hobbies, or professional credential matching.
Established volume favors Subscription Services; emerging adoption favors Premium Features.
User Demographics:
Cost tier differentiation separates high-lifetime-value professionals from price-sensitive young adult cohorts with divergent feature expectations.
- Young Adults:Mobile-native users aged 18-25 prioritizing gamified interfaces and social authentication. Demand clusters in urban India, Brazil, and Indonesia where smartphone penetration outpaces subscription saturation, with session frequency driven by push-notification optimization and viral referral mechanics.
- Professionals:Time-constrained users aged 30-45 seeking efficiency-oriented matching with verified income and education credentials. Concentrated in London, New York, and Singapore where career density supports premium tier conversion, constrained by work-hour limitations on engagement depth.
- Seniors:Users aged 55+ requiring simplified navigation and enhanced safety protocols.
- LGBTQ+:Identity-specific matching with enhanced privacy controls and community verification systems.
Revenue concentration anchors Professionals; steepest expansion trajectory sits with Young Adults.
Matchmaking Method:
Application maturity separates algorithmic infrastructure investments from experiential event economics with divergent capital intensity profiles.
- Algorithmic Matching:Machine learning inference systems processing behavioral telemetry, preference taxonomies, and cross-platform interaction signals. Deployed most extensively by platforms serving the United States and United Kingdom, where GPU inference costs and ML engineering talent scarcity compress margins for mid-tier operators.
- Manual Matching:Human-curated introductions with profile review and personalized pairing services. Persists in Japan and South Korea where concierge-oriented service expectations support premium pricing, though scalability constraints limit addressable market breadth.
- Group Events:Organized social gatherings with facilitated introductions at venues.
- Speed Dating:Time-compressed rotational meeting formats with post-event matching systems.
Technology investment concentrates in Algorithmic Matching; experiential differentiation sustains Manual Matching.
Device Type:
Customer engagement patterns separate persistent connectivity models from session-based desktop experiences with divergent notification architecture requirements.
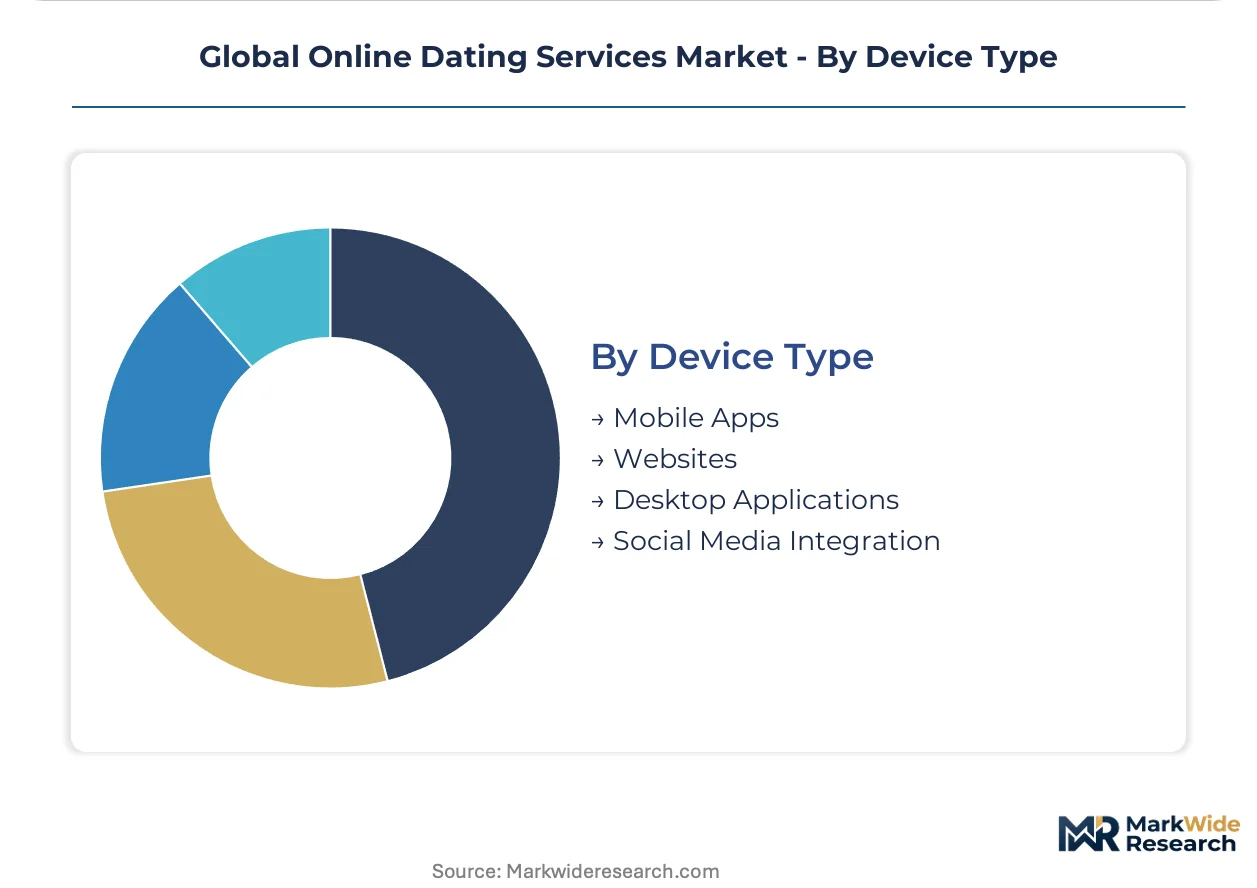
- Mobile Apps:Native iOS and Android applications with geolocation services, camera integration, and real-time push notifications. Dominates in China, India, and Nigeria where smartphone-first internet access is standard, with session frequency amplified by biometric authentication and frictionless payment integration.
- Social Media Integration:Embedded dating functionality within existing platform ecosystems. Expanding most quickly in Southeast Asia where super-app consolidation reduces standalone application adoption friction, constrained by platform dependency risks and data sharing governance.
- Websites:Browser-based responsive interfaces with reduced feature parity.
- Desktop Applications:Downloaded software with enhanced profile editing and photo management tools.
Engagement gravity centers on Mobile Apps; emerging integration favors Social Media Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in urban centers drive subscription conversion across mature markets, while smartphone-first adoption expands the addressable base in emerging economies. Platform localization requirements and divergent data protection regimes are fragmenting operational architectures. Regulatory compliance costs now separate scalable incumbents from constrained challengers.
United States
Time-constrained professionals aged 30-45 in New York and Los Angeles sustain premium tier willingness-to-pay through verified credential features. The Federal Trade Commission polices subscription disclosure practices and romance scam liability with escalating enforcement intensity. Silicon Valley technical talent clusters concentrate machine learning engineering resources for algorithmic matching infrastructure.
Germany
Household subscription density across digital services has reached saturation thresholds in Berlin and Munich, compressing free-to-paid conversion timelines. GDPR consent architecture and data portability mandates elevate operational compliance costs above mid-tier platform break-even levels. Hamburg hosts emerging platform policy infrastructure addressing algorithmic transparency requirements.
China
Smartphone-first internet access standardizes mobile-native engagement patterns among young adults in Shanghai and Shenzhen. The Personal Information Protection Law imposes server residency requirements that fragment technical infrastructure across jurisdictional boundaries. Beijing regulatory clarity on data processing restrictions shapes platform architecture decisions for domestic operators.
India
Urban young adults in Mumbai and Bangalore drive volume expansion where smartphone penetration outpaces subscription saturation. The Digital Personal Data Protection Act introduces localization and processing restrictions requiring domestic server infrastructure investment. Hyderabad technical clusters support behavioral analytics engine development for regional platform adaptation.
Brazil
Push-notification optimization and viral referral mechanics amplify session frequency among young adults in São Paulo and Rio de Janeiro. General Data Protection Law enforcement patterns remain less prescriptive than European equivalents, reducing compliance friction for foreign platform entry. São Paulo hosts Latin American headquarters for scaled international operators.
Global Online Dating Services Market Competitive Environment
Player mix skews toward portfolio conglomerates with cross-platform retention economies and single-brand specialists with differentiated interface architectures. Market structure concentrates around scaled incumbents with diversified revenue streams and emerging challengers with demographic-specific positioning. Strategic archetypes include women-first interface designers, LGBTQ+-focused community builders, and religious or professional vertical specialists. Dominant competitive moves encompass ISO/IEC 27001 certification pursuit for enterprise channel access and video-first interface convergence for premium tier differentiation.
Within the portfolio conglomerate tier, Match Group exemplifies cross-platform user retention economies spanning multiple branded interfaces. Bumble Inc occupies a differentiated position through women-first architecture that commands brand recognition in saturated North American and European markets. Grindr LLC anchors the LGBTQ+-focused specialist archetype with community verification systems and enhanced privacy controls. These three entities represent distinct strategic postures: portfolio breadth, interface differentiation, and vertical community depth.
| Leading Market Players |
|---|
| Match Group |
| Bumble Inc |
| The Meet Group |
| eHarmony |
| Grindr LLC |
| Spark Networks |
| Happn SAS |
| Hinge |
| Coffee Meets Bagel |
| Others |
Value Chain & Pricing Dynamics
Cloud compute capacity utilization at hyperscale providers anchors margin structures across the online dating services value chain, compressing price floors for mid-tier platforms while enabling premium tier differentiation through GPU-intensive inference services. This scale concentration shapes both upstream infrastructure procurement and downstream subscription pricing architecture.
Pricing Analysis
Cost-plus contracts with cloud infrastructure providers indexed to NVIDIA GPU availability and regional electricity tariffs dominate platform operating economics. Three-tier pricing structure across premium, standard, and economy levels separates unlimited algorithmic matching from capped daily interactions and advertising-supported free tiers. Price differentiation hinges on verification credential depth and real-time video streaming integration. Pricing pressure stems from subscription fatigue in Germany and France where household digital service density has reached saturation. Young adults in India and Brazil exhibit highest price sensitivity; professionals in New York and London demonstrate lowest.
Supply Chain Analysis
Inventory lead times for GPU clusters and specialized ML accelerators have extended to 26-40 weeks, constraining platform scaling velocity and forcing capacity reservation commitments. Technical infrastructure concentrates in the United States, Ireland, and Singapore where hyperscale data center density supports low-latency inference. Raw material dependencies center on NVIDIA A100/H100 chips, high-bandwidth memory modules, and renewable energy certificates for carbon-neutral compute claims. Single-source vulnerability to TSMC fabrication capacity represents the dominant supply chain risk. Distribution runs through direct-to-consumer application stores with Apple and Google extracting platform fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Social audio platforms and interest-based community applications constitute the substitution threat that incumbent dating services must actively defend against through interface innovation and retention mechanics.
For Market Incumbents: Secure algorithmic matching differentiation through proprietary behavioral modeling investments that widen engagement quality gaps against manual-curation alternatives. Pursue ISO/IEC 27001 certification to unlock enterprise advertising channels currently inaccessible to uncertified competitors. Vertical integration into video streaming infrastructure reduces third-party latency dependencies for real-time chemistry assessment features. For New Entrants and Emerging Players: Anchor in Southeast Asian whitespace where Indonesia, Vietnam, and Philippines exhibit smartphone penetration depth with subscription service underpenetration. Target young adult demographics in urban India and Brazil with gamified interface architectures and viral referral mechanics that minimize customer acquisition costs. Deploy social media integration strategies that leverage super-app ecosystems to reduce standalone application friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with production-scale ML engineering teams and established GDPR compliance infrastructure over nascent entrants facing talent scarcity and regulatory fragmentation. Long-term viability rests on recurring revenue model durability and cross-platform retention economies rather than advertising-dependent free services. Acquisition target archetype: vertically specialized platforms with demographic-specific community depth and unexploited geographic expansion potential. Signal to watch: regulatory clarity on age-verification mandates as technical reliability thresholds reshape platform architecture requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Matching Infrastructure Investment | Proprietary ML inference capabilities capture disproportionate user engagement against manual-curation systems. |
| ISO/IEC 27001 Certification Pursuit | Accredited data protection frameworks unlock enterprise partnership channels and institutional advertising budgets. |
| Video-First Interface Convergence | Synchronous streaming integration enables premium tier differentiation through real-time chemistry assessment. |
| Southeast Asia Geographic Expansion | Indonesia, Vietnam, and Philippines offer whitespace with low subscription saturation relative to smartphone depth. |
| Generative AI Conversation Assistance Deployment | LLM-powered messaging tools create engagement asymmetries that platforms must architect monetization around. |
Study Parameters
Operator-level perspectives from platform engineering directors, regulatory affairs leads, subscription product managers, and cloud infrastructure procurement specialists anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings, App Annie engagement metrics, hyperscaler capex disclosures, and GDPR enforcement tracking. Bottom-up segment sizing triangulated against top-down market aggregation across service type, demographic cohort, and matchmaking method dimensions.
Sensitivity analysis around GPU pricing volatility and regulatory compliance cost trajectories informed projection boundaries across the analysis window. Segmentation modeling incorporated service tier, user age cohort, device type, and geographic jurisdiction dimensions. CAGRs derived from trend extrapolation of subscriber growth, ARPU evolution, and churn rate assumptions. Industry-specific forecast inputs included smartphone penetration curves, data localization mandate implementation timelines, and machine learning talent supply elasticity.
Material uncertainties — regulatory fragmentation acceleration, substitution platform traction, and cloud infrastructure pricing shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding GDPR enforcement intensity and young adult demographic expansion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Utility Cases Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
System Integration Market
Digital Solutions
Digital Fitness Apps Market