
 Construction Simulation Software Market | 2026-2036
Construction Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Simulation Software Market Insights
Cloud-native computational engines is rewriting how construction teams prototype structural behavior before physical commitment. Autodesk Revit anchors the ecosystem through deep integration with architectural design workflows. Procore Technologies extends its position by embedding simulation modules directly within project management dashboards. Oracle Aconex competes through enterprise-grade data governance that satisfies owner-operator audit requirements.
Construction simulation software encompasses digital tools that apply finite element analysis, physics-based rendering, and parametric modeling to forecast building performance under load, weather, and schedule constraints. These platforms process geometric data, material properties, and environmental variables to generate predictive visualizations that reduce rework and safety incidents. Cloud-based deployment captures the fastest expansion as general contractors abandon on-premise server maintenance for elastic compute capacity. Among applications, infrastructure projects generate the deepest simulation complexity due to geotechnical variability and extended asset lifecycles. 3D modeling retains the largest revenue pool, though risk analysis modules command premium pricing from insurers and bond underwriters.
The EU Green Deal and F-Gas Regulation shape product roadmaps by mandating lifecycle carbon accounting that simulation software must validate. OSHA workplace safety directives in the United States accelerate demand for virtual hazard rehearsal before crews enter active sites. Stakeholders should track how building codes in Germany and Japan evolve their digital submission requirements, as these jurisdictions typically prefigure standards that propagate through ISO frameworks.
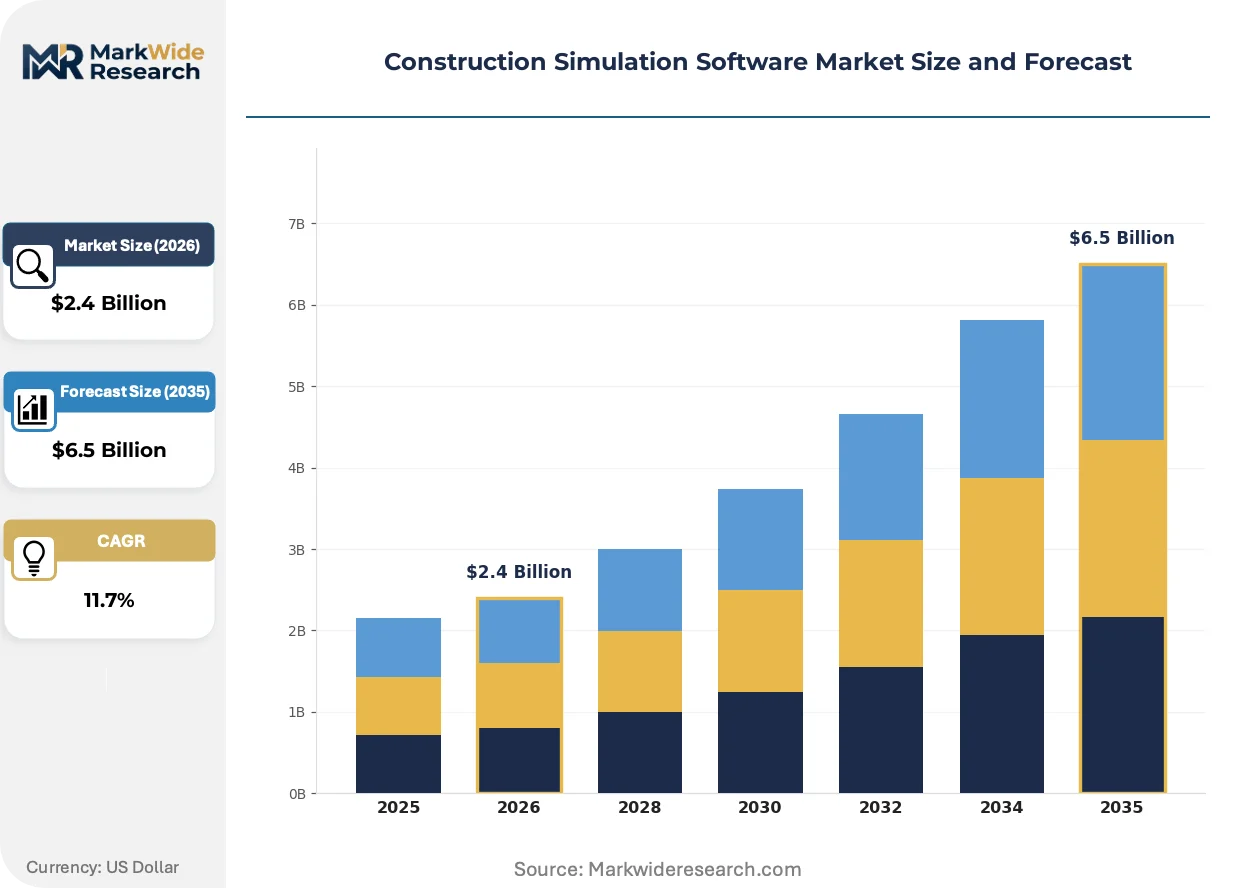
Market Dynamics
Cloud-native computational engines are compressing the pre-construction planning cycle from months to weeks, forcing general contractors to restructure project workflows around elastic compute capacity rather than fixed on-premise infrastructure.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Builders across Germany, France, and the Netherlands must model material lifecycle impacts before permitting, embedding simulation into standard project workflows.
- Infrastructure asset longevity requirements:Bridge and tunnel projects now demand century-scale performance forecasting, driving adoption of geotechnical and structural simulation modules.
- OSHA virtual hazard rehearsal directives:United States contractors deploy site-specific safety simulations to satisfy workplace safety pre-qualification requirements before crew deployment.
Market Restraints
- Elastic compute cost volatility:Cloud processing fees for finite element analysis fluctuate with energy markets, squeezing margin predictability for mid-sized engineering consultancies.
- Geographic talent concentration:Simulation-specialist civil engineers cluster in Stuttgart, Munich, and Düsseldorf, creating recruitment bottlenecks for projects outside German-speaking regions.
- Legacy BIM format incompatibility:Proprietary file structures from early 2010s building information modeling systems resist direct import into modern physics engines.
Strategic Opportunities
- Japan's digital submission pathway expansion:METI's evolving building code digitization creates first-mover advantage for platforms certifying JIS-compliant automated compliance checking.
- Parametric modeling-AI convergence:Generative design algorithms integrated with structural simulation enable real-time optioneering that compresses schematic design phases.
- Insurer risk-modeling partnerships:Bond underwriters seek direct API access to project simulation data, opening subscription revenue streams beyond traditional software licensing.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Wind load and thermal bridge simulation requires specialized physics knowledge that civil engineering curricula rarely emphasize.
- Multi-stakeholder data governance friction:Owner-operators, architects, and contractors dispute liability for simulation input accuracy, delaying project kickoffs.
- ISO 19650 certification timeline compression:Firms race to qualify information management processes before public procurement mandates take effect in core European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Simulation Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Project Management, Cost Estimation, Risk Analysis End User: Architects, Engineers, Contractors, Project Managers Deployment: On-Premise, Cloud-Based, Hybrid, Dedicated Server Application: Residential, Commercial, Infrastructure, Industrial |
| Companies Covered | Allplan, Buildertrend, Procore Technologies, Jonas Construction Software, eSUB, Autodesk Revit, Planera, Oracle Aconex, Navisworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Simulation Software Market Trends and Innovations
Digital twin workflows are migrating from post-construction asset management into pre-construction decision support, compressing the feedback loop between design intent and performance prediction.
Real-time rendering engines are digitizing how structural behavior is communicated to non-technical stakeholders. Engineering consultancies in Germany and Japan deploy these tools during municipal review meetings to accelerate permitting timelines. The compression of visualization production cycles is lowering the threshold for simulation inclusion in early-stage proposals.
The F-Gas Regulation's lifecycle refrigerant tracking requirements are forcing HVAC simulation modules to integrate embodied carbon databases. Equipment manufacturers must now certify thermal performance predictions against actual operational data. This regulatory pressure is most acute in French and Nordic markets where municipal climate plans predate EU-wide implementation.
Subscription-based access models are displacing perpetual licenses among mid-sized contractors. German regional builders now procure simulation capacity through project-specific credits rather than enterprise agreements. This consumption-pattern shift favors platforms with granular usage metering and rapid onboarding protocols.
Construction Simulation Software Market Segmentation
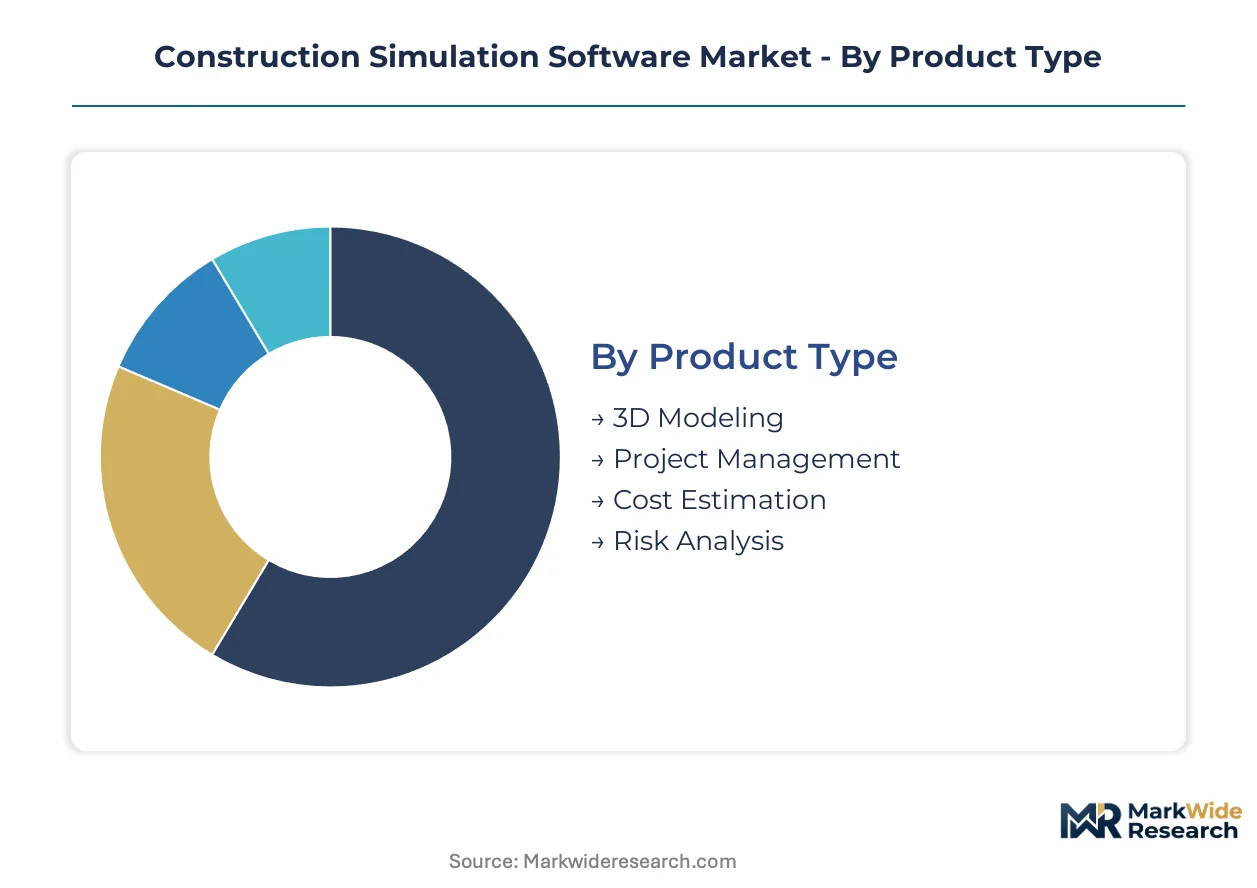
Construction simulation software segments reflect divergent technical requirements across project phases and stakeholder workflows. Procurement patterns vary sharply between design-stage architects and execution-focused contractors, while deployment preferences split along IT infrastructure maturity lines.
Product Type:
Cost tier differentiation separates entry-level visualization tools from premium physics engines that command enterprise budgets.
- 3D Modeling:Parametric geometry engines process architectural intent into structural meshes for finite element analysis. German civil engineering firms embed these tools into municipal bridge submissions to satisfy century-scale performance forecasting mandates.
- Risk Analysis:Probabilistic simulation modules quantify schedule overrun and cost variance exposure. Bond underwriters in France and the Netherlands require these outputs for infrastructure project surety underwriting.
- Project Management:Schedule compression algorithms integrate critical path analysis with resource loading constraints.
- Cost Estimation:Quantity takeoff automation links geometric data to material pricing databases for bid preparation.
3D modeling commands the established base. The steepest expansion runs through risk analysis.
End User:
Customer type determines feature prioritization, with architects demanding visualization fidelity while contractors prioritize field logistics integration.
- Contractors:Field execution platforms merge simulation output with procurement and crew scheduling systems. Hochtief and Strabag mandate these capabilities across their European project portfolios to compress pre-construction planning cycles.
- Engineers:Structural analysis specialists require geotechnical and wind load modules for bridge and tunnel design. Talent scarcity in computational fluid dynamics creates recruitment bottlenecks for consultancies outside Stuttgart and Munich.
- Architects:Design-phase visualization tools emphasize real-time rendering for client presentations and municipal review meetings.
- Project Managers:Cross-functional coordination platforms aggregate simulation inputs from multiple technical disciplines.
Contractors anchor current revenue concentration. Architects are gaining share fastest as real-time rendering lowers simulation inclusion thresholds in early-stage proposals.
Deployment:
Volume distribution tracks IT infrastructure maturity, with elastic compute adoption accelerating among mid-sized engineering consultancies.
- Cloud-Based:Elastic computational engines eliminate on-premise server maintenance overhead. German regional builders now procure simulation capacity through project-specific credits rather than enterprise agreements.
- Hybrid:Split architectures retain sensitive geotechnical data on local infrastructure while offloading rendering workloads to cloud instances. This configuration dominates French and Nordic markets where municipal climate plans impose strict data residency requirements.
- On-Premise:Perpetual license models persist among owner-operators with dedicated IT security teams.
- Dedicated Server:Single-tenant infrastructure serves defense and critical infrastructure projects with classified design parameters.
On-premise retains the legacy installed base. Cloud-based deployment climbs the fastest as general contractors abandon fixed infrastructure for consumption-based models.
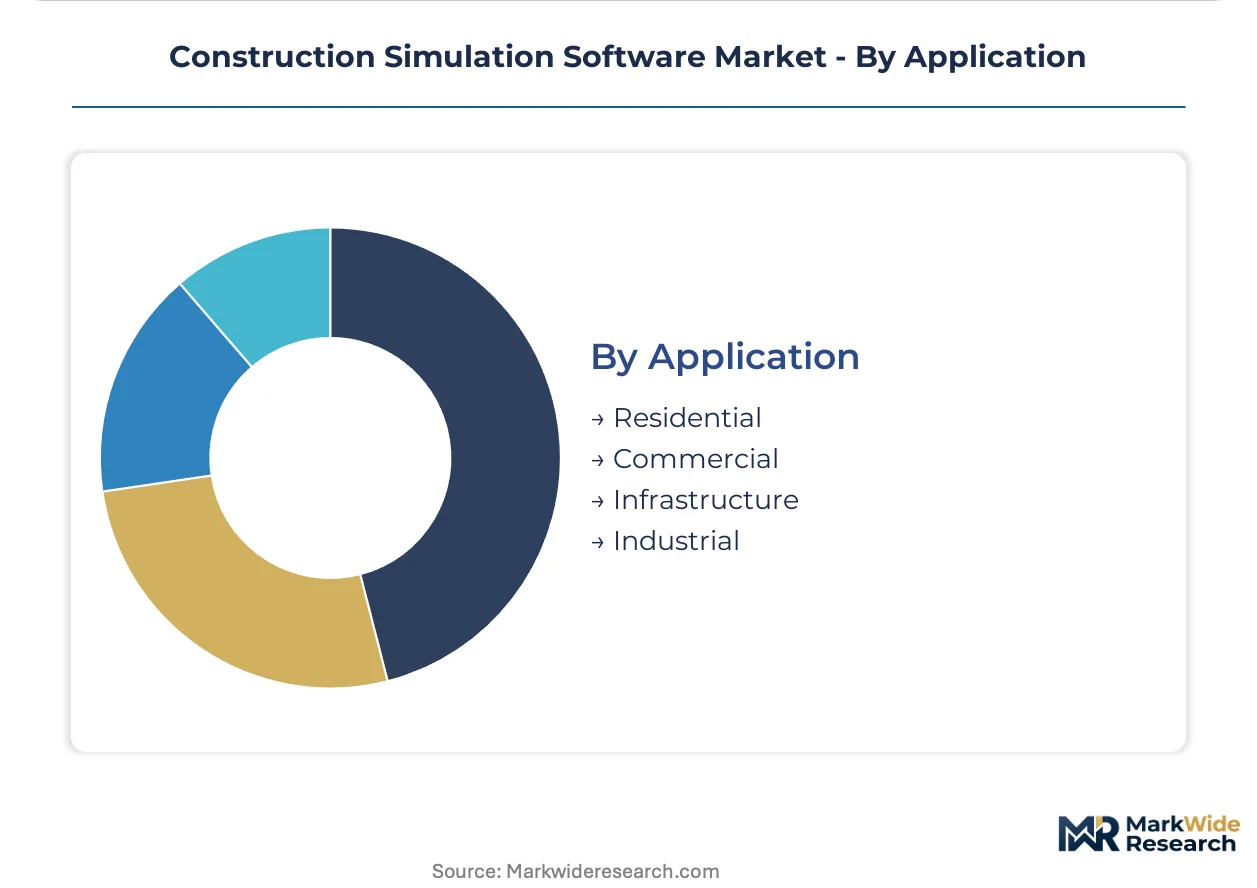
Application:
Application scope dictates simulation complexity, with infrastructure projects demanding century-scale asset performance forecasting.
- Infrastructure:Bridge and tunnel projects integrate geotechnical variability, seismic loading, and extended lifecycle analysis. EU Green Deal embodied-carbon disclosure rules mandate material impact modeling before permitting in Germany, France, and the Netherlands.
- Commercial:High-rise and mixed-use developments emphasize HVAC thermal bridge simulation under F-Gas Regulation lifecycle refrigerant tracking requirements.
- Residential:Single-family and multi-family projects prioritize cost estimation accuracy and construction sequencing optimization.
- Industrial:Manufacturing facilities and process plants require specialized modules for equipment vibration and hazardous material containment.
Infrastructure commands premium pricing and deepest technical requirements. Commercial applications expand most quickly as urban density intensifies across European metropolitan corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction simulation software demand concentrates in export-oriented economies with advanced infrastructure sectors, while import-dependent markets rely on cloud licensing to bypass capital expenditure barriers. Trade in digital engineering services now exceeds physical construction equipment flows between Germany and Gulf Cooperation Council states.
United States
Federal infrastructure spending and OSHA workplace safety directives drive adoption among general contractors. The Infrastructure Investment and Jobs Act mandates digital project delivery standards for bridge and highway awards. Engineering consultancies cluster in Houston and Chicago, where firms embed simulation modules into municipal pre-qualification submissions.
Germany
EU Green Deal embodied-carbon disclosure rules force builders to model material impacts before permitting. Hochtief and Strabag mandate simulation-driven planning across European portfolios. Stuttgart and Munich host dense concentrations of computational fluid dynamics specialists serving bridge and tunnel projects.
Japan
METI building code digitization creates first-mover opportunities for automated compliance checking platforms. Century-scale asset performance requirements dominate infrastructure procurement. The Kanto region around Tokyo anchors demand for seismic load simulation and geotechnical analysis modules.
France
F-Gas Regulation lifecycle refrigerant tracking forces HVAC simulation integration with embodied carbon databases. Municipal climate plans in Paris and Lyon predate EU-wide implementation, accelerating vendor certification requirements. Bond underwriters in Lyon require probabilistic risk analysis outputs for infrastructure surety.
United Arab Emirates
Mega-project scale and compressed delivery timelines compress pre-construction planning cycles to weeks. Owner-operators in Dubai mandate digital twin workflows for asset handover compliance. Abu Dhabi-based engineering procurement firms procure cloud simulation credits for project-specific elasticity.
Construction Simulation Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Enterprise suites anchor the premium segment through deep BIM integration and owner-operator audit compliance. Mid-market platforms compete on rapid onboarding and consumption-based pricing. Niche specialists command premium fees for geotechnical and computational fluid dynamics modules. Dominant competitive moves include strategic API partnerships with insurers and bond underwriters, plus backward integration into cloud infrastructure to control compute cost volatility.
Among design-originated platforms, Autodesk Revit and Navisworks exemplify the ecosystem-anchor archetype through parametric geometry engine dominance. Procore Technologies and Oracle Aconex occupy the project-management-integrated tier, embedding simulation outputs directly within contractor dashboards. Allplan represents the European specialist position with municipal submission compliance depth in German-speaking markets.
| Leading Market Players |
|---|
| Allplan |
| Buildertrend |
| Procore Technologies |
| Jonas Construction Software |
| eSUB |
| Autodesk Revit |
| Planera |
| Oracle Aconex |
| Navisworks |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp corridor freight costs for specialized compute hardware shipments shape margin structures across German engineering consultancies and French HVAC simulation vendors, compressing price differentiation between cloud-native platforms and legacy on-premise installations while amplifying regional procurement advantages for Benelux-based resellers.
Pricing Analysis
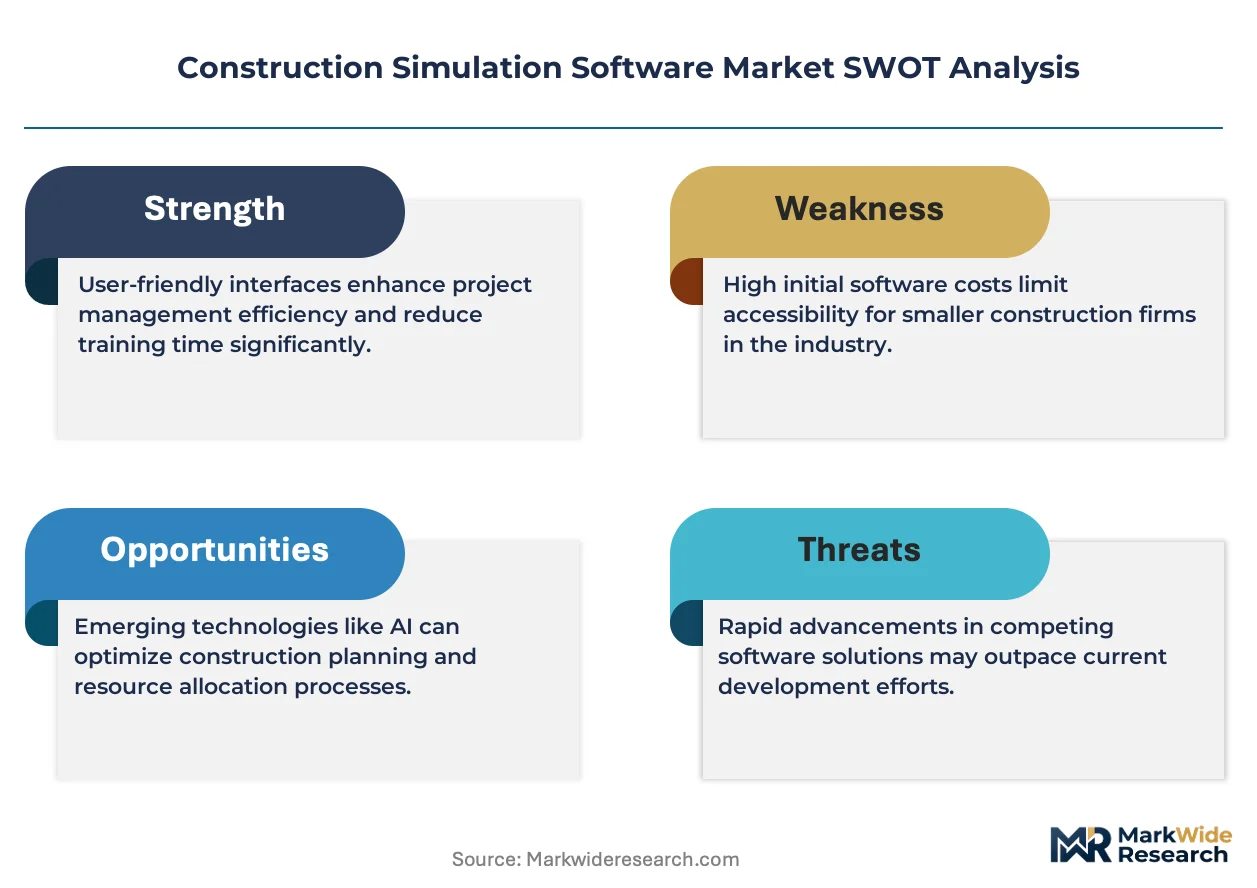
Next-generation AI-integrated simulation modules command 40-60% subscription premiums over current-generation cloud-native engines, while prior-generation perpetual-license tools face accelerating price erosion as German regional builders abandon fixed infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade BIM-integrated suites from mid-market project-based credits and entry-level visualization tools. Price differentiation hinges on ISO 19650 certification tier and embedded carbon validation capabilities. Pricing pressure stems from elastic compute cost volatility squeezing mid-sized engineering consultancies. Contractors with thin pre-construction margins exhibit highest price sensitivity; owner-operators with dedicated compliance teams show lowest.
Supply Chain Analysis
Cloud infrastructure provisioning concentrates among hyperscale data center operators in Ireland, Germany, and the Netherlands, with specialized GPU clusters anchoring in Frankfurt and Amsterdam for low-latency finite element processing. Software development draws from Estonian and Polish engineering talent pools for computational geometry modules, while visualization engine components source from Japanese and South Korean rendering specialists. Supply chain risk centers on single-source vulnerability for computational fluid dynamics solver libraries. Distribution runs through Autodesk and Procore partner networks for enterprise accounts, with direct SaaS procurement dominating mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction simulation software sits in early-cycle expansion as EU Green Deal embodied-carbon mandates force simulation into standard permitting workflows across Germany, France, and the Netherlands, accelerating penetration beyond traditional infrastructure verticals.
For Market Incumbents: Pre-empt margin compression in mid-market cloud tiers by backward integration into dedicated GPU cluster infrastructure in Frankfurt and Amsterdam, reducing elastic compute cost exposure. Anchor enterprise retention through ISO 19650 certification automation that accelerates compliance timelines for Hochtief and Strabag procurement requirements. Defend against generative design insurgents by embedding real-time optioneering APIs directly into municipal submission portals. For New Entrants and Emerging Players: French regional construction markets outside Paris exhibit pronounced underpenetration for HVAC-integrated carbon simulation tools, creating white-space for F-Gas Regulation-compliant modules. Target Japanese prefectural governments beyond Tokyo-Kanto for METI digital submission pathway certification, where localized seismic analysis requirements resist incumbent standardization. Pursue insurer API partnerships as primary go-to-market channel, offering bond underwriters direct simulation data access for infrastructure surety pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized computational fluid dynamics boutiques with captive Stuttgart or Munich talent pools, as wind load and thermal bridge expertise scarcity intensifies acquisition premiums. Long-term viability hinges on regulatory compliance automation depth rather than visualization fidelity. Target acquisition archetype: geotechnical simulation specialists with century-scale infrastructure forecasting credentials. Signal to watch: JIS-compliant automated compliance checking certification timelines from METI.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding simulation modules within Procore and Oracle Aconex dashboards compresses contractor onboarding cycles. |
| Acquisition of Specialist Firm | Computational fluid dynamics boutiques in Stuttgart command premiums as wind load expertise scarcity intensifies. |
| Strategic Partnership | API agreements with French and Dutch bond underwriters unlock subscription revenue beyond traditional licensing. |
| Geographic Expansion | METI digital submission pathway certification creates first-mover advantage in Japanese prefectural markets. |
| Product Launch | Real-time generative design algorithms integrated with structural simulation compress schematic design phases. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs at German civil engineering firms, IT procurement officers at French general contractors, platform engineers at cloud infrastructure providers, and integration specialists at BIM consultancy practices; and secondary validation against SEC filings from Autodesk and Procore, EU Green Deal implementation trackers, METI building code digitization announcements, and ISO 19650 certification registries. Bottom-up triangulation of project-level simulation procurement patterns with top-down market sizing from vendor revenue disclosures anchored volume estimates.
Forecast inputs span deployment model transitions from on-premise to cloud-native architectures, organization size tiering from regional builders to multinational contractors, vertical segmentation across infrastructure and commercial applications, integration complexity levels for BIM-embedded versus standalone modules, and regional adoption patterns reflecting EU Green Deal enforcement intensity. CAGRs were derived from elasticity modeling of pre-construction planning cycle compression rates and cloud compute cost trajectories across the analysis window. Industry-specific inputs include embodied-carbon disclosure mandate rollout schedules and OSHA virtual hazard rehearsal directive implementation phases.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by hyperscale cloud providers or accelerated JIS certification timelines from METI would shift outcomes. Specific risk factors include computational fluid dynamics talent concentration bottlenecks in German-speaking regions and legacy BIM format incompatibility resistance from early-2010s system archives. Quarterly review of EU Green Deal enforcement variance across member states and METI digital submission pathway expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Visitor Identification Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Quality Management Software Market
Software & Services
Global App Design Software Market
Software & Services
Vertical Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Computer Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Automotive Design Software Market
Software & Services
HR Tech Market
Software & Services
Enterprise Software Market
Software & Services
Global Client Portal Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Data Governance Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
PCB Design Software Market