
 Data Extraction Market | 2026-2036
Data Extraction Market Size, Share, and Industry Trends Forecast 2026-2036
Data Extraction Market Analysis
Platform licensing revenue is narrowing as vendors shift toward consumption-based pricing for extraction workloads. IBM Corporation leverages its hybrid cloud architecture to anchor large enterprise deployments across regulated industries. Microsoft Corporation sustains competitive pressure through native integration with productivity suites and Azure data services. UiPath specializes in robotic process automation pipelines that embed extraction as a workflow step, occupying a distinct automation-centric niche.
Data extraction encompasses the automated identification, parsing, and transformation of structured and unstructured information from documents, databases, web sources, and streaming feeds into machine-readable formats using pattern-matching algorithms, API connectors, and natural language processing engines with throughput metrics often exceeding thousands of pages per hour. Its primary commercial purpose is to eliminate manual data entry, reduce processing latency, and enable downstream analytics, reporting, and decision systems. Machine learning and natural language processing segments are capturing disproportionate investment as enterprises prioritize semantic understanding over template-based parsing, while optical character recognition remains mature with compressed margins. Cloud-based and SaaS deployment modes are expanding fastest as IT departments abandon capital-intensive on-premises infrastructure.
The EU AI Act, HIPAA in the United States, and ISO 27001 standards collectively shape product requirements by mandating audit trails, data lineage documentation, and access controls that extraction platforms must embed by design. The Federal Risk and Authorization Management Program in the United States further constrains vendor eligibility for government contracts through security certification gates. Stakeholders must monitor how divergent national AI governance frameworks fragment compliance architectures and influence platform roadmap prioritization.
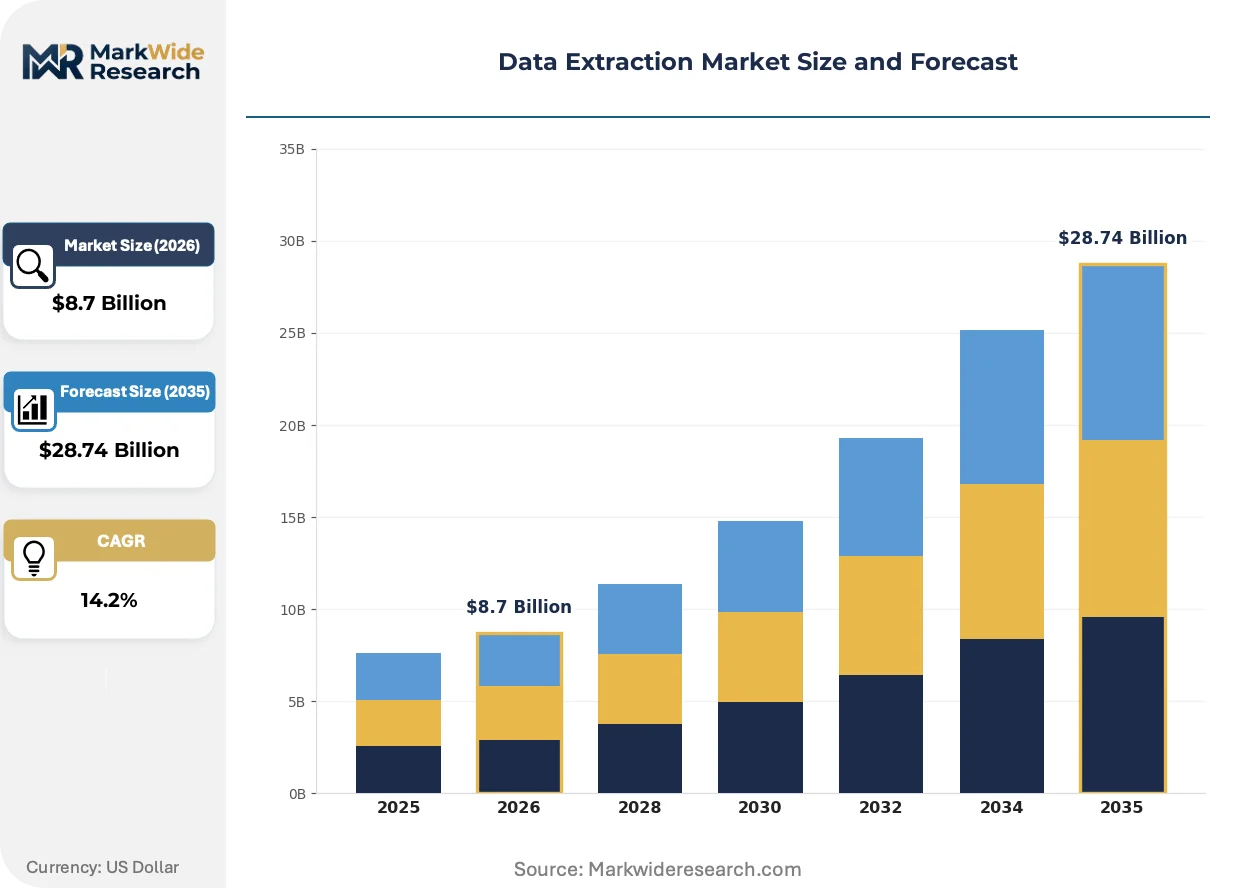
Market Dynamics
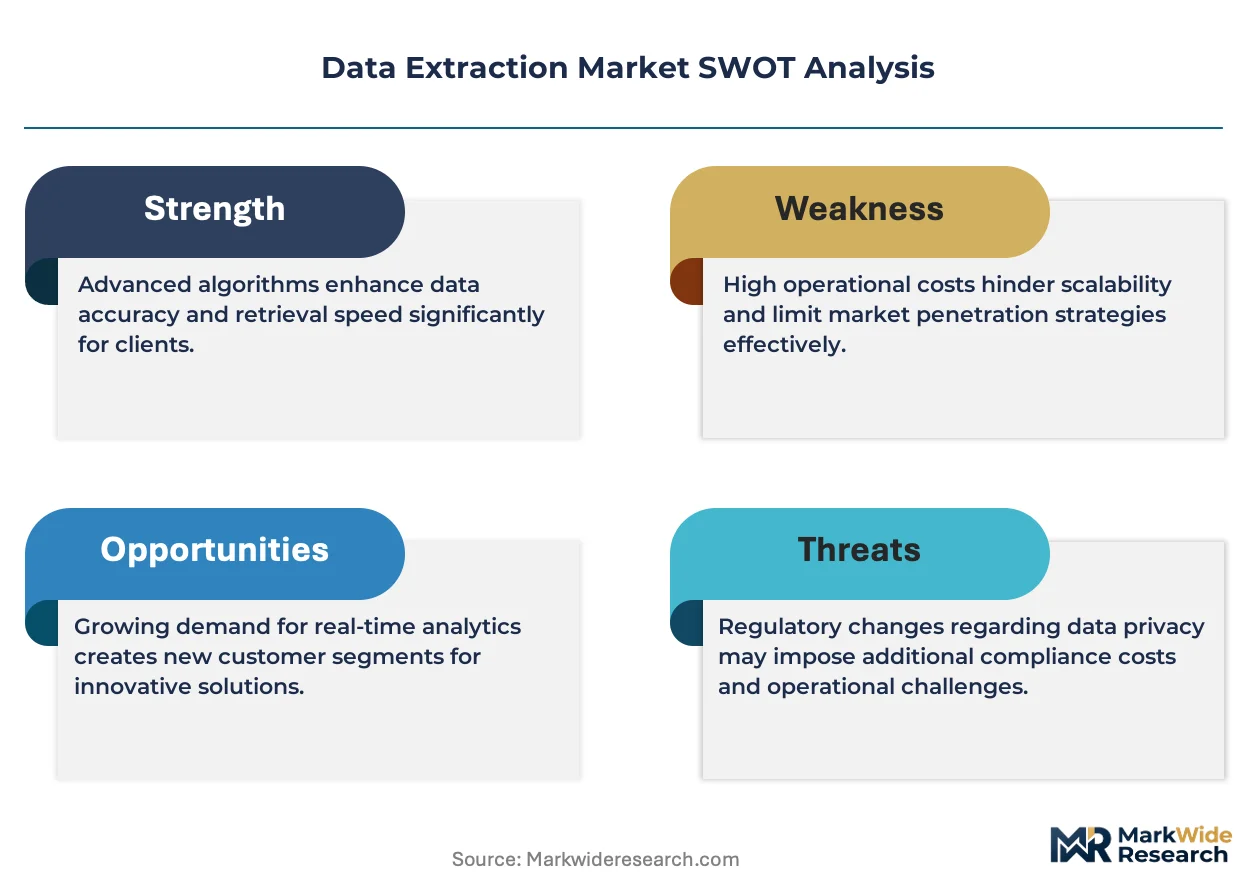
Healthcare providers are accelerating automated extraction tool adoption to process unstructured clinical records, while the EU AI Act's risk-based classification system forces vendors to rebuild compliance architectures from the ground up.
Growth Catalysts
- HIPAA audit mandates:US healthcare systems must maintain complete data lineage documentation, driving procurement of extraction platforms with embedded access controls and immutable audit trails.
- Unstructured clinical data volumes:Electronic health record proliferation generates petabytes of physician notes and imaging reports requiring automated parsing at throughput rates exceeding thousands of pages per hour.
- Federal IT modernization budgets:United States enterprise procurement of cloud-native extraction platforms concentrates demand as agencies retire legacy on-premises infrastructure under data governance mandates.
Market Restraints
- ISO 27001 certification costs:Small and mid-sized vendors face capital barriers to achieving information security management system accreditation required by regulated buyers.
- Optical character recognition margin compression:Mature OCR technology segments suffer from commoditized pricing as open-source alternatives erode proprietary solution value.
- Template-based parsing obsolescence:Rule-dependent extraction methods confront displacement by machine learning models, stranding technical debt in installed customer bases.
Strategic Opportunities
- EU AI Act compliance services:Vendors can capture recurring revenue by embedding automated risk classification and documentation workflows for European enterprise clients.
- Semantic understanding convergence:Natural language processing integration with robotic process automation pipelines creates differentiated workflow automation for financial services and legal sectors.
- Consumption-based pricing expansion:Metered extraction workloads replace perpetual licensing, aligning vendor revenue with customer value realization and reducing upfront procurement friction.
Industry Challenges
- NLP engineer scarcity:Recruitment of specialists capable of training domain-specific language models for clinical and legal document types constrains product roadmap velocity.
- Legacy system integration complexity:Mainframe and proprietary database connectors require custom development for each enterprise deployment, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Extraction Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Optical Character Recognition, Web Scraping Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, Finance, Healthcare, Telecommunications Application: Data Mining, Data Warehousing, Market Research, Automated Reporting |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP, Informatica, UiPath, Alteryx, Talend, Bright Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Extraction Market Emerging Trajectories
Machine learning and natural language processing segments are capturing disproportionate investment as enterprises prioritize semantic understanding over rigid template-based parsing methods.
Transformer-based large language models are rendering obsolete rule-dependent extraction systems that require pre-defined document templates. Healthcare networks and insurance payers are deploying these models for real-time clinical coding and claims processing. The shift is compressing implementation timelines from months to weeks while expanding addressable document types beyond structured forms.
REACH chemical substance registration requirements in Europe are mandating automated extraction of safety data sheet information across extended supply chains. Manufacturers must demonstrate automated data lineage from raw material certificates to finished product documentation. Chemical and pharmaceutical producers are responding by embedding extraction APIs directly into supplier onboarding portals.
Buyers are unbundling after-sales service contracts from platform licensing, preferring to source implementation and tuning expertise from specialized systems integrators. This channel fragmentation pressures vendor professional services margins while elevating the importance of certification programs for third-party deployment partners. The pattern is most pronounced in United States federal contracting, where FedRAMP authorization requirements create barriers to direct vendor-customer relationships.
Data Extraction Market Segmentation
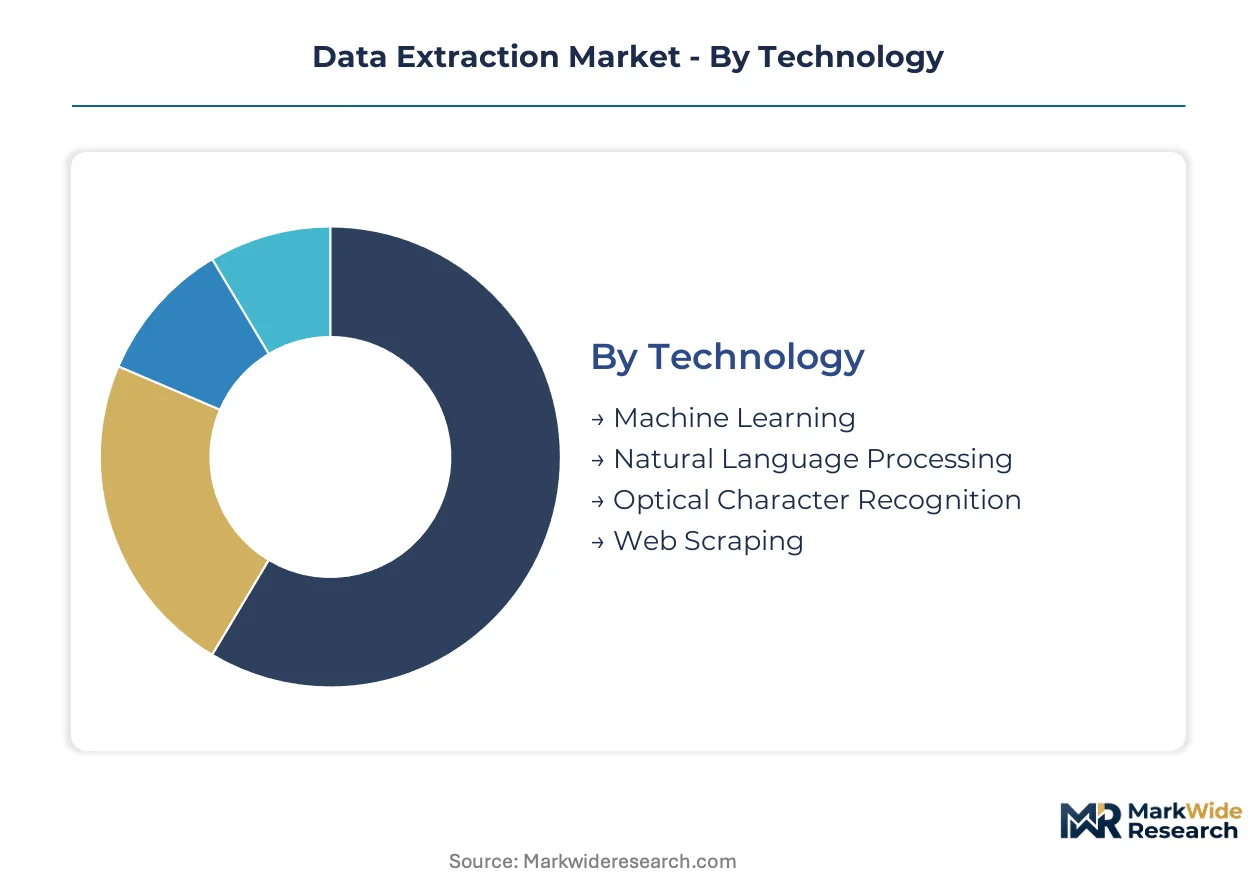
Technology choice determines extraction accuracy, latency, and total cost of ownership across document-intensive workflows. Deployment architecture shapes procurement cycles, with cloud-native platforms compressing implementation timelines against legacy on-premises installations. End-user verticals impose distinct compliance and throughput requirements that segment vendor specialization.
Technology:
Natural language processing and machine learning platforms refresh capabilities quarterly through model retraining, while optical character recognition and web scraping tools exhibit slower technical obsolescence cycles measured in years.
- Machine Learning:Pattern recognition engines trained on domain-specific document corpora enable extraction from unstructured formats without template configuration. Healthcare networks in the United States deploy these systems for clinical coding automation under HIPAA audit mandates requiring complete data lineage documentation.
- Natural Language Processing:Transformer-based architectures parse semantic relationships within text blocks, enabling entity extraction and relationship mapping from physician notes and legal contracts. Financial services procurement concentrates here for real-time regulatory filing automation.
- Optical Character Recognition:Mature image-to-text conversion technology with commoditized pricing pressure from open-source alternatives.
- Web Scraping:Automated HTML parsing and API-based data harvesting from public and authenticated web sources.
Optical character recognition dominates installed base across legacy document archives. Natural language processing is where expansion concentrates.
Deployment:
Cost tier structures separate capital-intensive perpetual licensing from metered consumption models that align vendor revenue with customer utilization patterns.
- Cloud-Based:Scalable infrastructure with pay-per-page pricing eliminates upfront hardware procurement. United States federal agencies drive demand here under IT modernization mandates retiring on-premises infrastructure.
- SaaS:Pre-configured extraction pipelines with embedded compliance controls and automatic security patching. Healthcare providers prefer this model for rapid deployment without internal DevOps resources.
- Hybrid:Sensitive data processing on-premises with burst capacity to cloud for peak workloads.
- On-Premises:Dedicated hardware deployments in air-gapped environments for classified or highly regulated data.
On-premises deployments anchor legacy financial services infrastructure. SaaS offerings are climbing the fastest as procurement teams prioritize operational expenditure over capital allocation.
End User:
Application complexity varies sharply across verticals, with healthcare and finance demanding the highest accuracy thresholds and audit trail granularity.
- Healthcare:Clinical record extraction with ICD-10 coding automation and imaging report parsing. HIPAA mandates for access controls and immutable audit trails drive platform selection criteria.
- Finance:Regulatory filing extraction, KYC document processing, and transaction monitoring data preparation. EU AI Act risk classification requirements reshape vendor compliance architectures for European deployments.
- Retail:Supplier onboarding documentation and competitive price monitoring through web scraping.
- Telecommunications:Customer service transcript analysis and network log parsing for operational intelligence.
Healthcare represents the fastest-growing trajectory as unstructured clinical data volumes expand. Retail maintains the largest installed base of legacy template-based systems.
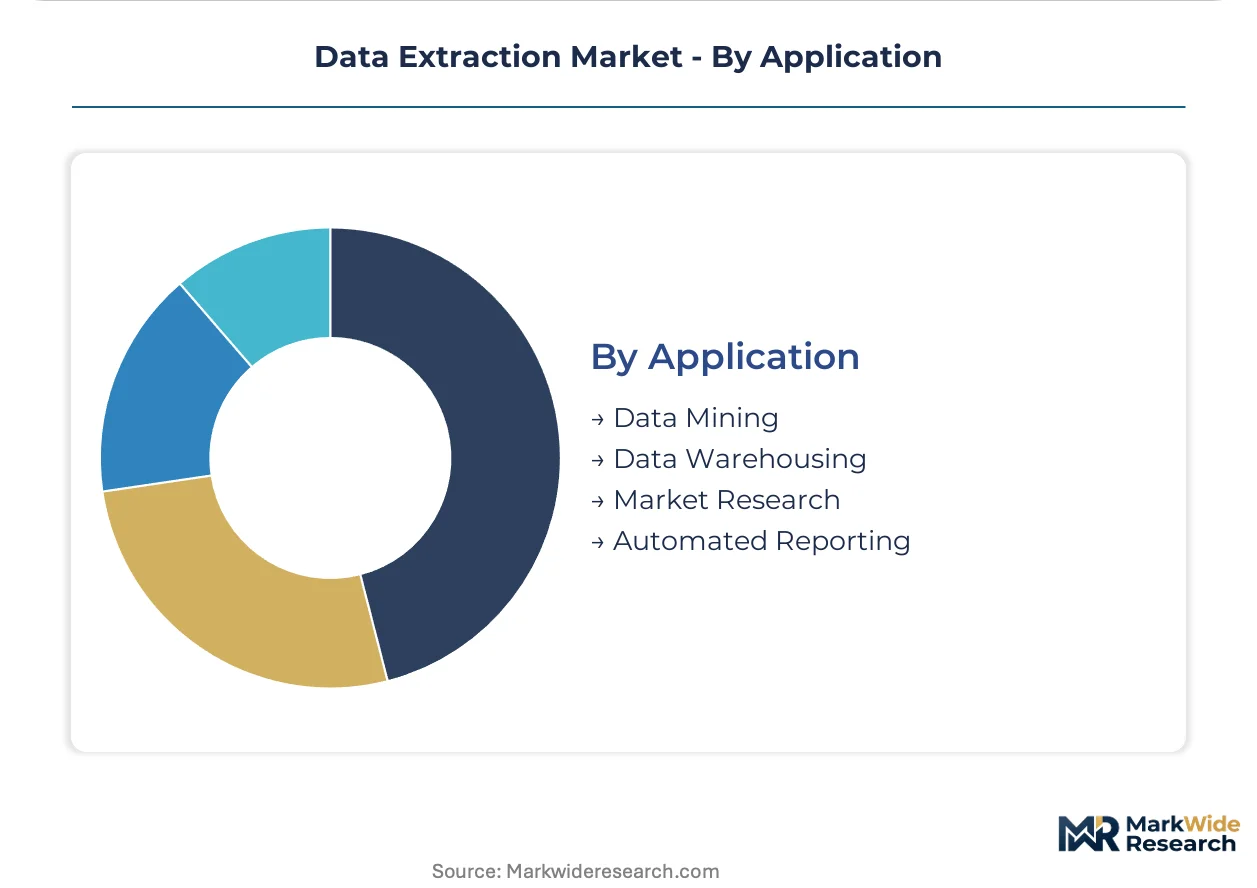
Application:
Volume concentration separates high-frequency automated reporting from episodic market research engagements with irregular procurement patterns.
- Automated Reporting:Scheduled extraction pipelines feeding business intelligence dashboards and regulatory submission workflows. United States federal contractors deploy these systems for FedRAMP-authorized continuous compliance documentation.
- Data Mining:Large-scale pattern discovery across unstructured document repositories to identify risk signals or commercial opportunities.
- Data Warehousing:ETL pipeline integration for structured data loading into analytical databases.
- Market Research:Ad-hoc competitive intelligence gathering and sentiment analysis from public sources.
Data warehousing dominates historical infrastructure investment. Automated reporting is gaining share fastest as real-time operational intelligence becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity, absorbing premium SaaS extraction platforms under federal IT modernization mandates, while emerging market procurement remains acutely sensitive to per-page metering costs and open-source alternatives.
United States
HIPAA audit mandates and FedRAMP authorization requirements drive healthcare and federal agency procurement of cloud-native extraction platforms with embedded compliance controls. The Federal Risk and Authorization Management Program constrains vendor eligibility through security certification gates. Enterprise clusters in Northern Virginia and Seattle anchor deployment of hybrid cloud architectures for classified data workloads.
Germany
REACH chemical substance registration and the EU AI Act's risk-based classification system mandate automated data lineage documentation across manufacturing supply chains. The country's national chemical regulator enforces extraction accuracy standards for safety data sheet processing. Industrial concentrations in North Rhine-Westphalia and Bavaria embed extraction APIs directly into supplier onboarding portals for compliance verification.
United Kingdom
Financial services procurement concentrates on natural language processing platforms for real-time regulatory filing automation under Prudential Regulation Authority supervision. GDPR-derived data protection requirements shape platform selection criteria for audit trail granularity. London's fintech cluster drives adoption of transformer-based extraction models for contract parsing and entity recognition.
Japan
METI industrial digitization programs accelerate replacement of legacy template-based systems with machine learning extraction across automotive and electronics supply chains. The country's pharmaceutical regulator mandates complete documentation lineage for clinical trial submissions. Manufacturing hubs in Aichi Prefecture and Osaka deploy extraction pipelines for supplier quality certificate processing at throughput rates exceeding thousands of documents per hour.
India
Bureau of Indian Standards certification requirements and RBI data localization mandates constrain vendor selection for financial services extraction deployments. The country's central bank imposes strict audit trail requirements on automated decision-making systems. IT services clusters in Bengaluru and Hyderabad specialize in custom integration development for legacy mainframe connectors, extending implementation timelines for enterprise deployments.
Data Extraction Market Vendor Landscape
Cloud-native platform specialists and legacy enterprise software incumbents split the market between consumption-based pricing models and perpetual licensing architectures. Market structure exhibits moderate consolidation around vendors with hybrid cloud credentials and federal security authorizations. Three archetypes dominate: automation-centric workflow integrators, hyperscale cloud service providers, and independent data management specialists. Competitive moves concentrate on strategic partnerships with systems integrators and vertical specialization around HIPAA and EU AI Act compliance architectures.
Within the automation-centric tier, UiPath exemplifies robotic process automation pipeline integration where extraction functions as an embedded workflow step. IBM Corporation anchors the hybrid cloud specialist position, leveraging security certifications for regulated industry deployments. Microsoft Corporation occupies the hyperscale integration archetype, sustaining competitive pressure through native connectivity with productivity suites and cloud data services. These three entities represent distinct strategic vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP |
| Informatica |
| UiPath |
| Alteryx |
| Talend |
| Bright Data |
| Others |
Supply Flow & Price Mechanics
Bengaluru's IT services cluster anchors global capacity for custom extraction platform development, with its engineering density translating into pricing leverage for enterprise deployments requiring legacy mainframe integration. Cloud-native vendors headquartered in Northern Virginia and Seattle compress margins through consumption-based metering, while specialized systems integrators in Hyderabad capture aftermarket service premiums.
Pricing Analysis
After-sales service contracts now drive lifetime value as buyers unbundle implementation from platform licensing. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized federal deployments from mid-market SaaS tiers and open-source alternatives. Cost compression in optical character recognition segments stems from commoditized open-source tools. Healthcare providers demonstrate lowest price sensitivity under HIPAA audit mandates, while emerging market procurement remains acutely responsive to per-page metering costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent on-premises deployments. Software development concentrates in India, the United States, and Ireland, with model training infrastructure drawing from NVIDIA GPU supply and cloud compute capacity. Single-source vulnerability in transformer model licensing from hyperscalers threatens vendor roadmap autonomy. Distribution runs through direct enterprise sales teams and certified systems integrators, with channel partners gaining share in federal contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT modernization cycles position this market for cyclical recovery, with federal data governance mandates and healthcare digitization budgets providing sequential demand waves.
For Market Incumbents: Build compliance certification moats through FedRAMP authorization and EU AI Act risk classification tooling. Deepen vertical integration into healthcare-specific NLP training pipelines to offset open-source displacement threats. Anchor capacity in Northern Virginia and Seattle federal contracting corridors. Prioritize R&D investment in transformer-based semantic extraction to strand competitor technical debt in template-based systems. For New Entrants and Emerging Players: Pursue white-space targets in mid-market legal services and regional insurance payers underserved by hyperscale platforms. Chemical supply chain compliance in Germany offers penetrable entry through REACH-mandated safety data sheet automation. Deploy consumption-based pricing with embedded risk classification documentation to reduce upfront procurement friction against perpetual licensing incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with domain-specific model training capabilities over generalist workflow platforms. Five-to-ten year viability hinges on semantic understanding convergence with robotic process automation pipelines. Acquisition targets should demonstrate healthcare or financial services vertical depth with recurring compliance service revenue. Monitor NLP engineer hiring velocity at leading vendors as inflection indicator for product roadmap execution capacity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Service Launch | Captures recurring revenue from European enterprise clients facing automated risk classification mandates. |
| Healthcare NLP Model Training Partnership | Secures clinical coding automation contracts under HIPAA audit requirements through domain specialization. |
| FedRAMP Authorization Investment | Unlocks United States federal agency procurement under IT modernization mandates retiring legacy infrastructure. |
| Consumption-Based Pricing Transition | Aligns vendor revenue with customer utilization patterns while reducing upfront procurement friction. |
| Systems Integrator Certification Program | Captures aftermarket service revenue as buyers unbundle implementation from platform licensing. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with healthcare CIOs, federal IT procurement officers, NLP engineering leads, and systems integrator partners. Secondary validation drew from FedRAMP authorization databases, HIPAA audit documentation, EU AI Act regulatory filings, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated against top-down enterprise IT spending benchmarks.
Calibration anchored historical adoption curves to federal modernization budget cycles and healthcare digitization waves. Segmentation dimensions modeled include deployment architecture, end-user vertical, technology type, and regional regulatory framework. CAGRs were derived from slope analysis of installed base expansion against pricing trajectory. Transformer model capability advancement and compliance mandate implementation timelines served as industry-specific forecast inputs.
Sensitivities concentrate around NLP engineer recruitment constraints and divergent national AI governance frameworks. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Legal Technology Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Online Dating Market