
 Global OLED Market | 2026-2036
Global OLED Market Size, Share, and Industry Trends Forecast 2026-2036
Global OLED Market Outlook
Panel refurbishment and secondary lifetime extension is tilting margin pools away from virgin manufacturing toward service ecosystems. Samsung Display leverages captive material sourcing to sustain wafer-thin margin control across Gen-8.5 lines. LG Display anchors premium television supply through white-OLED deposition mastery. BOE Technology Group competes aggressively on flexible AMOLED price positioning for smartphone brands.
Organic light-emitting diode technology employs electroluminescent organic compounds arranged in emissive layers between conductive electrodes, with active-matrix addressing requiring thin-film transistor backplanes to achieve sub-millisecond response times and true black states through pixel-level deactivation. The primary commercial purpose spans self-illuminated displays eliminating backlight assemblies for thinner form factors and superior contrast ratios. Flexible OLED dominates smartphone attachment as foldable hinge mechanisms mature, while transparent OLED carves nascent architectural and automotive glazing applications with see-through luminance properties. AMOLED commands the value pool across consumer electronics, whereas PMOLED retains niche instrument-cluster utility where resolution demands stay modest.
FDA scrutiny of OLED-based medical imaging interfaces intensifies as diagnostic display calibration standards tighten for radiological applications. EPA hazardous substance rules govern organic emitter compound disposal protocols in US fabrication facilities. REACH and RoHS frameworks in Europe restrict heavy metal content in phosphorescent dopant chemistry, compelling Universal Display Corporation and material suppliers to reformulate iridium complex compositions. Stakeholders must monitor how Korea's national emission trading scheme and China's dual carbon goals reshape energy-intensive vapor deposition economics before committing next-generation fab capacity.
Market Dynamics
Samsung Display and LG Display command over 80 percent of operational Gen-8.5 and Gen-6 vapor deposition capacity, creating a supply oligopoly that dictates pricing power and allocation priority for premium smartphone and television brands.
Growth Catalysts
- EU Green Deal ecodesign mandates:Tightening energy efficiency standards for display technologies accelerate OLED substitution against LCD in premium television and monitor segments.
- Automotive curved dashboard integration:OEMs in Germany, Japan, and the United States are specifying flexible OLED panels for instrument clusters and center-stack displays.
- Foldable hinge mechanism maturation:Mechanical reliability improvements in polymer substrate bending radii below 1.5mm enable clamshell and book-type smartphone form factors.
Market Restraints
- Iridium complex supply concentration:Phosphorescent dopant chemistry relies on rare earth processing concentrated in Chinese refining operations, creating input cost volatility.
- Gen-8.5 vapor deposition capex intensity:Single fabrication line commissioning exceeds two billion dollars, freezing out mid-tier capital pools.
- REACH and RoHS heavy metal restrictions:European chemical frameworks compel material reformulation, extending qualification timelines for new emitter compounds.
Strategic Opportunities
- Transparent OLED architectural glazing:See-through luminance properties open building-integrated display applications in commercial real estate and automotive windshields.
- India smartphone manufacturing incentives:PLI scheme subsidies attract panel module assembly investments to serve domestic brands and export markets.
- FDA diagnostic display calibration standards:Tightening radiological imaging requirements create certified medical-grade OLED monitor demand in hospital networks.
Industry Challenges
- Thin-film transistor backplane engineering talent:Active-matrix addressing expertise for sub-millisecond response times concentrates in South Korean and Taiwanese engineering pools.
- Dual carbon goal compliance:China's national emission trading scheme and Korea's carbon pricing reshape energy-intensive deposition economics, requiring fab location recalculation.
- Universal Display Corporation patent licensing:Phosphorescent OLED IP thickets complicate independent emitter material development for second-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OLED Market |
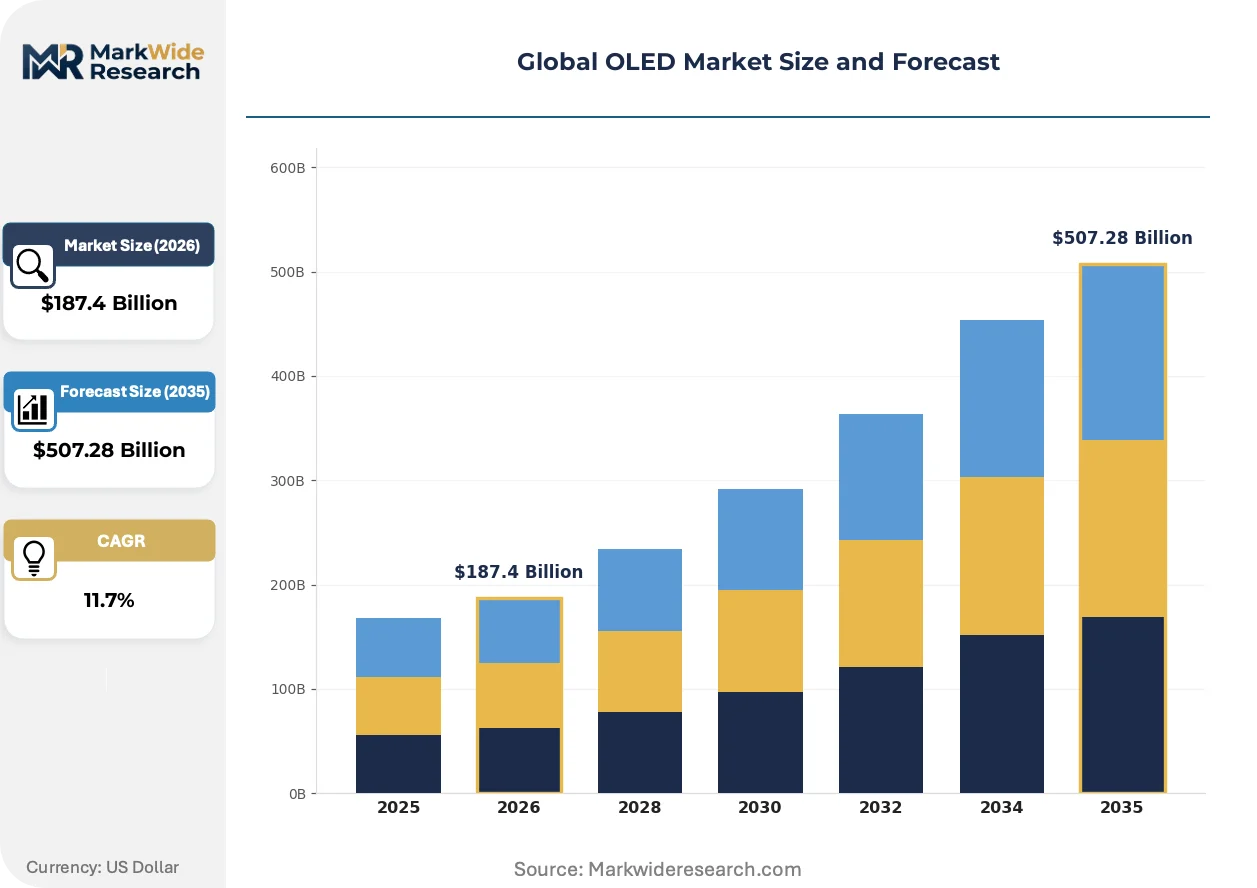
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Smartphones, Tablets, Monitors Technology: AMOLED, PMOLED, Transparent OLED, Flexible OLED End User: Consumer Electronics, Automotive, Healthcare, Advertising Application: Display Panels, Lighting Solutions, Wearable Devices, Signage |
| Companies Covered | Samsung Display, LG Display, BOE Technology Group, AU Optronics, Universal Display Corporation, Tianma Microelectronics, Japan Display Inc., Visionox Technology, CSOT (China Star Optoelectronics Technology), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OLED Market Strategic Shifts
Display technology architecture is bifurcating between premium flexible formats commanding design differentiation and rigid formats competing on cost efficiency in commoditized segments.
Tandem OLED stack architecture is migrating from experimental television prototypes to mass-production smartphone panels. Samsung Display deploys two-series-connected organic light-emitting layers in flagship handsets to double luminance efficiency and extend operational lifetime. This structural shift compresses power consumption benchmarks against conventional single-stack deposition while enabling brighter outdoor visibility without thermal degradation.
REACH authorization procedures for iridium-based phosphorescent dopants are tightening material disclosure requirements across European supply chains. ECHA scrutiny forces Universal Display Corporation and Asian material suppliers to document full substance toxicity profiles before market placement. Television manufacturers sourcing panels for EU distribution now demand pre-certified emitter compound documentation from Korean and Chinese fabrication partners.
Automotive procurement departments are consolidating display supplier rosters from fragmented multisource arrangements toward single-source strategic partnerships with tier-one panel makers. German OEMs including BMW and Mercedes-Benz now specify direct contractual relationships with Samsung Display and LG Display for curved instrument cluster panels, bypassing traditional tier-two module integrators. This channel compression concentrates volume commitment risk with fabrication leaders while squeezing margin capture for intermediate assembly operations.
Global OLED Market Segmentation
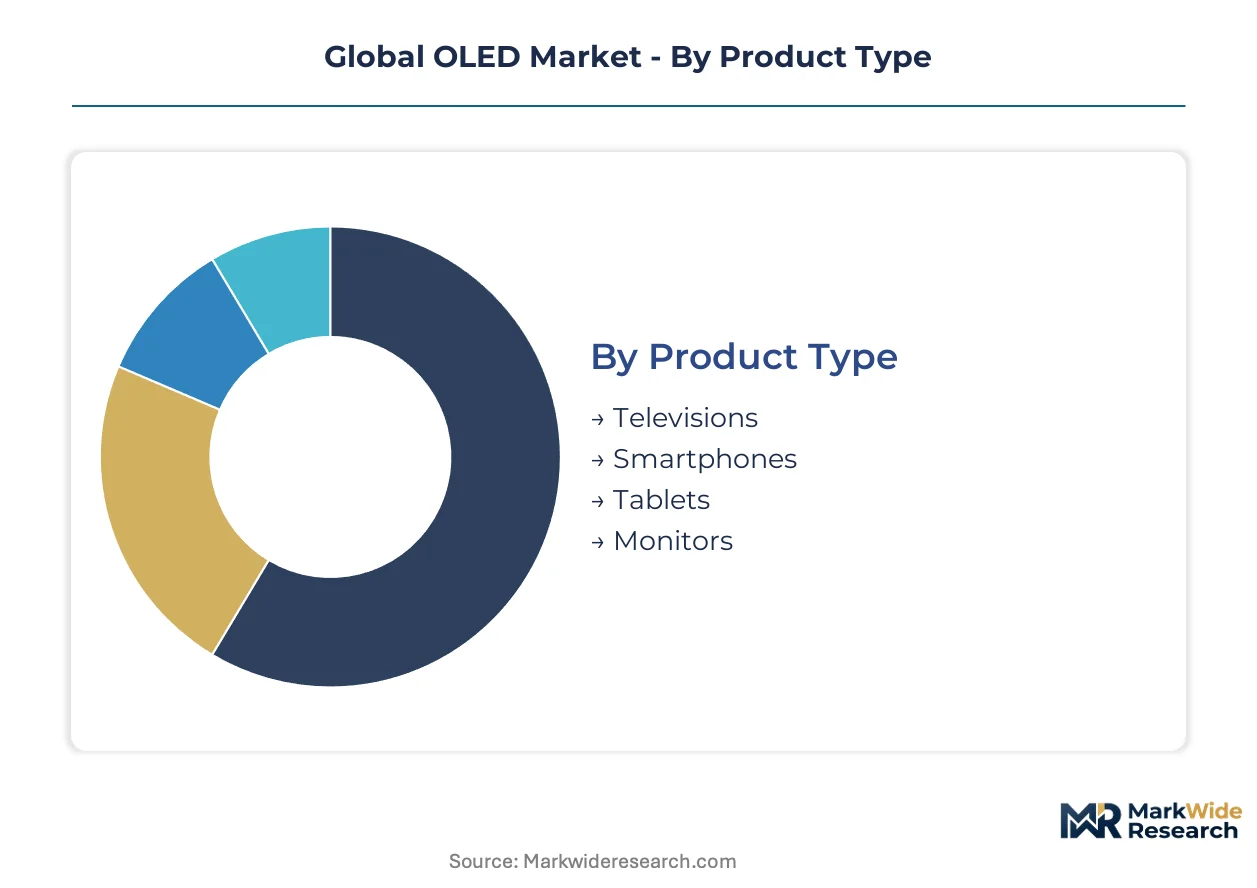
Segmentation in the OLED market reveals how fabrication capacity allocation and end-use specification requirements diverge across device categories. Understanding these partitions illuminates where vapor deposition investments concentrate and where material chemistry roadmaps must adapt.
Product Type:
Mature television applications anchor capital-heavy Gen-8.5 lines, while emerging form factors in foldable smartphones reshape substrate handling requirements.
- Televisions:White-OLED deposition architectures dominate screen sizes above 55 inches, with LG Display's tandem stack configurations addressing luminance decay in living-room ambient conditions. South Korean fabs dedicate dedicated vapor deposition chambers to television-grade mother glass throughput.
- Smartphones:Flexible AMOLED commands premium handset attachment as Samsung Display and BOE Technology Group compete on polymer substrate bending radii below 1.5mm for clamshell mechanisms.
- Tablets:Mid-size rigid OLED panels serve professional creative workflows where color gamut accuracy outweighs flexibility requirements.
- Monitors:Gaming-oriented specifications prioritize sub-millisecond response times through active-matrix addressing, with Samsung Display targeting high-refresh-rate desktop segments.
Televisions retain volume leadership; smartphones hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium deposition architectures from commodity configurations, with material chemistry costs driving the wedge.
- AMOLED:Thin-film transistor backplanes enable individual pixel addressing for true black states and sub-millisecond response, commanding consumer electronics value pools where power efficiency justifies higher panel costs.
- PMOLED:Passive-matrix addressing suits low-resolution instrument clusters in automotive applications where simple segment displays suffice and cost minimization dominates procurement criteria.
- Transparent OLED:See-through luminance properties open architectural glazing and automotive windshield applications, with LG Display piloting commercial installations in Korean retail environments.
- Flexible OLED:Polyimide substrate handling enables foldable and rollable form factors, with mechanical reliability testing concentrated in Samsung Display's Suwon engineering facilities.
AMOLED captures margin concentration; transparent OLED traces the most aggressive technology roadmap.
End User:
Customer type diversification stretches from mass-market consumer volumes to specialized certification requirements in regulated sectors.
- Consumer Electronics:Smartphone and television brands in South Korea, China, and the United States drive panel procurement volumes, with seasonal launch cycles dictating fab allocation priority.
- Automotive:BMW and Mercedes-Benz specify curved instrument cluster panels directly with Samsung Display and LG Display, bypassing traditional tier-two module integrators for dashboard integration.
- Healthcare:FDA diagnostic display calibration standards tighten for radiological imaging interfaces, creating certified medical-grade monitor demand in hospital networks.
- Advertising:Digital signage applications prioritize luminance uniformity for outdoor visibility, with commercial real estate developers specifying transparent OLED for building-integrated displays.
Consumer electronics sustains volume dominance; automotive climbs the fastest on curved dashboard penetration.
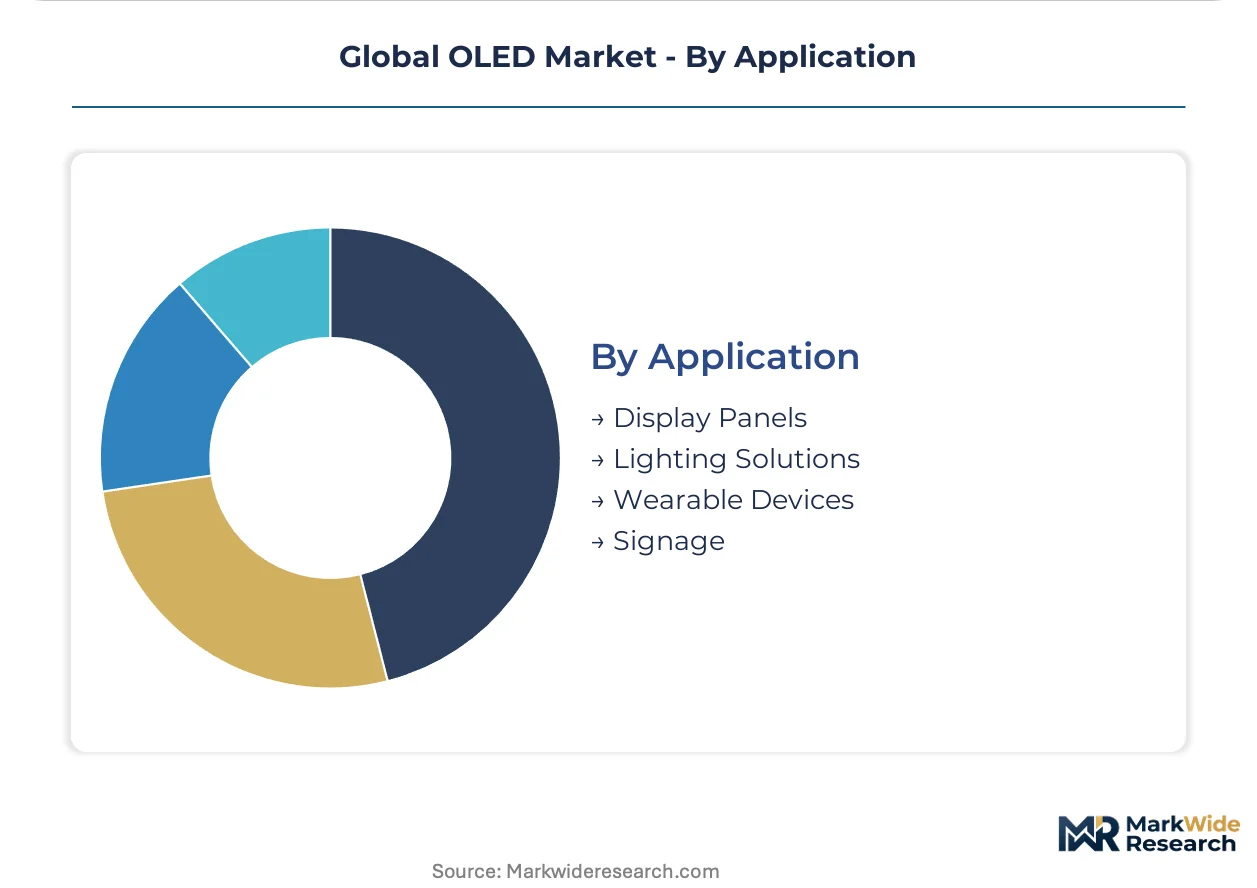
Application:
Application focus determines whether emissive layer engineering targets display performance or illumination function, diverging material roadmaps.
- Display Panels:Active-matrix addressing for sub-millisecond response concentrates TFT backplane expertise in South Korean and Taiwanese engineering pools, with Samsung Display and LG Display controlling premium supply.
- Lighting Solutions:Panel-level OLED illumination competes with LED in architectural applications where diffuse light quality outweighs cost efficiency.
- Wearable Devices:Small-form-factor flexible panels serve smartwatch and fitness tracker segments where power consumption constraints favor OLED's self-illuminating architecture over backlight assemblies.
- Signage:Commercial display installations prioritize operational lifetime in continuous-duty environments, with material suppliers reformulating emitter compounds for slower degradation curves.
Display panels command revenue concentration; wearable devices gain share fastest on health-monitoring device proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes OLED panels primarily for premium smartphone and television manufacturing, while China deploys the technology across mass-market handset production and emerging automotive applications. Germany and the United States focus on specialized automotive dashboard and medical imaging deployments. Japan maintains concentrated materials and equipment supply positions.
South Korea
Samsung Display and LG Display operate dominant Gen-8.5 and Gen-6 vapor deposition lines serving global smartphone and television brands. Korea's national emission trading scheme imposes carbon pricing on energy-intensive fabrication operations. The Suwon engineering cluster concentrates mechanical reliability testing for foldable polymer substrate development.
China
BOE Technology Group and CSOT expand flexible AMOLED capacity for domestic smartphone brands and export markets. MIIT industrial policy directs subsidies toward display panel localization under the dual carbon goals framework. The Yangtze River Delta fabrication corridor anchors government-backed Gen-6 line investments in Hefei and Wuhan.
Germany
BMW and Mercedes-Benz specify curved OLED instrument clusters directly with Korean panel makers for premium vehicle segments. REACH authorization procedures enforce heavy metal disclosure requirements on phosphorescent dopant imports. The Stuttgart automotive engineering cluster coordinates display integration specifications with tier-one module suppliers.
United States
Apple and other consumer electronics brands source premium flexible panels for flagship smartphone launches. FDA diagnostic display calibration standards tighten for radiological imaging interfaces in hospital networks. The Austin technology corridor hosts module assembly investments targeting North American consumer electronics supply chains.
Japan
Japan Display Inc. and materials suppliers concentrate on specialized small-form-factor panels and emitter compound development. METI industrial standards govern display energy efficiency benchmarking for domestic electronics manufacturers. The Nagoya precision equipment cluster supplies vapor deposition machinery to Korean and Chinese fabrication facilities.
Global OLED Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Korean fabricators command premium deposition expertise and captive material sourcing, while Chinese competitors compete on flexible AMOLED price positioning and capacity expansion velocity. Three archetypes define the field: integrated fabrication leaders with in-house emitter material development, mid-tier panel assemblers dependent on external chemistry supply, and specialized equipment and materials providers licensing intellectual property. Dominant competitive moves include strategic partnerships with automotive OEMs for curved dashboard supply and backward integration into phosphorescent dopant chemistry to secure input cost control.
Within the integrated fabrication tier, Samsung Display and LG Display exemplify capability concentration through captive Gen-8.5 line operation and white-OLED deposition mastery. BOE Technology Group occupies a position representing scale-driven competitive pressure through aggressive flexible AMOLED price positioning for smartphone brands. These three anchors illustrate how Korean expertise concentration confronts Chinese manufacturing scale across the consumer electronics value chain.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology Group |
| AU Optronics |
| Universal Display Corporation |
| Tianma Microelectronics |
| Japan Display Inc. |
| Visionox Technology |
| CSOT (China Star Optoelectronics Technology) |
| Others |
Value Chain & Pricing Dynamics
Iridium complex refining concentration in Chinese processing operations anchors input cost volatility that cascades through phosphorescent dopant chemistry pricing, compressing margin pools for mid-tier panel assemblers while Korean integrated fabricators capture value through captive material sourcing.
Pricing Analysis
Long-term offtake contracts dominate premium flexible AMOLED procurement between Samsung Display and flagship smartphone brands, while spot-market transactions govern commodity rigid panel segments. Price differentiation rests on deposition architecture complexity and FDA diagnostic calibration certification for medical-grade monitors. Cost compression in rigid OLED tiers is intensifying because BOE Technology Group and CSOT expand Gen-6 capacity. Automotive OEMs exhibit lowest price sensitivity due to curved dashboard integration specifications, whereas digital signage operators face acute margin pressure.
Supply Chain Analysis
Export-control restrictions on vapor deposition equipment and thin-film transistor backplane technology limit fabrication machinery flows from Japanese precision equipment clusters to emerging Chinese facilities. Manufacturing gravity centers on South Korea, China, and Japan for mother glass throughput and emitter compound formulation. Raw material dependencies span iridium complexes from Chinese refiners, polyimide substrates from Japanese chemical suppliers, and precision deposition chambers from Nagoya equipment makers. Single-source vulnerability concentrates in Universal Display Corporation phosphorescent OLED patent licensing. Distribution feeds from Korean and Chinese fabs through module assembly operations in India PLI-subsidized facilities to North American and European end-use markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where Universal Display Corporation patent thickets and Korean engineering talent concentration create switching costs that entrench incumbent positions against challenger entry.
For Market Incumbents: Entrench through backward integration into phosphorescent dopant chemistry to neutralize iridium supply volatility, and anchor capacity expansion in India PLI corridors to capture smartphone module assembly subsidies. Emerging Chinese flexible AMOLED price positioning threatens margin structures in commoditized smartphone tiers. Certification investment in FDA diagnostic display calibration standards secures medical-grade premium positioning.
For New Entrants and Emerging Players: Build out transparent OLED architectural glazing capabilities for commercial real estate and automotive windshield applications where Korean incumbents maintain limited deployment focus. The most penetrable segment sits in building-integrated display installations requiring see-through luminance properties absent from incumbent roadmaps. A go-to-market angle targeting European commercial developers with REACH pre-certified emitter documentation accelerates qualification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across tandem OLED stack architecture commercialization, favoring scaled fabricators with existing Gen-8.5 depreciation bases over greenfield entrants. Long-term viability across the analysis window favors acquisition targets with captive emitter material development and automotive OEM direct contractual relationships. The signal to watch is automotive procurement consolidation from multisource arrangements toward single-source strategic partnerships with tier-one panel makers.
| Strategic Initiative | Industry Significance |
|---|---|
| Tandem OLED Stack Commercialization | Samsung Display deploys dual-layer deposition to double luminance efficiency in flagship handsets. |
| Automotive Direct Partnership | BMW and Mercedes-Benz bypass tier-two integrators for curved instrument cluster supply contracts. |
| India Module Assembly Investment | PLI scheme subsidies attract panel finishing operations to serve domestic brands and export markets. |
| Phosphorescent Dopant Backward Integration | Captive iridium complex sourcing neutralizes Chinese refining concentration and input cost volatility. |
| Medical-Grade Certification Pathway | FDA diagnostic display calibration standards tighten for radiological imaging interface procurement. |
Study Parameters
Operator-level perspectives from display fabrication executives, automotive OEM procurement directors, phosphorescent material R&D leads, and hospital biomedical engineering managers anchored the qualitative base. Primary interview intelligence combined with secondary validation from SEC filings of publicly traded panel makers, MIIT industrial policy disclosures, FDA diagnostic device databases, and ECHA REACH authorization records. Bottom-up capacity modeling and top-down end-use demand triangulation cross-checked volume assumptions.
Scenario-bracketing around EU Green Deal ecodesign mandate implementation timelines and China dual carbon goal compliance costs framed the analytical envelope. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and application focus across the projection horizon. CAGRs derived from vapor deposition capacity commissioning schedules, seasonal smartphone launch cycles, and automotive platform design-in timelines. Industry-specific inputs incorporated foldable hinge mechanism reliability testing data and tandem OLED stack degradation curves.
Stress conditions across iridium complex supply disruption, REACH heavy metal restriction tightening, and Korean emission trading scheme carbon price escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Gen-8.5 line yield rates and automotive curved panel adoption velocity. Material shifts in phosphorescent emitter compound regulatory classification or vapor deposition equipment export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Tablets and Notebook Display Market
Display Technologies
LCD Panel Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
4K VR Displays Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Multi-Function Display Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Global Transparent Display Market
Display Technologies
Interactive Display Market
Display Technologies
3D Display Module Market
Display Technologies
4K Technology Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Quantum Dot Display Market