
 Electronic Board Level Underfill and Encapsulation Material Market | 2026-2036
Electronic Board Level Underfill and Encapsulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Board Level Underfill and Encapsulation Material Market Foresight
Automotive-grade reliability specifications is bifurcating the competitive landscape into suppliers capable of AEC-Q100 thermal cycling performance versus general electronics providers. Henkel leverages its adhesives portfolio to sustain automotive certification breadth across European OEM programs. Namics anchors high-purity epoxy underfill supply to Japanese semiconductor packaging houses. Showa Denko Materials Co., Ltd. competes through captive resin synthesis and flip-chip process integration.
Electronic board level underfill and encapsulation materials comprise thermosetting polymers—typically silica-filled epoxies, silicones, or polyurethanes with glass transition temperatures above 125°C—applied between die and substrate or over assembled components to mitigate thermomechanical stress, moisture ingress, and ionic contamination in high-density electronics. Epoxy underfill dominates current volume owing to its established use in flip-chip and ball-grid-array packages, while silicone encapsulation captures expanding share in LED assemblies and power electronics where thermal stability exceeds 150°C. Thermal conduction adhesive represents the fastest-growing product category as gallium-nitride and silicon-carbide device deployment accelerates heat dissipation requirements.
EPA regulations on volatile organic compound emissions constrain solvent-based formulation practices in US manufacturing facilities. REACH registration requirements and RoHS substance restrictions in Europe mandate comprehensive material disclosure and restricted substance screening across supply chains. China's GB standards and MIIT directives on electronic product environmental protection impose parallel compliance obligations for materials sold into domestic assembly operations. Stakeholders must monitor regulatory convergence on per- and polyfluoroalkyl substance restrictions, as these chemistries appear in surfactant packages used during underfill dispensing and flow control.
Market Dynamics
Automotive electrification is compressing qualification timelines for thermal-conduction-grade underfills as OEMs demand AEC-Q100 certification cycles under 18 months, forcing material suppliers to parallel-track formulation and validation rather than sequence them.
Growth Catalysts
- Silicon-carbide power module deployment:EV traction inverters and onboard chargers require thermal interface materials with thermal conductivity above 3 W/mK, pulling high-fill-factor epoxy formulations into automotive qualification pipelines.
- REACH Article 33 disclosure mandates:European electronics assemblers now screen underfill chemistries for SVHC content above 0.1% w/w, creating pull for pre-certified halogen-free formulations from compliant suppliers.
- Taiwan semiconductor packaging cluster concentration:Advanced packaging foundries in Hsinchu and Tainan consume over half of global flip-chip underfill volume, anchoring regional formulation R&D and captive resin synthesis investments.
Market Restraints
- Silica filler supply concentration:High-purity fused silica for thermal-conduction grades sources primarily from Chinese state-owned mining operations, exposing formulators to export quota volatility and forced localization requirements.
- Epoxy resin price volatility:Bisphenol-A and epichlorohydrin feedstock costs swing with crude oil derivatives and Chinese environmental inspection cycles, compressing gross margins on standard-grade underfills by 300-500 basis points during spike periods.
- Ceramic substrate substitution in power electronics:Direct-bond-copper and active-metal-brazed substrates with built-in thermal management reduce dependency on polymeric underfill in some high-voltage applications.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme disbursements for semiconductor assembly and mobile device production create first-mover advantage for underfill suppliers establishing local blending operations before 2026 subsidy cliffs.
- Photonic integrated circuit packaging:Co-packaged optics for AI datacenter switches require low-stress encapsulants with optical transparency above 90% at 1310nm, opening premium pricing tiers absent from legacy digital packaging.
- EU Green Deal sustainable chemistry mandates:Biobased epoxy feedstocks from lignin or epoxidized vegetable oils qualify for green public procurement preferences, enabling differentiation in European automotive and industrial electronics verticals.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in rheology control for high-fill-factor thermal pastes and capillary flow modeling for fine-pitch flip-chip applications concentrates among retiring Japanese and Korean specialists, constraining new product cycle acceleration.
- AEC-Q100 Grade 0 qualification timelines:Thermal cycling from -40°C to 150°C for 1000 cycles requires 12-18 months of reliability testing, locking working capital in inventory before revenue recognition and delaying customer switching decisions.
- Legacy dispensing equipment incompatibility:High-viscosity thermal-conduction underfills demand heated dispense heads and precision needle designs that retrofit poorly onto standard capillary underfill lines, forcing capital reinvestment or subcontracting arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Board Level Underfill and Encapsulation Material Market |
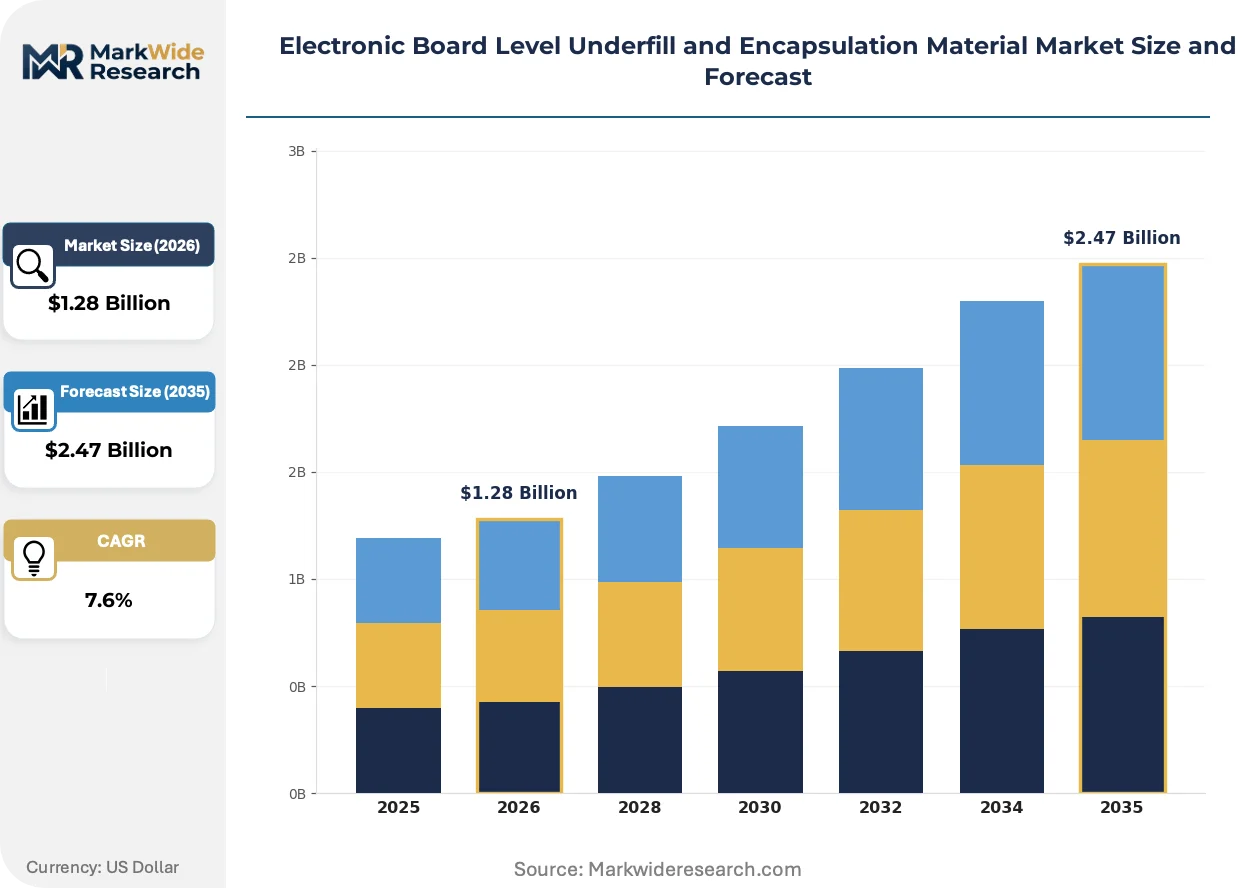
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.47 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Underfill, Silicone Encapsulation, Polyurethane Encapsulation, Thermal Conduction Adhesive End User: Telecommunications, Consumer Electronics, Automotive Electronics, Medical Devices Technology: Wave Soldering, Surface Mount Technology, Flip Chip Technology, Chip-on-Board Application: Core Electronics, High-Density Interconnects, LED Assemblies, Automotive Assemblies |
| Companies Covered | Namics, Zymet, Henkel, Showa Denko Materials Co., Ltd., Lord Corporation, H.B. Fuller, AI Technology, Epoxy Technology Inc, Protavic America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Board Level Underfill and Encapsulation Material Market Shifts & Advancements
Material-performance boundaries are dissolving as thermal, mechanical, and electrical requirements converge in advanced packaging architectures, forcing suppliers to engineer multi-property optimization rather than single-attribute leadership.
High thermal conductivity epoxy formulations incorporating boron nitride or aluminum nitride fillers alongside conventional fused silica are bifurcating the product roadmap between automotive power electronics requiring >150°C continuous operation and consumer mobile devices prioritizing low stress and fast flow. Tier-1 automotive suppliers are locking in dual-source agreements for these grades three years ahead of platform launches. The technology is compressing the addressable market for legacy silica-only thermal pastes into cost-sensitive industrial and white-goods segments.
ECHA's 2023 restriction proposal on per- and polyfluoroalkyl substances in industrial applications targets fluorosurfactants used for substrate wetting and void elimination during underfill dispense, forcing reformulation toward silicone-polyether hybrid surfactants with inferior flow characteristics. European automotive electronics assemblers are front-loading inventory of PFAS-containing materials ahead of anticipated 2026-2027 enforcement windows. The policy friction is accelerating migration of European packaging demand toward Asian facilities with less immediate regulatory exposure.
Consolidated procurement of underfill, die-attach adhesive, and thermal interface materials by OSATs and IDMs is displacing discrete supplier relationships, with packaging houses demanding single-source accountability for interfacial compatibility and reliability failure analysis. Tier-2 material specialists without full-stack portfolios are retreating to niche applications or accepting subcontractor status behind integrated adhesive suppliers. The pattern is most pronounced in Taiwan and South Korea, where packaging foundries have consolidated to three dominant players controlling over 70% of regional advanced packaging capacity.
Electronic Board Level Underfill and Encapsulation Material Market Segmentation
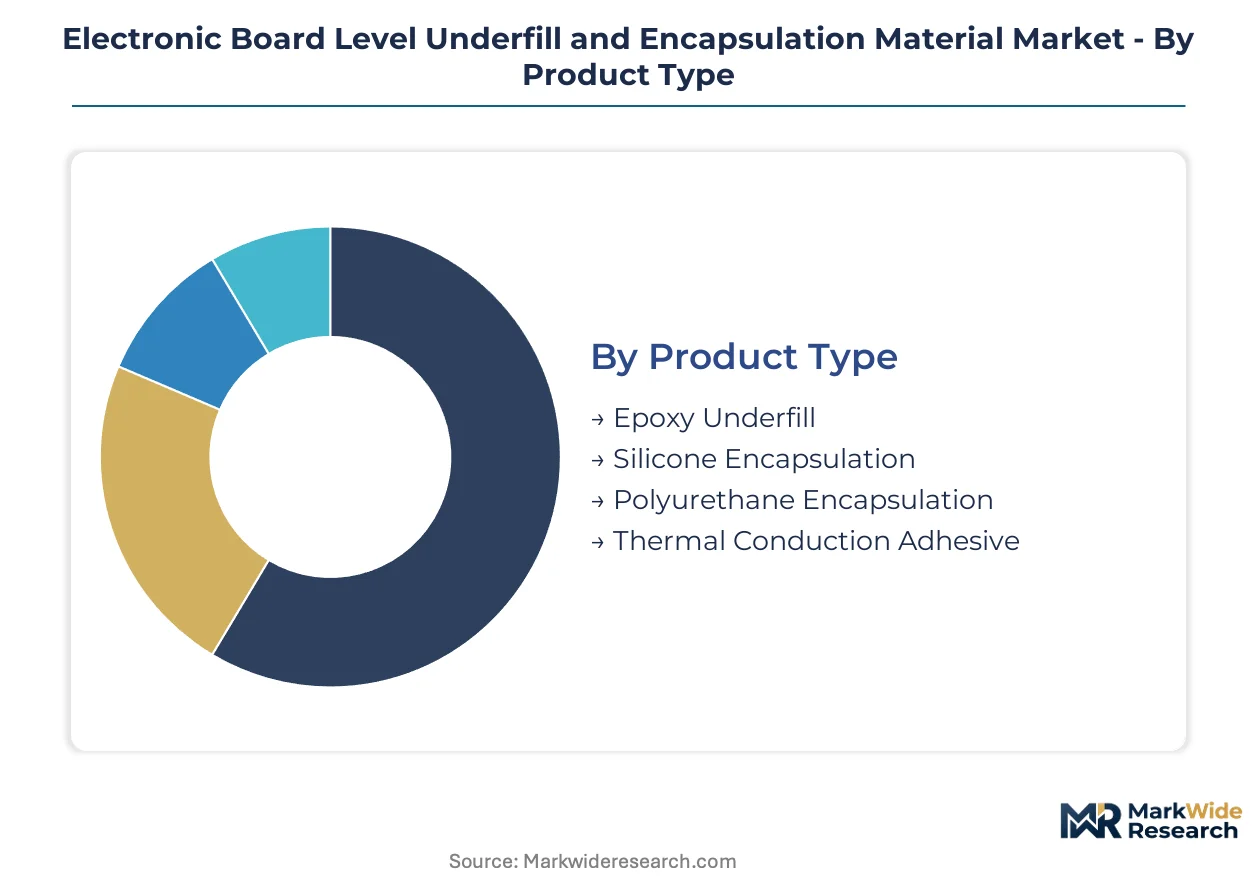
Segmentation in this market tracks how material specifications diverge across thermal, mechanical, and electrical requirements. Each dimension reveals distinct substitution pressures and margin structures that suppliers must navigate.
Product Type:
Silicone encapsulation faces the most acute substitution threat from advanced epoxy formulations that now match its thermal stability at lower cost.
- Epoxy Underfill:Silica-filled thermosetting polymers with glass transition temperatures above 125°C dominate flip-chip and ball-grid-array packaging. Demand concentrates in Taiwan's Hsinchu packaging cluster, where advanced foundries consume the majority of global volume for smartphone and AI accelerator chips.
- Thermal Conduction Adhesive:Boron nitride or aluminum nitride-filled formulations achieve thermal conductivity above 3 W/mK for silicon-carbide power modules. Automotive electrification in Germany and South Korea is pulling these grades through AEC-Q100 qualification pipelines faster than standard thermal pastes.
- Silicone Encapsulation:Maintains thermal stability beyond 150°C for LED assemblies and power electronics, though epoxy alternatives are eroding share in cost-sensitive applications.
- Polyurethane Encapsulation:Flexible, moisture-resistant formulations serve industrial electronics and white-goods control boards where thermal cycling demands remain moderate.
Epoxy underfill retains volume leadership; thermal conduction adhesive holds the steepest expansion curve.
End User:
Margin structures vary sharply across end users, with automotive electronics commanding certification premiums that consumer segments cannot support.
- Automotive Electronics:AEC-Q100 Grade 0 specifications demand thermal cycling performance from -40°C to 150°C, locking suppliers into 12-18 month qualification timelines. European OEM programs in Germany and France drive reformulation toward halogen-free, PFAS-free chemistries ahead of ECHA restriction windows.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize fast-flow, low-stress underfills for fine-pitch flip-chip packages. Assembly concentration in Vietnam and India is shifting procurement toward regional blending operations.
- Telecommunications:Base station and router manufacturers require underfills with low dielectric loss for high-frequency signal integrity.
- Medical Devices:Biocompatibility and sterilization resistance specifications limit qualified suppliers to specialty epoxy formulators with ISO 13485 certification.
Automotive electronics commands the highest price tiers; consumer electronics generates the largest absolute volume.
Technology:
Process equipment lock-in creates divergent paths for material formulation, with flip-chip technology demanding the most specialized rheology control.
- Flip Chip Technology:Capillary underfill dispensing requires precise control of filler sedimentation and flow front dynamics for die-to-substrate gaps below 50 microns. Taiwan and South Korea packaging foundries have consolidated procurement of these grades among three dominant suppliers.
- Surface Mount Technology:No-flow and wafer-level underfills serve ball-grid-array and chip-scale packages where board-level reliability requirements are less severe. Chinese contract manufacturers drive cost compression in this segment.
- Wave Soldering:Legacy through-hole assemblies still consume conformal coatings and potting compounds in industrial electronics.
- Chip-on-Board:Direct die attach to substrates without intermediate packages requires encapsulants with matched coefficients of thermal expansion for LED and power applications.
Flip chip technology anchors premium pricing; surface mount technology captures the broadest application base.
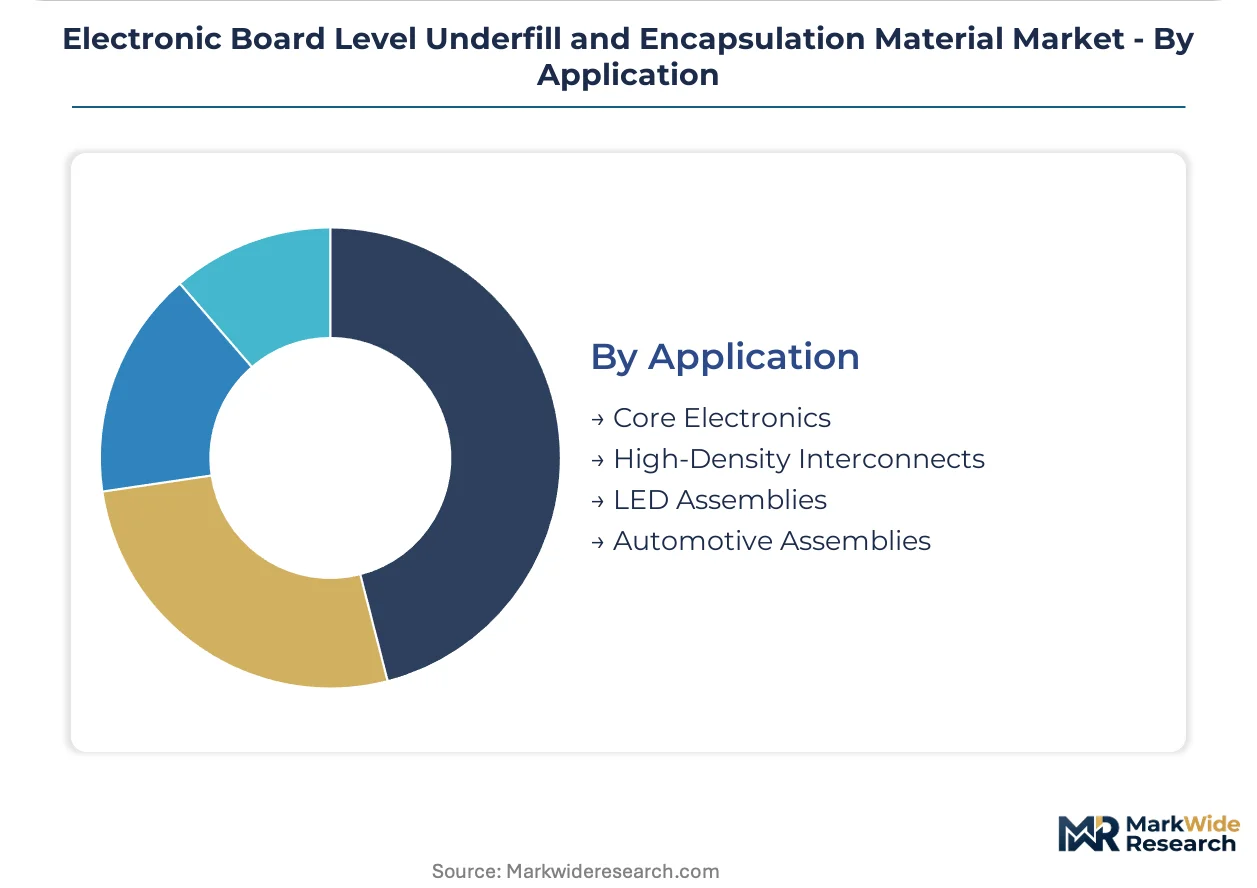
Application:
Performance requirements stratify sharply between core electronics and emerging high-density architectures.
- High-Density Interconnects:Fine-pitch substrates and multi-chip modules demand low-stress underfills with filler particle sizes below 5 microns to prevent voiding in narrow gaps. AI datacenter switch packaging for co-packaged optics in the United States and Japan is pulling optical-grade encapsulants with transparency above 90% at 1310nm.
- Automotive Assemblies:Onboard chargers, traction inverters, and battery management systems require thermal-conduction grades with continuous operation above 150°C.
- Core Electronics:Standard motherboards and peripheral cards consume commodity-grade capillary underfills with established reliability records.
- LED Assemblies:Silicone encapsulation retains dominance for high-brightness applications where phosphor conversion efficiency depends on optical clarity and thermal stability.
High-density interconnects command the steepest technology premiums; core electronics maintains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese specialty chemical producers export high-purity epoxy formulations to Taiwan's semiconductor packaging foundries, sustaining a trade corridor that handles the majority of global flip-chip underfill volume.
Taiwan
Advanced packaging foundries in Hsinchu and Tainan consume over half of global flip-chip underfill supply for smartphone and AI accelerator chip production. Taiwan's Ministry of Economic Affairs enforces environmental compliance through waste reduction mandates on chemical formulators. The Hsinchu Science Park anchors captive resin synthesis investments by Japanese and Korean material suppliers seeking proximity to TSMC and ASE Group operations.
South Korea
Samsung Electronics and SK Hynix drive demand for AEC-Q100 qualified thermal-conduction underfills in automotive memory modules and EV power electronics. South Korea's Ministry of Environment administers K-REACH registration requirements parallel to European SVHC disclosure standards. The Yongin-Giheung corridor hosts concentrated formulation R&D facilities serving both captive semiconductor fabrication and third-party OSAT customers.
China
Domestic assembly of silicon-carbide power modules for NEV traction inverters pulls high-fill-factor epoxy formulations through local qualification pipelines. China's MIIT implements GB standards on electronic product environmental protection that restrict halogenated flame retardants in underfill chemistries. The Yangtze River Delta packaging cluster around Suzhou and Wuxi is absorbing forced localization requirements for silica filler supply as export quotas tighten.
Germany
Bosch, Infineon, and Continental anchor European demand for thermal-conduction grades exceeding 150°C continuous operation in onboard chargers and battery management systems. ECHA's 2023 PFAS restriction proposal is accelerating reformulation timelines ahead of anticipated 2026-2027 enforcement windows. Bavaria's automotive electronics supply corridor is front-loading inventory of legacy formulations while qualifying halogen-free, PFAS-free alternatives.
United States
Co-packaged optics packaging for AI datacenter switches is pulling optical-grade encapsulants with transparency above 90% at 1310nm through specialized qualification channels. EPA regulations on volatile organic compound emissions constrain solvent-based formulation practices in domestic manufacturing facilities. Arizona's emerging semiconductor packaging hub around TSMC's Fab 21 is attracting regional blending operations from multinational adhesive suppliers.
Electronic Board Level Underfill and Encapsulation Material Market Competitive Landscape
Listed leaders compete with private specialists across certification breadth and captive resin synthesis capabilities. The supplier base stratifies into three tiers: multinational diversified adhesive producers with automotive OEM program breadth, Japanese and Korean specialists with high-purity epoxy expertise, and regional formulators serving cost-sensitive industrial segments. Competitive moves center on dual-source agreement capture three years ahead of automotive platform launches and backward integration into silica filler supply to mitigate Chinese export quota exposure.
Among diversified multinational suppliers, Henkel and H.B. Fuller occupy positions anchored by automotive certification breadth across European and North American OEM programs. Japanese specialists Namics and Showa Denko Materials Co., Ltd. exemplify the high-purity formulation archetype, serving semiconductor packaging houses with captive resin synthesis capabilities. These named companies represent the competitive tension between scale-driven portfolio diversification and specialist purity-grade leadership.
| Leading Market Players |
|---|
| Namics |
| Zymet |
| Henkel |
| Showa Denko Materials Co., Ltd. |
| Lord Corporation |
| H.B. Fuller |
| AI Technology |
| Epoxy Technology Inc |
| Protavic America |
| Others |
Supply & Pricing Matrix
Silicone encapsulation displacement by advanced epoxy formulations simultaneously shifts supply geography toward Japanese resin synthesis clusters and compresses pricing premiums previously commanded by thermal stability above 150°C. This substitution dynamic redirects procurement leverage from specialty silicone suppliers to diversified epoxy formulators with captive boron nitride filler compounding capabilities.
Pricing Analysis
Next-generation thermal-conduction adhesives command substantial premiums over legacy silica-only formulations and prior-generation thermal pastes. Three-tier pricing structure across AEC-Q100 certified, industrial-grade, and cost-optimized tiers reflects qualification investment recovery and raw material purity differentials. Pricing pressure stems from Chinese contract manufacturers driving standard-grade underfill commoditization through high-volume tenders. Automotive OEMs exhibit lowest price sensitivity due to 18-month qualification lock-ins, while consumer electronics assemblers in Vietnam and India prioritize unit cost minimization above performance headroom.
Supply Chain Analysis
China and Japan anchor high-purity fused silica production for thermal-conduction grades, with South Korea hosting concentrated formulation R&D for AEC-Q100 qualified materials. Epoxy resin feedstocks draw from bisphenol-A and epichlorohydrin supply chains tethered to crude oil derivatives and Chinese environmental inspection cycles. Single-source vulnerability concentrates in Chinese state-owned mining operations controlling high-purity silica export quotas. Distribution runs through Japanese and Korean material suppliers maintaining direct technical service relationships with Taiwan and South Korea packaging foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where AEC-Q100 certification timelines and REACH Article 33 disclosure mandates create structural barriers that favor incumbents with established compliance infrastructure and captive testing relationships.
For Market Incumbents: Consolidate formulation R&D capabilities in Taiwan and South Korea packaging corridors to secure dual-source agreements three years ahead of automotive platform launches. Deepen backward integration into boron nitride and aluminum nitride filler supply to mitigate Chinese silica export quota volatility. Lock in AEC-Q100 Grade 0 qualification breadth across European OEM programs before ECHA PFAS enforcement windows accelerate competitive displacement. For New Entrants and Emerging Players: Differentiate on optical-grade encapsulant transparency for co-packaged optics in AI datacenter switches, where legacy digital packaging suppliers lack refractive index optimization expertise. Target India's PLI scheme subsidy window for semiconductor assembly before local blending operations achieve scale. Pursue biobased epoxy feedstock qualification under EU Green Deal sustainable chemistry mandates to capture green public procurement preferences in German and French automotive electronics verticals. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Japanese specialty chemical formulators possessing high-purity epoxy expertise but lacking automotive OEM program breadth. Five-to-ten year viability hinges on successful migration from consumer electronics volume to automotive certification premiums. Monitor ECHA PFAS restriction enforcement timelines as inflection indicator for European packaging demand migration toward Asian regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Supply | Captive boron nitride sourcing insulates Henkel and Namics from Chinese silica quota volatility. |
| AEC-Q100 Grade 0 Qualification Acceleration | Parallel-tracked formulation and validation compresses 18-month timelines for Bosch and Continental programs. |
| Optical-Grade Encapsulant Development | Transparency above 90% at 1310nm opens premium tiers for AI datacenter switch packaging in Arizona. |
| Biobased Epoxy Feedstock Transition | Lignin-derived formulations qualify for EU Green Deal preferences in Bavaria's automotive corridor. |
| Regional Blending Operations in India | Local compounding captures PLI scheme disbursements before 2026 subsidy cliffs. |
Research Methodology
Desk research of customs trade databases, SEC chemical company filings, and ECHA substance restriction proposals preceded structured interviews with epoxy formulation chemists, automotive electronics procurement managers at Tier 1 suppliers, semiconductor packaging foundry process engineers, and thermal materials distribution channel partners. Primary fieldwork across Taiwan's Hsinchu Science Park and South Korea's Yongin-Giheung corridor validated secondary estimates through bottom-up consumption modeling and top-down market sizing triangulation.
Variance decomposition across product type, end user certification tier, technology node, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier mix and cross-referenced against foundry capacity expansion announcements. Industry-specific forecast inputs incorporated silicon-carbide power module deployment curves and co-packaged optics packaging adoption in AI infrastructure.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital expenditure or accelerated ECHA PFAS enforcement would require recalibration. Forecasts reflect assumptions regarding AEC-Q100 qualification timeline stability and Chinese environmental inspection cycle continuity. Recalibration cycles align with material shifts in semiconductor packaging technology roadmaps and European chemical restriction implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market